
 Asia Pacific Smart Water Metering Market | 2026-2036
Asia Pacific Smart Water Metering Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Smart Water Metering Market Analysis
Modular smart meter bundling with communications modules and cloud software is broadening procurement options for Asian utilities. Kamstrup A/S leverages its ultrasonic meter specialization to anchor premium utility contracts across East Asia. Itron Inc. competes through integrated IoT platform offerings that extend beyond hardware into data analytics services. Badger Meter Inc. differentiates via manufacturing scale that controls per-unit costs for large municipal rollouts.
Asia Pacific smart water metering encompasses automated systems that measure consumption, detect leaks, and transmit data through embedded communication protocols such as LoRaWAN or NB-IoT, primarily serving water utilities seeking operational efficiency and revenue protection. Ultrasonic meters lead product type demand due to accuracy advantages and declining unit costs, while smart meter systems capture expanding margin pools through recurring software revenue. IoT solutions within the technology segment represent the fastest-growing category as utilities prioritize real-time network visibility over basic automated meter reading.
India's Bureau of Indian Standards (BIS) and China's Ministry of Ecology and Environment (MEE) enforce efficiency benchmarks that shape product certification requirements and market access timelines across the region. Australia's Water Services Association and Japan's METI guidelines further fragment compliance obligations for vendors operating across multiple jurisdictions. Stakeholders must monitor evolving data localization mandates and interoperability standards that will determine which technology platforms achieve scalable deployment.
Market Dynamics
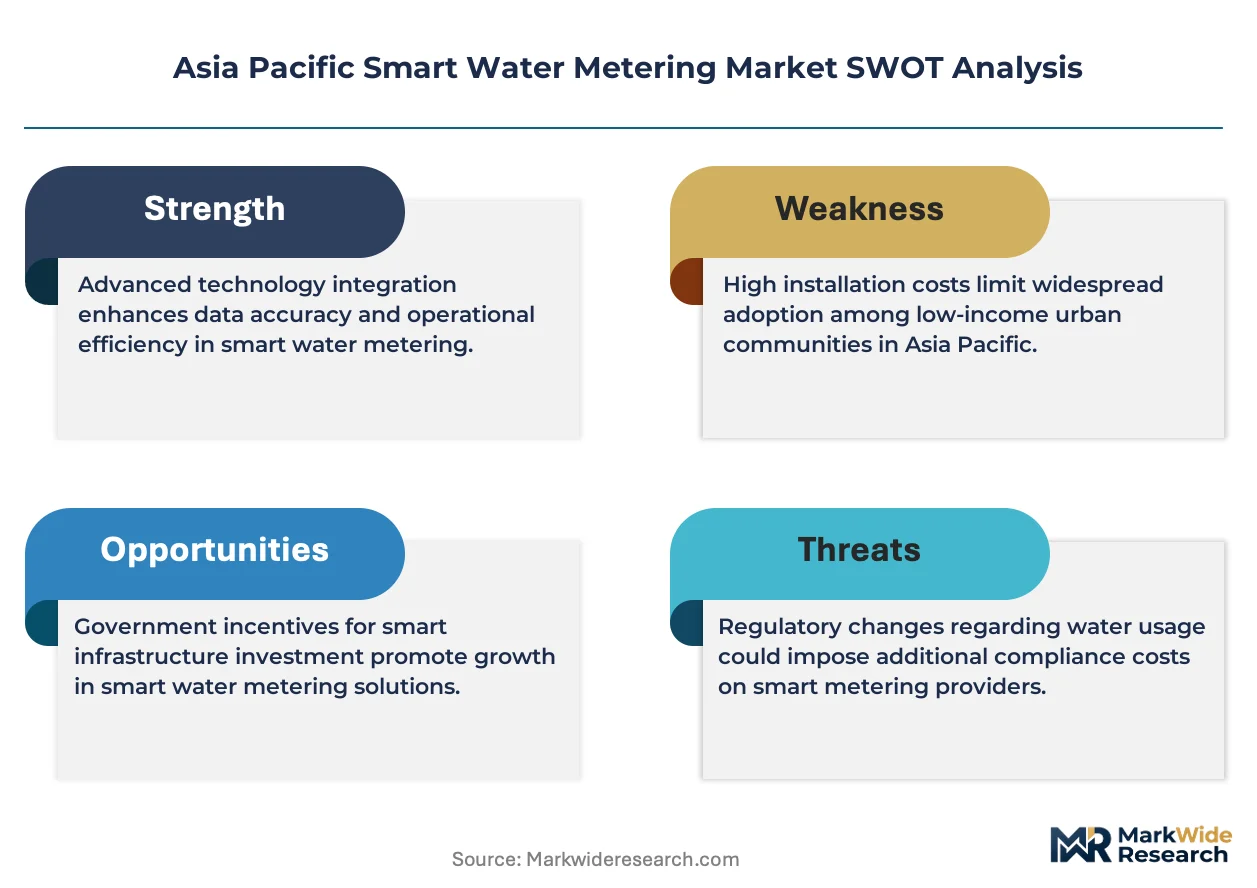
China's dual carbon goals and India's BIS mandates are compressing deployment timelines for ultrasonic and NB-IoT-enabled meters across municipal utilities, forcing vendors to pre-certify hardware against fragmented efficiency benchmarks before tender participation.
Growth Catalysts
- NB-IoT protocol adoption:China's MIIT spectrum allocation enables low-power wide-area networks that slash transmission costs for utilities in tier-one cities.
- Australia's drought contingency frameworks:Water Services Association guidelines mandate real-time leak detection, accelerating replacement of mechanical meters in Sydney and Melbourne.
- Revenue protection urgency:Non-revenue water losses exceeding 30% in several South Asian municipalities drive procurement of automated meter reading systems with tamper alerts.
Market Restraints
- Semiconductor supply concentration:Reliance on Taiwan and South Korea for LoRaWAN chipsets creates procurement bottlenecks during capacity constraints.
- Battery chemistry limitations:Lithium thionyl chloride cell lifespans cap at 15 years, falling short of 20-year meter depreciation schedules.
- Data localization mandates:China's Cybersecurity Law and India's draft data protection rules force redundant cloud infrastructure investments.
Strategic Opportunities
- Vietnam's Mekong Delta utilities:Salinity intrusion monitoring creates demand for multi-parameter sensors beyond basic flow measurement.
- Japan's METI green innovation fund:Subsidies cover 50% of pilot costs for AI-integrated district metering areas in Osaka and Nagoya.
- Convergence of acoustic leak detection with AMI:Vendors bundling pressure transient analysis with consumption data unlock premium pricing from Singapore's PUB.
Industry Challenges
- Interoperability certification delays:Australia's NMI pattern approval and Japan's JIS mark require 18-24 month testing cycles that stall multi-country rollouts.
- Legacy mechanical meter integration:Hybrid AMI deployments demand custom pulse-output modules for 30-year-old brass body installations common in India's older municipal networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Smart Water Metering Market |
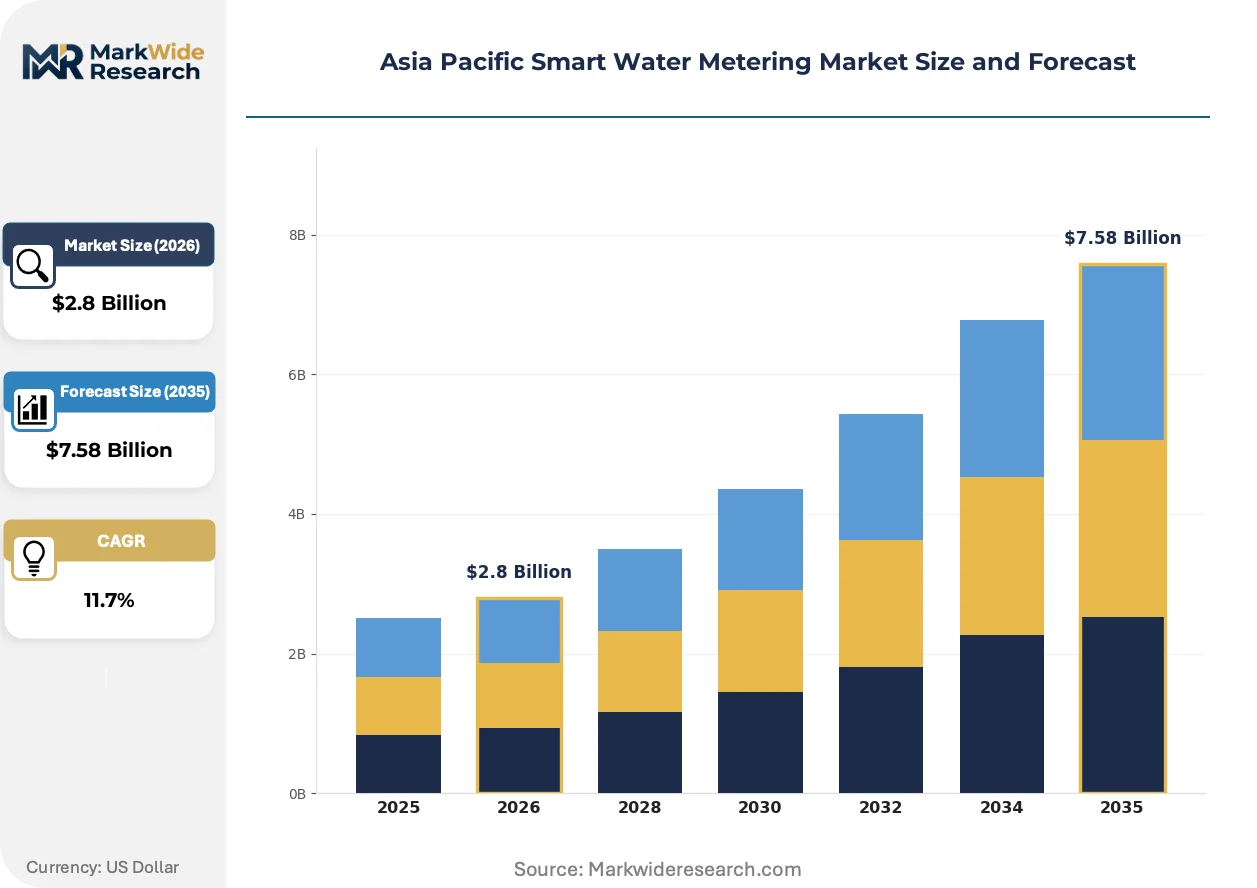
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Meters, Electromagnetic Meters, Mechanical Meters, Smart Meter Systems Technology: IOT Solutions, Wireless Communication, Data Analytics, Cloud Integration End User: Utilities, Municipalities, Residential Users, Commercial Establishments Installation Type: Indoor Installation, Outdoor Installation, Retrofit, New Construction |
| Companies Covered | Itron Inc., Honeywell International Inc., Kamstrup A/S, Landis+Gyr, Siemens, Badger Meter Inc., Diehl Stiftung & Co. KG, Arad Group, Aclara Technologies LLC., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Smart Water Metering Market Emerging Trajectories
Ultrasonic measurement cores and edge computing architectures are displacing mechanical impellers and centralized data processing across Asia Pacific utility procurement specifications.
Ultrasonic transit-time technology measures flow without moving parts, eliminating wear-induced drift. Utilities in China's Pearl River Delta are specifying these meters for 99% accuracy at low-flow conditions. The shift is electrifying competitive differentiation around firmware calibration capabilities rather than mechanical precision.
India's BIS IS 15884 standard mandates IP68 ingress protection and electromagnetic compatibility testing for all smart meters deployed in public networks. The regulation compresses vendor qualification timelines to 12 months. Domestic manufacturers with in-house testing laboratories are securing preferential treatment in state-level tenders.
Performance-based service agreements are replacing capital purchase models for large municipal deployments. Australian utilities now contract meter-as-a-service providers who retain ownership and guarantee 98% data capture rates. This restructuring is most advanced in Victoria's urban water corporations, where opex budgeting flexibility outweighs balance sheet constraints.
Asia Pacific Smart Water Metering Market Segmentation
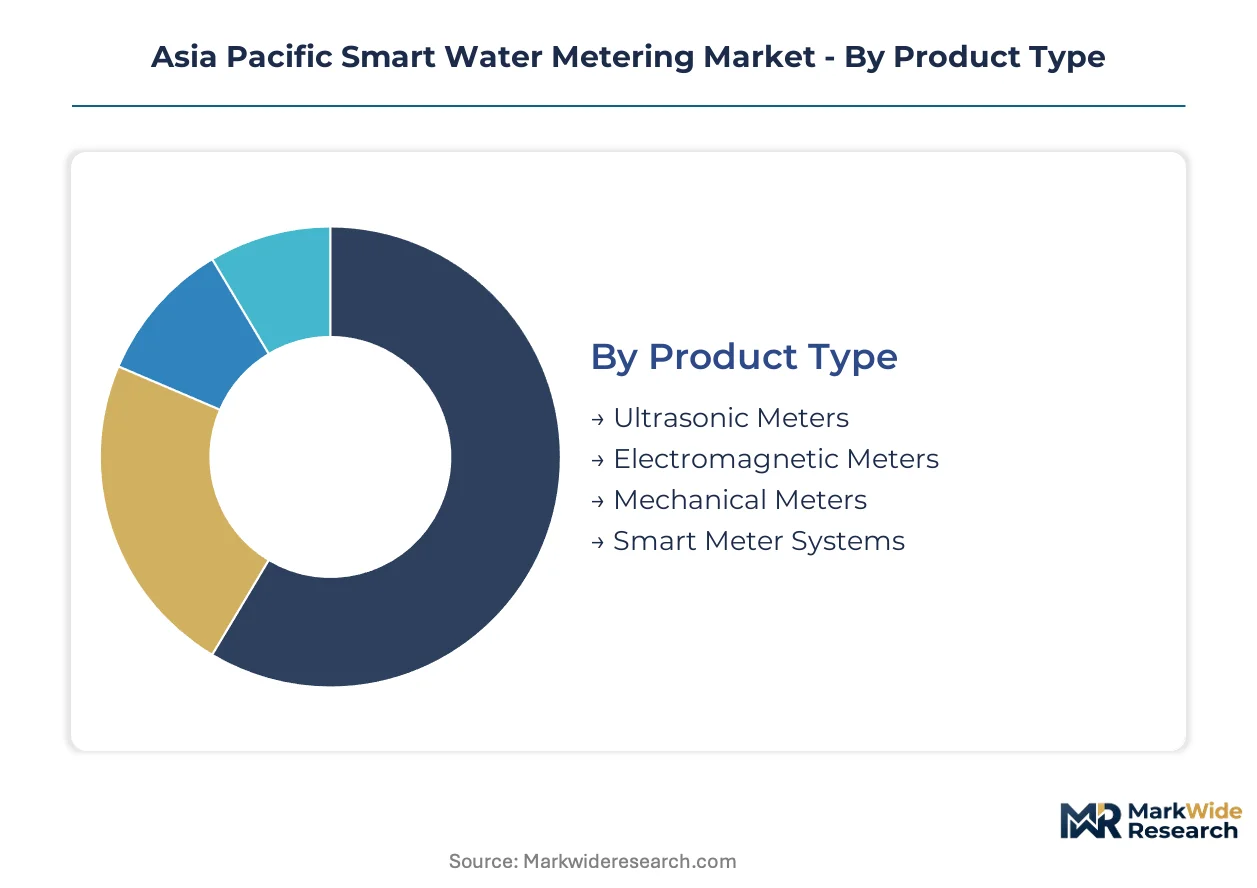
Segmentation in Asia Pacific smart water metering reveals distinct procurement patterns across utility types, technology maturity, and installation constraints. Buyers prioritize accuracy specifications, communication protocol compatibility, and total cost of ownership differently based on infrastructure age and regulatory pressure.
Product Type:
Cost tier separates premium ultrasonic specifications from legacy mechanical replacements in municipal tenders.
- Ultrasonic Meters:Transit-time measurement eliminates moving parts, delivering 99% accuracy at low-flow conditions. China's tier-one cities specify these for district metering areas under MEE efficiency mandates, with Pearl River Delta utilities leading procurement volume.
- Smart Meter Systems:Bundled hardware-software platforms generate recurring revenue through data analytics subscriptions. Australian water corporations in Victoria and New South Wales favor meter-as-a-service models that transfer ownership risk to vendors.
- Electromagnetic Meters:Faraday's law-based measurement suits industrial flow monitoring with conductive fluids, common in Japan's manufacturing belt utilities.
- Mechanical Meters:Impeller and turbine designs persist in India's older municipal networks where capital constraints delay AMI upgrades.
Volume sits with Ultrasonic Meters; growth tilts toward Smart Meter Systems.
Technology:
Application context determines whether utilities prioritize real-time visibility or backward compatibility with existing infrastructure.
- IOT Solutions:Edge computing architectures process consumption data locally before cloud transmission, reducing latency for leak detection algorithms. Singapore's PUB mandates these for pressure transient analysis integration.
- Cloud Integration:Centralized data lakes enable cross-utility benchmarking and predictive maintenance scheduling. China's Cybersecurity Law forces redundant domestic server deployments that inflate implementation costs.
- Wireless Communication:LoRaWAN and NB-IoT protocols dominate last-mile connectivity, with MIIT spectrum allocation in China accelerating NB-IoT adoption.
- Data Analytics:Machine learning models for non-revenue water identification attract premium pricing from South Asian municipalities facing 30% plus distribution losses.
Deployment scale favors Wireless Communication; margin expansion concentrates in IOT Solutions.
End User:
Customer type dictates procurement complexity, from centralized utility tenders to fragmented residential retrofits.
- Utilities:Integrated water authorities with opex budgeting flexibility drive performance-based service agreements. Australia's Water Services Association members contract guaranteed data capture rates rather than capital purchases.
- Municipalities:Fragmented tender processes across India's state-level urban bodies create qualification bottlenecks, with BIS IS 15884 certification compressing vendor timelines to 12 months.
- Residential Users:Individual household installations concentrate in Japan's METI-subsidized green innovation pilots across Osaka and Nagoya.
- Commercial Establishments:High-volume consumers in Vietnam's Mekong Delta industrial zones demand multi-parameter sensors for salinity intrusion monitoring beyond basic flow measurement.
Contract value peaks with Utilities; transaction volume concentrates in Municipalities.
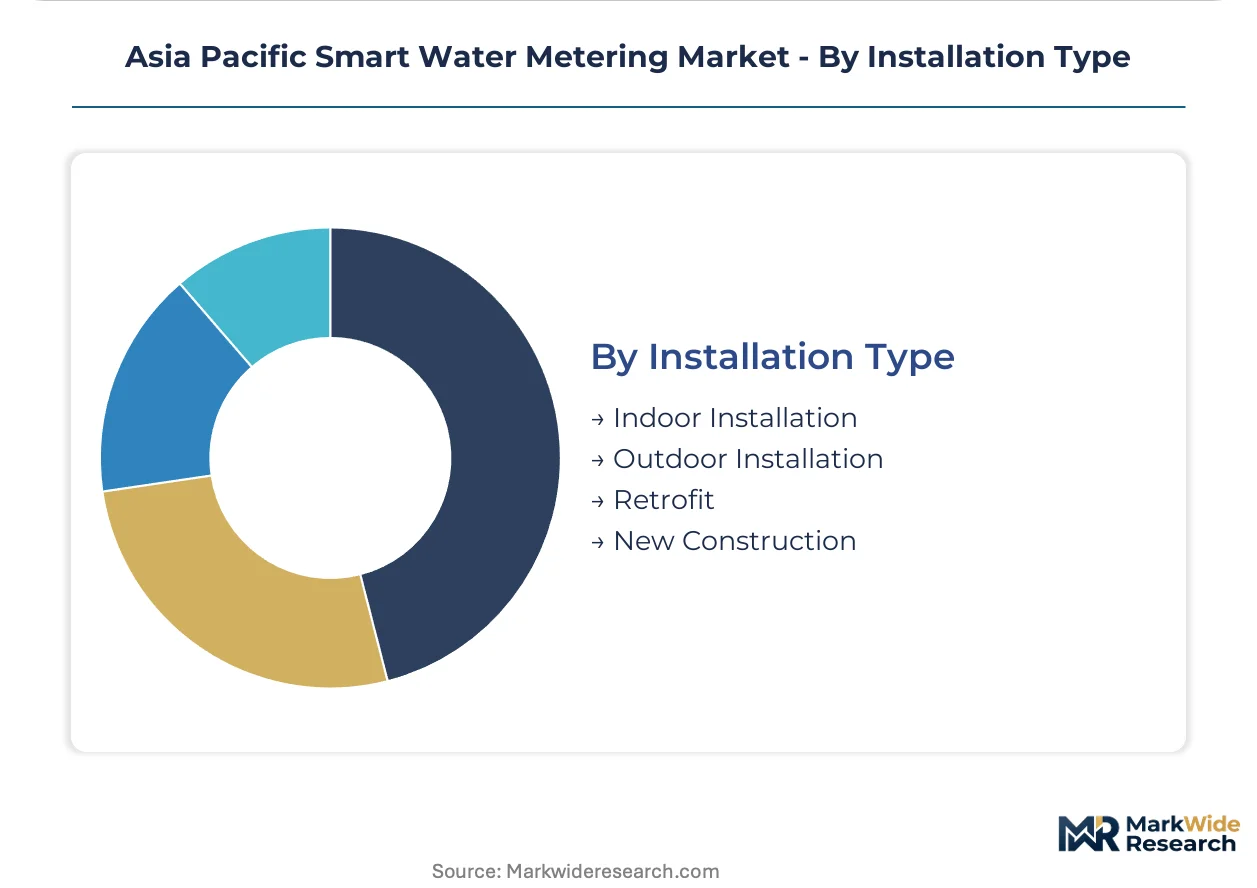
Installation Type:
Site constraints and infrastructure age create divergent technical requirements for deployment teams.
- Retrofit:Pulse-output module integration for 30-year-old brass body meters dominates India's older urban networks. Custom engineering for legacy mechanical infrastructure extends project timelines.
- New Construction:Greenfield deployments specify IP68 ingress protection and electromagnetic compatibility from project inception, aligning with BIS mandates for public network readiness.
- Outdoor Installation:Extended temperature range and vandal-resistant enclosures address Australia's harsh climate conditions and Sydney's public exposure risks.
- Indoor Installation:Compact form factors suit high-rise residential complexes in China's dense tier-one cities where meter room space constraints apply.
Project pipeline depth favors Retrofit; specification control rests with New Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of ultrasonic meter cores for Asia Pacific utilities, while Australia and Japan consume the most advanced AMI systems per capita. Production concentrates in the Pearl River Delta, whereas deployment intensity clusters in drought-prone Australian cities and China's tier-one municipalities.
China
Tier-one cities including Shanghai, Beijing, and Guangzhou drive NB-IoT meter procurement under MEE efficiency mandates. MIIT spectrum allocation enables low-power wide-area networks that slash transmission costs for municipal utilities. The Pearl River Delta hosts manufacturing clusters producing transit-time ultrasonic meters for 99% accuracy specifications.
Australia
Sydney and Melbourne water corporations replace mechanical meters under drought contingency frameworks mandating real-time leak detection. Victoria's urban utilities contract meter-as-a-service providers who guarantee data capture rates rather than executing capital purchases. The Water Services Association guidelines compress procurement timelines for pressure transient analysis integration.
Japan
Osaka and Nagoya pilot AI-integrated district metering areas subsidized through METI's green innovation fund covering 50% of implementation costs. Kansai region utilities specify edge computing architectures for local consumption data processing. JIS mark certification requirements enforce 18-24 month testing cycles for foreign equipment.
India
Maharashtra and Gujarat state urban bodies accelerate AMI tenders following BIS IS 15884 mandates for IP68 ingress protection. Non-revenue water losses exceeding 30% in South Asian municipalities drive procurement of automated systems with tamper alerts. Domestic manufacturers with in-house testing laboratories secure preferential state-level tender treatment.
Vietnam
Mekong Delta utilities demand multi-parameter sensors for salinity intrusion monitoring beyond basic flow measurement. Industrial zones in Ho Chi Minh City periphery contract for electromagnetic meters suited to conductive fluid monitoring. The country's national water regulator tightens efficiency benchmarks for public network deployments.
Asia Pacific Smart Water Metering Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across Asia Pacific smart water metering procurement channels. The vendor base organizes into three tiers: multinational industrial conglomerates with integrated IoT platforms, European specialists in ultrasonic measurement technology, and regional system integrators with local certification expertise. Consolidation pressure intensifies as utilities demand end-to-end service bundles spanning hardware, communications infrastructure, and cloud analytics. Dominant competitive moves include strategic partnerships with telecommunications providers for NB-IoT network access and portfolio diversification into pressure management software.
Among the multinational tier, Itron Inc. and Honeywell International Inc. occupy positions exemplifying integrated platform strategies that extend beyond hardware into data services. Kamstrup A/S and Badger Meter Inc. represent specialization archetypes, with the Danish entity anchoring premium ultrasonic contracts and the US manufacturer exemplifying scale-driven cost control for municipal rollouts. Landis+Gyr and Siemens sit within the industrial conglomerate category, leveraging existing utility relationships across power and gas verticals to cross-sell water metering solutions.
| Leading Market Players |
|---|
| Itron Inc. |
| Honeywell International Inc. |
| Kamstrup A/S |
| Landis+Gyr |
| Siemens |
| Badger Meter Inc. |
| Diehl Stiftung & Co. KG |
| Arad Group |
| Aclara Technologies LLC. |
| Others |
Supply Flow & Price Mechanics
Lithium thionyl chloride cell pricing indices cascade through smart water meter manufacturing into three distinct procurement tiers across Asia Pacific utilities. China's MIIT spectrum allocation for NB-IoT modules compresses communication hardware costs, while BIS IS 15884 certification requirements in India inflate qualification expenses that concentrate in premium ultrasonic specifications.
Pricing Analysis
Cost-down pressure on municipal tender participants accelerates because China's Pearl River Delta manufacturing clusters achieve scale efficiencies in transit-time ultrasonic cores. Three-tier pricing structure across premium, standard, and economy levels separates IP68-certified AMI systems from basic automated meter reading units and legacy mechanical replacements. Price differentiation hinges on firmware calibration capabilities and guaranteed data capture rate commitments. India's state-level urban bodies exhibit highest price sensitivity due to capital budgeting constraints, whereas Australia's Water Services Association members prioritize operational expenditure flexibility over unit economics.
Supply Chain Analysis
Certification gating through BIS IS 15884, Australia's NMI pattern approval, and Japan's JIS mark fragments vendor qualification timelines across 18-24 month testing cycles. Component manufacturing concentrates in China, Taiwan, and South Korea, with LoRaWAN and NB-IoT chipsets drawing from semiconductor foundries in Hsinchu and Seoul. Raw material dependencies include lithium thionyl chloride cells, brass meter bodies, and epoxy potting compounds. Single-source vulnerability in Taiwan semiconductor capacity creates procurement bottlenecks during allocation constraints. Distribution runs through municipal tender processes, regional system integrators, and meter-as-a-service providers retaining ownership risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific smart water metering sits in a technology-transition phase where ultrasonic transit-time measurement displaces mechanical impeller architectures. NB-IoT protocol adoption and edge computing integration reshape competitive positioning across utility procurement specifications.
For Market Incumbents: Extend firmware calibration service offerings to anchor premium pricing against emerging pure-play software competitors. Deepen backward integration into lithium thionyl chloride cell supply through partnerships with South Korean battery manufacturers to defend margin position against raw material volatility. Accelerate pre-certification investments against India's BIS IS 15884 and Australia's NMI standards to compress multi-country rollout timelines.
For New Entrants and Emerging Players: Vietnam's Mekong Delta utilities present an underserved buyer archetype demanding multi-parameter sensors for salinity intrusion monitoring beyond basic flow measurement. India's state-level tender fragmentation creates qualification bottlenecks where domestic manufacturers with in-house testing laboratories secure preferential treatment. A channel partnership strategy with regional telecommunications providers for NB-IoT network access unlocks faster market entry than direct utility sales approaches.
For Investors and Strategic Acquirers: Distressed-cycle entries favor meter-as-a-service providers with contracted revenue streams in Australia's Victoria and New South Wales urban water corporations. Long-term viability over a multi-year horizon rests on recurring software revenue capture rather than hardware shipment volumes. The signal to watch is METI green innovation fund allocation acceleration across Osaka and Nagoya pilot programs as an inflection indicator for AI-integrated district metering area demand.
| Strategic Initiative | Industry Significance |
|---|---|
| NB-IoT Module Pre-Certification | MIIT spectrum allocation in China accelerates municipal utility deployment timelines. |
| Acoustic Leak Detection Bundling | Singapore's PUB mandates pressure transient analysis integration for premium pricing capture. |
| Domestic Testing Laboratory Investment | BIS IS 15884 compliance secures preferential state-level tender treatment in India. |
| Meter-as-a-Service Model Expansion | Australia's Water Services Association guidelines favor opex budgeting flexibility over capital purchases. |
| Edge Computing Architecture Development | Japan's METI subsidies cover pilot costs for AI-integrated district metering areas. |
Methodological Framework
Document review covered customs filings, MIIT spectrum allocation records, BIS certification registries, and Water Services Association procurement guidelines, complemented by interviews with utility planning officers, municipal tender managers, smart meter procurement leads, and telecommunications network engineers. Secondary validation drew from SEC 10-K filings of listed meter manufacturers, NB-IoT deployment databases, and state-level urban body tender documents. Bottom-up unit shipment estimates triangulated against top-down utility capital expenditure projections.
Segment-level outputs across the projection horizon reflect modeled dimensions including product type, communication protocol, installation context, and end-user category. CAGRs derive from regression analysis against historical deployment trajectories in comparable regulatory environments. Forecast inputs incorporate BIS mandate implementation schedules, METI subsidy allocation patterns, and drought contingency framework activation triggers.
Revisions become necessary when semiconductor capacity constraints extend beyond current allocation cycles, data localization mandates expand to additional jurisdictions, or battery chemistry breakthroughs disrupt 15-year replacement assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and utility budgeting flexibility. A model refresh is warranted upon material change in China's dual carbon goal implementation pace or Australia's drought contingency framework activation frequency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Global Smart Electricity Meter Market
Smart Meters
Europe Smart Meters Market
Smart Meters
Smart Gas Meter Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Power Metering Market
Smart Meters
Smart Meter Battery Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Plug in Power Meter Market
Smart Meters
LNG Metering Skids Market
Smart Meters
Smart Electric Meter Market
Smart Meters
North America Gas Meter Market
Smart Meters
Power Monitoring System Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Water Meter Market
Smart Meters
Solar Meter Market