
 Commercial Non IC Card Gas Smart Meter Sales Market | 2026-2036
Commercial Non IC Card Gas Smart Meter Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Non IC Card Gas Smart Meter Sales Market Insights
Commercial building portfolios is recalibrating procurement priorities toward real-time consumption visibility and automated billing reconciliation. Landis+Gyr leverages its installed base across European utility networks to sustain recurring service revenue streams. Itron anchors its position through deep integration with advanced metering infrastructure software stacks. Honeywell International differentiates via cross-selling building automation systems alongside meter hardware.
Commercial Non IC Card Gas Smart Meters are electronic flow measurement devices that communicate consumption data through radio frequency or power-line carrier networks without integrated circuit card interfaces, typically achieving accuracy classes of 1.5 or 2.5 under EN 1359 standards for diaphragm and rotary displacement designs. Their primary commercial purpose is to eliminate manual reading cycles while enabling time-of-use tariff structures and leak detection alerts for multi-tenant properties. Smart Meters within the product type dimension command the dominant revenue share as utilities phase out manual reading programs, while IoT Solutions across the technology dimension represent the fastest-expanding configuration due to cloud-native analytics integration. The retrofit installation category carries higher margin pools than new construction given labor complexity and custom piping adaptation requirements.
The Federal Energy Regulatory Commission shapes US market access through interstate pipeline safety standards that mandate remote shutoff capabilities, while the EU Green Deal and national transpositions under the Energy Efficiency Directive enforce smart meter rollout obligations. Germany's Bundesnetzagentur specifies minimum functional requirements for gas meters in commercial applications, directly influencing product certification pathways. Stakeholders must monitor evolving cybersecurity mandates for connected metering infrastructure as regulatory bodies on both sides of the Atlantic draft firmware update and data encryption requirements.
Market Dynamics
The European Union's F-Gas Regulation is compressing replacement cycles for legacy diaphragm meters across commercial building portfolios, forcing distribution system operators to accelerate capital deployment toward networked measurement systems before binding digitization deadlines.
Growth Catalysts
- EU Energy Efficiency Directive:National transpositions mandate smart meter rollouts for commercial gas connections above defined consumption thresholds, creating regulatory pull across Germany, Italy, and the Netherlands.
- Automated Meter Reading Infrastructure:Radio frequency mesh networks eliminate manual reading labor while enabling real-time leak detection alerts for multi-tenant properties.
- Utility Non-Revenue Loss Reduction:Distribution system operators in North America deploy remote shutoff-capable meters to address theft and measurement inaccuracies in commercial segments.
Market Restraints
- Semiconductor Supply Concentration:RF transceiver and microcontroller fabrication concentrates in East Asian foundries, exposing meter manufacturers to allocation volatility and extended lead times.
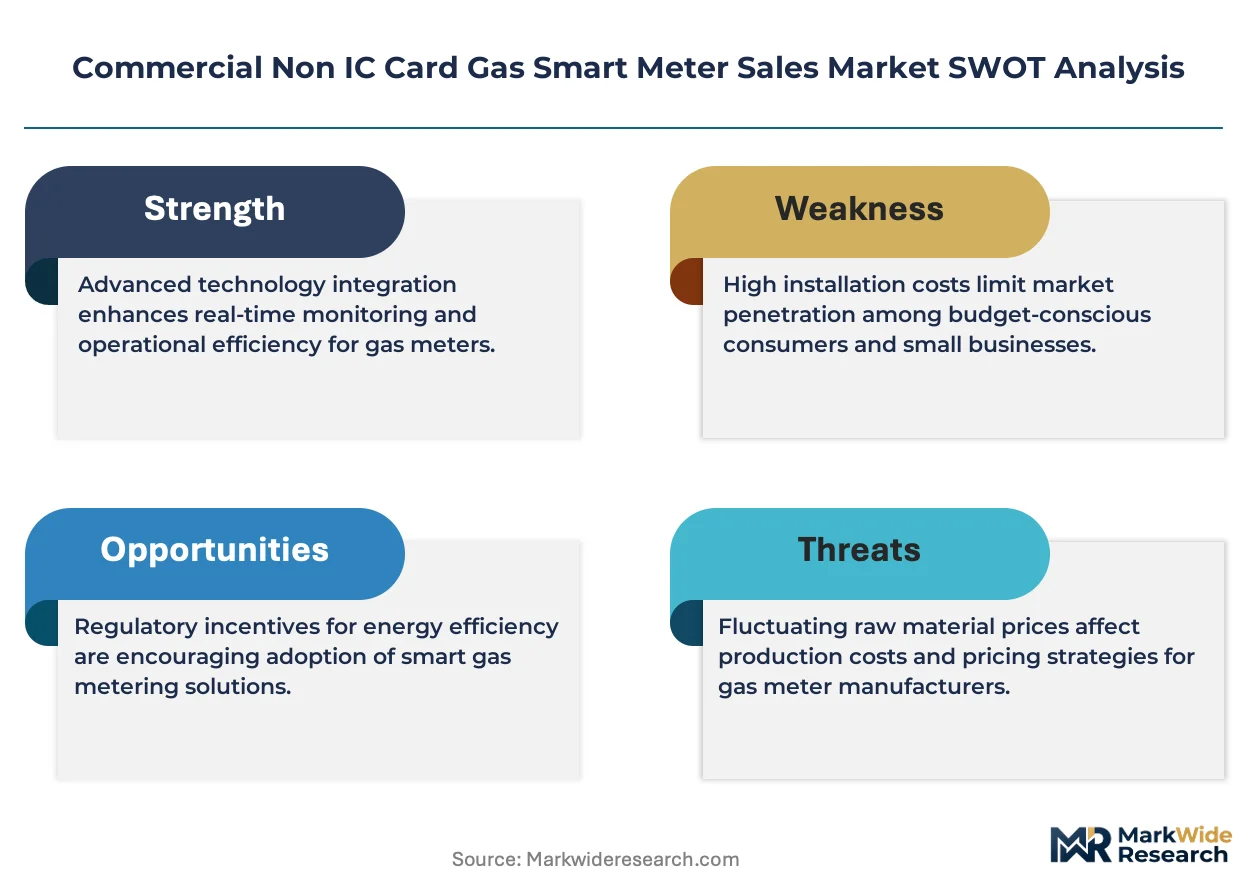
- Copper and Aluminum Price Volatility:Diaphragm meter castings and electrical housings face input cost pressure from commodity market swings, compressing hardware margins on fixed-price utility contracts.
- Mechanical Meter Longevity:Legacy diaphragm designs operate for 15-20 years without failure, extending replacement cycles beyond regulatory mandates in jurisdictions with grandfathering provisions.
Strategic Opportunities
- Cloud-Native Analytics Convergence:Integration of gas consumption data with building management systems creates cross-selling potential for energy service companies targeting commercial portfolios.
- Retrofit Installation Services:Custom piping adaptation and labor-intensive fieldwork in existing buildings command premium pricing compared to new construction deployments.
- US Inflation Reduction Act:Efficiency incentives for commercial building upgrades create indirect demand pull for measurement infrastructure supporting utility rebate programs.
Industry Challenges
- Cybersecurity Certification Complexity:Evolving firmware update and data encryption requirements from the Federal Energy Regulatory Commission and Bundesnetzagentur extend product validation timelines.
- Legacy System Integration:Head-end software from incumbent advanced metering infrastructure vendors creates interoperability friction for new meter entrants seeking utility adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Non IC Card Gas Smart Meter Sales Market |
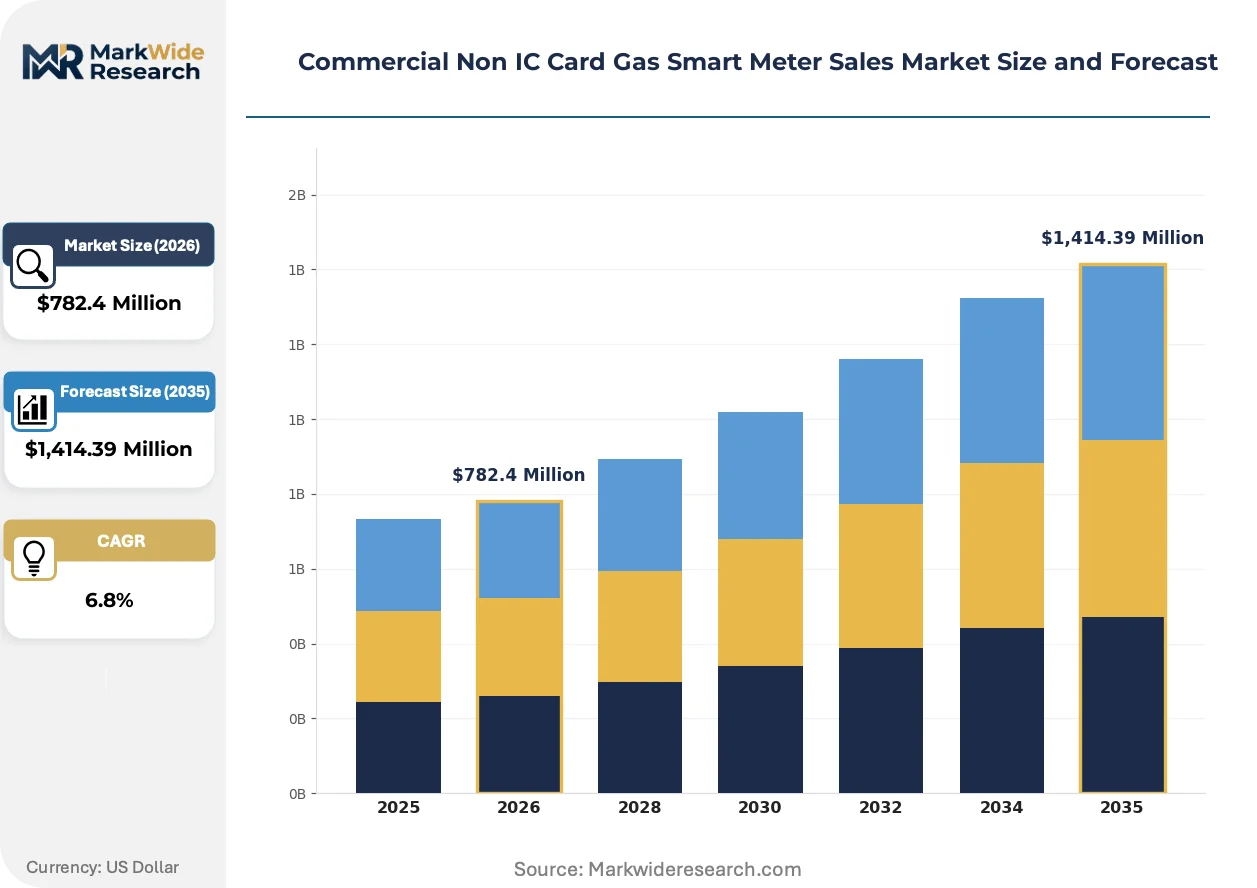
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,414.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
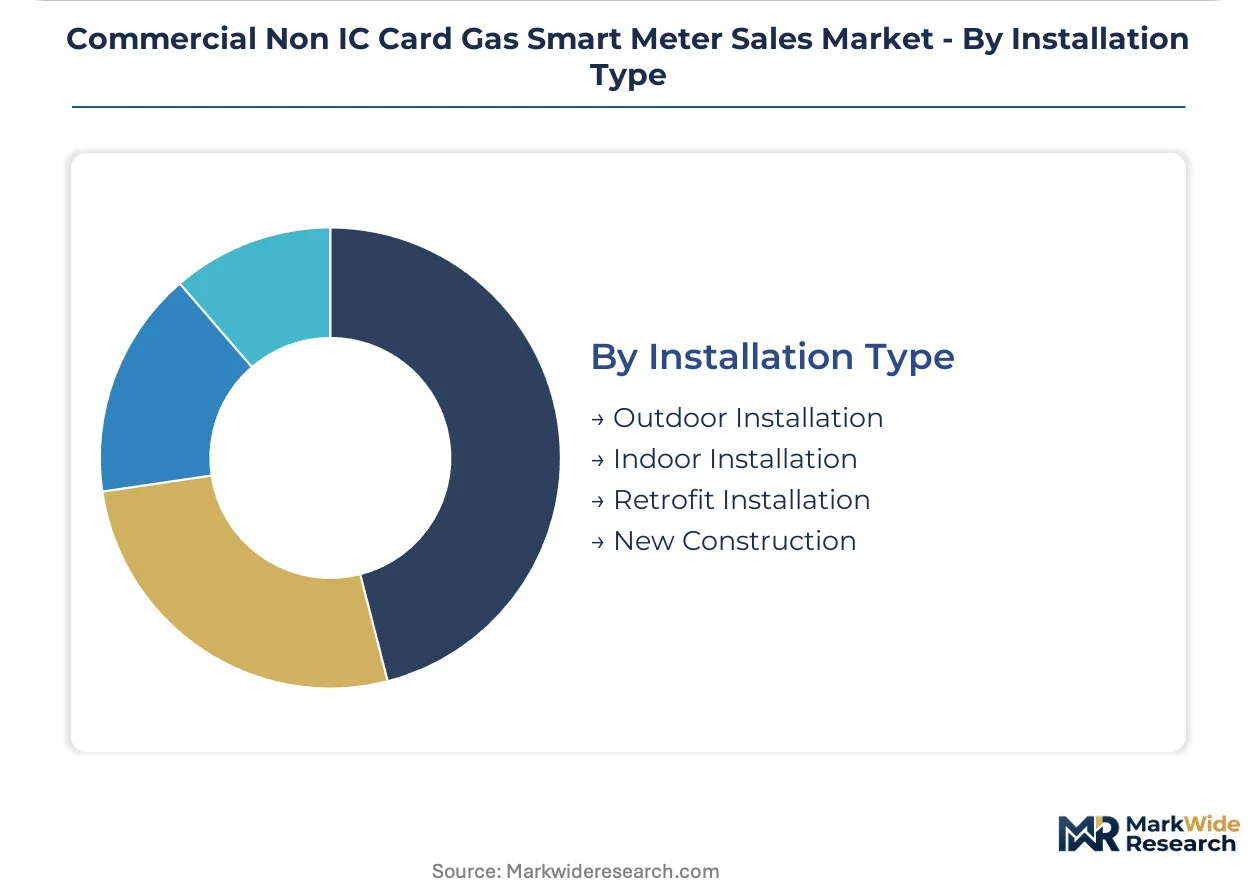
| Segmentation | Product Type: Domestic Meters, Industrial Meters, Smart Meters, Manual Meters Technology: Wireless Communication, Wired Communication, Hybrid Technology, IoT Solutions End User: Utilities, Commercial Businesses, Institutions, Government Agencies Installation Type: Outdoor Installation, Indoor Installation, Retrofit Installation, New Construction |
| Companies Covered | Landis+Gyr, Itron, Honeywell International, Diehl Stiftung & Co. KG, Apator S.A., Siemens, ABB, Kamstrup, GE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Non IC Card Gas Smart Meter Sales Market Trends and Innovations
Measurement hardware is fragmenting into interoperable subsystems while regulatory pressure fuses energy efficiency mandates with cybersecurity requirements, reshaping how utilities specify and procure connected gas infrastructure.
Ultrasonic flow sensing is modularizing commercial gas meter architectures by separating the measurement cartridge from the communications and valve control modules. Large property management firms in Germany are piloting these designs to enable field-swappable metrology without full meter replacement. This modularity is compressing total cost of ownership calculations for distribution system operators evaluating 15-year deployment horizons.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in meter manufacturing processes, forcing suppliers to reformulate seal materials and lubricants. Meter assemblers face reformulation validation costs while awaiting harmonized test protocols from European standardization bodies. Commercial diaphragm meter categories face the steepest compliance burden given their reliance on legacy elastomer compounds.
Building operators are unbundling meter hardware from installation and data management services, issuing separate RFPs for each layer. Energy service companies are capturing the analytics and billing reconciliation functions that utilities once bundled with device supply. This unbundling is most advanced in the United Kingdom, where deregulated metering competition has created specialized field service providers independent of hardware manufacturers.
Commercial Non IC Card Gas Smart Meter Sales Market Segmentation
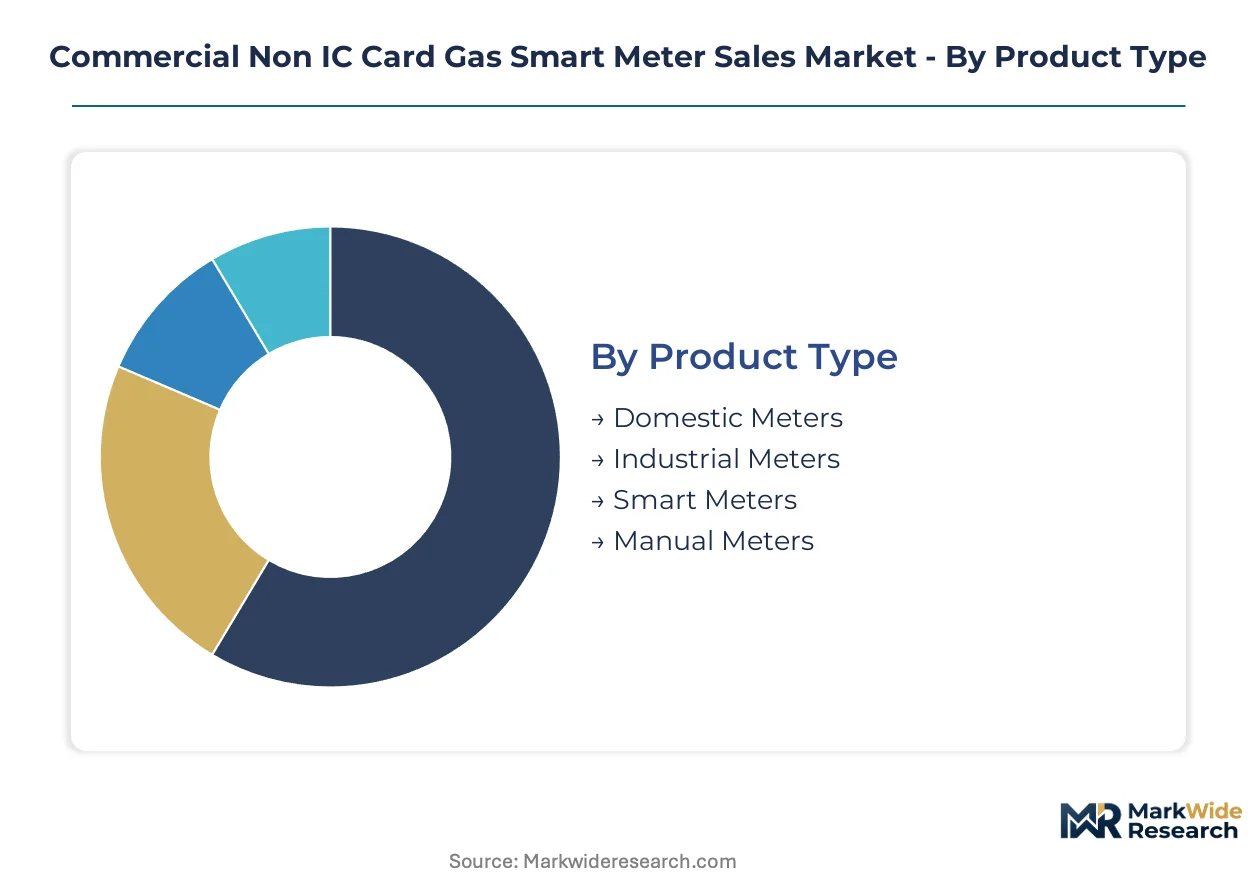
Commercial gas smart meter procurement patterns fragment sharply across technical specifications, deployment contexts, and regulatory exposure. Utility buyers prioritize interoperability certifications while commercial property operators weigh installation disruption against long-term data visibility. These divergent selection criteria create distinct margin pools and competitive dynamics within each segment category.
Product Type:
Supply concentration in diaphragm meter manufacturing concentrates procurement leverage among legacy European and North American foundries, with casting capacity constraints favoring established volume contracts.
- Smart Meters:Electronic flow measurement devices integrate RF transceivers or power-line carrier modules for automated data transmission, achieving EN 1359 accuracy classes of 1.5 or 2.5. German distribution system operators under Bundesnetzagentur digitization mandates are deploying these units most aggressively across multi-tenant commercial properties. Networked measurement capabilities eliminate manual reading labor while enabling time-of-use tariff structures.
- Domestic Meters:Lower-capacity diaphragm designs serve small commercial connections below regulatory smart meter thresholds. Italian utilities are phasing these out fastest under national energy efficiency transpositions, though grandfathering provisions in some jurisdictions extend replacement cycles.
- Industrial Meters:Rotary displacement and turbine configurations handle high-volume commercial connections with extended flow ranges. Chemical processing facilities in the Netherlands specify these for process gas measurement.
- Manual Meters:Legacy mechanical designs without communication modules persist in jurisdictions without binding smart meter mandates. Eastern European building portfolios retain these where regulatory deadlines remain distant.
Today's leader: Smart Meters. Tomorrow's challenger: Industrial Meters.
Technology:
Cost tier differentiation separates cloud-native architectures from legacy field area network deployments, with subscription-based analytics commanding premium pricing over hardware-only sales.
- IoT Solutions:Cloud-native platforms integrate gas consumption data with building management systems through cellular or LPWAN connectivity. Large property management firms in the United Kingdom pilot these configurations for portfolio-wide energy benchmarking. API-first architectures enable third-party analytics vendors to displace utility-controlled data monopolies.
- Wireless Communication:RF mesh networks operating in licensed or unlicensed spectrum bands dominate North American utility deployments. FCC Part 15 compliance requirements shape transceiver selection for commercial meter manufacturers.
- Hybrid Technology:Dual-path architectures combine power-line carrier backbone with wireless last-mile connectivity. German distribution system operators favor these for underground service entries where RF propagation is degraded.
- Wired Communication:Direct Ethernet or RS-485 connections serve campus-style commercial developments with centralized meter banks. University and hospital districts in the Netherlands specify these for cybersecurity isolation.
Volume concentrates in Wireless Communication. Margin expansion centers on IoT Solutions.
End User:
Application maturity varies sharply across customer types, with regulated utilities driving standardization while commercial businesses demand customization.
- Utilities:Distribution system operators specify interoperable meters compatible with incumbent advanced metering infrastructure head-end systems. FERC interstate pipeline safety standards mandate remote shutoff capabilities for US commercial connections.
- Commercial Businesses:Property management firms and retail chains prioritize real-time consumption dashboards for sustainability reporting. Energy service companies capture these accounts through unbundled analytics contracts.
- Institutions:Universities and healthcare systems specify meters with BACnet or Modbus integration for building automation convergence.
- Government Agencies:Federal and municipal facilities procurement emphasizes cybersecurity certification under evolving encryption mandates.
Procurement scale favors Utilities. Specification complexity rises fastest among Commercial Businesses.
Installation Type:
Margin structure inverts between deployment contexts, with labor-intensive retrofit work commanding premium pricing over standardized new construction rolls.
- Retrofit Installation:Custom piping adaptation and confined-space fieldwork in existing commercial buildings generate service revenue multiples above hardware margins. German craft guild certification requirements limit qualified installer supply.
- New Construction:Standardized meter sets installed during building commissioning compete on volume pricing with thin installation margins.
- Outdoor Installation:Weather-hardened enclosures with tamper-evident sealing serve utility-controlled service points. FERC regulations govern accessibility for emergency shutoff.
- Indoor Installation:Aesthetic housings for lobby or mechanical room placement respond to commercial tenant visibility concerns.
Profitability peaks in Retrofit Installation. Volume growth concentrates in New Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors European demand for commercial gas smart meters, with distribution system operators across Germany executing accelerated replacement programs ahead of federal digitization deadlines. Utility procurement teams in North America and Asia-Pacific are deploying similar networked measurement infrastructure to address non-revenue losses and regulatory compliance mandates.
United States
FERC interstate pipeline safety standards mandate remote shutoff capabilities for commercial gas connections, driving utility procurement toward automated meter reading systems. Distribution system operators in Texas and California are replacing legacy mechanical meters with RF-enabled designs to reduce theft-related losses. The Inflation Reduction Act efficiency incentives create indirect demand pull for measurement infrastructure supporting commercial building rebate programs.
Germany
Bundesnetzagentur digitization deadlines are compressing replacement cycles for diaphragm meters across multi-tenant commercial properties. The EU F-Gas Regulation accelerates phase-out of hydrofluorocarbon-dependent seal materials in meter manufacturing. Distribution system operators in Bavaria and North Rhine-Westphalia are deploying hybrid power-line carrier and wireless architectures for underground service entries.
United Kingdom
Deregulated metering competition has unbundled hardware supply from installation and data management services, creating specialized field service providers. Energy service companies are capturing analytics and billing reconciliation functions through separate RFP processes. London property management firms are piloting cloud-native IoT platforms for portfolio-wide energy benchmarking.
Netherlands
National smart metering mandates under EU Energy Efficiency Directive transpositions are phasing out domestic meter categories fastest. Chemical processing facilities in Rotterdam specify rotary displacement and turbine configurations for high-volume process gas measurement. University and hospital districts specify wired Ethernet connections for cybersecurity isolation in campus-style developments.
Italy
National energy efficiency transpositions are accelerating smart meter rollouts for commercial gas connections above defined consumption thresholds. Grandfathering provisions in some jurisdictions extend replacement cycles for lower-capacity connections. Distribution system operators in Lombardy and Emilia-Romagna are prioritizing retrofit installations in existing commercial building stock.
Commercial Non IC Card Gas Smart Meter Sales Market Competitive Landscape
Strategic partnerships dominate the current landscape as meter manufacturers seek to integrate with incumbent advanced metering infrastructure head-end systems. The vendor base clusters around three archetypes: European foundry-integrated specialists with casting capacity advantages, North American RF communications technology licensors, and building automation conglomerates cross-selling energy management software. Portfolio diversification and technology licensing represent the primary competitive moves, with players expanding from hardware supply into cloud-native analytics and retrofit installation services.
Within the European specialist tier, Landis+Gyr and Diehl Stiftung & Co. KG exemplify foundry-integrated positioning with sustained recurring service revenue streams across utility networks. Among North American technology providers, Itron and Honeywell International occupy positions bridging meter hardware with software stack integration and building automation cross-selling. These three anchors represent distinct strategic vectors: utility-centric service models, AMI software convergence, and building system integration.
| Leading Market Players |
|---|
| Landis+Gyr |
| Itron |
| Honeywell International |
| Diehl Stiftung & Co. KG |
| Apator S.A. |
| Siemens |
| ABB |
| Kamstrup |
| GE |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating hydrofluorocarbon-free seal materials and lubricants in commercial gas meter manufacturing. Meter assemblers face reformulation validation costs while awaiting harmonized test protocols from European standardization bodies, compressing margin pools for non-compliant suppliers and concentrating pricing power among early certifiers.
Pricing Analysis
Distributor margins in European utility procurement typically run 12-18 percent for diaphragm meter categories, with direct-to-utility contracts commanding steeper discounts. Three-tier pricing structure across premium, standard, and economy levels separates EN 1359 Class 1.5 certified units from Class 2.5 diaphragm designs and uncertified manual meter alternatives. Pricing pressure stems from copper and aluminum commodity volatility compressing hardware margins on fixed-price contracts. Small commercial connections below regulatory smart meter thresholds exhibit highest price sensitivity, while German distribution system operators under Bundesnetzagentur mandates show lowest elasticity due to binding digitization deadlines.
Supply Chain Analysis
Domestic-content mandates in Germany and Italy are reshaping sourcing patterns by requiring local assembly certification for utility tender eligibility. RF transceiver and microcontroller fabrication concentrates in Taiwan, South Korea, and China, exposing meter manufacturers to allocation volatility. Raw material dependencies span aluminum castings for diaphragm housings, elastomer compounds for seal reformulation, and copper wiring for electrical connections. Single-source vulnerability in East Asian semiconductor foundries represents the dominant structural risk. Distribution runs through utility procurement departments and specialized metering contractors rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Commercial Non IC Card Gas Smart Meter Sales Market functions as a regulatory compounder where EU Energy Efficiency Directive transpositions and F-Gas phase-down mandates create irreversible replacement demand cycles. Distribution system operators face binding procurement deadlines that override short-term price sensitivity.
For Market Incumbents: Lock in recurring service revenue streams by extending advanced metering infrastructure software integration beyond hardware supply. Deepen backward integration into foundry capacity for aluminum diaphragm castings to defend against commodity volatility squeezing fixed-price contracts. Invest in cybersecurity certification pathways ahead of evolving Bundesnetzagentur and FERC encryption mandates to maintain utility procurement eligibility.
For New Entrants and Emerging Players: Mid-sized property management firms in the United Kingdom represent an underserved buyer archetype seeking unbundled analytics contracts separate from utility-controlled data monopolies. Cloud-native IoT platforms with API-first architectures offer the most penetrable technology layer for displacing incumbent meter data management. Pursue white-label partnerships with energy service companies already capturing billing reconciliation functions through separate RFP processes.
For Investors and Strategic Acquirers: Roll-up economics work for specialized field service providers because deregulated metering competition in the United Kingdom and Netherlands has fragmented installation and maintenance capabilities away from hardware manufacturers. Target mid-cap craft guild-certified installers in Germany with captive relationships to distribution system operators. Watch for EU cybersecurity mandate finalization as the inflection signal accelerating consolidation among firmware-capable vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| AMI Software Integration | Deepens vendor lock-in with utility head-end systems against interoperability friction. |
| Retrofit Installation Services | Captures premium pricing multiples in German commercial building stock with craft guild constraints. |
| Ultrasonic Flow Sensing Modularization | Enables field-swappable metrology for Ruhr industrial corridor distribution operators. |
| Cloud-Native Analytics Convergence | Positions energy service companies to displace utility data monopolies in UK portfolios. |
| Cybersecurity Certification Investment | Secures procurement eligibility under evolving FERC and Bundesnetzagentur encryption mandates. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down meter manufacturing capacity tracking forms the analytical core of this study. Primary interviews with distribution system operators, energy service company executives, craft guild-certified installers, and advanced metering infrastructure software architects combined with secondary validation from Bundesnetzagentur technical specifications, FERC interstate pipeline safety standards, EU Energy Efficiency Directive national transpositions, and EN 1359 certification databases. Triangulation across these sources calibrated shipment volumes against regulatory mandate timelines.
Input-output matrices mapped gas consumption thresholds to smart meter deployment obligations across Germany, Italy, Netherlands, United Kingdom, and United States segments. Product type, technology architecture, end-user category, and installation context dimensions structured the segmentation framework. CAGRs derived from replacement cycle compression under F-Gas Regulation deadlines and digitization mandates. Forecast inputs incorporated semiconductor allocation volatility and copper price trajectory sensitivity.
Underlying measurement precision varies by segment; retrofit installation and IoT Solutions categories carry tighter precision than manual meter legacy segments due to data availability from utility procurement disclosures. Forecasts reflect assumptions regarding regulatory deadline adherence and grandfathering provision enforcement. Cybersecurity mandate evolution and East Asian foundry capacity constraints represent primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Watt Meter Market
Smart Meters
North America Smart Meters Market
Smart Meters
Plug in Power Meter Market
Smart Meters
Middle East and Africa Smart Meters Market
Smart Meters
US Smart Meter Data Management Market
Smart Meters
Smart Meter Battery Market
Smart Meters
Smart Electric Meter Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
US Water Meter Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Global Smart Energy Meters Market
Smart Meters
Smart Water Metering Market
Smart Meters
LNG Metering Skids Market
Smart Meters
Global Smart Water Meter Market
Smart Meters
North America Smart Meter Data Management Market