
 Pipeline Pigging System Market | 2026-2036
Pipeline Pigging System Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Pigging System Market Analysis
The premium smart-pigging tier is consolidating around multi-sensor platforms with real-time data telemetry, while commodity foam and plastic pig segments compete on price and regional availability. Baker Hughes Company leverages its turbine and compressor heritage to integrate pigging with broader pipeline integrity suites. T.D. Williamson sustains leadership in bidirectional and sphere launcher systems for complex pipeline geometries. ROSEN Group differentiates through proprietary magnetic flux leakage and ultrasonic testing tool development.
A pipeline pigging system comprises self-propelled or flow-driven devices inserted into pipelines to perform cleaning, inspection, gauging, or batching operations, typically incorporating polyurethane bodies, steel mandrels, and sensor arrays rated for pressures exceeding 100 bar and temperatures to 120°C. Its primary purpose is maintaining throughput efficiency and structural integrity in hydrocarbon, water, and chemical transport networks. Smart pigs within the technology dimension command disproportionate margin pools due to embedded electronics and data analytics requirements, while foam pigs occupy high-volume, low-unit-cost replacement cycles. The offshore deployment category faces elevated technical barriers from deepwater pressure ratings and subsea launcher complexity.
The US DOT PHMSA enforces pipeline safety regulations mandating inline inspection intervals for high-consequence areas, directly stimulating smart pig procurement cycles. API 1163 and NACE SP0102 standards define inline inspection system qualification protocols that vendors must satisfy for market access. Stakeholders must monitor evolving methane emissions detection requirements and assess whether next-generation acoustic pigging platforms can satisfy both integrity and emissions verification mandates.
Market Dynamics
The pipeline pigging system market is experiencing structural pressure from regulatory mandates requiring more frequent inline inspection cycles, particularly in high-consequence areas where aging infrastructure intersects with population density and environmental sensitivity.
Growth Catalysts
- US DOT PHMSA Integrity Management:Federal regulations now mandate accelerated inline inspection intervals for pipelines operating near urban centers and sensitive ecosystems, directly expanding procurement of smart pigging platforms.
- Deepwater subsea infrastructure:Brazil's pre-salt fields and West Africa's offshore corridors are deploying specialized launcher systems rated for pressures exceeding 300 bar, creating demand for pressure-resistant pigging technologies.
- Polyurethane elastomer advances:Next-generation disc and cup materials now withstand aromatic hydrocarbon exposure at 120°C, extending operational windows in heavy crude transport networks.
Market Restraints
- Specialized steel alloy costs:Mandrel bodies requiring API 5L X80-grade steel face price volatility tied to scrap metal markets and electric arc furnace capacity constraints in East Asia.
- Sensor supplier concentration:Magnetic flux leakage sensor arrays depend on a narrow base of European and Japanese magnetic core manufacturers, creating single-source vulnerability.
- Ultrasonic tool velocity limits:Current acoustic transducer technologies cannot reliably capture wall-thickness data at flow velocities exceeding 5 meters per second, restricting deployment in high-pressure gas lines.
Strategic Opportunities
- Carbon capture transport networks:CO2 pipeline specifications require corrosion-resistant pigging protocols that existing vendors have not fully addressed, creating first-mover potential for qualified suppliers.
- Hydrogen blending infrastructure:European operators are retrofitting natural gas lines for hydrogen service, necessitating new pig designs compatible with embrittlement-sensitive steel and modified sealing geometries.
- Real-time telemetry integration:Convergence of fiber-optic communication modules with in-pig data processing enables continuous wall-monitoring rather than episodic inspection, shifting revenue models toward subscription-based integrity services.
Industry Challenges
- Multi-physics simulation expertise:Designing pigs for bidirectional operation in dual-diameter pipelines requires rare competency in computational fluid dynamics coupled with elastomer deformation modeling.
- API 1163 qualification timelines:Third-party validation of new inspection tool configurations typically requires 18-24 months of field trials, compressing product development cycles against regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Pigging System Market |
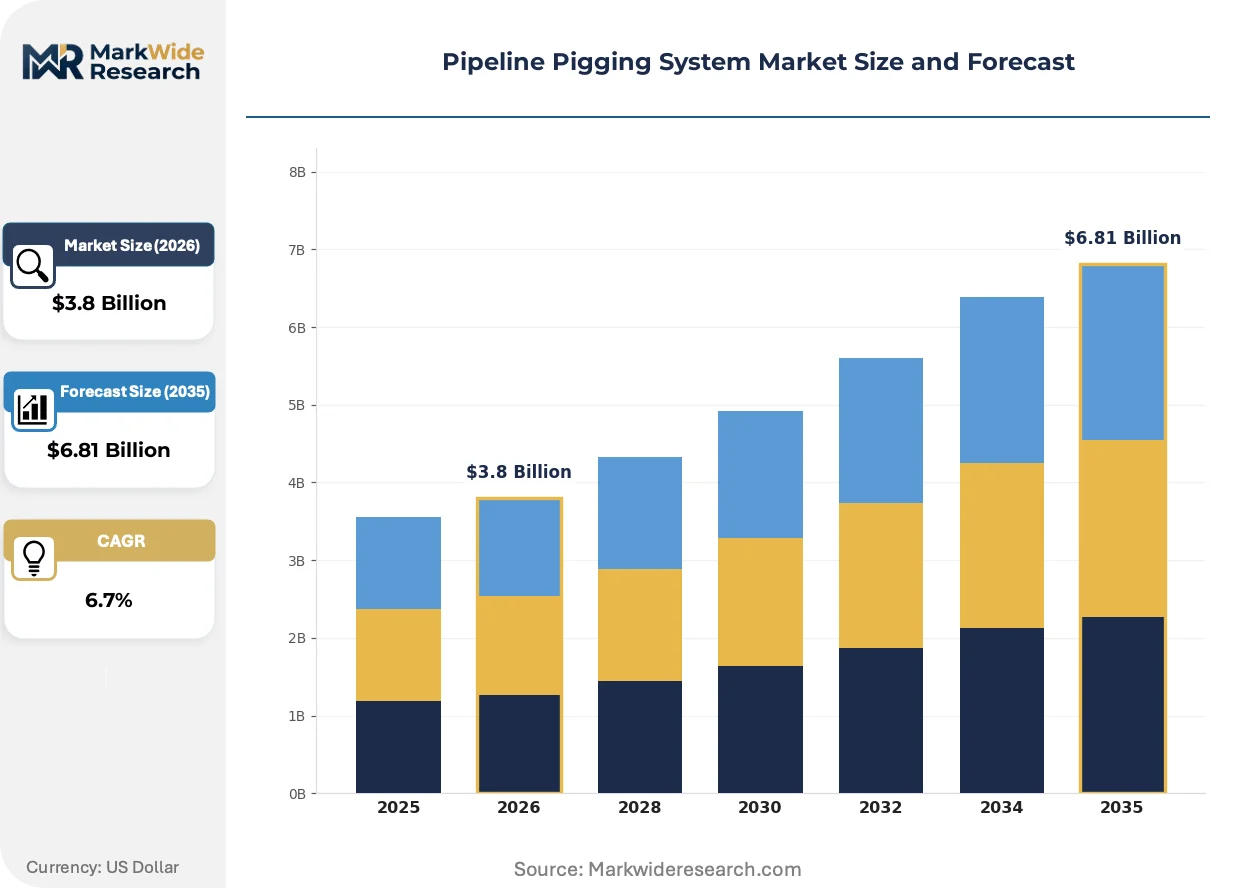
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pigs, Accessories, Monitoring Systems, Cleaning Agents Deployment: Onshore, Offshore, Hybrid, Mobile End User: Oil & Gas, Water Treatment, Chemicals, Food & Beverage Technology: Smart Pigs, Magnetic Pigs, Foam Pigs, Plastic Pigs |
| Companies Covered | Baker Hughes Company, T.D. Williamson, ROSEN Group, 3P Services GmbH & Co KG, NDT Global Corporate Limited, Pigtek Ltd., Enduro Pipeline Services, Dacon Inspection Services Co. Ltd., LIN SCAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Pigging System Market Emerging Trajectories
Pipeline pigging technology is pivoting from episodic maintenance tools toward continuous monitoring platforms, with embedded sensor density and data transmission bandwidth becoming the primary axes of competitive differentiation.
Electromagnetic acoustic transducers are overtaking conventional piezoelectric arrays for crack detection in liquid pipelines. Permian Basin operators now specify EMAT-equipped smart pigs for crude gathering systems where wax deposition complicates ultrasonic coupling. The technology is overtaking legacy methods by eliminating the need for liquid couplant, reducing pre-inspection cleaning requirements and compressing operational downtime by half.
EU methane emissions regulations under the CSRD and F-Gas frameworks now require leak detection verification alongside structural integrity assessment. Pipeline operators must demonstrate quantitative emissions monitoring capabilities during inline inspection campaigns. European transmission system operators are responding by specifying next-generation pigs with integrated infrared sensors capable of detecting ppm-level methane concentrations.
Service unbundling is fragmenting traditional procurement relationships. Major midstream companies now separate tool rental, data analysis, and remediation consulting into distinct contracts, enabling specialist vendors to compete without full vertical integration. This pattern is most visible in the US Gulf Coast corridor, where independent data analytics firms now process pigging telemetry that operators previously received exclusively from equipment suppliers.
Pipeline Pigging System Market Segmentation
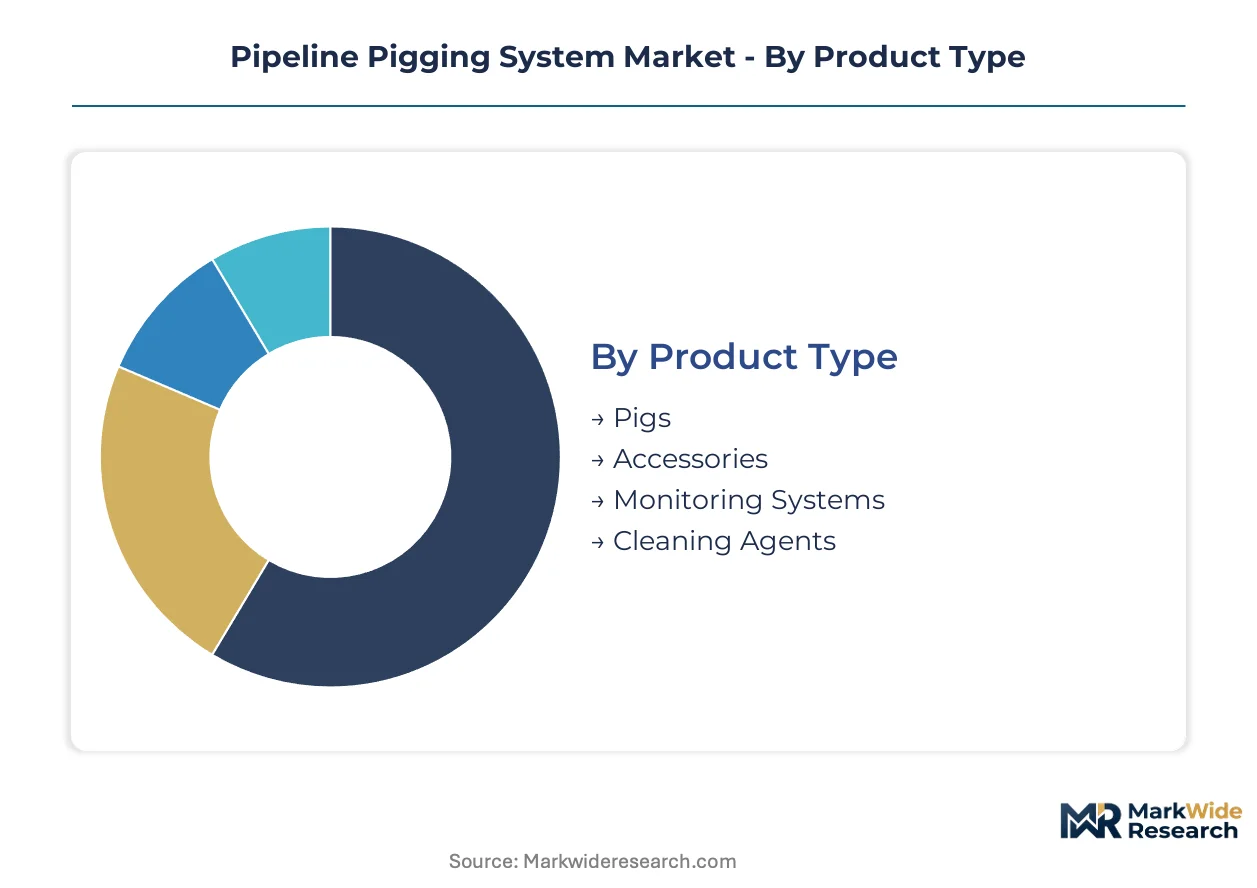
Pipeline pigging systems fragment across four dimensions that shape procurement economics and vendor specialization. Product type determines capital intensity and replacement frequency. Deployment mode governs pressure ratings and launcher complexity. End-user verticals impose divergent regulatory and material compatibility requirements. Technology tier separates premium inspection platforms from commodity cleaning tools.
Product Type:
Capital intensity peaks with monitoring systems requiring embedded sensor arrays and telemetry infrastructure, while cleaning agents represent the lowest barrier to entry.
- Pigs:Self-propelled or flow-driven devices incorporating polyurethane bodies, steel mandrels, and modular sensor mounts rated for pressures exceeding 100 bar. Demand concentrates in the Permian Basin and Gulf Coast corridor where midstream operators face aging infrastructure replacement cycles driven by US DOT PHMSA integrity management mandates.
- Accessories:Launcher and receiver systems, tracking equipment, and recovery mechanisms fabricated from API 5L-grade steel. Procurement cycles accelerate in Brazil's pre-salt fields and West Africa's offshore corridors where deepwater pressure ratings exceed 300 bar.
- Monitoring Systems:Real-time telemetry platforms integrating fiber-optic communication with in-pig data processing.
- Cleaning Agents:Solvent and surfactant formulations for pre-inspection pipeline conditioning.
Most installed capacity flows through Pigs. Expansion is steepest in Monitoring Systems.
Deployment:
Application context dictates engineering complexity and service margins, with subsea installations commanding specialized fabrication expertise.
- Onshore:Conventional pipeline networks operating at standard pressure ratings with above-ground launcher accessibility. The US Gulf Coast corridor and Permian Basin dominate procurement volumes as operators comply with accelerated inline inspection intervals for high-consequence areas.
- Offshore:Subsea infrastructure requiring pressure-resistant designs rated beyond 300 bar and complex subsea launcher systems. Brazil's pre-salt fields and West Africa's offshore corridors drive specification demand for specialized metallurgy and remote deployment capabilities.
- Hybrid:Systems transitioning between onshore terminals and offshore platforms.
- Mobile:Portable launcher configurations for intermittent or emergency deployment.
Onshore deployments retain the largest installed base. Offshore configurations are climbing the fastest as deepwater production expands.
End User:
Regulatory stringency and fluid characteristics create distinct procurement patterns across vertical markets.
- Oil & Gas:Hydrocarbon transport networks subject to US DOT PHMSA integrity management regulations and API 1163 qualification protocols. Operators in the Permian Basin and Gulf Coast corridor now specify multi-sensor smart pigs with real-time data telemetry to satisfy accelerated inspection mandates.
- Water Treatment:Municipal and industrial water distribution systems requiring bi-directional cleaning capabilities.
- Chemicals:Corrosive fluid transport networks demanding specialized elastomer compatibility.
- Food & Beverage:Sanitary-grade pipelines requiring certified cleaning protocols.
Oil & Gas absorbs the dominant share of premium smart-pig procurement. Chemicals verticals are gaining share fastest as corrosion-resistant specifications proliferate.
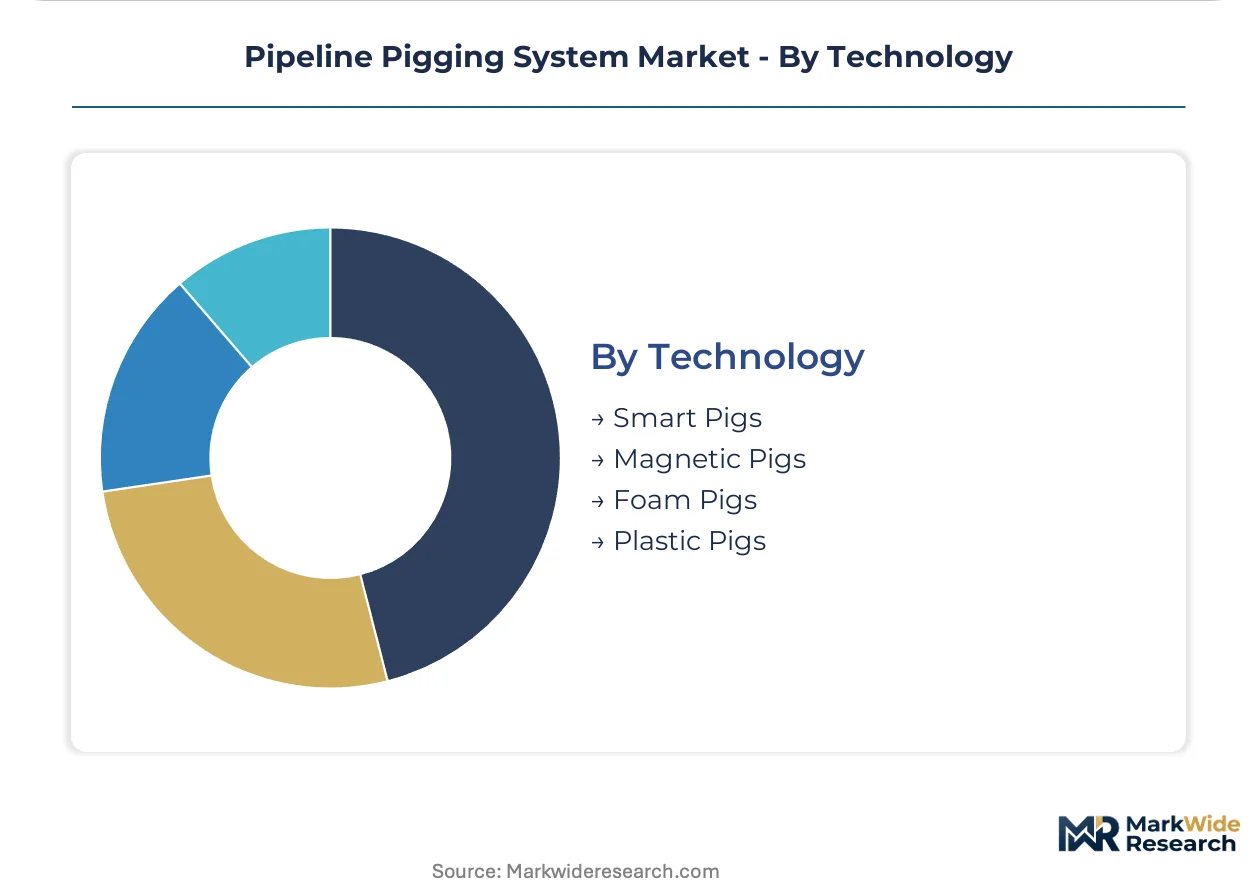
Technology:
Margin pools concentrate in electronic inspection platforms while foam and plastic variants compete on unit economics.
- Smart Pigs:Multi-sensor inspection platforms embedding magnetic flux leakage arrays, ultrasonic transducers, and electromagnetic acoustic transducers for crack detection. Permian Basin operators now specify EMAT-equipped configurations for crude gathering systems where wax deposition complicates ultrasonic coupling.
- Magnetic Pigs:Magnetic flux leakage tools for wall-thickness measurement and metal loss detection.
- Foam Pigs:Low-density polyurethane configurations for routine cleaning and batching operations.
- Plastic Pigs:Injection-molded disc and cup designs for non-metallic pipeline compatibility.
Foam pigs move the highest unit volumes. Smart pigs command the steepest expansion trajectory as regulatory mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineering talent clusters in Houston, Aberdeen, and Singapore anchor the pipeline pigging industry's geographic footprint. These workforce concentrations attract inspection technology vendors and service companies seeking proximity to operator decision centers.
United States
Permian Basin midstream operators and Gulf Coast corridor infrastructure drive procurement of multi-sensor smart pigs. US DOT PHMSA integrity management regulations mandate accelerated inspection intervals for high-consequence areas. Houston hosts the densest concentration of pigging service providers and technology developers.
Brazil
Pre-salt deepwater field development creates demand for pressure-resistant pigging systems rated beyond 300 bar. The national petroleum regulator ANP imposes strict subsea infrastructure inspection protocols. Rio de Janeiro anchors engineering centers serving offshore pipeline operators.
Norway
North Sea aging pipeline networks require frequent inline inspection and cleaning campaigns. The Petroleum Safety Authority Norway enforces rigorous pipeline integrity standards. Stavanger and Bergen host specialized subsea pigging technology firms.
Saudi Arabia
Expansion of Master Gas System infrastructure drives procurement of corrosion-resistant pigging protocols. Saudi Aramco's internal standards exceed international norms for inspection frequency. The Eastern Province concentrates pipeline construction and maintenance activity.
United Kingdom
North Sea decommissioning schedules and remaining production assets sustain inspection service demand. The Health and Safety Executive pipeline safety regulations require documented integrity management. Aberdeen maintains Europe's largest concentration of offshore pigging engineering expertise.
Pipeline Pigging System Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the pipeline pigging system market. The vendor base organizes into three tiers: integrated energy technology conglomerates, specialized inline inspection service providers, and regional fabrication shops. Strategic differentiation concentrates on sensor platform development, data analytics capabilities, and launcher system engineering. Dominant competitive moves include technology licensing partnerships and vertical integration into adjacent pipeline integrity services.
Among integrated technology providers, Baker Hughes Company represents the full-spectrum archetype combining turbomachinery heritage with inspection platform development. T.D. Williamson exemplifies specialized launcher and bidirectional system expertise. ROSEN Group anchors the dedicated inline inspection tier with proprietary tool development capabilities.
| Leading Market Players |
|---|
| Baker Hughes Company |
| T.D. Williamson |
| ROSEN Group |
| 3P Services GmbH & Co KG |
| NDT Global Corporate Limited |
| Pigtek Ltd. |
| Enduro Pipeline Services |
| Dacon Inspection Services Co. Ltd. |
| LIN SCAN |
| Others |
Supply Flow & Price Mechanics
Specialized electromagnetic sensor engineers in Houston and Aberdeen command wage premiums that widen spreads between premium smart-pigging tiers and commodity foam-pig segments. Labor-cost differentials between these engineering clusters and regional fabrication centers in East Asia directly translate into pricing-tier stratification across the market.
Pricing Analysis
Bundled tool-plus-data-service packages are fragmenting into unbundled component contracts. Three-tier pricing structure across premium, standard, and economy levels separates multi-sensor smart platforms with real-time telemetry from basic magnetic flux leakage tools and disposable foam configurations. Pricing pressure stems from midstream operators separating analytics contracts from equipment rental. National oil companies in the Gulf Coast corridor exhibit lowest price sensitivity; independent Permian Basin gatherers face acute margin compression.
Supply Chain Analysis
Magnetic core supply for flux leakage sensors rests on Japanese and European specialty steel producers, with polyurethane elastomer formulation concentrated in Germany and the United States. API 5L X80-grade steel mandrels, EMAT transducer arrays, and fiber-optic telemetry modules constitute critical input dependencies. Single-source vulnerability in magnetic core manufacturing creates exposure to regional trade restrictions. Distribution runs through authorized service centers co-located with major pipeline corridors rather than direct manufacturer-to-operator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pipeline pigging system market functions as a stable compounder anchored by regulatory mandates that enforce recurring inspection cycles regardless of commodity price cycles.
For Market Incumbents: Deepen captive supply of magnetic flux leakage sensor arrays to offset European and Japanese supplier concentration risk. Expand in-house polyurethane elastomer compounding capabilities to capture margin pools currently flowing to specialty chemical suppliers. API 1163 qualification timelines compress product development cycles against regulatory deadlines. For New Entrants and Emerging Players: EMAT-equipped smart pigs for wax-heavy crude gathering systems offer a technology-first wedge into Permian Basin midstream contracts. Carbon capture transport networks and hydrogen blending retrofit specifications represent adjacent white-space targets with unmet corrosion-resistant pigging protocols. Pursue pilot-to-contract pathways with independent data analytics firms rather than competing against vertically integrated incumbents. For Investors and Strategic Acquirers: Pipeline integrity service conglomerates are the most active acquirer in this space, seeking sensor platform capabilities to complement existing launcher system portfolios. The market supports long-term infrastructure exposure through recurring inspection mandates and aging pipeline replacement cycles. Watch EMAT adoption velocity in liquid gathering systems as inflection indicator for technology displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Telemetry Integration | Fiber-optic communication modules enable subscription-based integrity services rather than episodic tool rental. |
| EMAT Sensor Platform Development | Eliminates liquid couplant requirements, compressing operational downtime for Permian Basin operators. |
| Carbon Capture Pigging Qualification | CO2 pipeline specifications create first-mover positioning for corrosion-resistant protocol suppliers. |
| Hydrogen Service Compatibility Testing | European natural gas line retrofits demand new sealing geometries for embrittlement-sensitive steel. |
| Subsea Launcher System Engineering | Brazil's pre-salt fields require pressure-resistant designs rated beyond 300 bar for deepwater deployment. |
Methodological Framework
Coverage spans North America, Europe, Middle East, and Latin America, with primary inputs from each region combining structured interviews with pipeline integrity managers, subsea engineering directors, midstream procurement officers, and regulatory compliance leads at transmission system operators. Secondary validation draws from US DOT PHMSA incident databases, API standards documentation, ANP regulatory filings, and trade flow data for pipeline construction materials. Bottom-up equipment procurement tracking triangulates against top-down infrastructure investment forecasts.
Rate-of-change decomposition separates volume expansion in pipeline mileage from value-per-unit escalation driven by smart-pig technology penetration. The analytical framework models product type, deployment mode, end-user vertical, and technology tier dimensions across the projection horizon. CAGRs derive from regression of historical inspection frequency mandates against pipeline age demographics and regulatory enforcement intensity. Forecast inputs incorporate EMAT adoption curves and carbon capture transport network development timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to methane emissions detection regulatory expansion and hydrogen infrastructure retrofit specifications. Forecasts reflect documented assumptions regarding PHMSA enforcement continuity and subsea field development schedules. A small set of named triggers—CSRD methane verification mandates, ANP inspection protocol revisions, and pre-salt production acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Middle East and Africa Industrial Valves Market
Valves
Insulation Flanges Market
Valves
Oil Drain Valves Market
Valves
Middle East and Africa Electro Hydraulic Servo Valve Market
Valves
Flare Stack Monitoring Systems Market
Valves
Expansion Valves Market
Valves
Dense Phase Vessels Market
Valves
Safety Valve Test Benches Market
Valves
Global Thermostatic Radiator Valve Market
Valves
Total Containment Vessels Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Pipeline Equipment Market
Valves
One-Way Valve Market
Valves
Tubing Heads Market
Valves
Pneumatic Slide Gates Market
Valves
United States Valves Market