
 Global Smart Electricity Meter Market | 2026-2036
Global Smart Electricity Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Electricity Meter Market Analysis
Asian meter manufacturing clusters is restructuring supply dynamics for advanced metering components. Landis+Gyr leverages its European R&D footprint to sustain technology leadership in AMI platforms. Siemens AG anchors its position through deep utility relationships and integrated grid software stacks. Kamstrup A/S differentiates via precision ultrasonic measurement and Nordic energy efficiency compliance.
A smart electricity meter is a digital device that measures electrical energy consumption at intervals of one hour or less and communicates that data to the utility for monitoring, billing, and system optimization; it typically incorporates two-way communication modules, solid-state measurement engines, and remote disconnect capabilities operating across RF mesh, cellular, or power-line carrier networks. Residential end users represent the largest installed base, though utility providers command the highest per-unit margins through enterprise-grade AMI deployments. Wireless technology segments are expanding fastest as utilities phase out manual read systems, while AMR retains residual share in cost-constrained emerging markets.
The EU Green Deal and F-Gas Regulation shape European meter specifications, while the EPA and state-level public utility commissions drive North American replacement cycles through efficiency mandates and time-of-use pricing frameworks. China's NMPA and GB standards authorities enforce domestic communication protocol requirements that limit foreign vendor access. Stakeholders must weigh interoperability standards against sovereign certification barriers when allocating R&D budgets across regional product variants.
Market Dynamics
AMI platform standardization is compressing vendor margins while accelerating procurement cycles for utilities seeking interoperability across RF mesh and cellular networks.
Growth Catalysts
- EU Green Deal efficiency mandates:Binding targets for real-time consumption monitoring drive replacement waves across Germany, France, and Italy.
- Wireless RF mesh networks:Utilities abandon manual read systems for automated data capture, reducing operational overhead and enabling dynamic pricing.
- China's dual carbon goals:State Grid Corporation accelerates smart meter deployment to meet provincial-level carbon intensity reduction commitments.
Market Restraints
- Semiconductor supply concentration:RF transceiver and power management IC sourcing remains concentrated in Taiwan and South Korea fabrication facilities.
- F-Gas Regulation compliance costs:EU restrictions on fluorinated gases increase sealed meter housing production expenses for European deployments.
- Legacy AMR infrastructure:Existing drive-by reading systems in cost-constrained utilities delay full AMI conversion timelines.
Strategic Opportunities
- India's smart city initiatives:Urban local bodies under the Ministry of Housing and Urban Affairs seek integrated metering for distribution loss reduction.
- Edge AI convergence with AMI:On-device anomaly detection enables predictive maintenance and fraud identification without cloud dependency.
- US Inflation Reduction Act incentives:Tax credits for grid modernization accelerate municipal utility procurement cycles.
Industry Challenges
- Cybersecurity certification timelines:IEC 62351 and NERC CIP compliance requirements extend product validation cycles by months.
- Protocol fragmentation:DLMS/COSEM, IEEE 2030.5, and proprietary utility standards force redundant firmware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Electricity Meter Market |
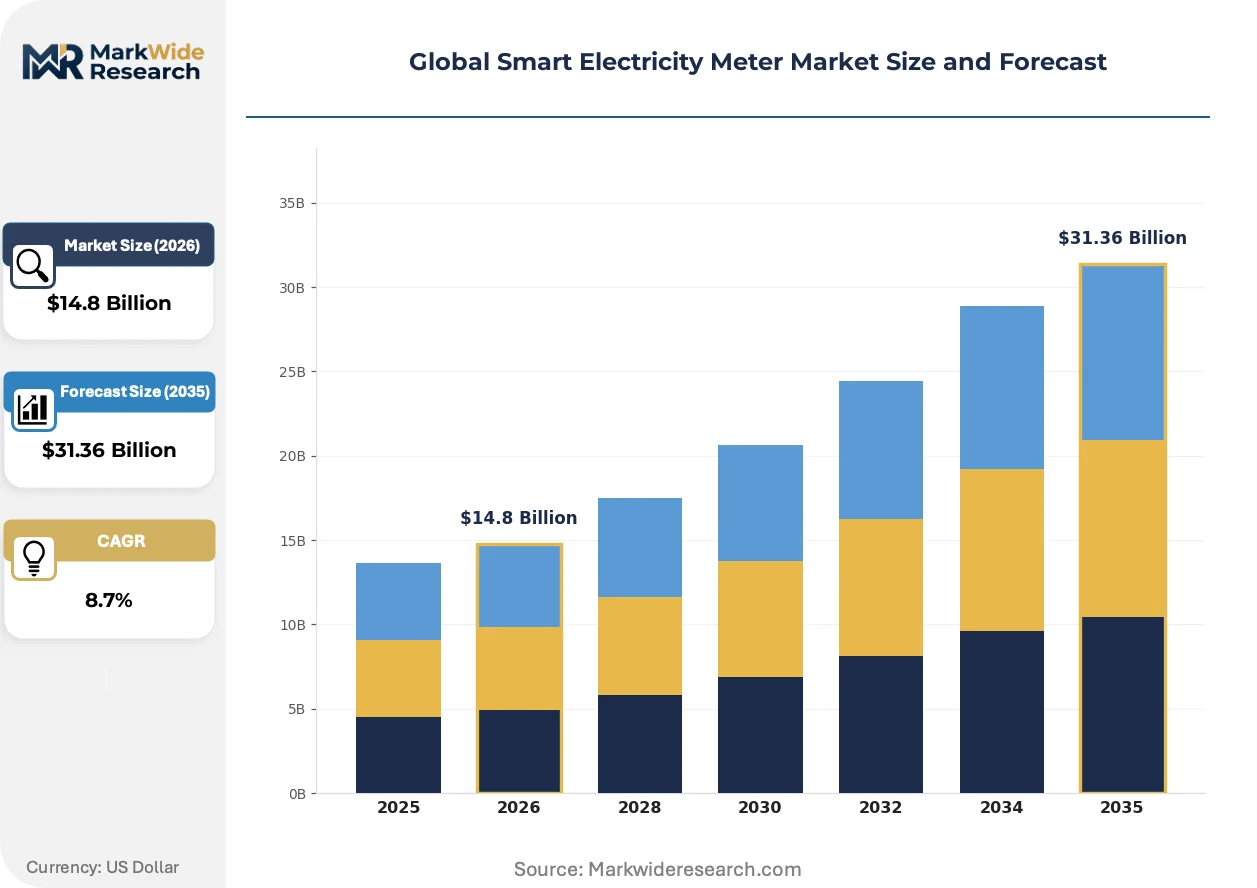
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Meter Type: Smart Digital, Smart Analog, Prepayment, Advanced Metering Infrastructure Technology: AMR, AMI, Wireless, ZigBee End User: Residential, Commercial, Industrial, Utility Providers Installation Type: Indoor, Outdoor, Retrofit, New Installation |
| Companies Covered | Landis+Gyr, Itron, Inc., ABB Ltd., Siemens AG, GE, Kamstrup A/S, Schneider Electric SE, Sensus, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Electricity Meter Market Emerging Trajectories
Communications module architecture is converging toward software-defined radios, enabling single-hardware platforms to address multiple regional spectrum allocations and protocol requirements.
Ultrasonic measurement cores are consolidating position in high-precision residential and commercial deployments. Nordic utilities specify solid-state engines for their immunity to magnetic tampering and extended calibration stability. This consolidation is compressing electromechanical induction meter residual share to niche retrofit applications only.
REACH substance restrictions and RoHS recast directives are forcing redesigns of meter PCB assemblies and solder compositions. European manufacturers must validate alternative alloys and flame retardants before CE marking renewal. German meter suppliers face the tightest compliance windows as TÜV certification bodies process backlog.
Utility procurement departments now bundle AMI hardware with managed services and software licensing. Traditional equipment-only tenders lose share to outcome-based contracts spanning installation, data management, and analytics. This pattern is most visible in UK water-electricity multi-utility frameworks and Australian state-owned distributor tenders.
Global Smart Electricity Meter Market Segmentation
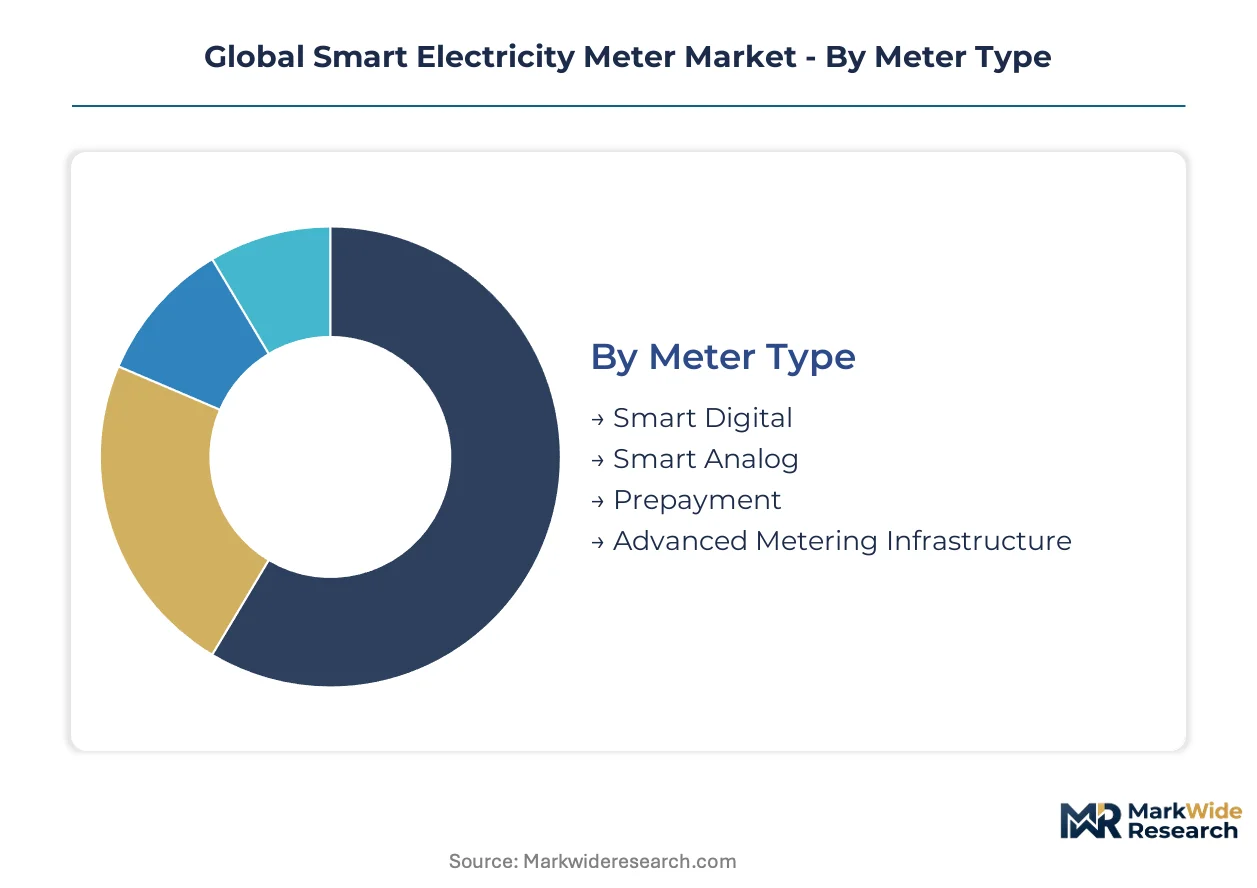
Segmentation in smart electricity metering reveals how procurement priorities diverge across utility business models and regulatory environments. Understanding these divisions illuminates where technology investments concentrate and which specifications command premium pricing.
Meter Type:
Utility procurement teams distinguish meters by data granularity and integration depth with grid management platforms.
- Smart Digital:Solid-state measurement engines capture consumption at 15-minute intervals with embedded RF or cellular communications. German distribution network operators specify these for EU Green Deal compliance and dynamic tariff enablement.
- Advanced Metering Infrastructure:Two-way communication platforms integrate remote disconnect, outage detection, and distributed energy resource coordination. State Grid Corporation of China deploys these at scale for provincial carbon intensity monitoring and demand response orchestration.
- Smart Analog:Electromechanical cores with digital readout overlays serve cost-constrained retrofit scenarios where full AMI conversion remains uneconomical.
- Prepayment:Token-based or smart-card systems dominate informal settlement electrification in South Africa and emerging market utilities seeking revenue protection.
Volume sits with Smart Digital; growth tilts toward Advanced Metering Infrastructure.
Technology:
Communication architecture determines deployment economics and interoperability with existing utility IT infrastructure.
- AMI:Platform-level solutions bundle meters, communications networks, and head-end systems into unified procurement frameworks. UK multi-utility tenders increasingly specify AMI as a managed service rather than hardware-only purchase.
- Wireless:RF mesh and cellular modules eliminate manual meter reading while supporting time-of-use pricing. US municipal utilities leverage FCC spectrum allocations for private LTE networks in rural service territories.
- AMR:Automated one-way data collection retains residual share where drive-by reading infrastructure already exists and full two-way communication remains unjustified.
- ZigBee:Home area network protocols enable in-premise energy management displays and appliance-level load disaggregation for residential demand response programs.
Wireless deployments dominate new installations; AMI platforms capture the steepest expansion trajectory as utilities phase out legacy systems.
End User:
Customer scale and regulatory exposure shape specification requirements and contract value.
- Utility Providers:Enterprise-scale AMI deployments span millions of endpoints with integrated analytics platforms. These contracts command the highest per-unit margins through software licensing and data management services.
- Residential:Single-family and multi-unit dwellings represent the largest installed base by unit count, with procurement driven by regulatory mandates for real-time consumption visibility.
- Commercial:Small and medium enterprises require sub-metering granularity for tenant billing and sustainability reporting compliance.
- Industrial:Heavy manufacturing and data center operators specify high-accuracy meters with power quality monitoring for tariff optimization and equipment protection.
Residential segment holds unit volume; Utility Providers concentrate revenue and margin.
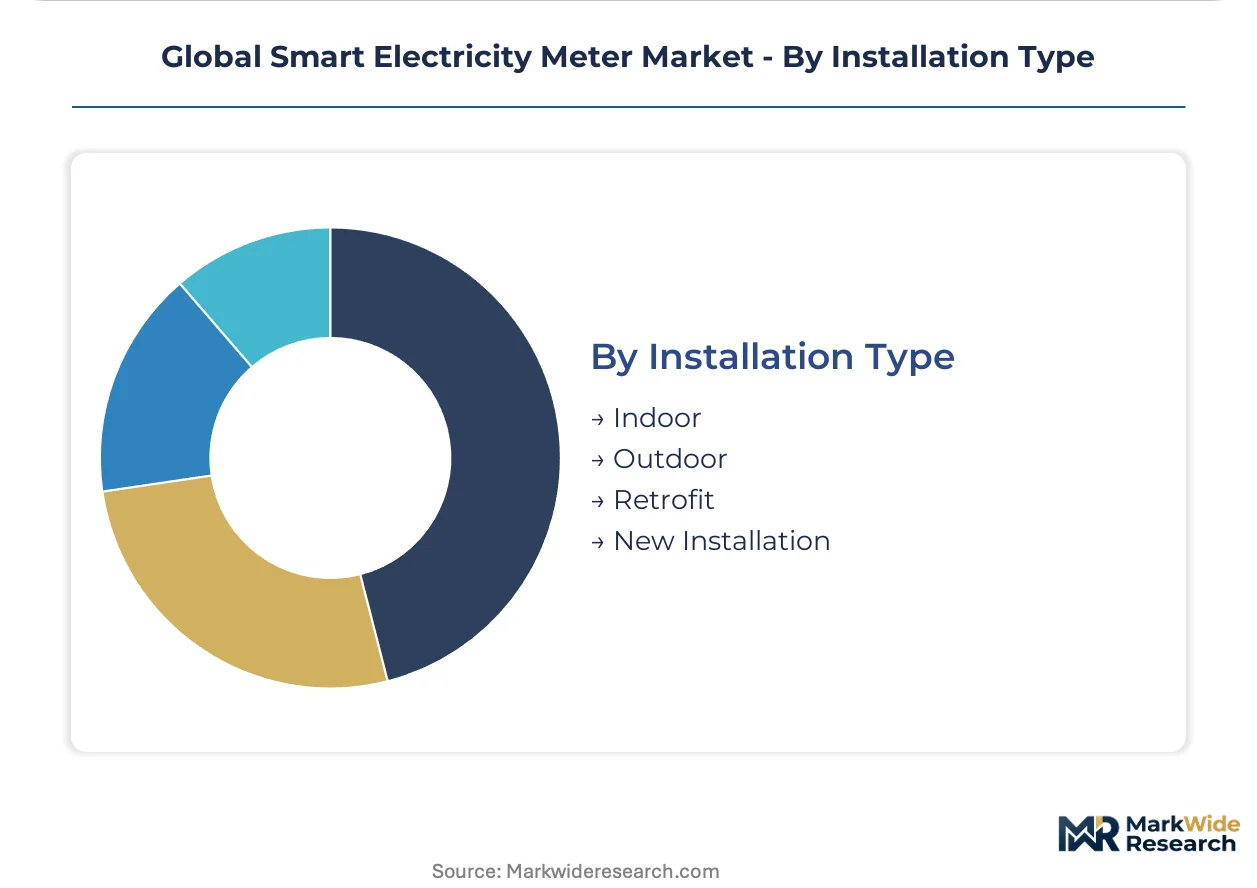
Installation Type:
Physical deployment context determines enclosure specifications and commissioning complexity.
- New Installation:Greenfield deployments integrate meters during construction, enabling optimal communications module placement and avoiding legacy compatibility constraints. China's urbanization drives concentrated demand here.
- Retrofit:Replacement of electromechanical meters in existing sockets requires form-factor compatibility and minimal service disruption. European replacement waves under EU efficiency mandates dominate this segment.
- Outdoor:IP-rated enclosures withstand temperature cycling and moisture exposure for pole-mounted or pedestal installations common in US suburban distribution.
- Indoor:Basement and utility room placements predominate in dense European urban housing stock with dedicated meter cabinets.
Retrofit work sustains near-term volume; New Installation expands most quickly in emerging market grid extensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing capacity in Inner Mongolia anchors Chinese meter component supply. German precision engineering clusters around Munich and Stuttgart shape European AMI specifications. Silicon Valley RF semiconductor design houses influence wireless communication module roadmaps worldwide.
United States
State-level renewable portfolio standards and grid modernization mandates drive municipal utility procurement. The Inflation Reduction Act channels tax credits toward AMI deployment in rural electric cooperatives. Texas and California distribution utilities lead endpoint installation velocity.
Germany
Distribution network operators face binding EU Green Deal efficiency targets for real-time consumption monitoring. The F-Gas Regulation tightens sealed housing specifications for outdoor meter installations. Industrial metering demand concentrates in Bavaria's manufacturing belt.
China
State Grid Corporation accelerates provincial carbon intensity reduction through AMI deployment at scale. The National Energy Administration enforces domestic communication protocol requirements through GB standards certification. Yangtze River Delta component suppliers dominate RF module and power management IC sourcing.
India
Urban local bodies under the Ministry of Housing and Urban Affairs seek integrated metering for distribution loss reduction. The Central Electricity Authority mandates smart prepaid meters for state distribution companies. Maharashtra and Gujarat utilities pilot RF mesh networks in dense urban corridors.
Japan
Feed-in-tariff revisions for distributed solar generation necessitate bidirectional metering infrastructure. METI efficiency standards accelerate replacement of electromechanical meters in multi-unit dwellings. Kansai region utilities specify ultrasonic measurement cores for magnetic tamper immunity.
Global Smart Electricity Meter Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-AI integration and managed service bundling. The vendor base stratifies across three tiers: integrated conglomerates with software stacks, specialized measurement technology firms, and regional contract manufacturers. Two strategic archetypes dominate: technology licensors seeking protocol standardization, and vertically integrated suppliers controlling RF module sourcing. Competitive moves concentrate on AMI platform consolidation and outcome-based contract structures.
Among European-based specialists, Landis+Gyr and Kamstrup A/S occupy positions emphasizing precision measurement and Nordic energy efficiency compliance. Siemens AG exemplifies the integrated conglomerate archetype through deep utility relationships and grid software integration. These three represent distinct competitive vectors: specialized measurement engineering, regional regulatory alignment, and enterprise-scale platform bundling.
| Leading Market Players |
|---|
| Landis+Gyr |
| Itron, Inc. |
| ABB Ltd. |
| Siemens AG |
| GE |
| Kamstrup A/S |
| Schneider Electric SE |
| Sensus |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
RF transceiver module costs cascade from Taiwan and South Korea fabrication facilities through three distinct pricing tiers downstream, with premium AMI platforms absorbing semiconductor scarcity through bundled managed service contracts while economy-tier electromechanical retrofits face margin compression from raw material volatility.
Pricing Analysis
Warranty and service bundling separates premium AMI deployments from hardware-only tenders, with German distribution network operators specifying 10-year calibration guarantees and remote firmware update subscriptions as standard procurement terms. Price differentiation hinges on IEC 62351 cybersecurity certification tier and volume scale, with municipal utilities commanding standard-tier rates and rural electric cooperatives negotiating economy-tier stripped configurations. Pricing pressure stems from AMI platform standardization compressing vendor margins as interoperability mandates proliferate. Residential retrofit buyers exhibit highest price sensitivity, while enterprise-scale utility providers prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Warehouse distribution for meter components follows hub-and-spoke patterns anchored in Rotterdam for European deployments and Singapore for Asia-Pacific fulfillment, with regional distribution centers holding 6-8 weeks of RF module safety stock. Manufacturing concentration centers on China for PCB assembly and plastic injection molding, Germany for precision measurement core calibration, and Mexico for North American final assembly. Raw material dependencies include rare earth elements for magnetic shielding, copper for current transformers, and specialized epoxy resins for outdoor-rated enclosures. Supply chain risk manifests in single-source vulnerability for Taiwan-sourced power management ICs. Distribution runs through direct utility procurement channels and specialized energy infrastructure distributors with meter-specific logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart electricity meter market sits in a technology-transition phase where solid-state ultrasonic measurement cores are systematically displacing electromechanical induction engines across all but the most cost-constrained retrofit scenarios.
For Market Incumbents: Extend software stack integration depth to defend against pure-play communications module vendors encroaching on AMI platform territory. Prioritize backward integration into RF semiconductor sourcing to mitigate Taiwan fabrication concentration risk. Invest in IEC 62351 pre-certification testing to compress product validation cycles as cybersecurity mandates tighten. For New Entrants and Emerging Players: Municipal utilities in US rural electric cooperatives represent the most penetrable buyer segment, with Inflation Reduction Act tax credits creating procurement acceleration windows. Target India's urban local bodies under smart city initiatives, where distribution loss reduction mandates outpace incumbent vendor capacity. Pursue white-label manufacturing partnerships with established European precision engineering clusters to bypass GB standards certification barriers in China. For Investors and Strategic Acquirers: State Grid Corporation tender announcements for provincial carbon intensity monitoring infrastructure are the leading indicator that Chinese AMI deployment velocity is inflecting upward. Position for 5-10 year holding periods aligned with EU Green Deal replacement wave completion. Acquisition targets should display ultrasonic measurement core IP and existing TÜV certification relationships.| Strategic Initiative | Industry Significance |
|---|---|
| AMI Platform Managed Service Bundling | UK multi-utility frameworks now specify outcome-based contracts spanning installation through analytics, displacing hardware-only tenders. |
| Software-Defined Radio Module Development | Single-hardware platforms addressing multiple regional spectrum allocations reduce redundant firmware development costs for DLMS/COSEM and IEEE 2030.5 protocols. |
| Ultrasonic Measurement Core IP Acquisition | Nordic utilities specify solid-state engines for magnetic tamper immunity, consolidating electromechanical residual share to niche retrofit applications. |
| Edge AI Convergence Investment | On-device anomaly detection enables predictive maintenance without cloud dependency, differentiating next-generation AMI endpoints. |
| REACH and RoHS Compliance Pre-Validation | German TÜV certification backlogs force early alternative alloy and flame retardant validation to maintain CE marking continuity. |
Methodological Framework
Document review covered regulatory filings from FERC and state public utility commissions, EU Green Deal implementation directives, and GB standards certification databases, complemented by interviews with utility planning officers, AMI procurement managers at distribution network operators, RF module engineering leads, and smart city implementation directors. Secondary validation drew from EIA deployment statistics, IEA grid modernization reports, SEC filings from listed meter manufacturers, and customs data on semiconductor component trade flows. Bottom-up unit installation forecasts triangulated against top-down utility capital expenditure projections.
Segmented outputs across meter type, communication technology, end-user scale, and installation context informed the analytical framework over the projection horizon. CAGRs were derived from regression analysis against historical replacement cycle data and regulatory mandate timelines. Industry-specific forecast inputs included State Grid Corporation provincial deployment schedules and EU F-Gas Regulation compliance cost assumptions for sealed housing specifications.
Caveats apply where semiconductor supply disruptions, cybersecurity certification timeline extensions, or protocol fragmentation forcing redundant development could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Industrial Power Monitoring System Market
Smart Meters
Power Monitoring System Market
Smart Meters
Digital Gas Meter Market
Smart Meters
LNG Metering Skids Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
Middle East and Africa Smart Meters Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
Power Quality Meter Market
Smart Meters
Asia-Pacific Smart Meter Data Management Market
Smart Meters
Solar Meter Market
Smart Meters
Digital Water Meters Market
Smart Meters
Water Meter Market
Smart Meters
Home Energy Monitor Market
Smart Meters
US Water Meter Market
Smart Meters
Advanced Metering Infrastructure Market