
 North America Smart Meter Data Management Market | 2026-2036
North America Smart Meter Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Meter Data Management Market Analytics
Subscription-based SaaS delivery is expanding as the dominant commercial model for meter data platforms across North American utilities. Oracle Corporation leverages its cloud infrastructure to anchor enterprise-scale deployments with integrated analytics stacks. Itron, Inc. competes through specialized AMI software modules that sustain long-term service contracts with cooperative utilities. Trilliant Holdings, Inc. differentiates via communications-layer integration that positions its data management suite for hybrid grid environments.
Smart meter data management encompasses the software systems that collect, validate, store, and analyze interval consumption data from advanced metering infrastructure, typically processing 15-minute to hourly reads through scalable time-series databases and API-driven analytics engines. Electric meter and AMI technology segments dominate current revenue as utilities replace first-generation smart meter fleets with second-wave systems supporting bidirectional power flows and distributed energy resource coordination. Cloud-based and SaaS deployment categories are expanding fastest, shifting margin pools from perpetual licenses toward recurring platform fees and managed services.
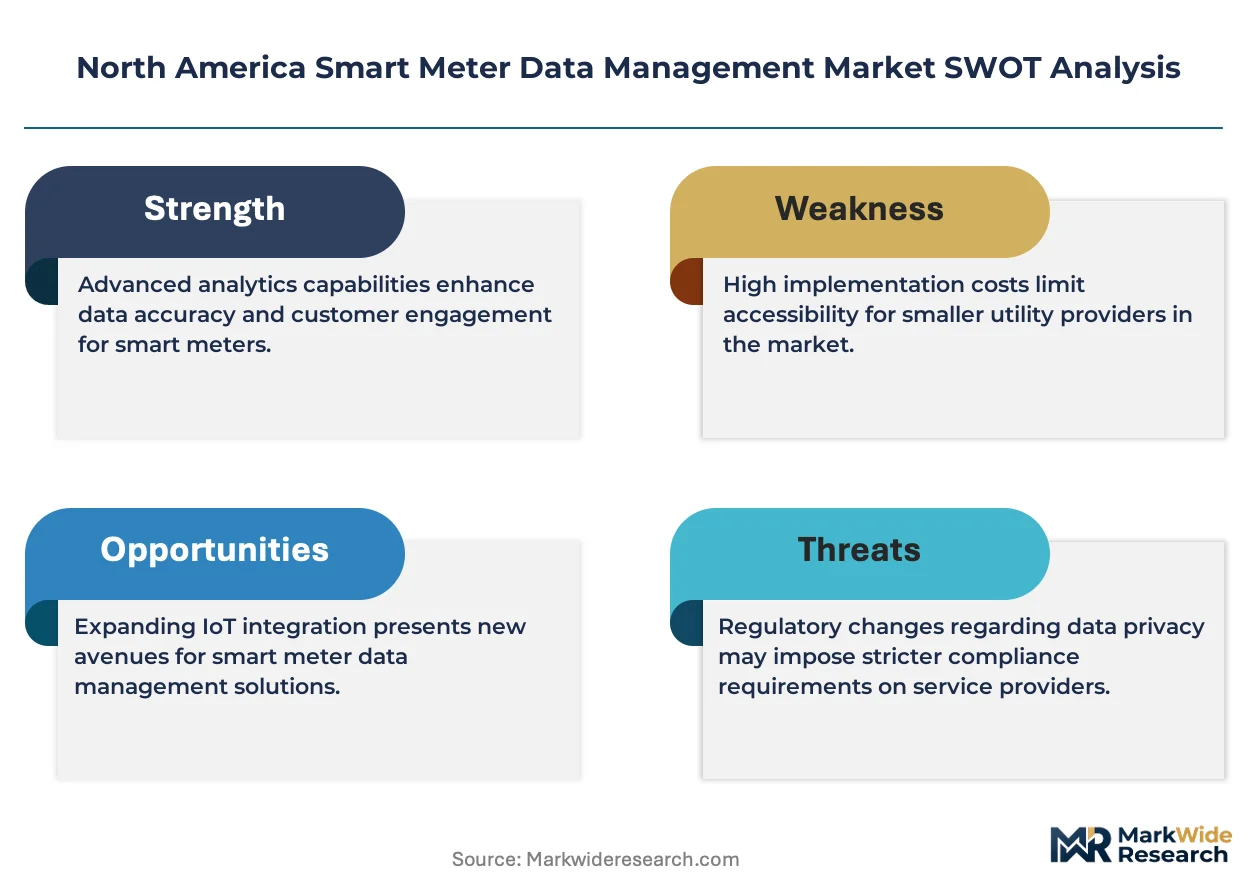
FERC Order 2222 and state-level public utility commission mandates in California and Texas are accelerating demand for interoperable data platforms that enable aggregated distributed energy resource participation. NIST cybersecurity frameworks and IEEE 2030.5 protocol standards shape product certification requirements and market access conditions for platform vendors. Stakeholders must monitor evolving state-level data privacy regulations and utility procurement shifts toward outcome-based service contracts that tie vendor compensation to grid efficiency metrics.
Market Dynamics
Cloud-based SaaS delivery models are compressing procurement cycles across municipal utilities and cooperative networks, shifting vendor compensation structures from perpetual licenses toward recurring platform fees tied to grid performance outcomes.
Growth Catalysts
- FERC Order 2222:This federal mandate requires grid operators to accommodate aggregated distributed energy resource participation, forcing utilities to deploy interoperable data platforms that can process bidirectional power flow telemetry from rooftop solar and battery storage systems.
- AMI 2.0 replacement cycles:First-generation smart meter fleets deployed in the late 2000s are reaching end-of-life across Texas and California, creating replacement demand for second-wave systems with enhanced cybersecurity and edge computing capabilities.
- California SB 100 mandates:The state's 100% clean electricity target by 2045 is accelerating investments in grid-edge intelligence platforms that coordinate demand response with intermittent renewable generation.
Market Restraints
- Semiconductor supply concentration:AMI hardware relies on specialized system-on-chip components fabricated primarily in East Asian foundries, exposing deployment timelines to geopolitical trade friction and capacity constraints.
- Utility capex approval cycles:Rate-base treatment for software investments remains contested in multiple state jurisdictions, stretching procurement timelines from initial budget requests to contract signature.
- Cybersecurity certification complexity:NIST framework compliance and state-level data privacy regulations impose multi-stage validation protocols that delay platform rollouts by 12-18 months.
Strategic Opportunities
- Cooperative utility penetration:Rural electric cooperatives serving the Great Plains and Mountain West remain underpenetrated by enterprise-grade MDM platforms, presenting white-space demand for modular SaaS solutions.
- EV load forecasting integration:Convergence of AMI data streams with electric vehicle charging telemetry creates new revenue pools for predictive analytics services targeting distribution network planning.
- Texas ERCOT market design:The state's energy-only wholesale market structure incentivizes real-time demand flexibility, creating regulatory tailwinds for advanced meter data platforms that enable sub-hourly price response.
Industry Challenges
- Cybersecurity talent scarcity:Utilities face acute shortages of professionals certified in IEC 62351 standards for power system communications security, constraining platform deployment velocity.
- Legacy SCADA integration:Decades-old control systems in Midwest municipal utilities require costly middleware development to achieve API compatibility with modern time-series databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Meter Data Management Market |
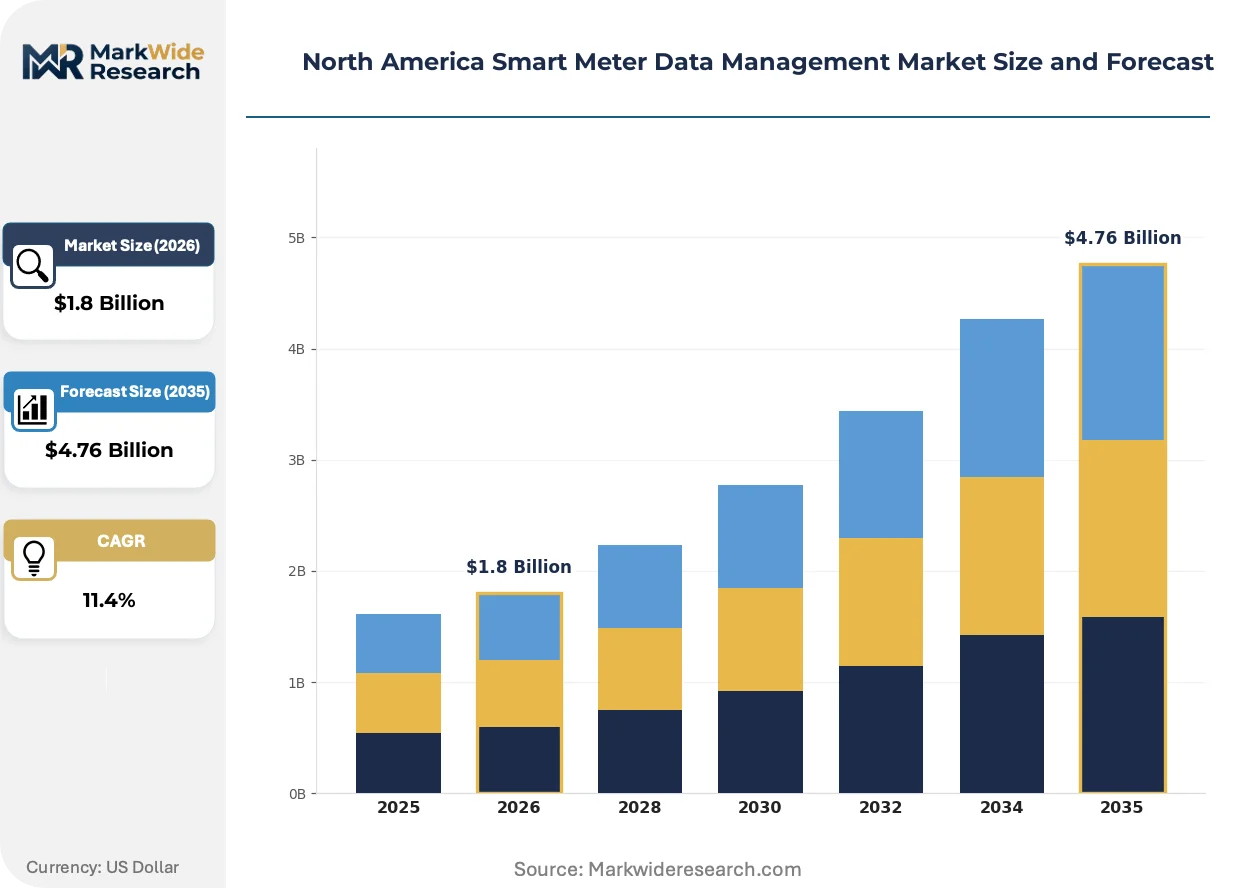
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Meters, Gas Meters, Water Meters, Multi-Utility Meters Technology: AMR, AMI, IoT Solutions, Cloud Computing Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Utilities, Residential Customers, Commercial Users, Industrial Clients |
| Companies Covered | Oracle Corporation, Trilliant Holdings, Inc., Itron, Inc., Arad Group, Siemens AG, ABB Group, Honeywell International, Inc., Eaton Corporation PLC, Hubbell Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Meter Data Management Market Evolving Landscape
Edge computing architectures are redistributing data processing workloads from centralized cloud instances toward field-deployed gateways, reducing latency for real-time grid control applications while complicating vendor platform standardization.
Time-series databases optimized for 15-minute interval reads are expanding into predictive maintenance applications for distribution transformers. Municipal utilities in Ontario and California are piloting these analytics engines to forecast equipment failures before outage events occur. The technology is compressing traditional asset management cycles and enabling condition-based replacement schedules.
FERC Order 2222 implementation deadlines are forcing regional transmission organizations to revise interconnection standards for behind-the-meter resources. PJM and ERCOT are developing new data exchange protocols that require MDM platforms to support sub-second telemetry streams. AMI vendors serving these markets are accelerating IEEE 2030.5 certification timelines to maintain eligibility.
Outcome-based service contracts are displacing traditional software licensing across large investor-owned utilities. Pacific Gas and Electric and Duke Energy have shifted procurement criteria toward vendor compensation tied to measurable grid efficiency improvements. This behavioral shift is most visible in California and Texas, where regulatory pressure on rate-case outcomes intensifies scrutiny of technology vendor performance guarantees.
North America Smart Meter Data Management Market Segmentation
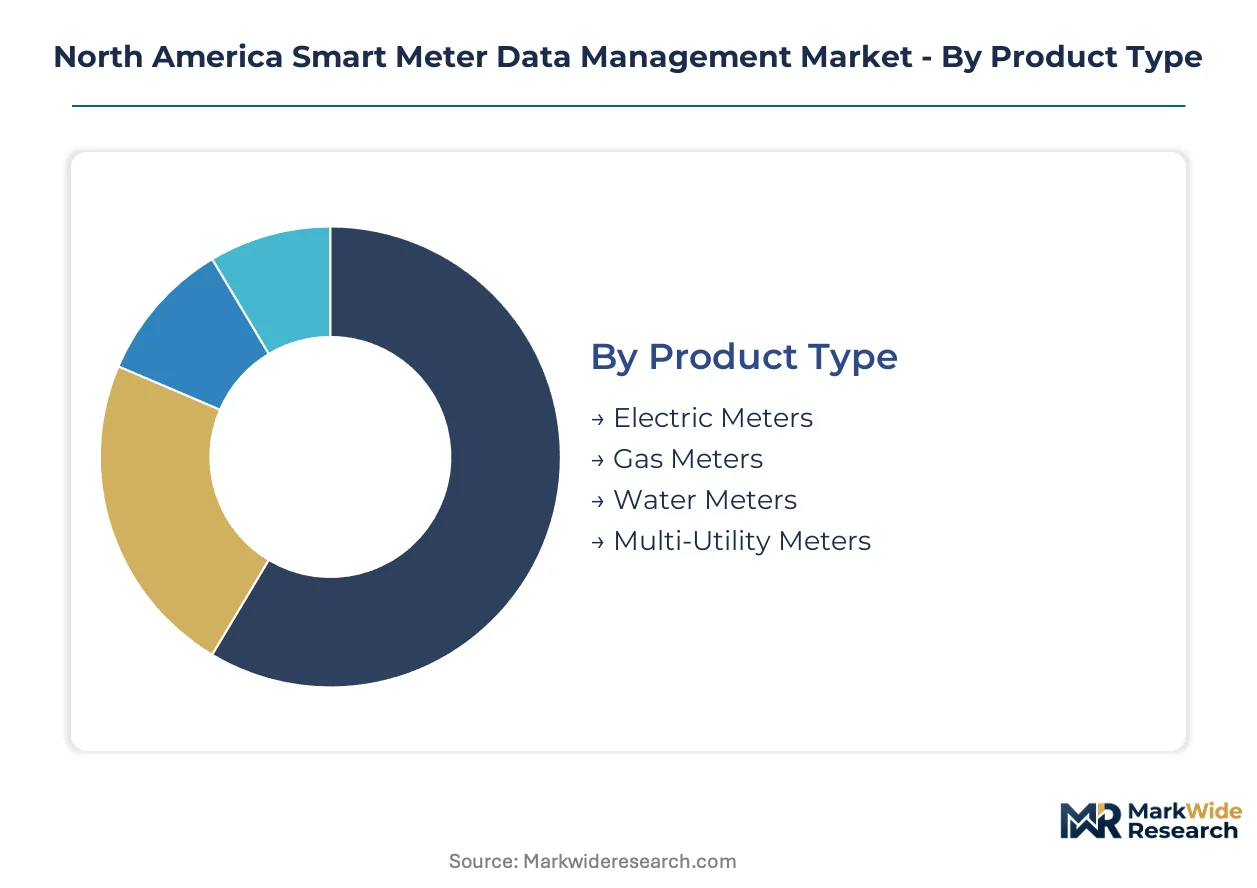
Smart meter data management platforms serve heterogeneous infrastructure environments across North America, from aging first-generation AMR deployments in rural cooperatives to cloud-native AMI rollouts in California investor-owned utilities. Segmentation reveals how vendor pricing, deployment architecture, and customer procurement authority fragment the competitive landscape. Understanding these dimensions clarifies why SaaS delivery models concentrate in municipal utilities while hybrid architectures persist among large IOUs.
Product Type:
Second-wave replacement cycles dominate procurement timelines across all meter categories, with utilities prioritizing bidirectional communication capabilities and edge computing readiness in new deployments.
- Electric Meters:Interval data collection systems process 15-minute to hourly consumption telemetry through time-series databases. Demand concentrates in Texas and California IOUs replacing late-2000s AMI 1.0 fleets with cybersecurity-hardened second-generation units capable of distributed energy resource coordination under FERC Order 2222.
- Gas Meters:Ultrasonic and diaphragm meter variants equipped with RF modules transmit hourly pressure-corrected volume data. Deployment velocity lags electric counterparts across Ontario municipal utilities due to lower regulatory pressure for real-time telemetry and compressed natural gas infrastructure priorities.
- Water Meters:Electromagnetic and ultrasonic flow sensors with integrated leak detection algorithms serve drought-stressed California water districts. Sacramento and Los Angeles Department of Water and Power pilot programs validate AMI integration for conservation pricing.
- Multi-Utility Meters:Single-device platforms consolidating electric, gas, and water measurement through unified communications modules. Rural electric cooperatives in the Mountain West evaluate these units to reduce truck-roll costs across sparse service territories.
Volume placements concentrate in Electric Meters; the faster expansion belongs to Multi-Utility Meters.
Technology:
Communications protocol selection determines platform interoperability with existing utility SCADA investments and future grid-edge intelligence requirements.
- AMR:Drive-by and fixed-network automated meter reading systems using one-way RF telemetry remain entrenched in budget-constrained municipal utilities. Midwest cities with 1990s-era infrastructure defer full AMI migration due to rate-case approval delays.
- AMI:Two-way advanced metering infrastructure with home area network connectivity and remote disconnect capability anchors Texas ERCOT market designs requiring sub-hourly price response. California SB 100 compliance timelines accelerate procurement of IEEE 2030.5-certified platforms.
- IoT Solutions:Low-power wide-area network protocols extending meter connectivity to distribution transformers and voltage regulators. Ontario Hydro One pilots LoRaWAN overlays to bridge rural coverage gaps without cellular subscription costs.
- Cloud Computing:Elastic compute resources for time-series analytics and machine learning model training. Cooperative utilities lacking internal IT capacity adopt these platforms fastest.
Legacy AMR still dominates installed base; AMI claims the steepest expansion trajectory among active deployments.
Deployment:
Capital recovery mechanisms and cybersecurity risk appetite shape whether utilities retain infrastructure control or outsource platform operations.
- On-Premises:Utility-owned data centers with air-gapped networks satisfying NIST framework requirements for critical infrastructure protection. Large IOUs in Texas maintain these architectures for operational technology isolation.
- Cloud-Based:Hyperscaler-hosted instances with SOC 2 Type II certification and encrypted data residency guarantees. Municipal utilities in California accelerate migration to reduce datacenter capital expenditures from rate base.
- Hybrid:Edge gateways processing real-time control signals locally with batched analytics upload to cloud repositories. ERCOT's four-second dispatch intervals necessitate this architecture for demand response aggregation.
- SaaS:Subscription meter data management with vendor-managed updates and cybersecurity patching. Cooperative networks across the Great Plains favor this model to access enterprise-grade capabilities without dedicated IT staff.
Hybrid configurations lead among large IOUs; SaaS delivery is gaining share fastest in the cooperative segment.
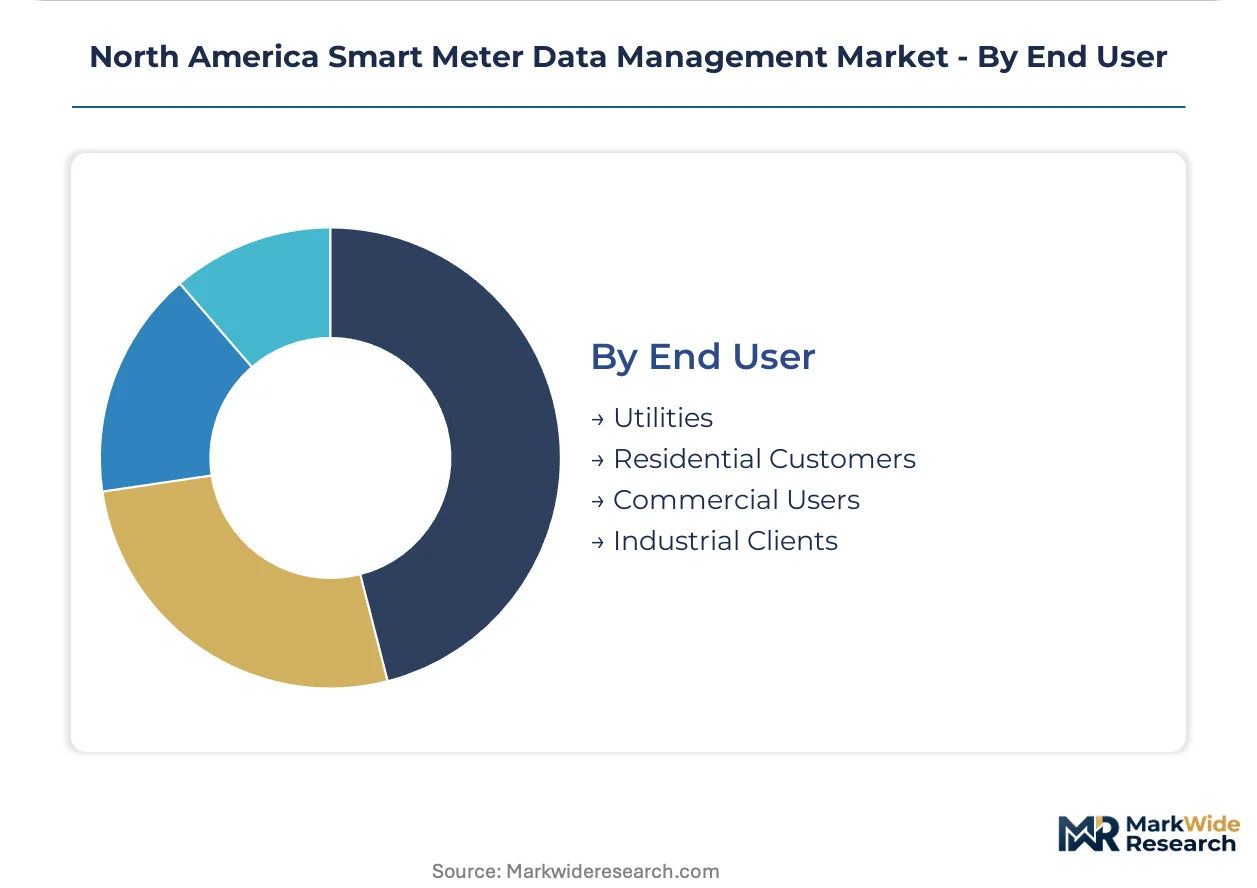
End User:
Procurement authority and rate-base treatment differentiate how each customer category evaluates platform investments.
- Utilities:Regulated entities with rate-case approval requirements for technology capital expenditures. California and Texas public utility commissions scrutinize software cost recovery with intensified outcome-based performance standards.
- Residential Customers:Behind-the-meter solar and battery storage owners requiring interval data access for FERC Order 2222 participation. Third-party aggregators in Texas recruit these resources into wholesale demand response programs.
- Commercial Users:Multi-site enterprises with interval metering for peak demand charge management. California's time-of-use rate structures create subscription demand for analytics platforms forecasting optimal load shifting.
- Industrial Clients:Heavy manufacturing facilities with power quality monitoring and sub-metering for process optimization. Petrochemical complexes along the Texas Gulf Coast deploy these systems for interruptible rate qualification.
Utility procurement commands the largest contract values; Industrial Clients are expanding most quickly as manufacturing reshoring intensifies energy management priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform deployment concentrates in the United States while Canadian utilities adopt at measured rates. Mexico's nascent smart grid investments lag substantially behind its northern neighbors. Sub-regional variation within each country reflects divergent regulatory pressure and utility ownership structures.
United States
Texas and California utilities drive replacement cycles for first-generation AMI fleets. FERC Order 2222 mandates aggregated distributed energy resource participation, compelling grid operators to upgrade data platforms. ERCOT's real-time market design in Austin and Dallas-Fort Worth accelerates sub-hourly telemetry deployments for demand response aggregation.
California
SB 100 clean electricity targets force investor-owned utilities toward grid-edge intelligence investments. The California Public Utilities Commission scrutinizes rate-case software cost recovery with outcome-based performance standards. San Diego Gas & Electric and Pacific Gas & Electric pilot predictive maintenance analytics for distribution transformers in coastal load centers.
Texas
Energy-only wholesale market structures incentivize demand flexibility platforms across municipal and cooperative utilities. The Public Utility Commission of Texas oversees interconnection standards revision for behind-the-meter resources. Houston and Dallas metropolitan utilities deploy hybrid cloud-edge architectures to meet four-second dispatch intervals.
Ontario
Hydro One pilots low-power wide-area network overlays to bridge rural coverage gaps without cellular subscription costs. The Ontario Energy Board regulates smart meter cost recovery through rate-base mechanisms. Toronto and Ottawa municipal utilities accelerate cloud migration to reduce datacenter capital expenditures.
Mexico
Federal electricity commission restructuring creates procurement uncertainty for advanced metering investments. The national energy regulator develops interconnection standards for distributed generation participation. Monterrey and Mexico City industrial zones show preliminary demand for multi-utility meter consolidation.
North America Smart Meter Data Management Market Competitive Landscape
Top-tier vendors anchor enterprise-scale deployments, while specialized communications-layer providers compete for cooperative utility segments. The market structures around three distinct tiers: cloud infrastructure giants with integrated analytics stacks, dedicated AMI software specialists, and industrial conglomerates with power systems divisions. Strategic differentiation concentrates on SaaS delivery models and cybersecurity certification timelines. Competitive moves emphasize outcome-based service contracts and IEEE 2030.5 protocol compliance acceleration.
Within the cloud-platform tier, Oracle Corporation represents the integrated infrastructure archetype, leveraging hyperscaler resources for enterprise utility deployments. Itron, Inc. and Trilliant Holdings, Inc. exemplify specialized AMI software and communications-layer positioning respectively, each occupying distinct competitive territory in vendor-managed service delivery. These three anchors illustrate how commercial model selection—perpetual license versus recurring platform fee—separates strategic positioning across municipal, cooperative, and investor-owned utility segments.
| Leading Market Players |
|---|
| Oracle Corporation |
| Trilliant Holdings, Inc. |
| Itron, Inc. |
| Arad Group |
| Siemens AG |
| ABB Group |
| Honeywell International, Inc. |
| Eaton Corporation PLC |
| Hubbell Incorporated |
| Others |
Value Network & Pricing Analysis
California SB 100 clean electricity mandates gate qualified supply for premium-tier AMI platforms, restricting vendor eligibility to IEEE 2030.5-certified providers while amplifying price premiums for compliant cybersecurity-hardened systems. This regulatory filter concentrates procurement authority among utilities with rate-base approval for outcome-based service contracts, compressing margins for non-certified entrants.
Pricing Analysis
Margin tightening in SaaS delivery reflects the shift from perpetual licenses toward subscription models tied to grid performance outcomes. Three-tier pricing structure across premium, standard, and economy levels separates Oracle's enterprise analytics stacks from Itron's modular cooperative solutions and Trilliant's communications-layer bundles. Price differentiation hinges on NIST framework certification grade and after-sales cybersecurity patching scope. Cooperative utilities in the Great Plains exhibit highest price sensitivity due to constrained IT budgets; Texas IOUs demonstrate lowest sensitivity given ERCOT's real-time market incentives for sub-hourly telemetry.
Supply Chain Analysis
Domestic-content mandates in Ontario and Buy American provisions for federally funded grid projects reshape sourcing toward North American final assembly. AMI hardware draws from Taiwan and South Korea for system-on-chip components, with Mexico emerging as a regional integration hub. Specialized RF modules and time-series database licenses rest on concentrated East Asian foundry capacity. Single-source vulnerability in semiconductor fabrication exposes deployment timelines to geopolitical trade friction. Distribution runs through utility procurement departments with 12-18 month rate-case approval cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native SaaS architectures are displacing on-premises MDM installations across municipal utilities, with edge computing gateways replacing centralized data centers for real-time grid control applications.
For Market Incumbents: Lock in long-term service contracts with Texas and California IOUs before AMI 2.0 replacement cycles peak. Deepen backward integration into edge computing hardware to defend against communications-layer specialists. Accelerate IEEE 2030.5 certification timelines to maintain eligibility under FERC Order 2222 implementation deadlines.
For New Entrants and Emerging Players: Direct-to-utility SaaS platforms offer the fastest penetration route for undercapitalized vendors. Target rural electric cooperatives in the Mountain West with modular subscription offerings requiring minimal IT staff. Emphasize LoRaWAN integration for Ontario Hydro One's rural coverage gap pilots.
For Investors and Strategic Acquirers: ERCOT's four-second dispatch interval adoption is the leading indicator that real-time demand response platforms will command acquisition premiums. Focus on mid-cap AMI software specialists with FERC-compliant cybersecurity stacks. Watch for state-level data privacy regulation divergence as the signal for platform consolidation necessity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Converges AMI data streams with EV charging telemetry for predictive distribution planning. |
| Geographic Expansion | Extends modular SaaS offerings into underpenetrated Great Plains cooperative territories. |
| Strategic Partnership | Aligns communications-layer vendors with hyperscaler cloud infrastructure for hybrid deployments. |
| Acquisition of Specialist Firm | Consolidates IEEE 2030.5 certification expertise ahead of FERC Order 2222 deadlines. |
| Product Launch | Introduces multi-utility meters consolidating electric, gas, and water measurement for rural networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with utility planning officers, AMI platform engineers, cooperative procurement managers, and cybersecurity compliance leads combined with FERC dockets, state public utility commission rate-case filings, and EIA smart grid deployment databases. Bottom-up utility procurement tracking and top-down market sizing triangulated volume estimates.
Granularity-level modeling segmented deployments by meter type, communications protocol, and delivery architecture across the projection horizon. CAGRs derived from utility capital expenditure trajectories and replacement cycle timing. Forecast inputs incorporated FERC Order 2222 implementation schedules and state renewable integration mandates without year-specific anchoring.
The model holds under stable regulatory enforcement of NIST cybersecurity frameworks; deviation in state-level data privacy legislation or semiconductor trade restrictions would shift vendor eligibility and deployment velocity assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Home Energy Monitor Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Digital Water Meters Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
US Water Meter Market
Smart Meters
Global Smart Electricity Meter Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Digital Gas Meter Market
Smart Meters
LNG Metering Skids Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Solar Meter Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Europe Smart Meters Market