
 Smart Metering Systems Market | 2026-2036
Smart Metering Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Metering Systems Market Insights
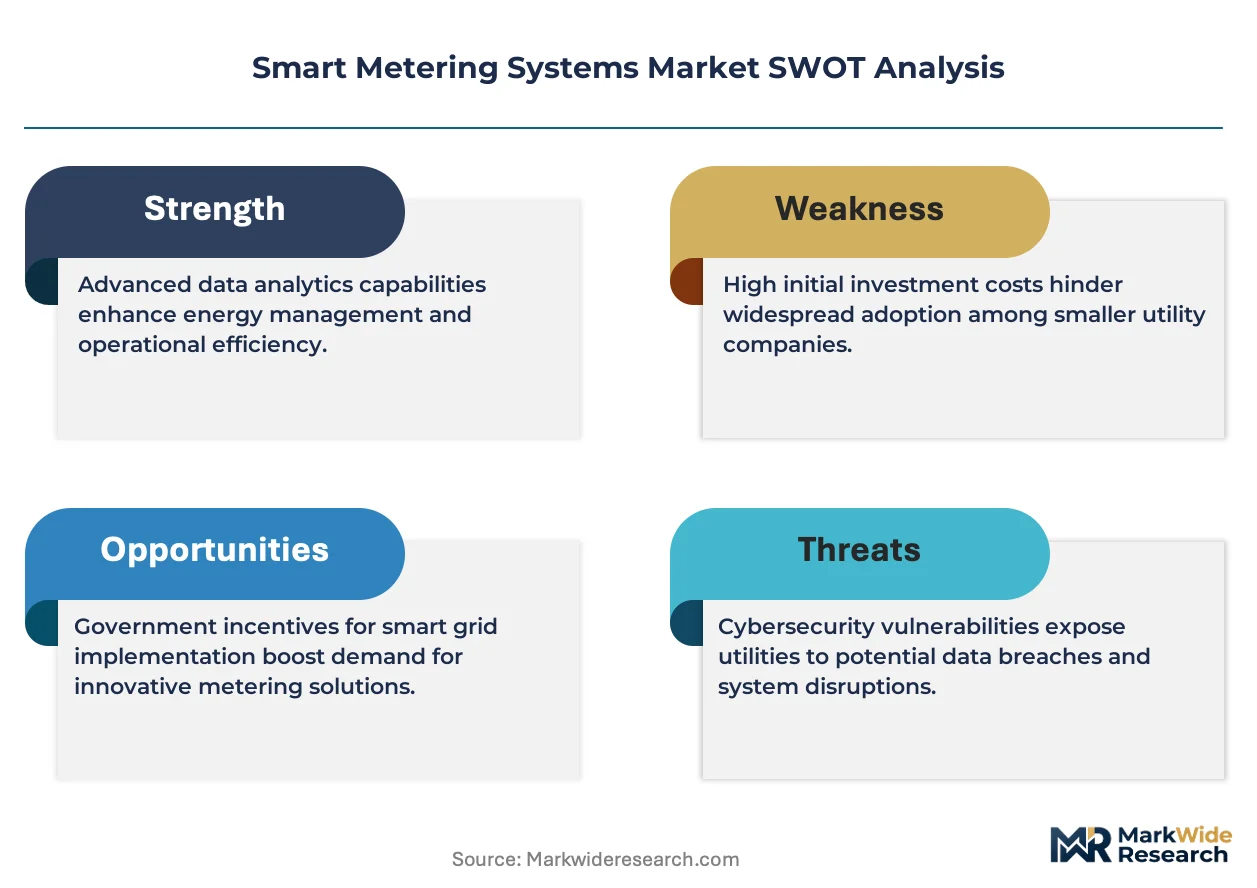
The EU F-Gas Regulation is restructuring compliance costs for gas meter manufacturers serving European utilities. Itron Inc. leverages its AMI software stack to sustain recurring revenue from North American electric cooperatives. Landis+Gyr AG anchors its position through deep utility relationships across European distribution system operators. Honeywell International Inc. differentiates via integrated building-to-grid platforms that bridge residential and commercial metering.
Smart metering systems comprise networked measurement devices that capture consumption data at intervals as fine as fifteen minutes and transmit readings through RF mesh, cellular, or power-line carrier protocols to central management platforms. Their primary purpose is to enable demand-response programs, reduce non-technical losses, and support time-of-use tariff structures for grid operators. Electric meters dominate installed value due to capital-intensive grid modernization programs, while IoT-based connectivity is displacing legacy AMR as utilities prioritize real-time outage detection and distributed energy resource coordination. Cloud-based deployment architectures capture expanding margin pools as utilities outsource meter data management to specialized platform providers.
The US Federal Energy Regulatory Commission shapes wholesale market participation rules that determine whether advanced metering infrastructure qualifies for demand-response compensation, while the EPA's greenhouse gas reporting protocols indirectly drive sub-hourly data granularity requirements. European regulators enforce CE marking and MID certification for billing-grade accuracy, creating asymmetric compliance burdens between domestic and import suppliers. India's Bureau of Indian Standards mandates local testing facilities that extend product qualification timelines for foreign meter vendors. Stakeholders must weigh certification jurisdiction against manufacturing location as tariff and technical barrier configurations shift.
Market Dynamics
The EU F-Gas Regulation is forcing gas meter manufacturers to redesign product architectures around low-global-warming-potential alternatives, compressing certification timelines and fragmenting supplier tiers between compliant and non-compliant component sources.
Growth Catalysts
- AMI Software Stack Convergence:North American electric cooperatives are consolidating vendor relationships around unified meter-to-cash platforms that bundle RF mesh connectivity with cloud-based data analytics.
- Messstellenbetriebsgesetz Enforcement:Germany's national energy regulator mandates smart meter gateway certification for all new installations, creating locked-in demand cycles for certified device manufacturers.
- Grid-Edge Intelligence:Real-time consumption analytics enable distribution system operators to coordinate distributed energy resources at the substation level.
Market Restraints
- Semiconductor Supply Concentration:RF transceiver and power management IC sourcing remains concentrated among Taiwanese foundries, exposing meter OEMs to allocation volatility.
- CE Marking Asymmetry:European MID certification requires domestic testing facility access, extending product qualification timelines for import suppliers versus domestic peers.
- Power-Line Carrier Obsolescence:Legacy PLC protocols face bandwidth limitations that prevent sub-15-minute interval metering, constraining upgrade paths for deployed AMR estates.
Strategic Opportunities
- Building-to-Grid Integration:Residential-commercial metering convergence creates white space for platforms that unify HVAC load control with tariff optimization.
- India BIS Localization:Bureau of Indian Standards mandates for domestic testing facilities favor joint-venture structures over direct import for foreign meter vendors.
- Cellular LPWAN Expansion:NB-IoT and LTE-M module cost compression enables greenfield deployments in rural cooperatives previously uneconomical for mesh architectures.
Industry Challenges
- Cybersecurity Certification Bottlenecks:IEC 62351 compliance for meter-to-headend encryption adds 6-12 months to product release cycles.
- Legacy System Integration Friction:Utilities with 20-year-old CIS platforms face data schema mismatches when ingesting sub-hourly interval reads from advanced metering infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Metering Systems Market |
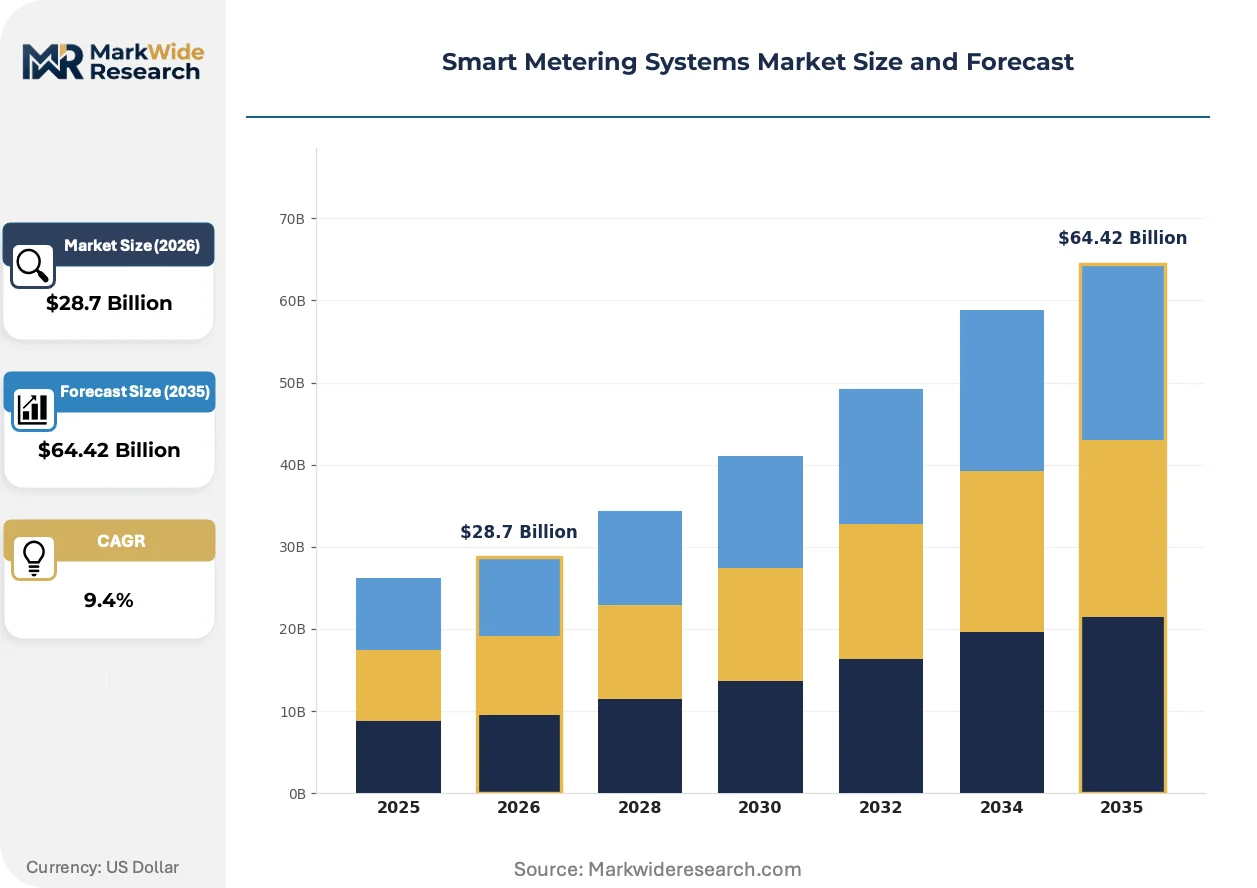
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $64.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Meters, Water Meters, Gas Meters, Multi-Utility Meters Technology: AMR, AMI, IoT-Based, Analog End User: Utilities, Residential, Commercial, Industrial Deployment: On-Premises, Cloud-Based, Hybrid, Remote |
| Companies Covered | Itron Inc., Landis+Gyr AG, Honeywell International Inc., ABB Ltd., General Electric, Siemens AG, Aclara Technologies LLC, Sensus (Xylem Inc.), Kamstrup A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Metering Systems Market Trends and Innovations
Smart metering architectures are fragmenting into specialized layers as utilities decouple hardware procurement from software platform selection, enabling vendor substitution at the connectivity or analytics tier without full-system replacement.
Edge computing hardware is modularizing meter functionality into discrete, upgradeable sub-assemblies. European distribution system operators are piloting swappable communication modules that separate metrology from connectivity, allowing RF mesh to coexist with cellular backup on identical meter bases. This architecture is modularizing vendor lock-in, compressing replacement cycles from 15-year full-unit swaps to 3-year module upgrades.
The EU F-Gas Regulation is restructuring compliance costs for gas meter manufacturers serving European utilities. Equipment suppliers must now certify alternative sealing technologies and refrigerant-free pressure sensors under accelerated timelines. Gas meter OEMs with pre-certified low-GWP component supply chains are capturing displaced demand from legacy suppliers facing redesign delays.
Buyer procurement patterns are compressing vendor evaluation cycles as utilities shift from capital-purchase models to meter-as-a-service contracts. North American electric cooperatives are unbundling hardware ownership from data management, outsourcing meter data management to specialized platform providers. This shift is most visible in Germany, where Messstellenbetriebsgesetz-compliant gateway operators now bundle device provisioning with regulatory data hosting.
Smart Metering Systems Market Segmentation
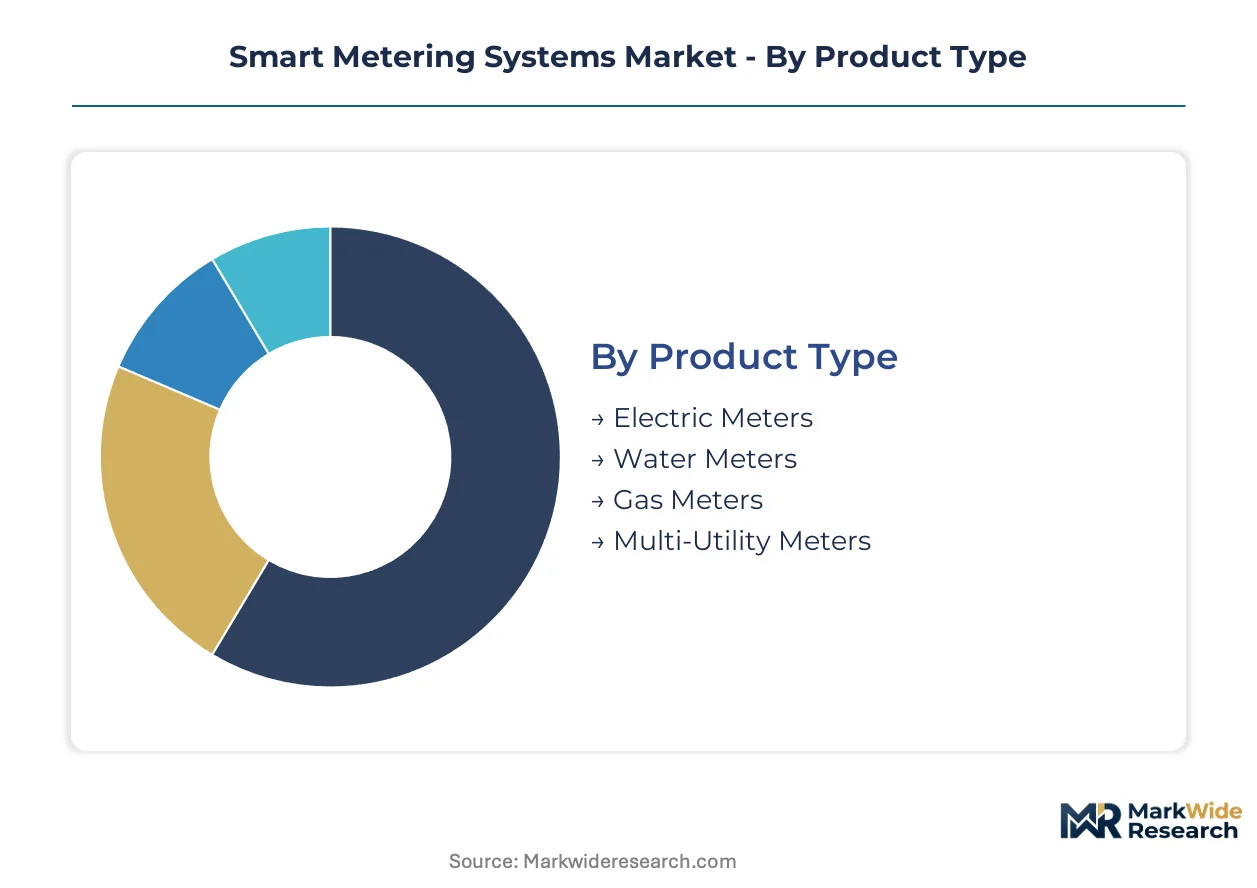
Smart metering procurement decisions fragment across technical specifications, regulatory compliance tiers, and ownership models. Vendors must map capabilities to distinct buyer workflows that separate capital-intensive utility deployments from service-oriented residential offerings.
Product Type:
Capital allocation intensity and grid modernization timelines determine buyer selection across meter categories.
- Electric Meters:These devices measure voltage, current, and power factor at sub-15-minute intervals for billing and load profiling. Demand concentrates in Germany where the Messstellenbetriebsgesetz mandates certified smart meter gateways for all new installations.
- Water Meters:Ultrasonic and electromagnetic flow sensors enable leak detection and pressure management in distribution networks. North American municipalities are accelerating replacement cycles as EPA water loss regulations tighten non-revenue water thresholds.
- Gas Meters:Diaphragm and ultrasonic designs incorporate temperature compensation and low-GWP sealing technologies under EU F-Gas Regulation compliance requirements.
- Multi-Utility Meters:Integrated metrology platforms consolidate electric, water, and thermal measurement within single hardware enclosures for campus and district energy systems.
Electric meters lead on scale; multi-utility meters lead on momentum.
Technology:
Connectivity protocol selection locks buyers into decade-long vendor relationships and determines data granularity capabilities.
- AMR:Automated meter reading systems use one-way communication for monthly billing cycles via drive-by RF or walk-by optical interfaces. European utilities are phasing out AMR estates as MID certification requirements shift toward two-way AMI architectures.
- AMI:Advanced metering infrastructure enables real-time bidirectional communication between meters and headend systems. US electric cooperatives are consolidating procurement around unified meter-to-cash platforms that bundle RF mesh with cloud analytics.
- IoT-Based:Cellular LPWAN modules using NB-IoT and LTE-M protocols bypass proprietary mesh infrastructure. Rural cooperatives previously uneconomical for mesh deployment are adopting cellular as module costs compress.
- Analog:Electromechanical meters with manual read requirements persist in legacy estates and jurisdictions with weak regulatory mandates for smart meter adoption.
AMI dominates current deployment value; IoT-based configurations are climbing the fastest.
End User:
Procurement authority and technical specification complexity vary sharply across customer categories.
- Utilities:Distribution system operators specify billing-grade accuracy, cybersecurity certification, and 15-20 year operational lifecycles. German DSOs enforce gateway certification under national energy regulator standards.
- Residential:Single-family and multi-family dwellings drive volume through utility-managed deployment programs with opt-out provisions in some North American jurisdictions.
- Commercial:Retail, office, and hospitality facilities demand sub-metering for tenant billing and LEED certification compliance.
- Industrial:Manufacturing and process industries require power quality monitoring and harmonics measurement beyond standard consumption metering.
Utilities command specification authority; commercial segments are expanding most quickly.
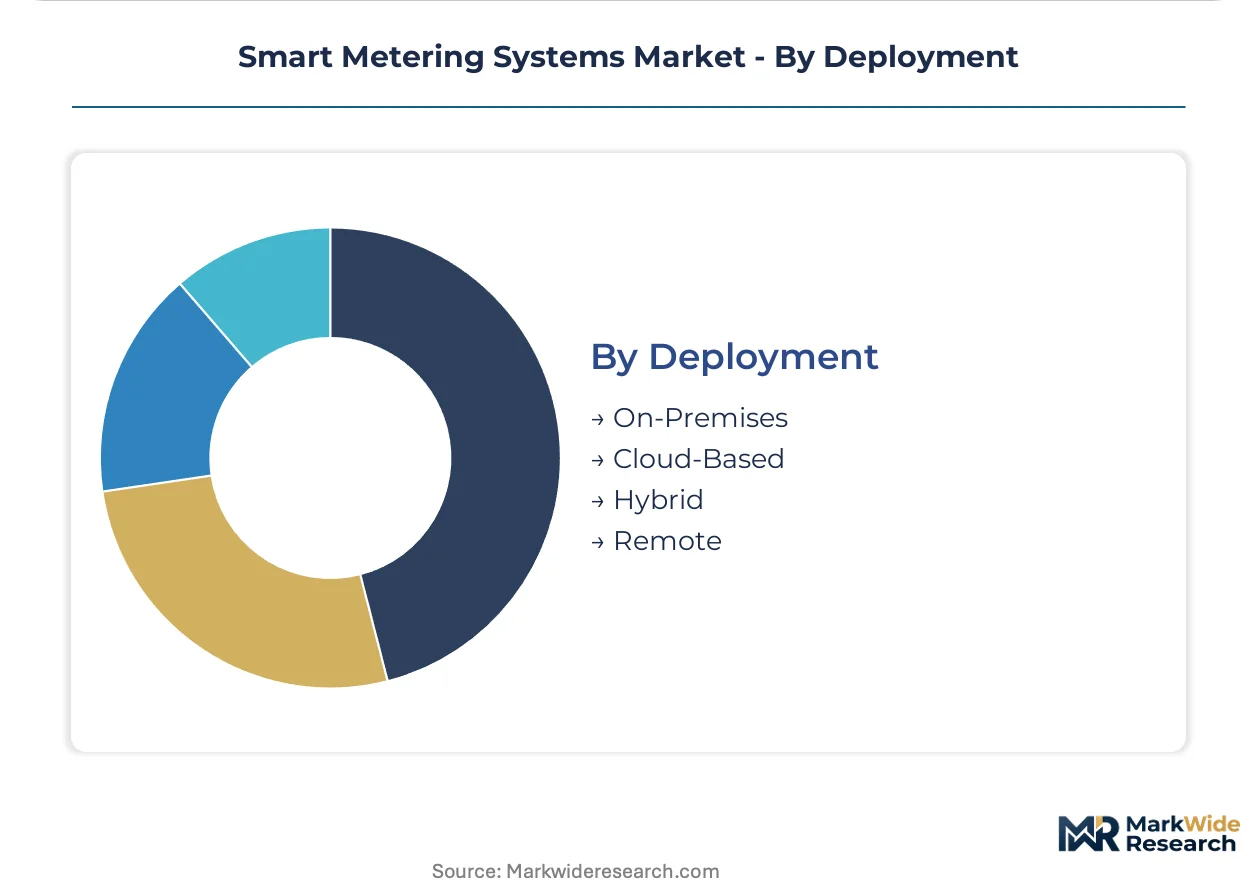
Deployment:
Data sovereignty requirements and legacy system integration constraints shape infrastructure ownership decisions.
- On-Premises:Meter data management systems hosted within utility data centers satisfy strict cybersecurity and data residency requirements. Indian utilities favor on-premises deployment given BIS localization mandates for critical infrastructure.
- Cloud-Based:SaaS platforms outsource data storage and analytics to specialized providers. North American electric cooperatives are unbundling hardware ownership from meter data management services.
- Hybrid:Architectures partition real-time operations on-premises while archiving historical data to cloud environments for regulatory reporting.
- Remote:Fully outsourced meter-as-a-service contracts transfer asset ownership and maintenance liability to vendors.
On-premises retains share in regulated markets; cloud-based models are gaining traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent clusters around Munich and Stuttgart anchor European smart metering deployment velocity. Utility workforce concentration in North Rhine-Westphalia drives gateway certification expertise.
United States
Texas and California utilities accelerate AMI rollouts to integrate rooftop solar and battery storage. FERC Order 2222 enables distributed energy resource aggregation, compensating smart meter-enabled demand response in wholesale markets. Austin Energy pilots sub-15-minute interval metering for grid-edge coordination.
Germany
Messstellenbetriebsgesetz mandates smart meter gateway certification for all new installations, creating locked-in demand cycles. The Federal Network Agency enforces strict interoperability standards under the Act. Engineering clusters in Munich and Karlsruhe dominate gateway manufacturing and testing facility concentration.
India
Maharashtra and Gujarat distribution companies deploy prepaid smart meters to reduce aggregate technical and commercial losses. Bureau of Indian Standards mandates domestic testing facilities, extending qualification timelines for foreign vendors. Bangalore hosts emerging meter data analytics software development centers.
China
State Grid Corporation's massive procurement programs drive electric meter volume. MIIT standards govern narrowband IoT module certification for rural deployments. Shenzhen manufacturing clusters supply RF transceiver components to global meter OEMs.
United Kingdom
The Smart Metering Implementation Programme targets universal rollout by 2025. Ofgem regulates supplier obligations for residential meter installation. Manchester and Glasgow host utility back-office operations for meter data management platform consolidation.
Smart Metering Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and integrated platform tiers. The vendor base stratifies between multinational industrial groups with captive utility relationships and meter-specific manufacturers with deep certification expertise. Three archetypes dominate: integrated building-to-grid platform providers, AMI software stack specialists, and component-focused metrology houses. Competitive moves concentrate on meter-as-a-service contract structures and strategic partnerships for cellular LPWAN module supply.
Among diversified industrial groups, Siemens AG and ABB Ltd. occupy positions spanning electrification infrastructure and utility automation. Itron Inc. exemplifies the AMI software specialist archetype, while Landis+Gyr AG represents the pure-play meter manufacturer with European regulatory depth. Honeywell International Inc. anchors the building-to-grid convergence segment. These three named entities sit within distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Itron Inc. |
| Landis+Gyr AG |
| Honeywell International Inc. |
| ABB Ltd. |
| General Electric |
| Siemens AG |
| Aclara Technologies LLC |
| Sensus (Xylem Inc.) |
| Kamstrup A/S |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between MID-certified billing meters and uncertified sub-metering devices fragments both procurement budgets and supplier sourcing strategies across European and North American utilities. Premium-tier gateway manufacturers in Germany command sustained margin pools through Messstellenbetriebsgesetz-mandated testing protocols, while commodity meter OEMs in China compete on module cost compression for rural cooperative deployments.
Pricing Analysis
The bundled-vs-unbundled service split now dominates smart metering procurement, with meter-as-a-service contracts separating hardware ownership from data management subscriptions. Three-tier pricing structure across certified gateway, standard AMI, and economy cellular tiers reflects cybersecurity certification investment and cloud analytics bundling. Pricing pressure stems from cellular LPWAN module cost compression enabling greenfield rural deployments at sub-mesh economics. Municipal utilities exhibit highest price sensitivity due to constrained capital budgets, while German distribution system operators absorb premium pricing for regulatory compliance certainty.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from State Grid Corporation and major European utilities, while distribution partners serve fragmented cooperative and municipal segments. RF transceiver and power management IC sourcing concentrates in Taiwan, South Korea, and China, with Shenzhen manufacturing clusters feeding global meter assembly. Semiconductor allocation volatility from foundry concentration poses structural supply risk for meter OEMs with limited buffer inventory. Distribution runs through specialized industrial distributors with utility certification expertise rather than broad-line electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart metering margins expand through cellular module cost compression and the shift toward recurring SaaS revenue from meter data management platforms, displacing one-time hardware transactions.
For Market Incumbents: Deepen vertical integration into cellular LPWAN module supply through strategic partnerships with Taiwanese foundries, insulating against allocation volatility that threatens fulfillment commitments to North American cooperatives. Expand in-house certification capabilities for IEC 62351 cybersecurity standards, compressing 6-12 month compliance timelines that currently delay product releases against nimbler competitors. For New Entrants and Emerging Players: Launch via white-label gateway manufacturing for German Messstellenbetriebsgesetz compliance, exploiting locked-in demand cycles where certified device shortages persist. Target rural electric cooperatives in the United States with cellular-first architectures bypassing proprietary mesh infrastructure investments, positioning against incumbent RF mesh specialists through deployment speed and lower total cost of ownership. For Investors and Strategic Acquirers: Consolidation pressure builds where AMI software stack convergence favors unified meter-to-cash platforms over point-solution vendors with narrow connectivity or analytics scope. Meter data management SaaS providers with recurring revenue concentration and utility-scale customer retention represent priority acquisition archetypes. Watch cellular LPWAN module cost curves as inflection indicator for rural cooperative addressability expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Meter-as-a-Service Contract Expansion | Unbundles hardware ownership from data management, capturing recurring revenue pools from North American cooperatives. |
| Cellular LPWAN Module Integration | NB-IoT and LTE-M cost compression enables rural deployments previously uneconomical for mesh architectures. |
| Cybersecurity Certification Investment | IEC 62351 compliance accelerates product release cycles and differentiates against uncertified competitors in European tenders. |
| Gateway Manufacturing Localization | India BIS mandates and German testing facility proximity reduce qualification timelines and tariff exposure. |
| Building-to-Grid Platform Convergence | HVAC load control integration with tariff optimization captures commercial segment expansion beyond pure consumption metering. |
Research Methodology
Direct dialogue with utility planning officers, AMI procurement leads at electric cooperatives, meter data management platform engineers, and regulatory affairs specialists at European distribution system operators grounded qualitative findings. Secondary validation drew from FERC filings, EIA smart grid deployment databases, Bundesnetzagentur certification registries, and Bureau of Indian Standards technical notifications. Bottom-up unit economics triangulated against top-down utility capital expenditure projections across the analysis window.
Segment-level outputs across electric, water, gas, and multi-utility meter categories, AMR-to-AMI-to-IoT technology migration curves, and on-premises versus cloud deployment splits informed the analytical framework. CAGRs derived from utility rollout timelines, regulatory mandate enforcement schedules, and module cost compression trajectories. Forecast inputs incorporated Messstellenbetriebsgesetz installation mandates, FERC Order 2222 demand-response compensation rules, and cellular LPWAN rural addressability expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor allocation disruptions, cybersecurity certification timeline extensions, or shifts in utility capital-purchase versus service-contract procurement preferences. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Smart Gas Metering Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
Water Meter Market
Smart Meters
Smart Meters Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Europe Smart Meters Market
Smart Meters
Global Smart Energy Meters Market
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Smart Gas Meter Market
Smart Meters
Europe Smart Meter Data Management Market
Smart Meters
Digital Gas Meter Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
Power Metering Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Residential Smart Water Metering Market