
 Middle East and Africa Smart Meters Market | 2026-2036
Middle East and Africa Smart Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Smart Meters Market Foresight
Utility procurement across the Middle East and Africa is consolidating around national power authorities and sovereign water utilities, reducing vendor fragmentation and raising contract values. Landis+Gyr Group AG anchors large-scale deployments through its manufacturing presence in regional hubs. Itron Inc. competes on advanced analytics platforms that integrate with existing SCADA systems. Schneider Electric SE differentiates through end-to-end grid automation portfolios that bundle metering with distribution management software.
Smart meters in this context denote digitally enabled measurement devices that record consumption of electric energy, water, or gas at intervals of one hour or less and communicate that data via RF, power-line carrier, or cellular networks to utilities for monitoring and billing. These devices typically incorporate solid-state measurement engines, non-volatile memory for interval data storage, and sealed enclosures rated for outdoor installation across desert and tropical climates. Smart electric meters lead product type adoption where utilities pursue loss reduction and demand response programs, while smart water meters represent the fastest-growing category amid scarcity-driven conservation mandates across the Gulf. PLC technology dominates communication architecture in dense urban deployments, though Zigbee gains traction in residential smart home integrations.
Saudi Arabia's Communications and Information Technology Commission sets device certification protocols for RF-enabled meters, while South Africa's National Energy Regulator mandates time-of-use billing infrastructure that drives smart meter specifications. The UAE's Emirates Authority for Standardization and Metrology enforces interoperability standards that shape procurement requirements across Gulf markets. Stakeholders must monitor how national data localization requirements evolve, as meter-generated consumption data increasingly falls under emerging privacy frameworks that could reshape cloud architecture decisions and vendor selection criteria.
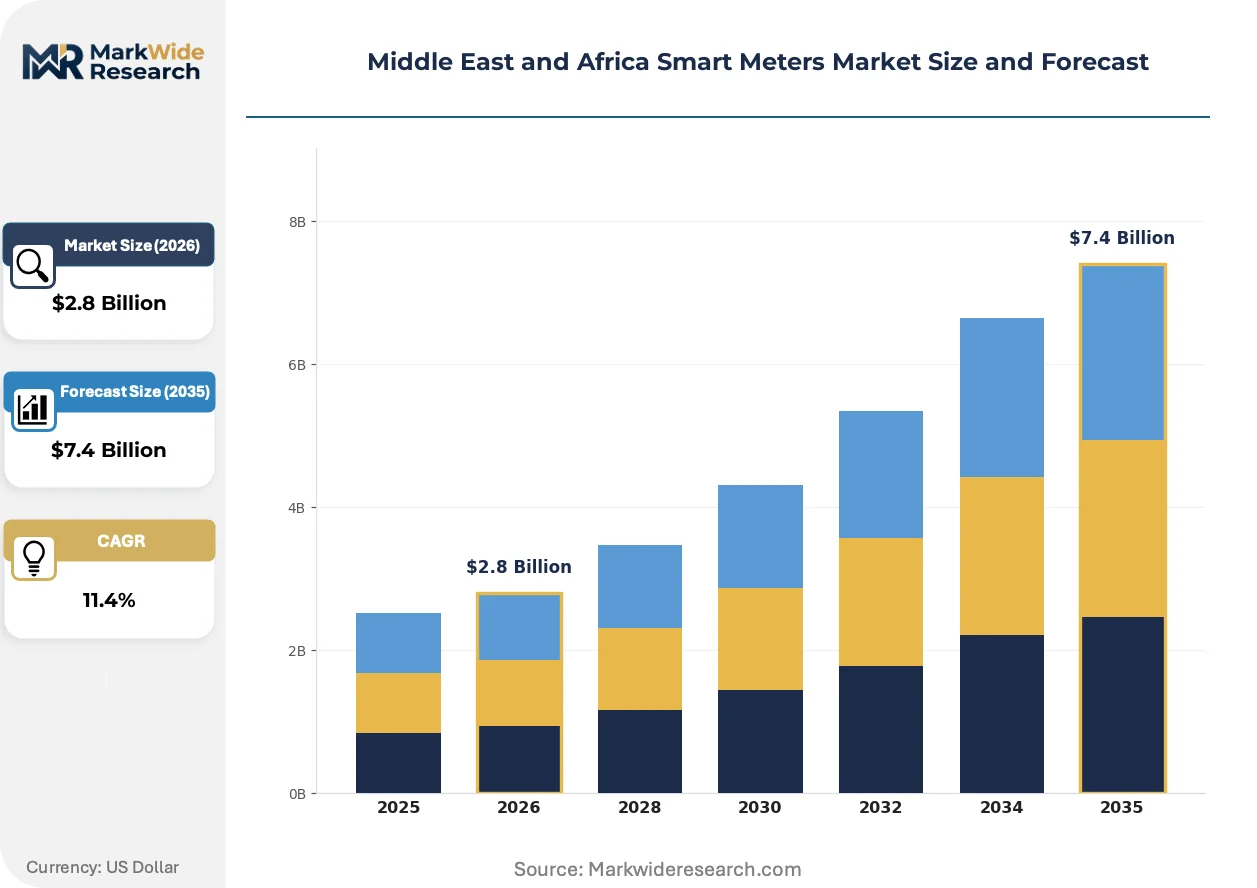
Market Dynamics
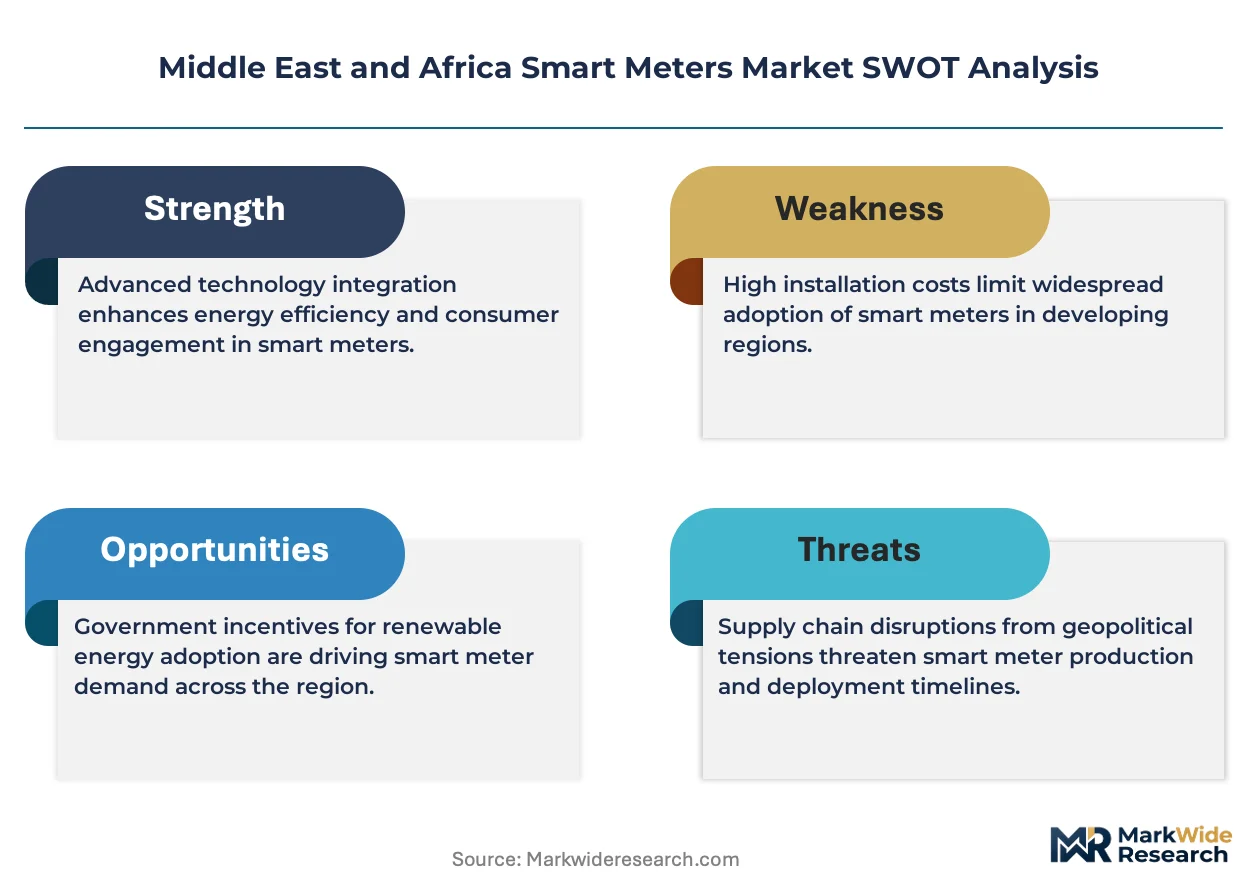
Utility-scale procurement consolidation across Saudi Arabia, South Africa, and the UAE is compressing vendor margins while elevating contract scale requirements for smart meter manufacturers serving national power authorities.
Growth Catalysts
- RF Certification Mandates:Saudi Arabia's Communications and Information Technology Commission enforces device certification protocols that standardize procurement specifications and accelerate replacement cycles for legacy electromechanical meters.
- Water Scarcity Conservation:Gulf Cooperation Council utilities deploy smart water meters under national conservation frameworks to reduce non-revenue water losses exceeding thirty percent in distribution networks.
- Time-of-Use Billing Infrastructure:South Africa's National Energy Regulator mandates interval metering capabilities that drive specifications for advanced metering infrastructure across municipal distribution zones.
Market Restraints
- Semiconductor Supply Concentration:Meter manufacturers depend on concentrated Asian foundry capacity for solid-state measurement engines, exposing procurement timelines to foundry allocation cycles.
- Cellular Module Cost Volatility:LTE-M and NB-IoT communication modules fluctuate with global memory pricing, compressing hardware margins on cellular-enabled deployments.
- Interoperability Friction:The UAE's Emirates Authority for Standardization and Metrology enforces certification requirements that fragment vendor qualification costs across Gulf markets with divergent technical addenda.
Strategic Opportunities
- Residential Smart Home Convergence:Zigbee-enabled meters integrate with home energy management systems in Saudi Arabia's Riyadh and Jeddah metropolitan zones, opening subscription revenue streams beyond hardware sales.
- Sub-Saharan Metering Gaps:Kenya and Nigeria's national utilities operate below ten percent smart meter penetration, presenting first-mover advantages for vendors accepting extended payment terms.
- Data Localization Requirements:Emerging privacy frameworks across the Gulf create demand for edge-computing architectures that process consumption data within national boundaries rather than cloud exports.
Industry Challenges
- SCADA Integration Complexity:Utilities in South Africa and Egypt operate heterogeneous legacy distribution management systems that require custom protocol adapters for smart meter head-end integration.
- Field Technician Certification Bottlenecks:National power authorities mandate installer qualifications for sealed outdoor enclosures that extend deployment timelines and constrain workforce scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Smart Meters Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Electric Meters, Smart Water Meters, Smart Gas Meters, Prepaid Meters Technology: RFID, PLC, Wi-Fi, Zigbee End User: Residential, Commercial, Industrial, Utilities Installation Type: On-grid, Off-grid, Retrofitted, New Installations |
| Companies Covered | Landis+Gyr Group AG, Itron Inc., Kamstrup A/S, Iskraemeco d.d., Elektromed (Termikel Group), Schneider Electric SE, Siemens AG, Honeywell International Inc, Sagemcom UK Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Smart Meters Market Shifts & Advancements
Communication architecture selection is bifurcating between power-line carrier dominance in dense urban zones and cellular adoption in dispersed rural networks, reshaping vendor product portfolio priorities.
Power-line carrier technology is consolidating its position as the default communication backbone for high-density residential deployments across Cairo, Johannesburg, and Dubai metropolitan zones. Municipal utilities favor PLC for its infrastructure reuse of existing distribution conductors, avoiding cellular subscription costs at scale. This technology is consolidating procurement decisions around single-vendor end-to-end solutions rather than best-of-breed component assembly.
Saudi Arabia's central regulator has expanded RF device certification protocols to include cybersecurity resilience testing for firmware over-the-air updates. The industrial consequence elevates engineering costs for meter firmware architecture but creates qualification barriers that favor established manufacturers with dedicated security engineering teams. Gulf Cooperation Council utilities now specify encrypted bootloaders and hardware security modules as standard procurement requirements.
Buyer concentration around sovereign water utilities in the UAE and Qatar is displacing fragmented municipal procurement with centralized framework agreements. National water authorities negotiate multi-year supply contracts that bundle metering hardware with fifteen-year data management services. This pattern concentrates most visible in Abu Dhabi and Doha, where single-source awards now exceed prior multi-vendor municipal tenders by order of magnitude.
Middle East and Africa Smart Meters Market Segmentation
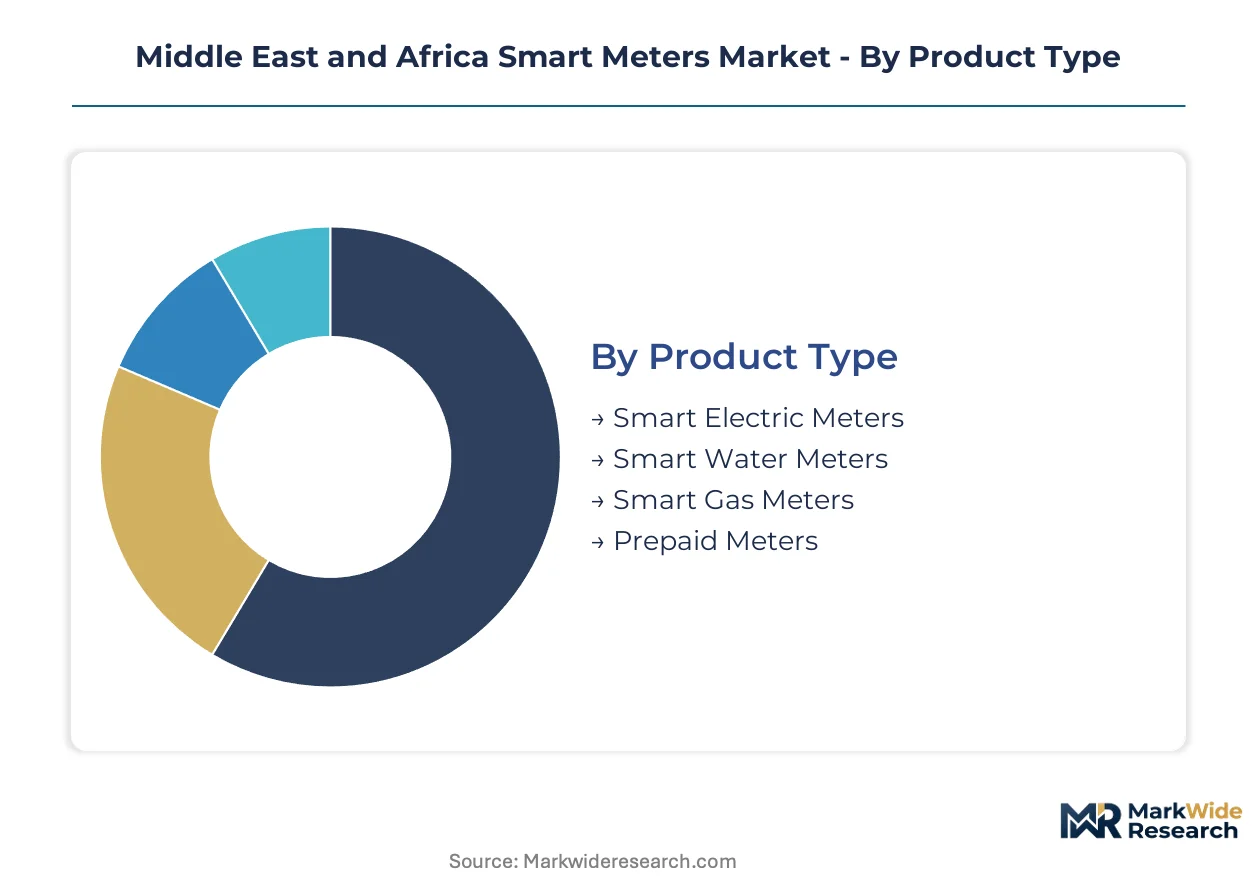
Smart meter procurement across the Middle East and Africa fragments across four distinct dimensions. Utility-scale tenders increasingly bundle hardware with long-term data services, elevating segment selection criteria beyond unit economics.
Product Type:
Replacement cycles for legacy electromechanical infrastructure are compressing as national regulators mandate interval metering capabilities.
- Smart Electric Meters:Solid-state measurement engines with non-volatile memory storage enable hourly consumption logging for time-of-use billing schemes. Saudi Arabia's national power authority specifies these units for loss-reduction programs targeting distribution networks exceeding fifteen percent technical losses.
- Smart Water Meters:Sealed ultrasonic or electromagnetic flow sensors withstand desert climate exposure while transmitting consumption data via RF networks. Abu Dhabi and Doha's sovereign water utilities deploy these under conservation mandates addressing non-revenue water losses surpassing thirty percent.
- Smart Gas Meters:Diaphragm or rotary displacement meters incorporate temperature compensation and remote shut-off valves for safety monitoring.
- Prepaid Meters:Token-based or keypad-enabled units dominate sub-Saharan municipal deployments where credit risk and collection costs constrain conventional billing models.
Volume placements concentrate in smart electric meters; the faster expansion belongs to smart water meters.
Technology:
Communication architecture selection hinges on population density and existing grid infrastructure maturity across deployment zones.
- PLC:Power-line carrier modems superimpose data signals onto distribution conductors, eliminating cellular subscription costs in dense Cairo and Johannesburg metropolitan zones. Municipal utilities favor single-vendor end-to-end solutions over component assembly for this technology.
- Zigbee:Mesh-networking protocols enable residential smart home integration, with Riyadh and Jeddah utilities specifying these for demand response programs linking meter data to home energy management systems.
- RFID:Passive or active radio-frequency identification supports walk-by or drive-by meter reading in dispersed rural networks where infrastructure density cannot justify fixed network investments.
- Wi-Fi:IEEE 802.11 protocols serve commercial and industrial premises with existing wireless LAN infrastructure, though power consumption limits residential battery-powered deployments.
Cost structures favor PLC in urban concentration zones; Zigbee climbs fastest where smart home convergence drives specification requirements.
End User:
Customer type determines data granularity requirements and integration complexity with existing utility information systems.
- Utilities:National power authorities and sovereign water utilities procure enterprise-scale head-end systems integrating hundreds of thousands of endpoints with SCADA and billing platforms. South Africa's municipal distributors mandate these deployments for time-of-use tariff enforcement.
- Residential:Single-family and multi-tenant dwellings drive unit volume through mass deployment programs, with Gulf Cooperation Council utilities prioritizing prepaid and smart home-compatible configurations.
- Commercial:Office buildings and retail premises require sub-metering capabilities for tenant billing and load profiling to support demand response participation.
- Industrial:Heavy manufacturing and processing facilities specify high-accuracy revenue-grade meters with power quality monitoring for harmonic distortion and voltage sag detection.
Revenue concentration sits with utility-scale procurement; residential segments expand most quickly through national electrification and water network extension programs.
Installation Type:
Grid connectivity status and building vintage shape deployment methodology and total cost of ownership calculations.
- Retrofitted:Replacement of existing electromechanical meters dominates mature urban networks across Dubai, Riyadh, and Johannesburg where legacy infrastructure reaches end-of-life. Field technician certification requirements for sealed outdoor enclosures extend deployment timelines.
- New Installations:Greenfield residential developments and industrial zones specify smart-ready infrastructure from construction, avoiding future replacement labor costs.
- On-grid:Grid-connected deployments leverage existing distribution infrastructure for power and communication backhaul.
- Off-grid:Solar-hybrid mini-grids in rural Kenya and Nigeria incorporate battery-powered smart meters with cellular backhaul where main grid extension remains uneconomic.
Retrofitted units command current volume leadership; new installations gain share fastest through Gulf urban expansion and special economic zone development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement concentrates in Gulf Cooperation Council capitals and South African metropolitan zones, with sovereign authorities consolidating multi-year framework agreements that displace fragmented municipal purchasing. National regulators in Saudi Arabia and the UAE now mandate device certification protocols that standardize technical specifications across contiguous markets.
Saudi Arabia
Riyadh and Jeddah utilities drive deployment volume through prepaid and smart home-compatible meter specifications. The Communications and Information Technology Commission enforces RF device certification protocols that accelerate replacement cycles for legacy electromechanical infrastructure. Eastern Province industrial zones specify high-accuracy revenue-grade meters for manufacturing facilities monitoring power quality parameters.
United Arab Emirates
Abu Dhabi and Dubai sovereign water utilities negotiate centralized framework agreements bundling hardware with fifteen-year data management services. The Emirates Authority for Standardization and Metrology enforces interoperability standards that shape procurement requirements across Gulf markets. Northern Emirates distribution networks favor PLC communication architecture to avoid cellular subscription costs at scale.
South Africa
Johannesburg and Cape Town municipal distributors mandate time-of-use billing infrastructure that drives advanced metering specifications. The National Energy Regulator requires interval metering capabilities across distribution zones with technical losses exceeding fifteen percent. Eastern Cape and KwaZulu-Natal utilities face SCADA integration complexity with heterogeneous legacy systems requiring custom protocol adapters.
Egypt
Cairo metropolitan utilities consolidate procurement around single-vendor end-to-end PLC solutions for dense urban residential deployments. The Egyptian Electric Utility and Consumer Protection Regulatory Agency oversees grid modernization programs targeting loss reduction in distribution networks. Alexandria and Delta region industrial clusters specify meters with harmonic distortion monitoring for heavy manufacturing load profiling.
Nigeria
Lagos and Abuja national utilities operate below ten percent smart meter penetration, presenting first-mover positioning for vendors accepting extended payment terms. The Nigerian Electricity Regulatory Commission mandates prepaid metering frameworks to address credit risk and collection cost constraints. Niger Delta oil-producing regions deploy cellular-enabled meters where distribution infrastructure density cannot justify fixed network investments.
Middle East and Africa Smart Meters Market Competitive Landscape
European producers anchor the premium-tier infrastructure segment; Asian component specialists hold supply-side positions in communication modules and solid-state measurement engines. Market structure tilts toward consolidated procurement around sovereign utilities, compressing vendor margins while elevating contract scale requirements. Three archetypes dominate: full-system integrators bundling hardware with data services; communication technology specialists licensing RF and PLC protocols; and regional fabrication partners assembling sealed enclosures for desert climate exposure. Competitive moves center on strategic partnerships with national power authorities and portfolio diversification into water and gas metering categories.
Within the full-system integrator tier, Landis+Gyr Group AG and Schneider Electric SE exemplify European-headquartered operators with manufacturing presence in regional hubs. Itron Inc. occupies a position among North American-based analytics platform providers integrating with existing utility SCADA systems. These three entities represent the dominant competitive anchors as Gulf Cooperation Council utilities consolidate procurement around framework agreements exceeding prior multi-vendor municipal tenders by order of magnitude.
| Leading Market Players |
|---|
| Landis+Gyr Group AG |
| Itron Inc. |
| Kamstrup A/S |
| Iskraemeco d.d. |
| Elektromed (Termikel Group) |
| Schneider Electric SE |
| Siemens AG |
| Honeywell International Inc |
| Sagemcom UK Ltd |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between RF-certified premium units and uncertified economy alternatives manifests in both procurement pricing and component sourcing patterns across Middle East and Africa smart meter deployments. Gulf Cooperation Council utilities pay substantial premiums for meters meeting Saudi Arabia's Communications and Information Technology Commission cybersecurity protocols, while sub-Saharan municipal buyers prioritize unit cost over certification depth, fragmenting supplier tiers and reshaping foundry allocation priorities.
Pricing Analysis
Volume-mass deployments in Nigeria and Kenya trade margin for market access, while premium-tier contracts in Saudi Arabia and the UAE sustain higher pricing through bundled data services. Price differentiation hinges on certification grade—CITC-compliant units command substantial premiums—and after-sales service bundling, with fifteen-year data management contracts elevating total contract value. Cost compression in cellular-enabled tiers intensifies because LTE-M module pricing fluctuates with memory spot markets. Municipal distributors in sub-Saharan markets exhibit highest price sensitivity; sovereign water utilities in Abu Dhabi and Doha show least sensitivity due to conservation-mandate urgency.
Supply Chain Analysis
Saudi Arabia's local-content rules and South Africa's domestic manufacturing incentives are reshaping sourcing patterns, pressuring vendors to establish regional assembly presence. Solid-state measurement engines draw from Taiwan and South Korea foundries; cellular communication modules source from China; sealed outdoor enclosures fabricate in Turkey and UAE free zones. Single-source vulnerability concentrates in Asian semiconductor foundry capacity, exposing procurement timelines to allocation cycles. Distribution runs through national power authority framework agreements that consolidate formerly fragmented municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where Saudi Arabia's CITC cybersecurity certification creates a barrier-to-entry moat that rewards established players with dedicated security engineering teams and punishes component assemblers lacking firmware architecture depth.
For Market Incumbents: Deploy backward integration into solid-state measurement engine sourcing to buffer foundry allocation volatility. Secure multi-year framework agreements with Saudi Arabia's national power authority and Abu Dhabi's sovereign water utility before certification requirements tighten further. Threat: Asian component specialists upgrading firmware capabilities to challenge system integrator positioning. For New Entrants and Emerging Players: Capture first-mover positioning in Nigeria's prepaid metering gap and Kenya's off-grid solar-hybrid mini-grid segment where penetration sits below ten percent. Most penetrable target: Lagos municipal distributors accepting extended payment terms. Go-to-market angle: cellular-enabled units bypassing fixed network infrastructure requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by European full-system integrators seeking regional manufacturing footholds. Long-term viability favors vendors with demonstrated CITC certification history and water metering portfolio diversification. Signal to watch: Emirates Authority for Standardization and Metrology expanding interoperability requirements to data localization architecture.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | CITC cybersecurity compliance opens Saudi framework agreements exceeding prior municipal tenders. |
| Regional Manufacturing Footprint | UAE and Turkey assembly presence satisfies Gulf local-content mandates and reduces logistics exposure. |
| Water Metering Portfolio Expansion | Abu Dhabi and Doha conservation mandates drive fastest-growing product category demand. |
| Cellular Module Supply Agreement | Long-term LTE-M contracts stabilize hardware margins against memory pricing volatility. |
| Data Localization Architecture | Edge-computing capabilities align with emerging Gulf privacy frameworks reshaping cloud decisions. |
Research Methodology
Independent corroboration across utility procurement officers, smart meter manufacturer product managers, and regulatory affairs specialists at national standards bodies underwrites the qualitative findings. Primary fieldwork engaged distribution network planners at Saudi Arabia's national power authority, firmware engineering leads at European system integrators, and metering program directors at South African municipal distributors. Secondary validation drew from CITC device certification registries, Emirates Authority for Standardization and Metrology technical addenda, and FERC-style regulatory filings from Middle East energy regulators. Bottom-up unit deployment tracking triangulates against top-down utility capex disclosure analysis.
Rate-of-change decomposition separates volume growth from pricing trajectory across the analysis window, with segmentation modeling across product type, communication technology, end user category, and installation methodology. The analytical framework incorporates smart electric meter replacement cycles, smart water meter conservation mandate acceleration, and prepaid metering penetration in sub-Saharan markets. CAGRs derive from utility framework agreement award timing, national regulator mandate implementation schedules, and foundry capacity allocation cycles for solid-state measurement engines.
The model holds under stable regulatory certification timelines and uninterrupted semiconductor foundry supply; deviation in CITC protocol expansion pace or Taiwan Strait logistics disruption would shift deployment trajectories. Forecasts reflect documented assumptions regarding national power authority procurement consolidation and sovereign water utility framework agreement migration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Smart Metering Systems Market
Smart Meters
US Water Meter Market
Smart Meters
Smart Utility Solutions Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Gas Meters Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Europe Smart Meters Market
Smart Meters
Power Metering Market
Smart Meters
Europe Water Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Smart Electric Meter Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
Europe Smart Meter Data Management Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Global Energy and Power Quality Meters Market