
 Smart Meter Antenna Market | 2026-2036
Smart Meter Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Meter Antenna Market Insights
Project finance for smart city infrastructure is fragmenting the competitive landscape for antenna procurement, lowering barriers for specialized vendors. Taoglas leverages its Irish design heritage to compete on multi-band cellular configurations for European utilities. Shenzhen Sunway Communication anchors high-volume production of integrated antenna modules for Asian meter OEMs. Continental AG extends its automotive RF expertise into ruggedized outdoor mount antennas for industrial metering applications.
Smart meter antennas are RF transducers engineered for sub-6 GHz operation with IP67 environmental sealing, converting electromagnetic signals between meter electronics and wide-area networks for remote data telemetry. Cellular technology leads value contribution as utilities mandate LTE-M and NB-IoT compatibility for mission-critical connectivity, while LoRaWAN segments compete on lower power budgets for rural deployments. External antennas sustain premium positioning where signal penetration challenges demand elevated gain profiles, whereas integrated antennas dominate unit economics in residential smart meter rollouts.
FCC Part 15 emissions rules in the United States, CE marking under the EU Radio Equipment Directive, and China's MIIT radio transmission type-approval framework collectively shape product certification timelines and technical specifications for cross-border suppliers. ETSI EN 303 645 cybersecurity standards for IoT devices are forcing antenna-integrated designs to accommodate hardware-level encryption modules. Stakeholders must monitor spectrum reallocation decisions by national regulators that could obsolete existing frequency-tuned antenna inventories before design refresh cycles complete.
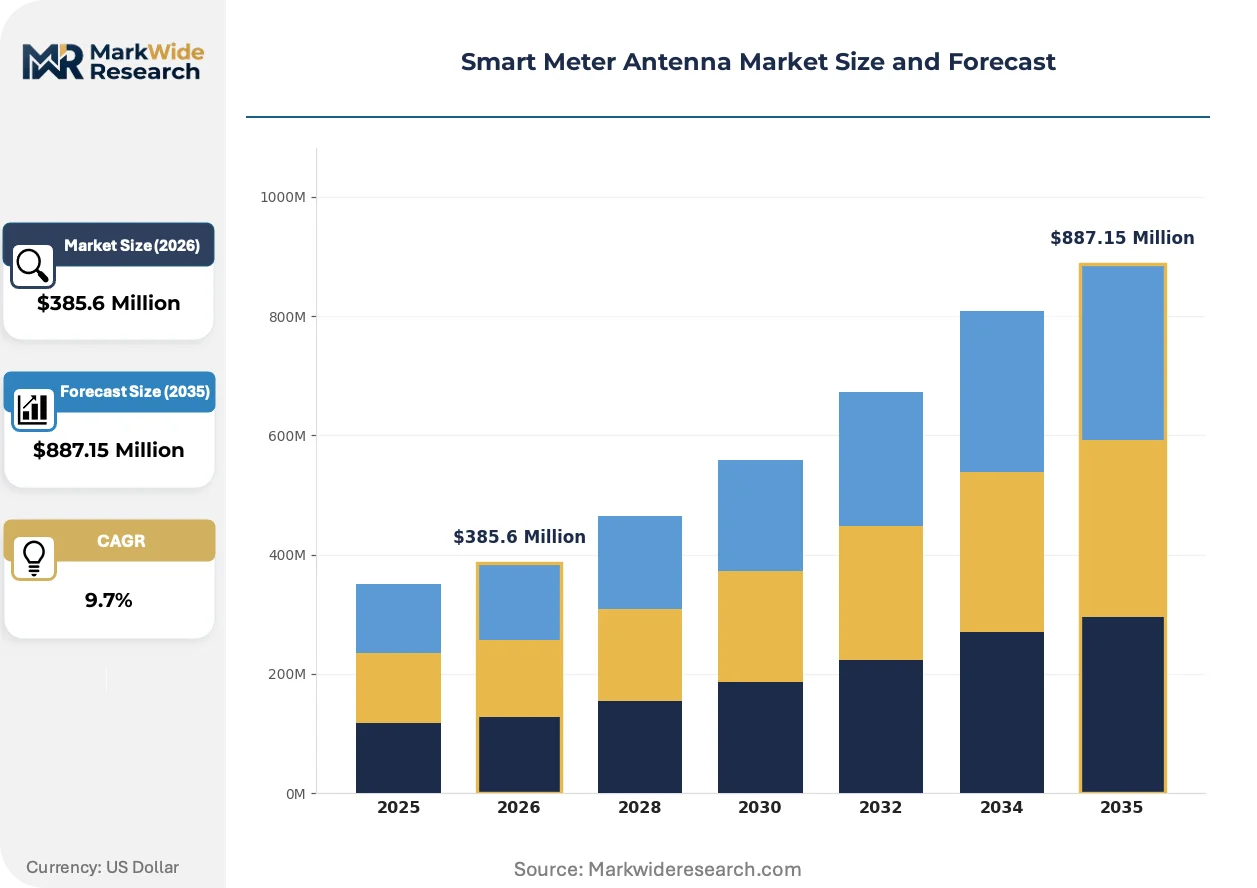
Market Dynamics
Grid operators are mandating LTE-M and NB-IoT compatibility in new meter deployments, forcing antenna suppliers to re-engineer multi-band architectures before legacy inventory clears. This technology refresh cycle compresses design timelines and fragments procurement across specialized RF vendors.
Growth Catalysts
- EU Green Deal mandates:Member-state utilities must deploy advanced metering infrastructure to meet carbon reduction targets, accelerating orders for cellular-enabled antennas with IP67 sealing.
- China MIIT type-approval framework:Standardized radio transmission certification reduces cross-border supplier friction, enabling faster market entry for compliant antenna modules.
- Sub-6 GHz spectrum allocation:National regulators are releasing dedicated IoT bands, allowing antenna designers to optimize gain profiles for mission-critical telemetry without interference from consumer cellular traffic.
Market Restraints
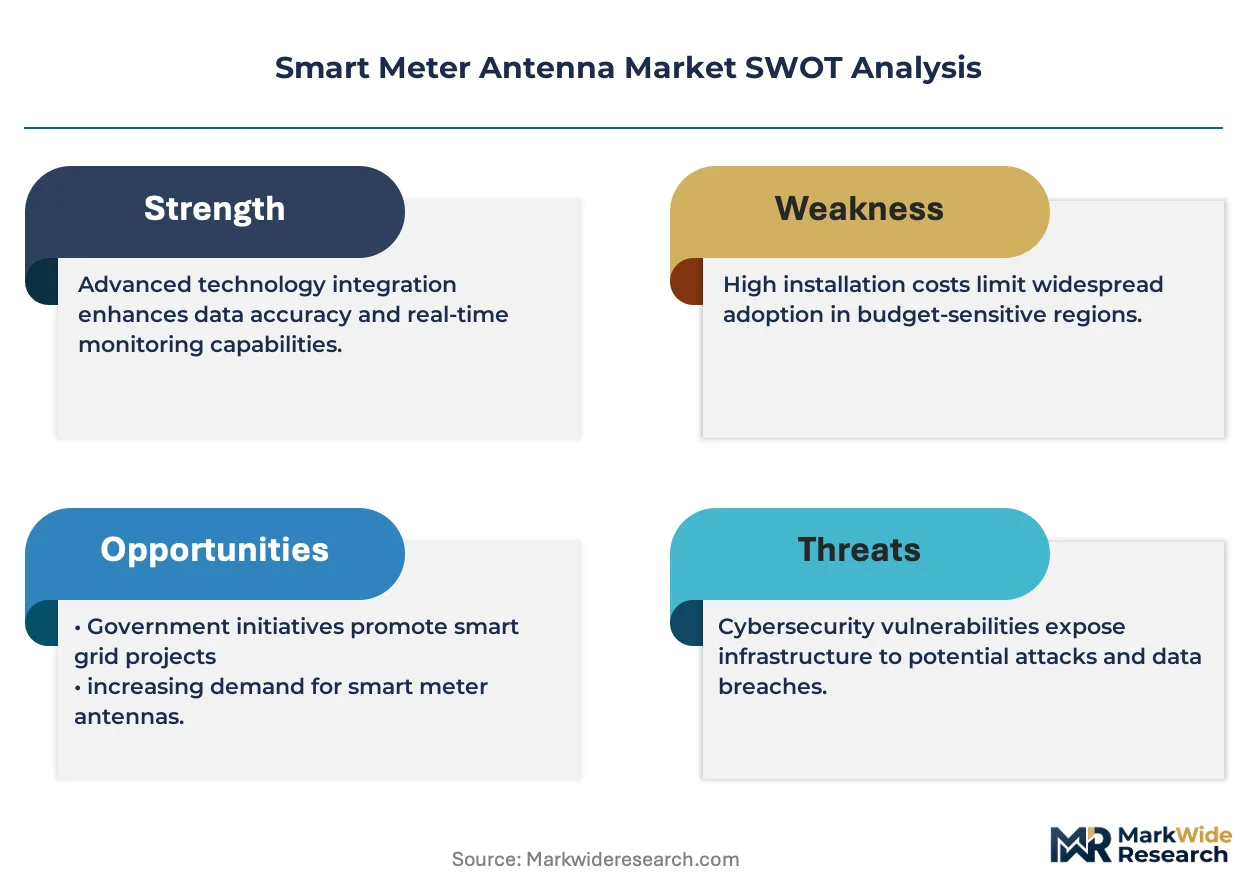
- RF ceramic substrate concentration:High-performance dielectric materials for sub-6 GHz operation source primarily from Japanese and Chinese suppliers, creating input cost volatility and allocation risk.
- ETSI EN 303 645 compliance burden:Hardware-level encryption module integration extends antenna-integrated design cycles by 4-6 months, stretching R&D budgets for mid-tier vendors.
- LoRaWAN substitution pressure:Rural utilities in cost-sensitive markets are selecting unlicensed spectrum alternatives, displacing cellular antenna volumes in low-density deployment zones.
Strategic Opportunities
- India smart city infrastructure:Underpenetrated urban metering programs offer white space for antenna suppliers with localized production and BIS certification capabilities.
- Dual-radio convergence:Antenna architectures combining cellular and powerline communication are capturing hybrid AMI deployments where utilities demand redundant backhaul paths.
- FCC spectrum reallocation timing:Anticipated 3.5 GHz CBRS band expansion creates first-mover advantage for vendors with pre-certified antenna designs tuned to emerging utility-private network specifications.
Industry Challenges
- RF simulation talent scarcity:Electromagnetic modeling expertise for multi-band optimization concentrates in aerospace and automotive sectors, forcing antenna vendors to compete for limited electromagnetic compatibility engineers.
- Legacy meter integration complexity:Retrofit antenna solutions must accommodate proprietary meter electronics from decade-old deployments without standardized mounting interfaces or power budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Meter Antenna Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $887.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Antennas, External Antennas, Integrated Antennas, Lens Antennas Technology: Wi-Fi, Zigbee, LoRaWAN, Cellular End User: Utilities, Residential Users, Commercial Users, Industrial Users Installation Type: Fixed Mount, Portable Mount, Outdoor Mount, Indoor Mount |
| Companies Covered | Panorama Antennas, Welotec GmbH, Taoglas, Poynting, Shenzhen Sunway Communication, Kunshan RCD Electronic Co., Ltd., Antenova, Continental AG, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Meter Antenna Market Trends and Innovations
Antenna form factors are compressing as utilities demand invisible integration into meter housings, while regulatory pressure on cybersecurity is embedding hardware authentication directly into RF modules. These shifts are redrawing supplier capabilities and procurement criteria simultaneously.
Dielectric resonator antenna technology is migrating from satellite communications into smart meter applications. German and Chinese utilities are piloting these compact, high-efficiency radiators for dense urban deployments where internal antenna mounting eliminates external vandalism risk. The technology is migrating from aerospace heritage into volume meter manufacturing, compressing the traditional trade-off between gain performance and physical footprint.
REACH substance restrictions on halogenated flame retardants are forcing antenna housing material transitions. European suppliers must reformulate IP67 enclosures to maintain UV stability without restricted brominated compounds, adding 8-12 weeks to qualification timelines. Meter OEMs serving EU member states are consolidating supplier bases to vendors with pre-certified green material portfolios, marginalizing smaller antenna houses lacking polymer chemistry partnerships.
Utility procurement departments are unbundling antenna supply from meter OEM captive sourcing. Large North American cooperatives now issue separate RF component tenders, enabling direct supplier relationships with Taoglas and Shenzhen Sunway Communication that bypass traditional meter manufacturer markups. This disintermediation is most visible in Texas and California municipal utility districts where technical evaluation committees possess standalone RF engineering expertise.
Smart Meter Antenna Market Segmentation
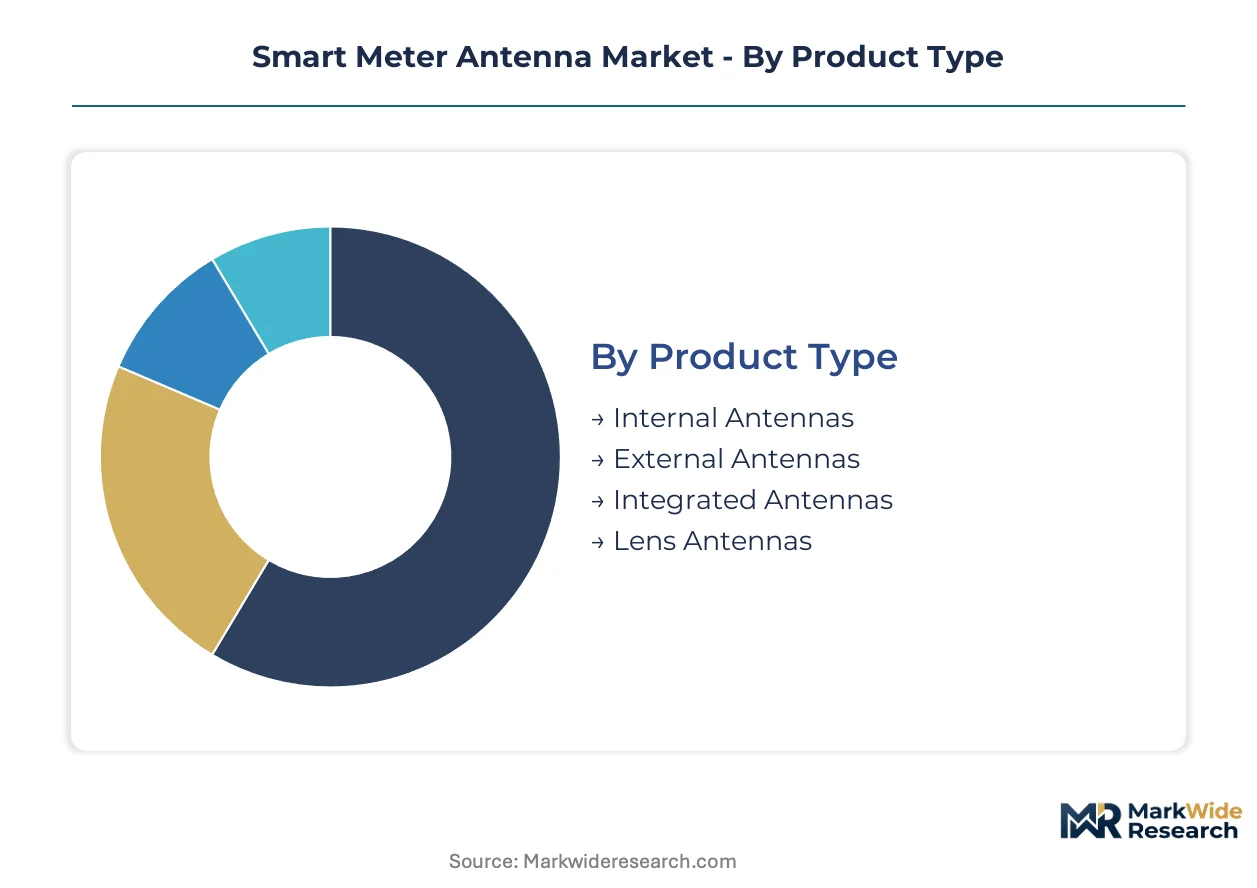
Smart meter antenna procurement splits across four orthogonal dimensions that rarely align in vendor selection. Product type and technology choices determine hardware compatibility, while end-user scale and installation constraints shape volume economics and certification requirements.
Product Type:
Replacement cycles vary dramatically: integrated antennas turn over with every meter generation, while external mountings persist across multiple hardware refreshes. Internal and lens architectures occupy intermediate positions depending on housing redesign frequency.
- Internal Antennas:Embedded directly within meter enclosures using PCB-trace or chip-antenna designs. German utilities deploying dense urban AMI clusters favor these configurations to eliminate external vandalism exposure and reduce installation labor.
- External Antennas:Ruggedized units with elevated gain profiles mounted outside meter housings. These sustain premium positioning in rural United States deployments where signal penetration challenges demand hardware replacement only when physical damage occurs, stretching effective lifecycles.
- Integrated Antennas:Pre-certified modules supplied by meter OEMs as captive components. Volume concentration in Chinese residential rollouts drives unit economics, though disintermediation trends in North America are opening direct procurement channels.
- Lens Antennas:Dielectric resonator variants migrating from satellite communications heritage. Pilot deployments by Chinese and German grid operators are validating compact form factors for space-constrained smart meter housings.
Integrated antennas dominate installed base. External mountings are where expansion concentrates for mission-critical connectivity in challenging RF environments.
Technology:
Cost tiers stratify sharply: unlicensed spectrum solutions compete on hardware economics, while cellular technologies command premium positioning through carrier certification and guaranteed quality-of-service.
- Cellular:LTE-M and NB-IoT transceivers with carrier-certified modules. United States utilities mandating mission-critical telemetry are standardizing on these technologies despite higher module costs, prioritizing network reliability over capital expenditure minimization.
- LoRaWAN:Unlicensed sub-GHz protocols optimized for low power budgets and extended range. Rural cooperatives in cost-sensitive markets are displacing cellular volumes in low-density deployment zones where private network ownership beats recurring carrier fees.
- Wi-Fi:2.4 GHz and 5 GHz modules for mesh-backhaul or consumer-visible deployments. Residential smart home integrations in United States municipal districts leverage existing broadband infrastructure.
- Zigbee:IEEE 802.15.4-based mesh networking for neighborhood-area network aggregation. Utility pilots in Germany explore hybrid architectures combining Zigbee local aggregation with cellular WAN backhaul.
Cellular technologies anchor revenue contribution. LoRaWAN is climbing the fastest as rural utilities prioritize total cost of ownership over performance specifications.
End User:
Customer type determines procurement sophistication: utilities issue formal RFQs with technical evaluation committees, while residential and commercial segments accept meter OEM bundled solutions.
- Utilities:Grid operators with dedicated RF engineering staff issuing standalone antenna tenders. Texas and California municipal districts now bypass traditional meter manufacturer markups through direct supplier relationships.
- Industrial Users:Heavy manufacturing and data center campuses with private network requirements. These deployments demand ruggedized outdoor mountings with elevated IP ratings and extended temperature tolerance.
- Commercial Users:Multi-tenant buildings and retail chains accepting standard meter OEM configurations. Procurement concentrates on installation speed rather than RF optimization.
- Residential Users:Single-family dwellings served by utility-managed AMI programs. End users rarely influence antenna selection, though visibility concerns are pushing invisible internal antenna preferences.
Utilities dominate installed base. Industrial users are gaining share fastest as private network deployments multiply.
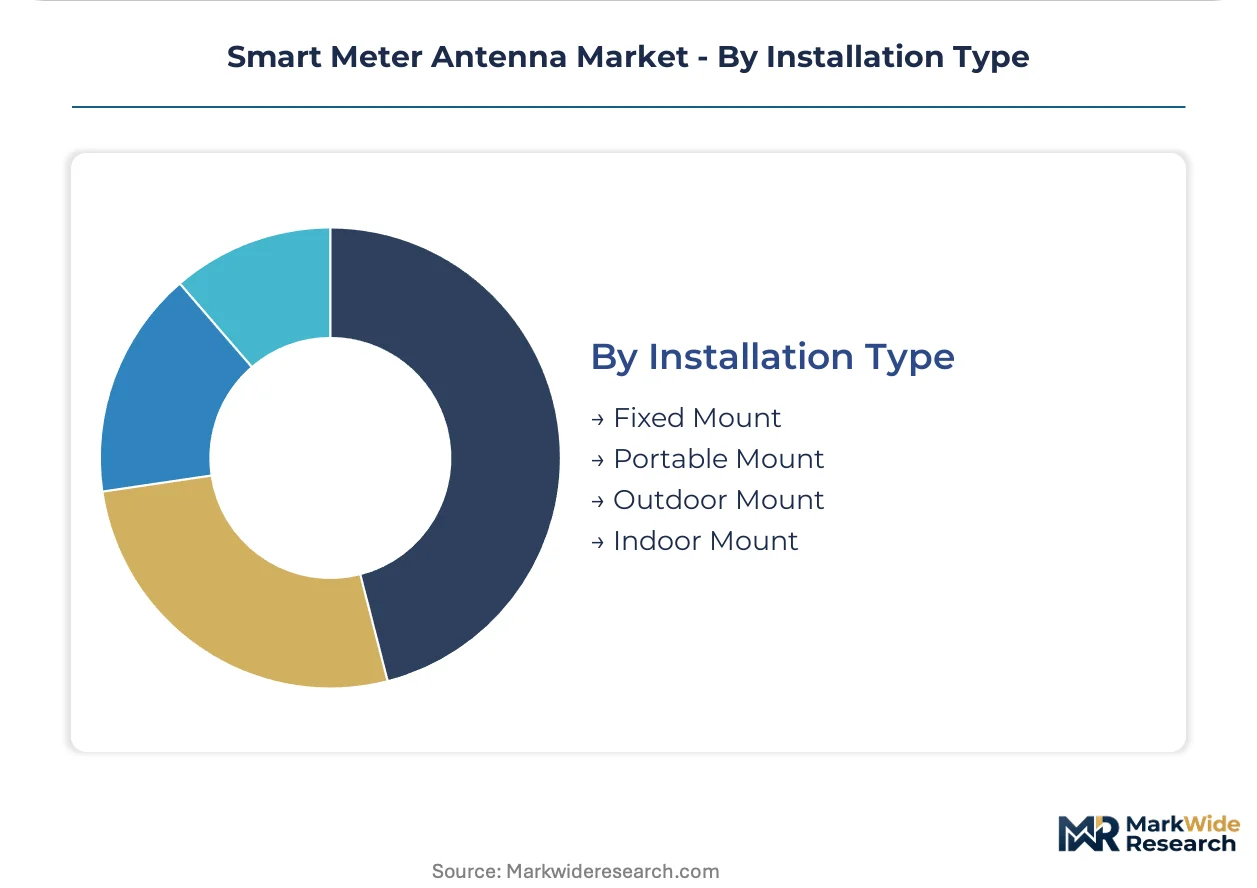
Installation Type:
Volume concentrates in fixed outdoor mountings for utility AMI, while portable and indoor variants serve niche applications with distinct certification and supply chains.
- Fixed Mount:Permanent installations on utility poles, building exteriors, or dedicated meter cabinets. These constitute the standard configuration for utility-scale AMI deployments across Germany, China, and the United States.
- Outdoor Mount:Weather-hardened enclosures with IP67 sealing and UV-stabilized polymers. REACH substance restrictions on halogenated flame retardants are forcing European suppliers to reformulate housing materials.
- Indoor Mount:Reduced sealing requirements for basement, utility room, or kiosk deployments. These configurations sacrifice environmental tolerance for cost minimization in controlled settings.
- Portable Mount:Temporary or mobile metering applications including construction sites and event infrastructure. Limited volume concentrates in rental equipment channels with accelerated depreciation cycles.
Fixed mount configurations dominate installed base. Outdoor mountings are where specification intensity concentrates as climate resilience requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in smart meter antennas track utility infrastructure investment cycles rather than manufacturing cost arbitrage. Germany and China run structural surpluses in high-performance RF components, while the United States remains a net importer of specialized cellular antenna modules despite domestic meter assembly capacity.
Germany
Dense urban AMI deployments in the Ruhr region and Bavaria drive demand for vandalism-resistant internal antenna configurations. The EU Green Deal and F-Gas Regulation mandate efficiency upgrades that accelerate cellular-enabled meter replacements. Berlin-Brandenburg hosts testing clusters where dielectric resonator antennas undergo field validation for space-constrained housings.
China
State Grid Corporation's nationwide smart meter rollout consumes integrated antenna modules at volumes unmatched elsewhere. MIIT type-approval standardization reduces certification friction for domestic suppliers. The Yangtze River Delta concentration around Shanghai and Suzhou anchors high-volume production of sub-6 GHz antenna substrates for regional meter OEMs.
United States
Texas and California municipal utility districts now issue standalone RF component tenders, bypassing traditional meter manufacturer markups. FCC Part 15 emissions rules and anticipated 3.5 GHz CBRS expansion shape procurement specifications. The Southwest sees concentrated outdoor antenna demand where signal penetration challenges persist across rural cooperative territories.
India
Underpenetrated urban metering programs in Maharashtra and Gujarat offer white space for suppliers with localized production and BIS certification capabilities. The national smart city mission channels central government funding into AMI infrastructure. Delhi-NCR serves as the regulatory compliance hub where antenna designs undergo type-approval before statewide deployment.
Japan
TEPCO and regional utilities prioritize earthquake-hardened meter installations with redundant connectivity architectures. METI standards for IoT device cybersecurity extend antenna design cycles to accommodate hardware-level encryption. The Kanto region around Tokyo concentrates pilot deployments of dual-radio antennas combining cellular and powerline backhaul.
Smart Meter Antenna Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the RF module layer. The supplier base organizes into three functional tiers: meter OEMs with captive antenna sourcing, independent RF component vendors, and substrate material suppliers. Consolidation pressure concentrates at the component tier where certification burdens favor scaled operations. Competitive moves center on disintermediation of traditional meter manufacturer channels and pre-certification of designs to emerging spectrum allocations.
Among European RF specialists, Taoglas and Welotec GmbH occupy positions anchored by regional design heritage and utility relationships. Shenzhen Sunway Communication exemplifies the Asia-Pacific volume tier serving meter OEMs with integrated module production. Continental AG represents industrial diversification from automotive RF expertise into ruggedized outdoor applications. These three archetypes illustrate the geographic and functional segmentation governing procurement decisions.
| Leading Market Players |
|---|
| Panorama Antennas |
| Welotec GmbH |
| Taoglas |
| Poynting |
| Shenzhen Sunway Communication |
| Kunshan RCD Electronic Co., Ltd. |
| Antenova |
| Continental AG |
| TE Connectivity |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese antenna substrate fabrication is compressing margins for mid-tier vendors while concentrating pricing power among Japanese dielectric material suppliers. This utilization imbalance forces procurement departments to accept longer qualification timelines or absorb premium input costs for mission-critical RF components.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across carrier-certified premium tiers, standard MIIT-compliant modules, and economy-grade unlicensed alternatives. Price differentiation hinges on certification grade and volume scale, with ETSI EN 303 645 hardware encryption compliance commanding substantial premiums. Cost compression in the standard tier is intensifying because LoRaWAN substitution pressure limits cellular antenna pricing power. Rural cooperatives exhibit highest price sensitivity, while German utilities with Green Deal mandates demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for North American meter OEMs. RF ceramic substrate production concentrates in Japan, China, and South Korea, with high-performance dielectric materials drawing from Japanese and Chinese suppliers. Single-source vulnerability persists for sub-6 GHz ceramic formulations. Distribution runs through meter OEM captive channels, though Texas and California municipal districts are disintermediating via direct RF component tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromagnetic modeling expertise for multi-band optimization remains scarce, concentrating in aerospace and automotive sectors rather than metering applications. This capability gap limits vendor expansion and creates acquisition premiums for RF engineering talent.
For Market Incumbents: Harden certification portfolios against ETSI EN 303 645 hardware encryption mandates before compliance deadlines fragment procurement further. Deepen backward integration into ceramic substrate supply through partnerships with Japanese dielectric material houses to offset allocation risk. Lock in long-term offtake agreements with German utilities executing Green Deal-mandated AMI rollouts. For New Entrants and Emerging Players: Underpenetrated urban metering programs in India offer white space for antenna suppliers with localized production and BIS certification capabilities. Target Maharashtra and Gujarat smart city infrastructure where technical evaluation committees lack standalone RF engineering expertise. Pursue dual-radio convergence architectures combining cellular and powerline communication as a differentiated entry angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hardware-encryption-integrated antenna designs due to extended R&D cycles and certification costs. Five-to-ten year viability favors vendors with pre-certified green material portfolios under REACH substance restrictions. Monitor FCC 3.5 GHz CBRS band expansion timing as the critical inflection signal for first-mover positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Japanese dielectric material partnerships reduce allocation risk for sub-6 GHz formulations. |
| Dual-Radio Convergence Development | Hybrid cellular-powerline architectures capture redundant backhaul demand from Japanese utilities. |
| REACH-Compliant Material Qualification | Halogen-free IP67 enclosures secure European procurement consolidation toward green portfolios. |
| Direct Utility Procurement Channel | Bypassing meter OEM markups captures margin expansion in Texas and California municipal districts. |
| Pre-Certification to Emerging Spectrum | 3.5 GHz CBRS-tuned designs create first-mover advantage ahead of FCC expansion rulings. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across utility RF engineering directors, meter OEM procurement leads, antenna module design engineers, and cellular carrier certification specialists. Primary interview insights were cross-validated against secondary sources including FCC equipment authorization databases, MIIT radio transmission type-approval records, ETSI EN 303 645 implementation guidance, and utility AMI deployment filings. Bottom-up antenna shipment estimates were triangulated with top-down utility infrastructure investment tracking.
Calibration against historical cellular module adoption curves and spectrum allocation timing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include antenna form factor, connectivity technology, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from utility deployment pipeline analysis and meter OEM order book trajectories, incorporating sub-6 GHz spectrum release schedules and cybersecurity compliance phase-in timelines as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in utility capital expenditure cycles or national spectrum reallocation decisions would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and technology refresh cadences. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Water Meter Market
Smart Meters
Europe Smart Meter Data Management Market
Smart Meters
Smart Gas Metering Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
Asia-Pacific Smart Meter Data Management Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
United States (US) Residential Smart Meters Market
Smart Meters
United States Smart Meter Market
Smart Meters
Power Metering Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Smart Water Metering Market
Smart Meters
Smart Utility Solutions Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Global Smart Energy Meters Market