
 Smart Electric Meter Market | 2026-2036
Smart Electric Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Electric Meter Market Analysis
Market Context
Southeast Asia's manufacturing corridor is fragmenting as domestic assembly capacity for smart metering hardware expands across Thailand, Vietnam, and Malaysia. Landis+Gyr leverages its Swiss engineering heritage to dominate European utility tenders with advanced metering infrastructure solutions. Itron Inc. sustains North American market presence through deep utility relationships and end-to-end managed services. Wasion Group anchors Asia-Pacific supply chains with cost-optimized production platforms and regional certification breadth.
Technical Definition and Structural Segments
A smart electric meter is an electronic device that records electricity consumption at intervals of one hour or less and communicates that data to the utility for monitoring and billing, typically incorporating solid-state measurement technology with accuracy classes of 0.2S to 1.0 and operating temperature ranges from minus 25 to plus 70 degrees Celsius. Single-phase meters occupy the largest volume tier as residential replacement cycles accelerate across mature markets, while three-phase meters command premium positioning in commercial and industrial deployments where power quality monitoring and demand response integration justify higher unit economics. Cellular technology leads connectivity adoption in rural and dispersed geographies where mesh alternatives face infrastructure gaps, whereas Power Line Communication dominates dense urban environments that leverage existing electrical distribution wiring for data backhaul.
Regulatory Frame and Outlook
The EU Green Deal and F-Gas Regulation shape European product standards by mandating interoperable communication protocols and restricting hazardous substances in meter electronics, while the FDA maintains indirect influence through electromagnetic compatibility requirements for meters deployed near medical facilities. India's BIS certification and CEA grid codes determine market access for foreign suppliers seeking participation in state-led smart metering programs. Stakeholders must monitor evolving cybersecurity mandates from ISO and IEC as utility regulators increasingly require embedded encryption and firmware update capabilities as baseline compliance conditions.
Market Dynamics
Utilities are replacing legacy electromechanical meters with digital two-way communication devices, compressing replacement cycles from decades to single-digit years as grid modernization mandates harden.
Growth Catalysts
- EU Green Deal mandates:European energy efficiency directives accelerate mandated rollouts across member states, creating predictable procurement pipelines for advanced metering infrastructure.
- India rural electrification:State-led smart metering programs and grid code enforcement by CEA expand addressable meter populations in underserved distribution territories.
- Cellular connectivity adoption:Rural and dispersed geographies deploy cellular-enabled meters where mesh alternatives face infrastructure gaps, unlocking previously unreachable service territories.
Market Restraints
- Semiconductor input volatility:Solid-state measurement components depend on specialized chip supply concentrated in East Asian foundries, exposing meter manufacturers to allocation risk.
- Cybersecurity compliance friction:ISO and IEC embedded encryption mandates require firmware architecture redesigns that extend development timelines and certification costs.
- Power Line Communication saturation:Dense urban environments leveraging existing electrical wiring for data backhaul face bandwidth constraints as meter density per transformer rises.
Strategic Opportunities
- Demand response integration:Commercial and industrial three-phase meter deployments enable power quality monitoring that justifies premium unit economics through value-added services.
- Thailand assembly expansion:Domestic manufacturing capacity growth across Southeast Asia reduces logistics costs for regional utility tenders and shortens fulfillment cycles.
- F-Gas substance restrictions:European hazardous substance limitations in meter electronics create first-mover advantage for suppliers with pre-qualified green component supply chains.
Industry Challenges
- Firmware engineering scarcity:Embedded systems talent with utility-grade cybersecurity expertise commands premium compensation, constraining development velocity for mid-tier suppliers.
- Interoperability certification delays:Multi-protocol compliance testing against divergent national grid codes extends time-to-revenue for new product introductions.
- Legacy system integration complexity:Head-end system compatibility with decades-old billing platforms requires custom middleware development that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Electric Meter Market |
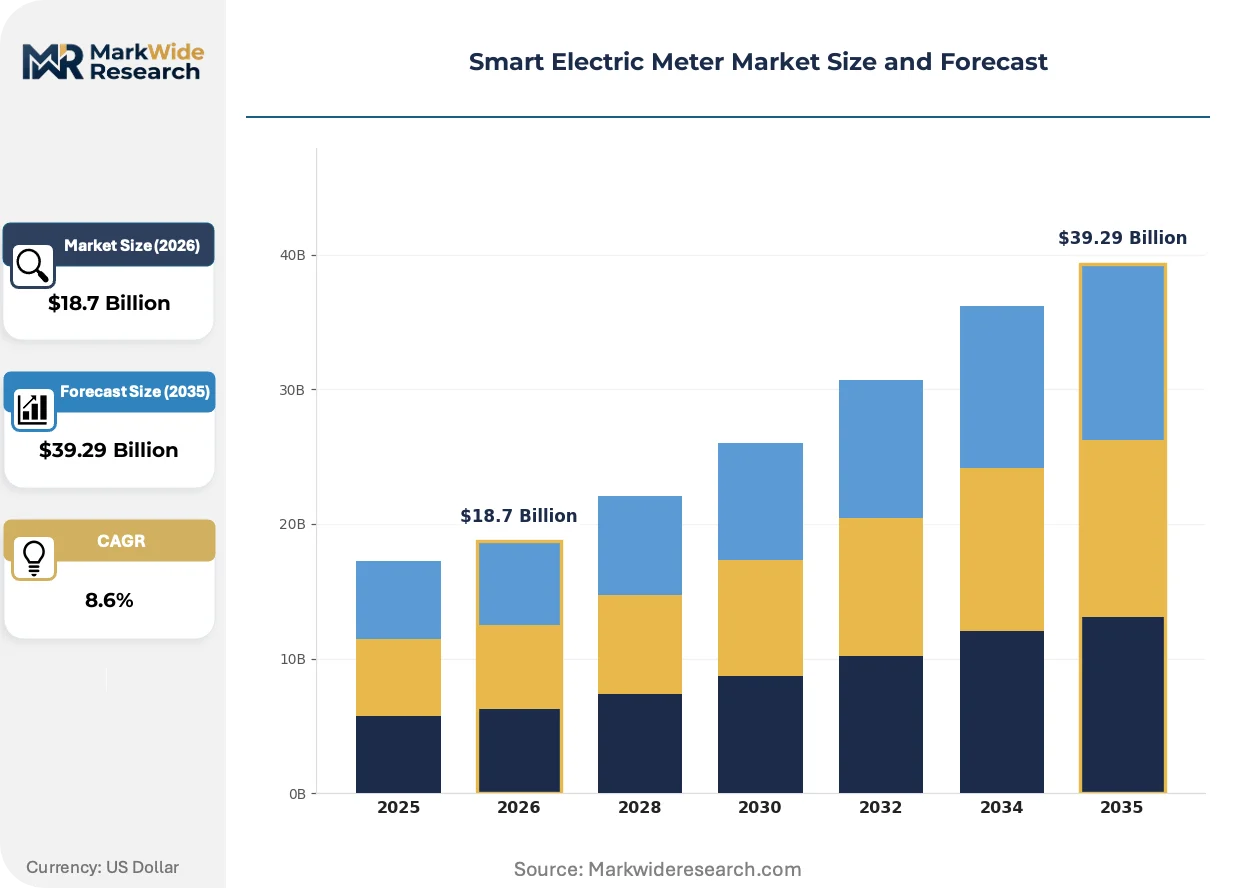
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase Meters, Three-Phase Meters, Smart Home Meters, Prepaid Meters Technology: Wi-Fi, Zigbee, Cellular, Power Line Communication End User: Residential, Commercial, Industrial, Utilities Deployment: Cloud-based, On-premises, Hybrid, Managed Service |
| Companies Covered | Landis+Gyr, Itron Inc., ABB Ltd., Siemens, General Electric, Schneider Electric, Honeywell International Inc., Wasion Group, Sagemcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Electric Meter Market Emerging Trajectories
Measurement accuracy classes and communication protocols are converging toward unified standards, compressing supplier differentiation while expanding addressable market scope for compliant hardware.
Edge computing capabilities embedded directly within meter firmware is collapsing the traditional separation between data acquisition and analytics processing. Large commercial and industrial buyers are specifying on-device load disaggregation and anomaly detection as baseline requirements. This compression eliminates separate gateway hardware procurement, reducing total installed cost while shifting value capture toward software-enabled service layers.
F-Gas Regulation amendments restrict fluorinated greenhouse gases in meter electronics manufacturing processes across European supply chains. The industrial consequence forces component suppliers to reformulate encapsulants and thermal interface materials. Meter assemblers serving EU utility tenders are responding with accelerated supplier qualification programs and dual-sourcing strategies for affected chemistries.
Utility procurement departments are unbundling hardware supply from installation and long-term data management services, fragmenting vendor relationships that previously ran through single-source contracts. Traditional full-service providers face disintermediation as specialized meter manufacturers, systems integrators, and SaaS analytics firms compete for discrete contract slices. This pattern is most visible in North American investor-owned utilities restructuring vendor management frameworks around tiered accountability.
Smart Electric Meter Market Segmentation
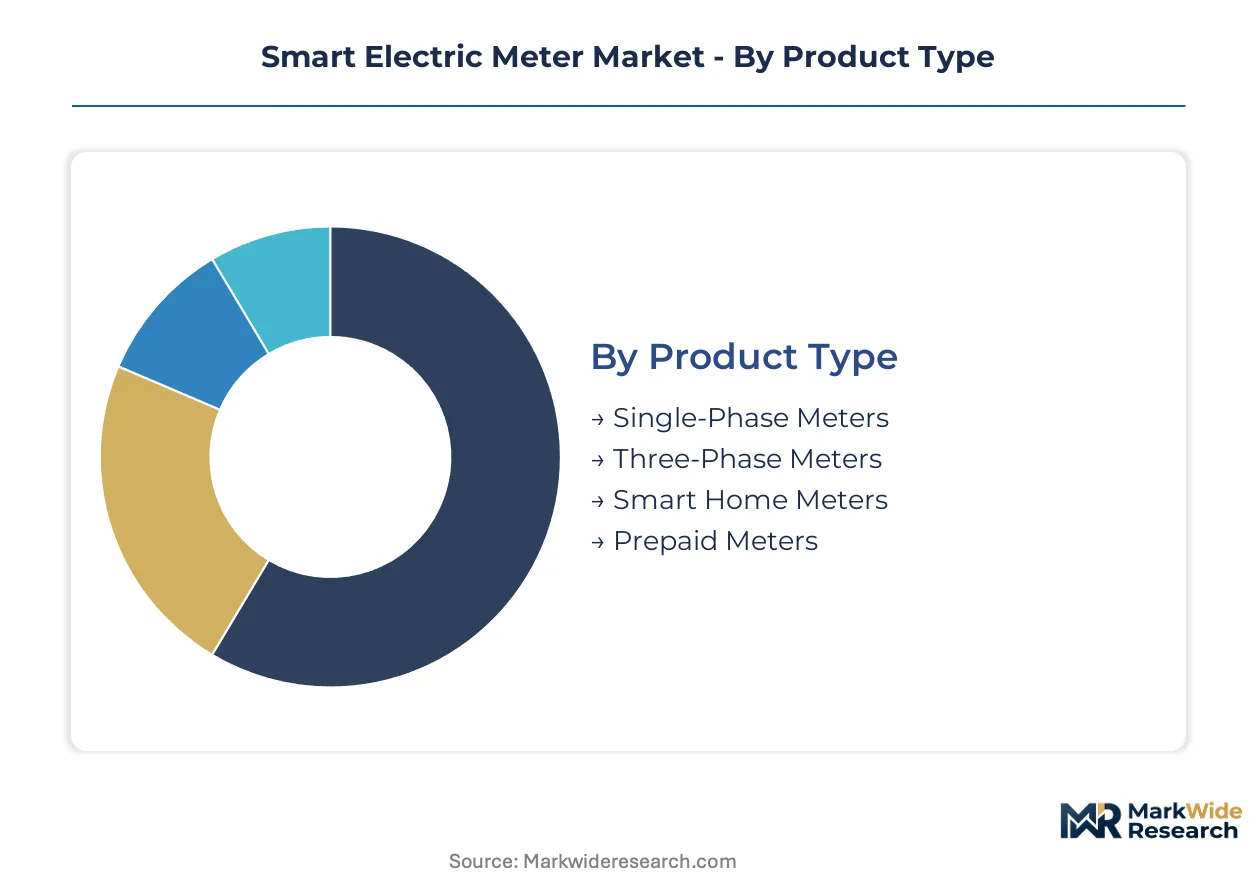
Smart electric meter procurement patterns diverge sharply across installation contexts, with residential mass deployments demanding streamlined logistics while industrial sites require embedded analytics and extended warranty structures. Understanding these segment boundaries enables suppliers to align firmware roadmaps, certification investments, and service attach rates with distinct buyer economics.
Product Type:
After-sales service intensity escalates from basic residential units to complex three-phase installations, with commercial and industrial deployments demanding multi-year maintenance contracts and remote diagnostic capabilities.
- Single-Phase Meters:These units incorporate solid-state measurement technology with accuracy classes of 0.2S to 1.0, designed for standard residential voltage levels. Demand concentrates in India's rural electrification programs and European replacement cycles, where state-led procurement mandates compress installation timelines and standardize communication protocols.
- Three-Phase Meters:Built for commercial and industrial power quality monitoring, these devices integrate demand response capabilities and harmonic distortion measurement. German utilities and Indian CEA grid code enforcement drive specification intensity, with premium unit economics justified through value-added energy management services.
- Smart Home Meters:Consumer-facing devices with in-home display integration and real-time consumption feedback for residential energy management.
- Prepaid Meters:Token-based or mobile-money-enabled units deployed in emerging markets with high collection risk and limited billing infrastructure.
By volume, single-phase meters lead. By growth pace, three-phase meters are gaining share fastest through industrial electrification and commercial building retrofits.
Technology:
Connectivity choice directly shapes hardware cost tiers, with cellular modules commanding premium positioning against mesh alternatives while Power Line Communication minimizes incremental infrastructure spend in dense urban deployments.
- Cellular:LTE-M and NB-IoT modules enable deployment in rural and dispersed geographies where mesh networks face infrastructure gaps. Indian utilities and North American cooperatives prioritize this technology for unreachable service territories, accepting higher unit costs to eliminate separate backhaul investment.
- Power Line Communication:Data transmission over existing electrical distribution wiring dominates European urban rollouts and dense Asian metropolitan deployments. Bandwidth constraints emerge as transformer-level meter density rises, forcing protocol upgrades and segment prioritization.
- Wi-Fi:Consumer-grade connectivity for smart home meter segments with existing residential internet infrastructure.
- Zigbee:Low-power mesh networking for neighborhood-area networks with utility-controlled gateway aggregation.
By installed base, Power Line Communication leads. By expansion trajectory, cellular is climbing the fastest as utilities target previously unserved territories.
End User:
Customer type determines procurement complexity, with residential programs running through centralized tenders and industrial buyers specifying custom integration with existing building management systems.
- Utilities:Centralized procurement of AMI infrastructure with 10-15 year service contracts and firmware update obligations. EU Green Deal mandates and Indian state-led programs concentrate demand, with interoperability certification against national grid codes determining vendor qualification.
- Industrial:Large commercial and manufacturing facilities specifying on-device load disaggregation and power quality analytics. German industrial clusters and Southeast Asian manufacturing corridors drive specification intensity, with premium pricing justified through energy cost reduction and demand charge management.
- Residential:Mass-market replacement cycles with standardized specifications and compressed installation timelines.
- Commercial:Mid-size building deployments balancing metering accuracy with integration flexibility for multi-tenant billing.
By contract value, utilities lead. By margin expansion, industrial is expanding most quickly through software-enabled service layers.
Deployment:
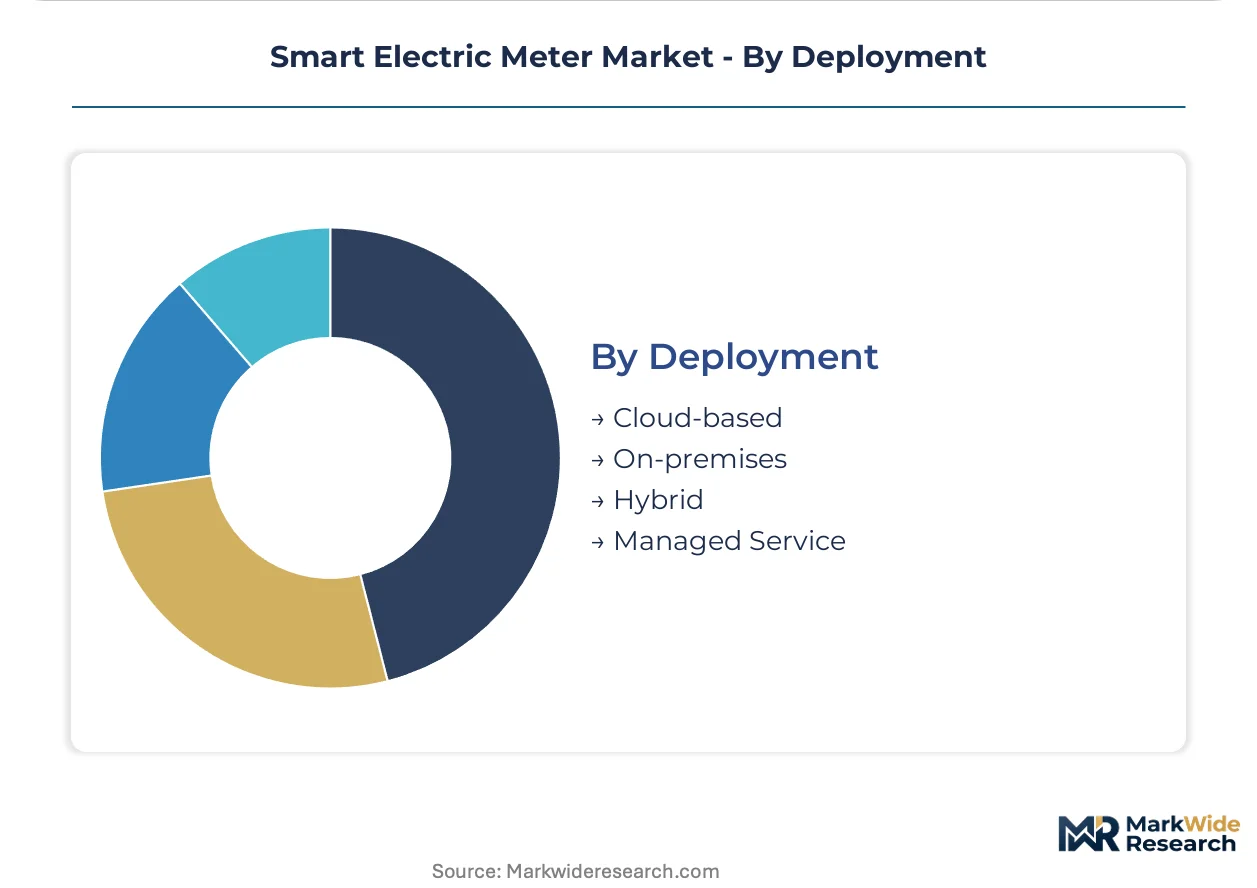
Delivery model selection reflects IT maturity and regulatory data sovereignty requirements, with European utilities favoring hybrid architectures and emerging markets accepting managed services to bridge capability gaps.
- Cloud-based:Scalable data aggregation with utility-specific tenant isolation and regional data residency compliance. EU GDPR requirements and Indian data localization mandates shape vendor selection, with European tenders requiring EU-based processing infrastructure.
- Managed Service:End-to-end outsourcing of meter operations, data management, and billing integration. Southeast Asian utilities and North American cooperatives adopt this model to access specialized expertise without internal IT expansion, accepting recurring fee structures over capital ownership.
- On-premises:Utility-controlled head-end systems for data sovereignty and legacy billing platform integration.
- Hybrid:Mixed architectures with edge processing for time-critical functions and cloud aggregation for analytics.
By new contract volume, cloud-based leads. By adoption velocity, managed service is gaining share fastest as utilities unbundle vendor relationships and seek operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEA grid code enforcement anchors Indian procurement intensity, while EU Green Deal mandates and F-Gas Regulation compliance reshape European vendor qualification standards across national utility tenders.
United States
Investor-owned utilities compress replacement cycles from decades to single-digit years as FERC grid modernization directives harden. State-level renewable portfolio standards in California and Texas accelerate AMI procurement for distributed solar integration. The Southeast manufacturing corridor expands domestic assembly capacity to shorten fulfillment cycles for cooperative utilities.
Germany
Industrial electrification and commercial building retrofits drive three-phase meter specification intensity. EU Green Deal energy efficiency directives mandate interoperable communication protocols for nationwide rollout completion. Bavarian industrial clusters specify on-device load disaggregation as baseline for demand charge management contracts.
India
Rural electrification programs and state-led smart metering initiatives expand addressable meter populations in underserved distribution territories. BIS certification and CEA grid code enforcement determine market access for foreign suppliers seeking participation. Maharashtra and Gujarat concentrate manufacturing investment for cost-optimized production platforms.
China
Dual carbon goals and MIIT smart grid investment targets accelerate domestic meter deployment at utility scale. GB standards for electromagnetic compatibility and data security shape product architecture for both domestic consumption and export manufacturing. Yangtze River Delta electronics clusters supply solid-state measurement components to regional meter assemblers.
Thailand
Domestic assembly capacity expansion reduces logistics costs for Southeast Asian utility tenders and shortens fulfillment cycles. Government smart city initiatives in Bangkok Metropolitan Region drive cellular-enabled meter procurement for dense urban deployment. Eastern Economic Corridor manufacturing zones attract regional headquarters for Asia-Pacific supply chain coordination.
Smart Electric Meter Market Vendor Landscape
Capability concentration sits with full-service infrastructure providers; scale advantage sits with cost-optimized hardware fabricators. The vendor base organizes around three strategic archetypes: Swiss-engineered premium-tier specialists, North American managed services integrators, and Asia-Pacific volume manufacturers. Consolidation pressure intensifies as utilities unbundle hardware supply from installation and data management, fragmenting vendor relationships that previously ran through single-source contracts. Dominant competitive moves include geographic expansion into Southeast Asian assembly corridors and portfolio diversification toward software-enabled service layers.
Among Swiss-engineered specialists, Landis+Gyr exemplifies the premium-tier archetype through European utility tender dominance. Itron Inc. occupies a position within the North American managed services tier, sustaining market presence through deep utility relationships. Wasion Group anchors the Asia-Pacific volume manufacturing tier, leveraging cost-optimized production platforms and regional certification breadth to supply state-led procurement programs across India and Southeast Asia.
| Leading Market Players |
|---|
| Landis+Gyr |
| Itron Inc. |
| ABB Ltd. |
| Siemens |
| General Electric |
| Schneider Electric |
| Honeywell International Inc. |
| Wasion Group |
| Sagemcom |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta freight corridors transmit semiconductor cost volatility directly into meter hardware pricing tiers, compressing margins for volume manufacturers while Swiss-engineered specialists preserve premium positioning through certification-grade differentiation and after-sales bundling.
Pricing Analysis
Cellular-enabled meters in rural India and North American cooperatives command 15-25% premiums over Power Line Communication equivalents in dense European urban deployments. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified industrial units with embedded analytics from basic residential single-phase meters. Cost compression in the cellular module tier is intensifying because NB-IoT chipset supply concentrates in East Asian foundries. Utilities represent the least price-sensitive buyer segment through long-term service contracts, while state-led procurement programs in emerging markets exhibit acute sensitivity to unit economics.
Supply Chain Analysis
Specialized analog front-end integrated circuits and secure microcontroller units draw from Taiwan, South Korea, and China's Yangtze River Delta electronics clusters. Meter assemblers source solid-state measurement components, cellular communication modules, and encapsulant materials from these concentrated manufacturing hubs. Single-source vulnerability in advanced node semiconductor fabrication exposes procurement timelines to allocation risk during capacity crunches. Distribution runs through direct utility tender channels in regulated markets and systems integrator partnerships in unbundled procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as utilities unbundle hardware supply from installation and data management, fragmenting vendor relationships that previously ran through single-source contracts and forcing suppliers to compete for discrete procurement slices.
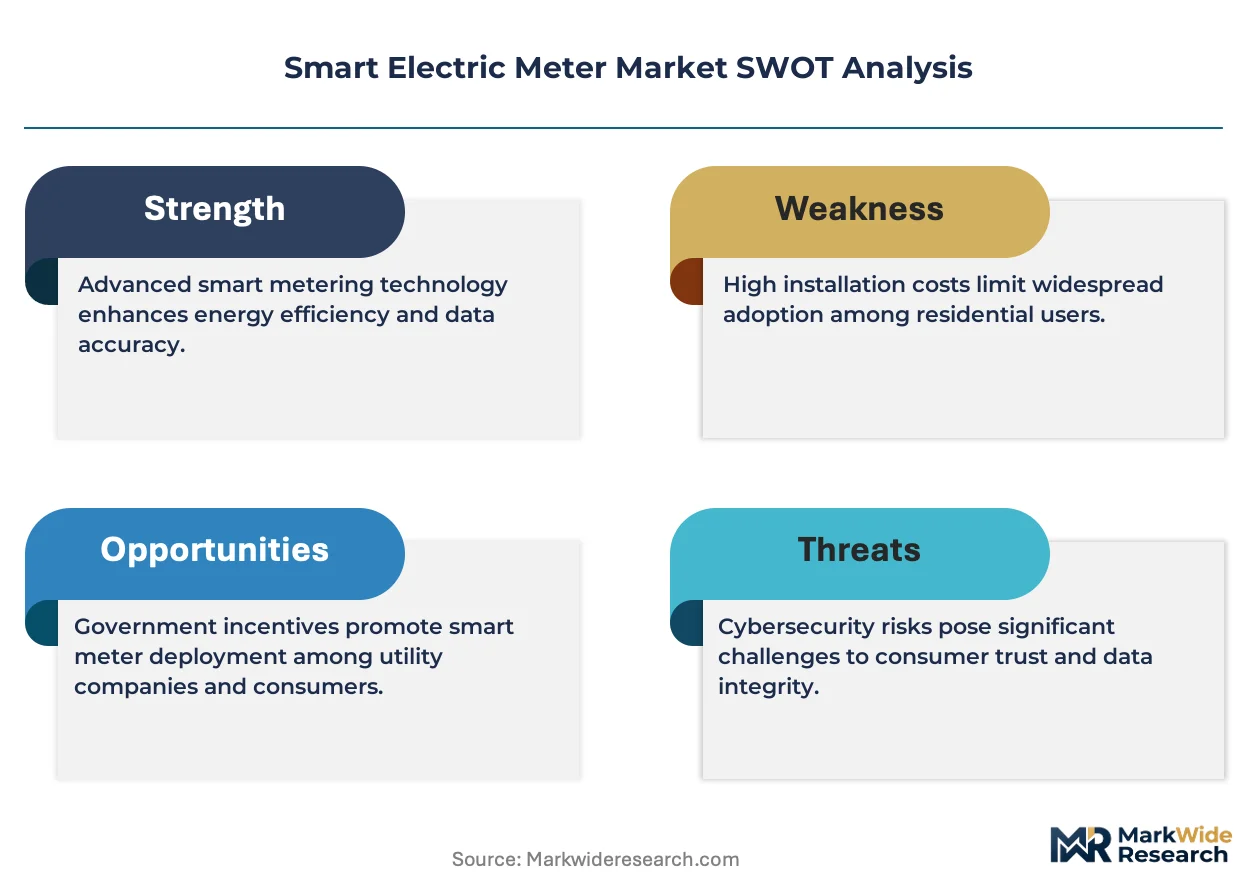
For Market Incumbents: Insulate service revenue streams by embedding firmware update obligations and cybersecurity certification into long-term utility contracts. Deepen backward integration into secure microcontroller supply through strategic foundry partnerships or captive wafer capacity commitments. Emerging SaaS analytics firms threaten disintermediation of traditional full-service providers.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asian manufacturing corridors represent the most penetrable entry point, with Thai and Vietnamese utilities seeking cellular-enabled three-phase meters for industrial electrification programs. Prepaid meter deployments in African and South Asian markets with limited billing infrastructure offer second-mover advantage through mobile-money integration partnerships.
For Investors and Strategic Acquirers: Firmware engineering boutiques with utility-grade cybersecurity expertise and embedded systems talent command scarcity premiums in a market where ISO and IEC compliance mandates are hardening. Long-term viability hinges on software-enabled service layer capture rather than hardware commoditization. Watch for CEA grid code enforcement intensity in India as inflection indicator for state-led procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Supply | Captive wafer capacity secures allocation priority during East Asian foundry crunches. |
| Cellular Module Certification Investment | LTE-M and NB-IoT carrier approvals unlock rural utility tenders in India and North America. |
| Demand Response Platform Development | Software-enabled load disaggregation captures premium pricing from German industrial clusters. |
| Southeast Asian Assembly Expansion | Thailand and Vietnam manufacturing reduces logistics costs for regional procurement programs. |
| F-Gas Compliant Component Qualification | Green chemistry pre-certification secures first-mover advantage in EU utility tenders. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility procurement officers, AMI program managers, meter manufacturer product directors, and systems integrator executives. Secondary validation drew from FERC grid modernization filings, EU Green Deal implementation reports, CEA smart metering directives, and customs trade data for solid-state measurement component flows. Bottom-up unit economics triangulated against top-down addressable market sizing across single-phase, three-phase, and smart home meter categories.
Calibration against historical deployment trajectories in Germany, India, and the United States anchored growth rate derivation across the projection horizon. Segmentation dimensions modeled include product type, communication technology, end-user archetype, and deployment architecture, with regional regulatory framework clusters as an industry-specific overlay. CAGRs were computed from installed base expansion and replacement cycle compression, incorporating utility capital expenditure patterns and state-led program commitments as forecast inputs.
Stress conditions across semiconductor allocation severity, cybersecurity mandate acceleration, and utility unbundling velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding replacement cycle timing and procurement program execution. Cross-checking against IEA smart grid investment databases and national utility regulatory filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Residential Water Submetering Market
Smart Meters
Digital Water Meters Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
Power Metering Market
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
US Smart Meter Data Management Market
Smart Meters
Smart Metering Systems Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Global Smart Water Meter Market
Smart Meters
Home Energy Monitor Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
US Water Meter Market
Smart Meters
Residential Smart Water Metering Market