

Residential Smart Water Metering Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Smart Water Metering Market Insights
Pay-as-you-go leasing and meter-as-a-service financing is fragmenting capital barriers for mid-sized water districts and property managers. Xylem leverages its integrated software-hardware platform to anchor long-term service contracts across North American utilities. Kamstrup competes through ultrasonic R&D intensity and closed-loop manufacturing in Denmark. Badger Meter specializes in cellular endpoints and cloud analytics, extending its reach into homeowner association-managed properties.
Residential smart water metering encompasses networked flow measurement devices with integrated radio-frequency or cellular transceivers, pressure sensors, and tamper-detection algorithms that transmit consumption data at intervals ranging from hourly to near-real-time. These systems enable automated billing, leak identification, and demand-response programs for water utilities and property operators. Ultrasonic meter types are displacing mechanical equivalents in new-build applications due to zero moving parts and extended calibration stability. RF mesh connectivity technology dominates North American deployments where utility-owned infrastructure supports multi-hop networks, while NB-IoT adoption accelerates in European markets with established cellular coverage obligations. Single-family units represent the largest application segment by installed base, though multi-family complexes offer higher per-site revenue density for advanced submetering configurations.
EPA regulations under the Safe Drinking Water Act and the Lead and Copper Rule Revision shape meter replacement timelines and material specifications for U.S. utilities. The EU Water Framework Directive and national implementations such as Germany's TrinkwV establish quality monitoring obligations that drive connected infrastructure investment. California's SB 606 water efficiency mandates and Australia's National Water Initiative compliance frameworks add jurisdiction-specific procurement pressures. Stakeholders must weigh cellular versus mesh technology commitments against evolving cybersecurity standards and utility balance-sheet constraints.
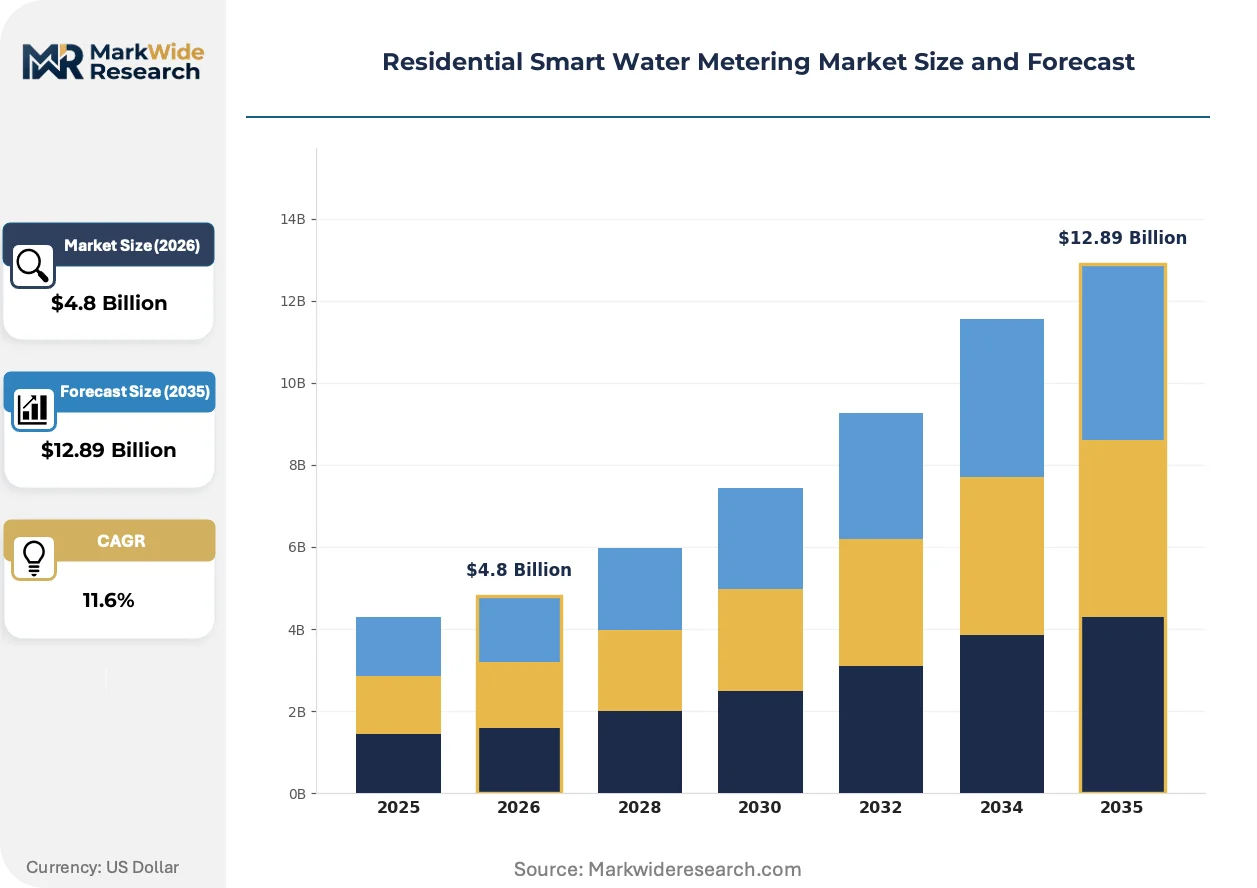
Market Dynamics
Meter-as-a-service financing is dissolving capital barriers for mid-sized utilities, converting upfront hardware procurement into operational expenditure streams that accelerate replacement cycles.
Growth Catalysts
- EPA Lead and Copper Rule Revision:U.S. utilities face mandated infrastructure audits and replacement timelines, forcing systematic meter upgrades in lead service line corridors across Michigan, Illinois, and Ohio.
- Ultrasonic measurement cores:Zero-moving-part designs eliminate mechanical wear and extend calibration intervals, reducing field service costs for utilities managing dispersed rural networks.
- Germany:The TrinkwV implementation of EU Water Framework Directive monitoring obligations requires real-time quality data transmission, driving RF mesh and NB-IoT endpoint installations in Bavaria and North Rhine-Westphalia.
Market Restraints
- Cellular module supply concentration:NB-IoT and LTE-M chipset fabrication concentrates among three semiconductor foundries, creating procurement bottlenecks for European meter OEMs.
- Copper and rare earth magnet costs:Mechanical meter production still depends on neodymium magnet assemblies and brass castings subject to commodity price volatility.
- Cybersecurity certification delays:IEC 62443 compliance timelines for industrial IoT devices extend product launch windows by 8-14 months in regulated European markets.
Strategic Opportunities
- Australia National Water Initiative compliance:Murray-Darling Basin water accounting reforms create demand for sub-hourly telemetry in agricultural-residential interface zones.
- AI-driven leak detection convergence:Pressure transient analysis algorithms fused with ultrasonic flow signatures enable predictive pipe failure models.
- Homeowner association channel development:Multi-family submetering bypasses traditional utility procurement, accessing California and Texas HOAs directly through certified installer networks.
Industry Challenges
- RF engineering talent scarcity:Utility-scale mesh network deployment requires specialized field engineers capable of propagation modeling and interference mitigation in dense urban RF environments.
- Legacy AMR system integration:Drive-by radio endpoints from 2005-2015 installations lack firmware upgrade paths, forcing parallel infrastructure operation during transition periods.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Smart Water Metering Market Trends and Innovations
Measurement technology, connectivity protocols, and procurement structures are simultaneously transforming how water data flows from household tap to utility billing system.
Ultrasonic transit-time measurement is migrating from premium new-build specifications to standard retrofit configurations. California water districts now specify solid-state cores for all replacement programs exceeding 5,000 units annually. The technology is migrating from high-value coastal municipalities to inland agricultural counties where extended calibration stability justifies higher unit costs.
California's SB 606 water efficiency mandates establish per-capita consumption targets that require granular household-level data. Utilities must demonstrate progress toward 55 gallons per person per day thresholds by 2030. Single-family retrofits in Los Angeles and San Diego counties now dominate procurement volumes, compressing installation contractor availability.
Financing structures now separate hardware ownership from data service provision. Mid-sized districts in Texas and Arizona lease endpoint estates through 10-year service agreements rather than capitalizing assets. Property managers of garden-style apartment complexes represent the fastest-adopting buyer segment, bypassing traditional municipal procurement cycles entirely.
Residential Smart Water Metering Market Segmentation
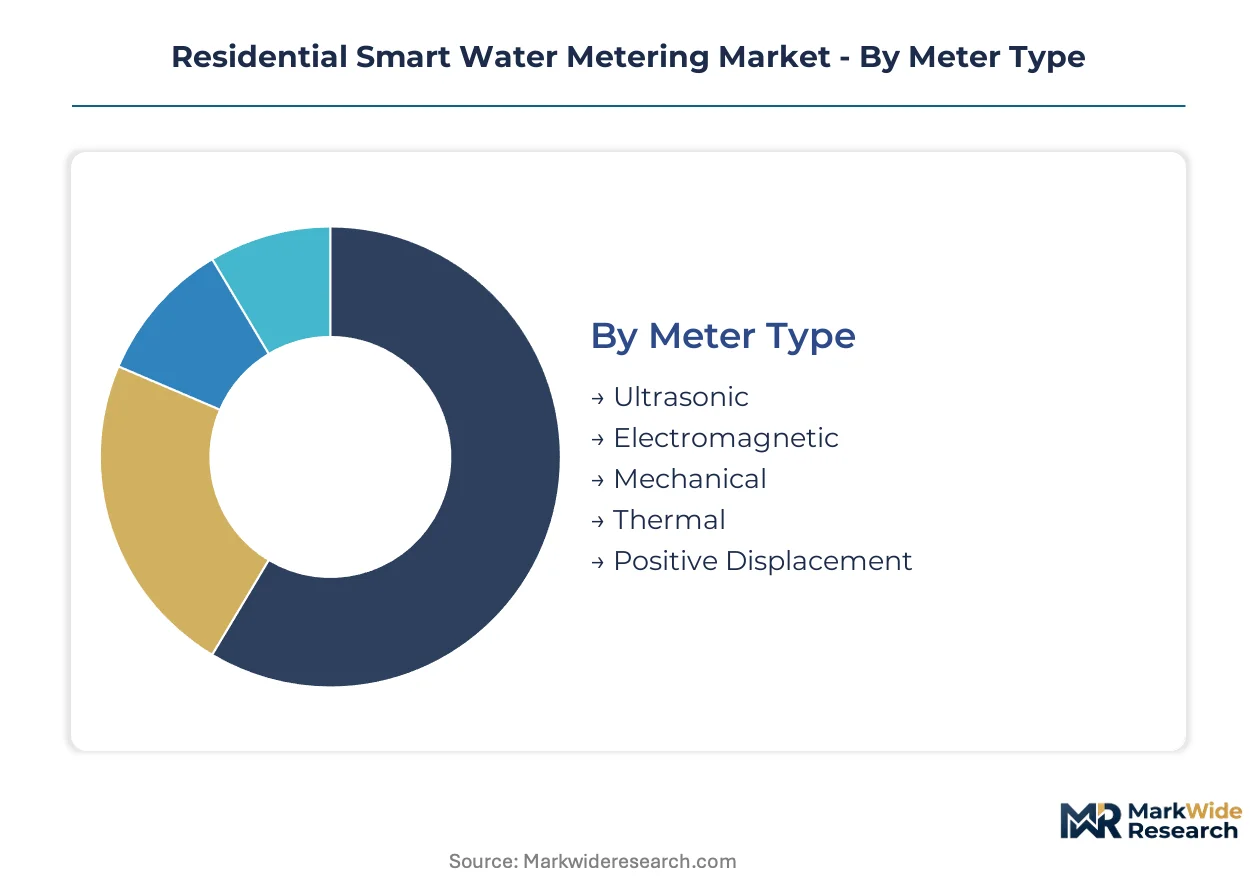
Segmentation in residential smart water metering reveals how technology maturity, connectivity economics, and property typology intersect to shape procurement patterns. Vendors must align product configurations with distinct buyer capabilities—from capital-constrained homeowner associations to regulated municipal utilities.
Meter Type:
Maturity varies sharply across measurement principles, with solid-state designs displacing mechanical cores in premium retrofit programs.
- Ultrasonic:Transit-time measurement employs piezoelectric transducers to calculate flow velocity without moving parts. Bavarian utilities and California water districts specify these cores for lead-corridor replacements, accepting 40-60% unit cost premiums in exchange for 15-year calibration stability and leak signature detection.
- Mechanical:Multi-jet and turbine designs retain dominance in emerging-market bulk procurement and price-sensitive North American rural cooperatives. Brass-bodied variants face EPA lead-content scrutiny, accelerating specification switches to polymer-composite housings in Michigan and Ohio replacement cycles.
- Electromagnetic:Faraday-effect measurement suits high-solids irrigation and reclaimed water applications where magnetic flow immunity matters.
- Thermal:Heat-based mass flow detection serves niche submetering in district heating-coupled residential blocks across Denmark and Sweden.
- Positive Displacement:Oscillating piston and nutating disc mechanisms persist in legacy AMR upgrade paths where utilities prioritize firmware compatibility over measurement advance.
Mechanical meters retain volume leadership in absolute unit shipments; ultrasonic designs hold the steepest expansion curve across replacement programs.
Connectivity Technology:
Cost tier stratification separates utility-owned infrastructure from carrier-dependent subscription models.
- RF Mesh:Multi-hop radio networks leverage 900 MHz ISM band spectrum with self-healing topology. North American municipal utilities in Texas and Arizona favor this architecture for its zero recurring carrier fees and 10-year total cost advantages over cellular in high-density suburban deployments.
- NB-IoT:Narrowband cellular operates in licensed spectrum with deep indoor penetration. German TrinkwV compliance deadlines and French utility consolidation drive endpoint procurement, though semiconductor supply concentration creates 6-9 month delivery volatility.
- Cellular:LTE-M endpoints suit remote single-family installations beyond mesh range, particularly in Australian Murray-Darling interface zones.
- Low Power Wide Area Network:Proprietary unlicensed protocols serve private campus networks at university housing and military installations.
- Zigbee:2.4 GHz mesh supports home-area network integration for consumer-facing leak alert applications, though utility-scale adoption remains limited.
RF Mesh dominates North American installed base; NB-IoT is climbing the fastest in European compliance-driven tenders.
Application:
Customer type dictates revenue density and installation logistics, with multi-family configurations offering per-site economies.
- Single-Family Units:Detached residential structures represent the largest addressable base by unit count. California SB 606 mandates concentrate retrofit demand in Los Angeles and San Diego counties, where contractors face compressed availability and 12-16 week project backlogs.
- Multi-Family Complexes:Garden-style apartments and mid-rise buildings enable submetering bypass of municipal billing. Texas and Arizona property managers adopt meter-as-a-service financing most aggressively, converting capital expenditure to operational leases.
- Vacation Homes:Seasonal occupancy patterns in Florida and Arizona drive demand for remote leak detection and automated shutoff capabilities.
- Low-Rise Buildings:Three-to-five-story walk-ups in older European city centers present RF propagation challenges that favor NB-IoT over mesh alternatives.
Single-Family Units retain volume leadership; Multi-Family Complexes hold the steepest expansion curve through submetering channel development.
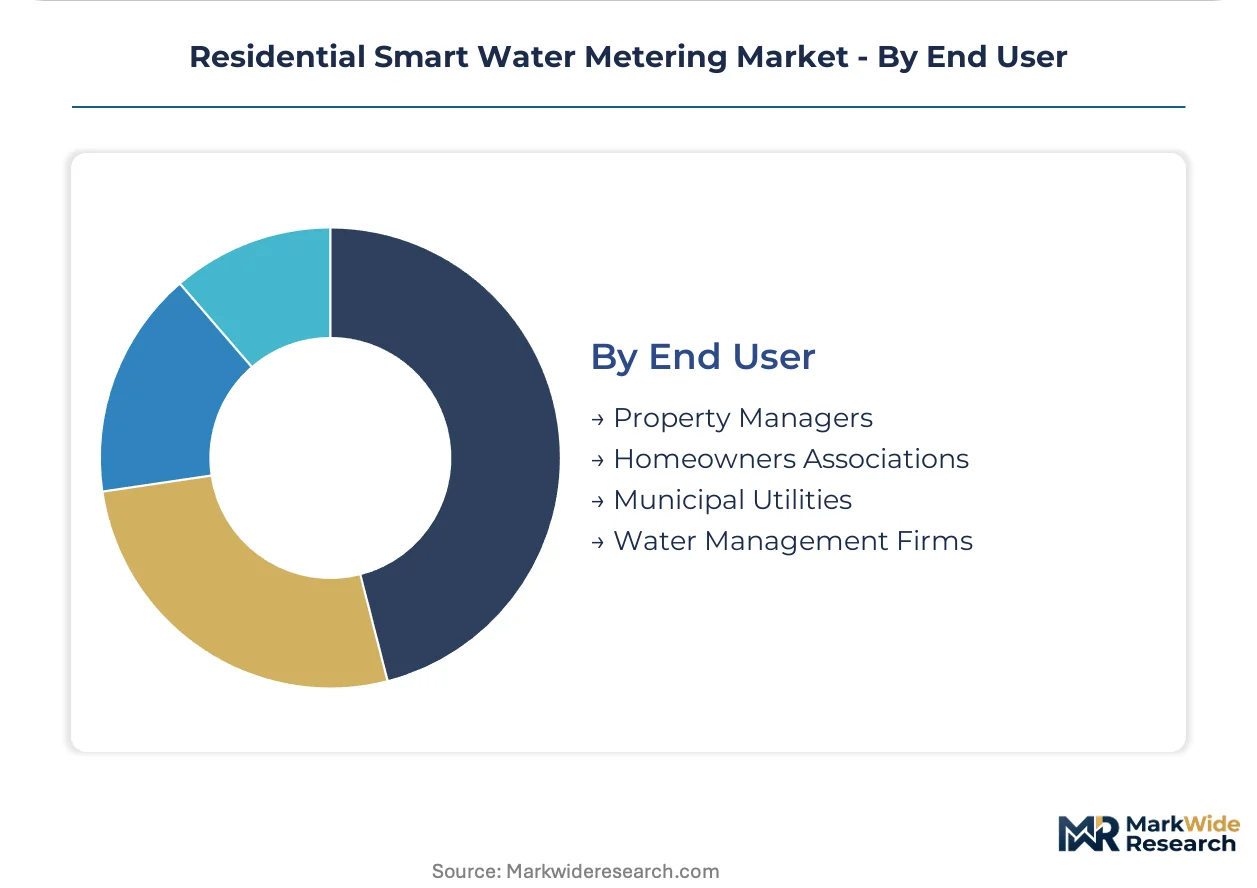
End User:
Procurement authority fragmentation creates parallel sales motions—regulated RFP processes versus direct property manager contracting.
- Municipal Utilities:Public-sector water authorities operate under EPA and state regulatory compliance timelines. Michigan, Illinois, and Ohio utilities accelerate replacement cycles under Lead and Copper Rule Revision mandates, with procurement governed by sealed bidding and prevailing wage requirements.
- Property Managers:Private-sector operators of garden-style and mid-rise residential assets bypass traditional utility procurement. Certified installer networks in California and Texas access this segment through 10-year service agreements rather than capital sales.
- Homeowners Associations:Collective governance structures in planned communities represent the fastest-adopting buyer segment for submetering retrofits, particularly in water-stressed Texas Hill Country and Arizona desert metros.
- Water Management Firms:Third-party operators of concession contracts—common in French and British municipal outsourcing—specify integrated hardware-software platforms with guaranteed uptime service levels.
Municipal Utilities retain volume leadership; Property Managers hold the steepest expansion curve through financing innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Lead and Copper Rule Revision mandates are accelerating meter replacement cycles across lead service line corridors, while EU Water Framework Directive enforcement drives connected infrastructure procurement in German and French utilities.
United States
California SB 606 water efficiency mandates establish per-capita consumption thresholds that require granular household-level data transmission. The EPA Lead and Copper Rule Revision forces systematic infrastructure audits across Michigan, Illinois, and Ohio. Los Angeles and San Diego counties concentrate single-family retrofit demand, compressing installation contractor availability to 12-16 week backlogs.
Germany
TrinkwV implementation of EU Water Framework Directive monitoring obligations requires real-time quality data transmission from distribution networks. Bavarian and North Rhine-Westphalia utilities specify ultrasonic cores for lead-corridor replacements, accepting 40-60% unit cost premiums. Industrial metering clusters in Munich and Düsseldorf anchor RF mesh and NB-IoT endpoint procurement volumes.
Australia
Murray-Darling Basin water accounting reforms create demand for sub-hourly telemetry in agricultural-residential interface zones. The National Water Initiative compliance frameworks add jurisdiction-specific procurement pressures for connected meters. Sydney and Melbourne utilities concentrate cellular endpoint deployments for remote single-family installations beyond mesh range.
France
Utility consolidation and concession contract restructuring drive integrated hardware-software platform specifications. ANSM quality monitoring obligations intersect with EU Water Framework Directive enforcement to accelerate connected infrastructure investment. Paris and Lyon metropolitan utilities concentrate NB-IoT adoption with established cellular coverage obligations.
United Kingdom
Ofwat regulatory pressure on leakage reduction targets forces systematic network monitoring upgrades across Thames Water and Anglian Water territories. The Environment Agency's abstraction licensing reforms create demand for granular consumption data. London and Southeast England concentrate smart meter pilot programs with pressure transient analysis capabilities.
Residential Smart Water Metering Market Competitive Landscape
Channel-controlling players compete with product-specialist players across financing, connectivity, and measurement technology vectors. The vendor base stratifies between integrated platform providers, component specialists, and regional system integrators. Three archetypes dominate: hardware-software bundlers anchoring long-term service contracts, ultrasonic measurement specialists competing on calibration stability, and cellular connectivity providers extending cloud analytics reach. M&A activity concentrates on software capability acquisition, while strategic partnerships address semiconductor supply concentration risks.
Among integrated platform providers, Xylem and Itron occupy positions that exemplify the hardware-software bundler archetype. Kamstrup represents the measurement-specialist tier with Danish manufacturing origins. Badger Meter sits within the cellular-first connectivity segment. These three anchors illustrate how competitive positioning fragments across financing innovation, ultrasonic R&D intensity, and cloud analytics extension rather than consolidating around a single dominant model.
| Leading Market Players |
|---|
| Itron |
| Xylem |
| Badger Meter |
| Landis+Gyr |
| Diehl Metering |
| Kamstrup |
| Neptune Technology Group |
| Aclara |
| ZENNER International |
| Others |
Pricing and Supply Chain Analysis
Semiconductor foundry concentration in Taiwan and South Korea for NB-IoT and LTE-M chipsets anchors margin pools with cellular module suppliers, forcing European meter OEMs to absorb 6-9 month delivery volatility through inventory carrying costs or premium spot purchasing.
Pricing Analysis
Certification level creates the primary spread between IEC 62443-compliant industrial IoT endpoints and standard commercial-grade hardware. Three-tier pricing structure across premium, standard, and economy levels reflects cybersecurity compliance investment, with TrinkwV-mandated German utilities absorbing 40-60% premiums for ultrasonic cores with embedded pressure sensors. Pricing pressure stems from commodity volatility in neodymium magnet and brass casting inputs for mechanical meter production. Municipal utilities exhibit highest price sensitivity due to prevailing wage requirements and sealed-bid procurement, while homeowner associations demonstrate lowest sensitivity through meter-as-a-service operational expenditure conversion.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now characterize supplier-finance relationships for mid-sized meter OEMs seeking working capital relief. Manufacturing concentrates in Denmark, Germany, and China for ultrasonic transducer assemblies, polymer-composite housings, and RF antenna modules. Raw material dependencies center on piezoelectric ceramics, brass and polymer feedstocks, and licensed cellular modem chipsets. Single-source vulnerability in semiconductor foundry capacity represents the dominant structural risk. Distribution runs through certified installer networks for property manager segments and municipal procurement offices for utility direct sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
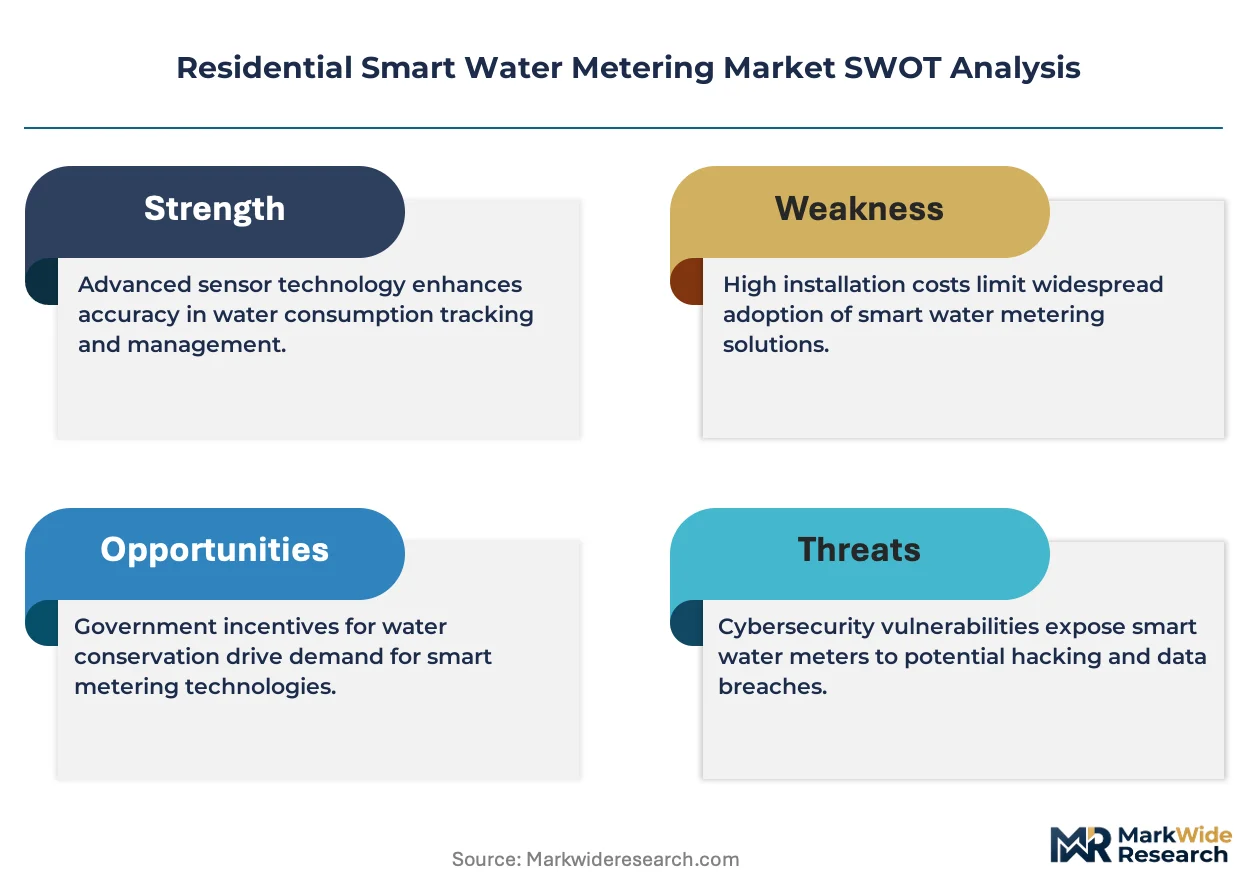
RF engineering talent scarcity constrains deployment velocity for utility-scale mesh networks, creating a capability gap that separates vendors with captive field teams from those dependent on contractor markets.
For Market Incumbents: Pre-empt ultrasonic R&D obsolescence by accelerating pressure-transient algorithm development before AI-driven leak detection converges into platform-standard features. Consolidate backward integration into piezoelectric transducer supply through long-term offtake agreements with Danish and German ceramic foundries, neutralizing semiconductor supply concentration risks that threaten cellular endpoint margins.
For New Entrants and Emerging Players: Australian Murray-Darling Basin agricultural-residential interface zones offer the most penetrable geography for sub-hourly telemetry solutions bypassing established utility procurement channels. Texas Hill Country homeowner associations represent the fastest-adopting buyer archetype for submetering retrofits. Pursue certified installer network partnerships rather than direct municipal RFP competition to compress customer acquisition timelines.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed meter-as-a-service platforms holding 10-year municipal lease portfolios. Long-term viability hinges on software recurring revenue attachment rates exceeding hardware depreciation schedules. Monitor IEC 62443 certification completion timelines as the critical inflection signal for European market access and margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Measurement Core Development | Solid-state transit-time designs displace mechanical meters in California SB 606 compliance corridors. |
| NB-IoT Connectivity Platform Integration | German TrinkwV mandates accelerate licensed-spectrum endpoint procurement in Bavaria and North Rhine-Westphalia. |
| Meter-as-a-Service Financing Launch | Operational expenditure conversion unlocks homeowner association and property manager segments in Texas and Arizona. |
| AI-Driven Leak Detection Algorithm Deployment | Pressure transient analysis fused with ultrasonic signatures enables predictive pipe failure models for utilities. |
| Certified Installer Network Expansion | Channel control bypasses municipal procurement cycles to access multi-family submetering demand directly. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, RF network engineers, property management executives, and certified installation contractors; and secondary validation against EPA enforcement records, EU Water Framework Directive implementation reports, state-level procurement databases, and utility capital improvement disclosures. Bottom-up endpoint shipment estimates triangulated against top-down infrastructure replacement spend projections.
Forecast inputs considered meter type migration curves, connectivity protocol adoption rates across regional regulatory clusters, and financing structure penetration by end-user archetype. Segmentation dimensions modeled include measurement technology, connectivity infrastructure, property typology, and procurement authority. CAGRs derived from replacement cycle acceleration under Lead and Copper Rule Revision timelines and TrinkwV compliance deadlines.
Practitioners should monitor semiconductor foundry capacity utilization, EPA enforcement variance across lead service line corridors, and IEC 62443 certification backlog durations for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.