
 United States (US) Water Meter Market | 2026-2036
United States (US) Water Meter Market Size, Share, and Industry Trends Forecast 2026-2036
United States (US) Water Meter Market Analytics
Consolidation among municipal water utilities is realigning procurement power toward larger metropolitan water districts with centralized AMI deployment budgets. Badger Meter, Inc. leverages its vertically integrated manufacturing footprint in Wisconsin to sustain competitive delivery timelines for smart meter rollouts. Mueller Systems, LLC anchors its position through deep relationships with mid-sized municipal buyers across the Midwest and Southeast. Kamstrup Water Metering LLC differentiates via ultrasonic technology leadership that competes directly against traditional mechanical incumbents.
A United States water meter is a precision flow measurement instrument engineered to quantify potable water consumption across residential, commercial, and industrial service connections, typically operating within pressure ranges of 150 psi and temperature tolerances from 33°F to 100°F to ensure accurate volumetric recording under variable distribution conditions. Its primary commercial purpose centers on revenue-grade billing accuracy, leak detection, and demand-side management for water utilities managing aging distribution infrastructure. Smart meters now command the fastest-growing product category as utilities prioritize real-time data transmission and remote shutoff capabilities over legacy mechanical units with limited telemetry. AMI technology dominates new installation specifications, while electromagnetic segments occupy specialized industrial and bulk-flow applications where minimal head loss and corrosion resistance justify premium positioning.
The EPA enforces Safe Drinking Water Act standards that directly mandate lead-free meter components and accuracy certification protocols, while the AWWA publishes C700-C715 standards governing meter performance tolerances and testing methodologies that shape manufacturer compliance costs. State-level public utility commissions in California, Texas, and Florida increasingly require AMI readiness as a condition of rate-case approvals, forcing accelerated capital replacement cycles. Stakeholders must monitor evolving cybersecurity frameworks from NIST and state regulators as networked meter infrastructure expands attack surfaces beyond traditional mechanical vulnerabilities.
Market Dynamics
The EPA's Lead and Copper Rule revisions are forcing municipal utilities to accelerate replacement cycles for legacy brass-bodied meters, compressing procurement timelines and favoring AMI-ready suppliers with certified lead-free manufacturing capabilities.
Growth Catalysts
- California Drought Emergency Mandates:The state's public utility commission requires AMI readiness for all rate-case approvals, compelling water districts in Los Angeles and San Diego to prioritize smart meter capital expenditures.
- Texas Infrastructure Modernization:The Texas Water Development Board channels state revolving fund dollars toward non-revenue water reduction programs, directly funding ultrasonic and electromagnetic meter conversions in Houston and Dallas metropolitan districts.
- Ultrasonic Flow Measurement:Solid-state meters eliminate moving parts, cutting maintenance costs by half and extending operational lifespans beyond twenty years in hard-water environments.
Market Restraints
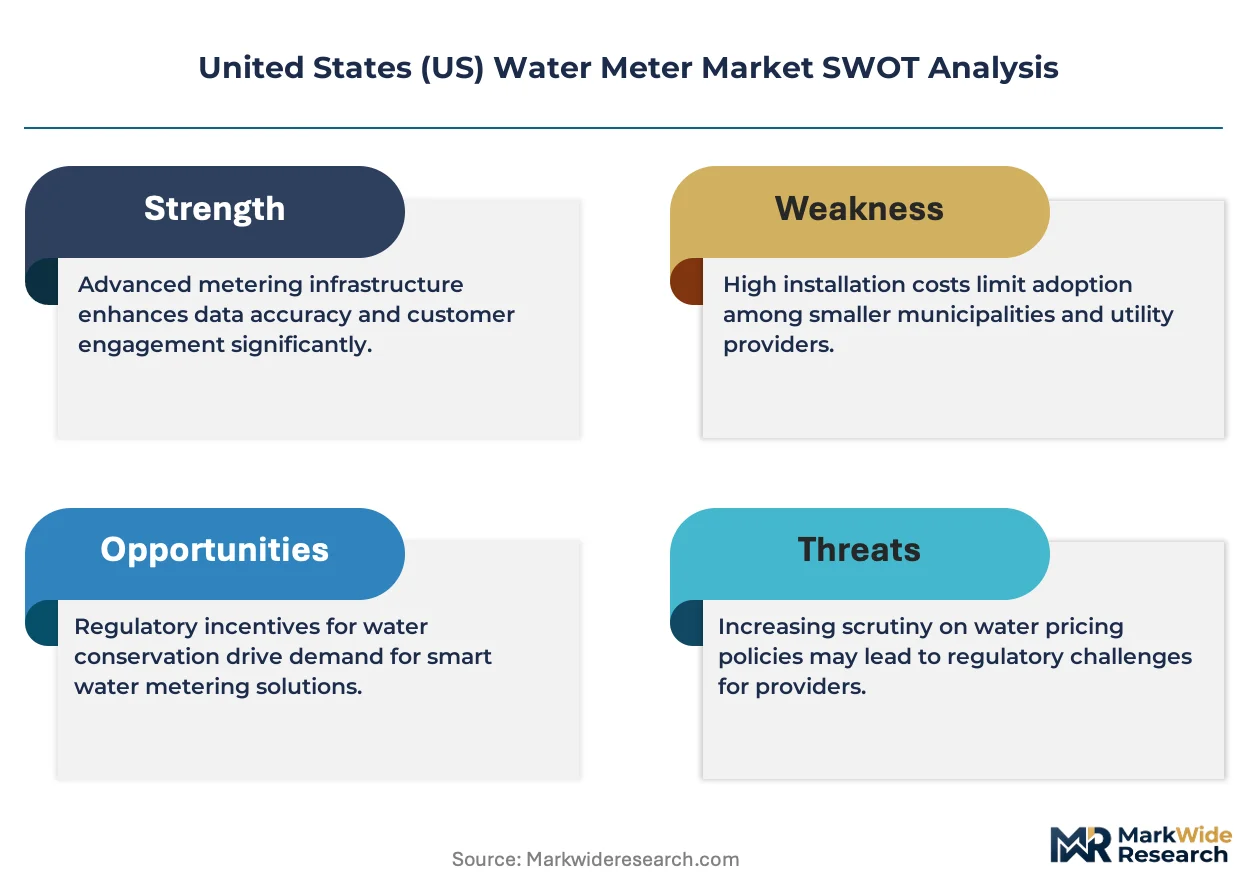
- Copper and Brass Input Volatility:Meter housings rely on lead-free bronze alloys, and price swings in copper cathode markets compress margin predictability for manufacturers without captive foundry operations.
- Midwest Manufacturing Concentration:Domestic production clusters in Wisconsin and Illinois create geographic vulnerability to regional labor shortages and logistics bottlenecks.
- Mechanical Meter Obsolescence Risk:Utilities with recently installed mechanical units face stranded asset exposure as AMI mandates render non-communicating infrastructure non-compliant.
Strategic Opportunities
- Florida Hurricane Resilience Funding:Federal disaster mitigation grants prioritize hardened metering infrastructure, opening replacement windows in Miami-Dade and Tampa Bay service territories.
- Industrial Submetering Convergence:Integration of water meters with building management systems and energy dashboards creates bundled service contracts for campus and manufacturing facility operators.
- Cybersecurity Certification Premiums:NIST framework compliance for networked meter infrastructure allows vendors to command price premiums from risk-averse municipal buyers.
Industry Challenges
- AMI Integration Complexity:Utilities struggle to synchronize new meter deployments with legacy billing software, stretching implementation timelines and requiring costly middleware development.
- Field Technician Skill Shortages:Electromechanical troubleshooting expertise outpaces training pipelines for digital diagnostics, creating service backlogs in rural water districts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States (US) Water Meter Market |
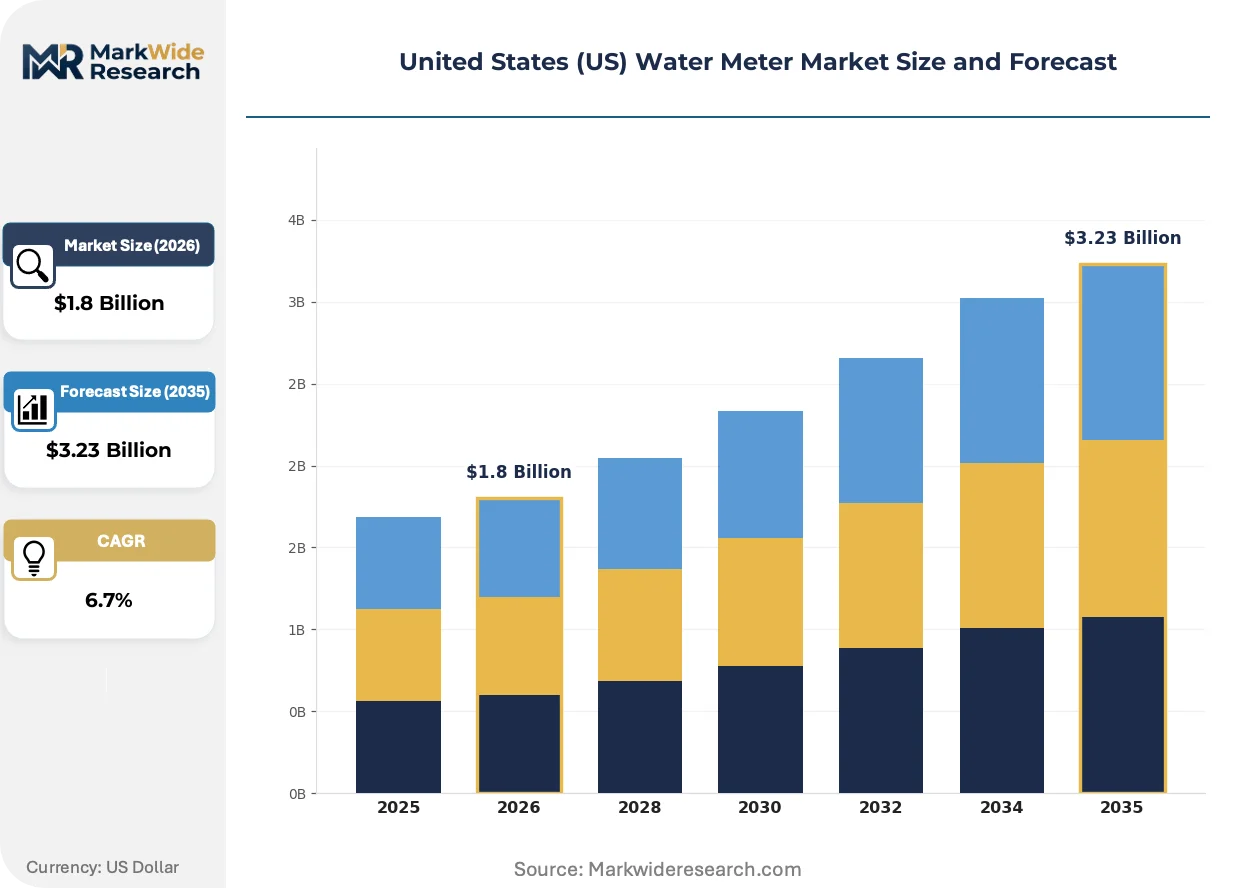
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electromagnetic, Ultrasonic, Smart Technology: AMR, AMI, Manual, Analog End User: Municipalities, Commercial, Residential, Industrial Installation: Above Ground, Below Ground, Wall Mounted, Portable |
| Companies Covered | Itron, Inc., Mueller Systems, LLC, Badger Meter, Inc., Diehl Stiftung & Co. KG, Kamstrup Water Metering LLC, Sensus USA Inc. (Xylem Inc.), Aclara (Hubbell), Flows.com, Neptune Technology Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States (US) Water Meter Market Evolving Landscape
Smart metering architecture is displacing standalone mechanical units as the default procurement specification, with data analytics and remote shutoff capabilities now treated as baseline utility requirements rather than premium features.
Ultrasonic sensing technology is overtaking traditional positive-displacement and turbine mechanisms in residential and commercial segments. Solid-state meters measure flow velocity through time-of-flight acoustic signals, eliminating wear-prone mechanical components. Municipal buyers in Arizona and Nevada are specifying ultrasonic units for hard-water applications where mineral buildup degrades mechanical accuracy. This shift is compressing aftermarket revenue streams for repair parts and recalibration services.
The EPA's Lead and Copper Rule Revision (LCRR) mandates lead-free certification for all new meter installations by October 2024. Manufacturers must submit third-party testing documentation proving components contain less than 0.25 percent lead content by weighted average. California and Illinois have enacted stricter state-level thresholds, forcing suppliers to maintain dual inventory streams or standardize to the most stringent specification nationwide.
Consolidated procurement by metropolitan water districts is displacing fragmented municipal purchasing. Regional authorities in Texas and Florida now negotiate enterprise-scale AMI contracts covering dozens of smaller member systems. This concentration favors vendors with dedicated public-sector sales teams and flexible financing structures. The shift is most visible in the Dallas-Fort Worth Metroplex, where the North Texas Municipal Water District centralizes specifications for over seventy member cities.
United States (US) Water Meter Market Segmentation
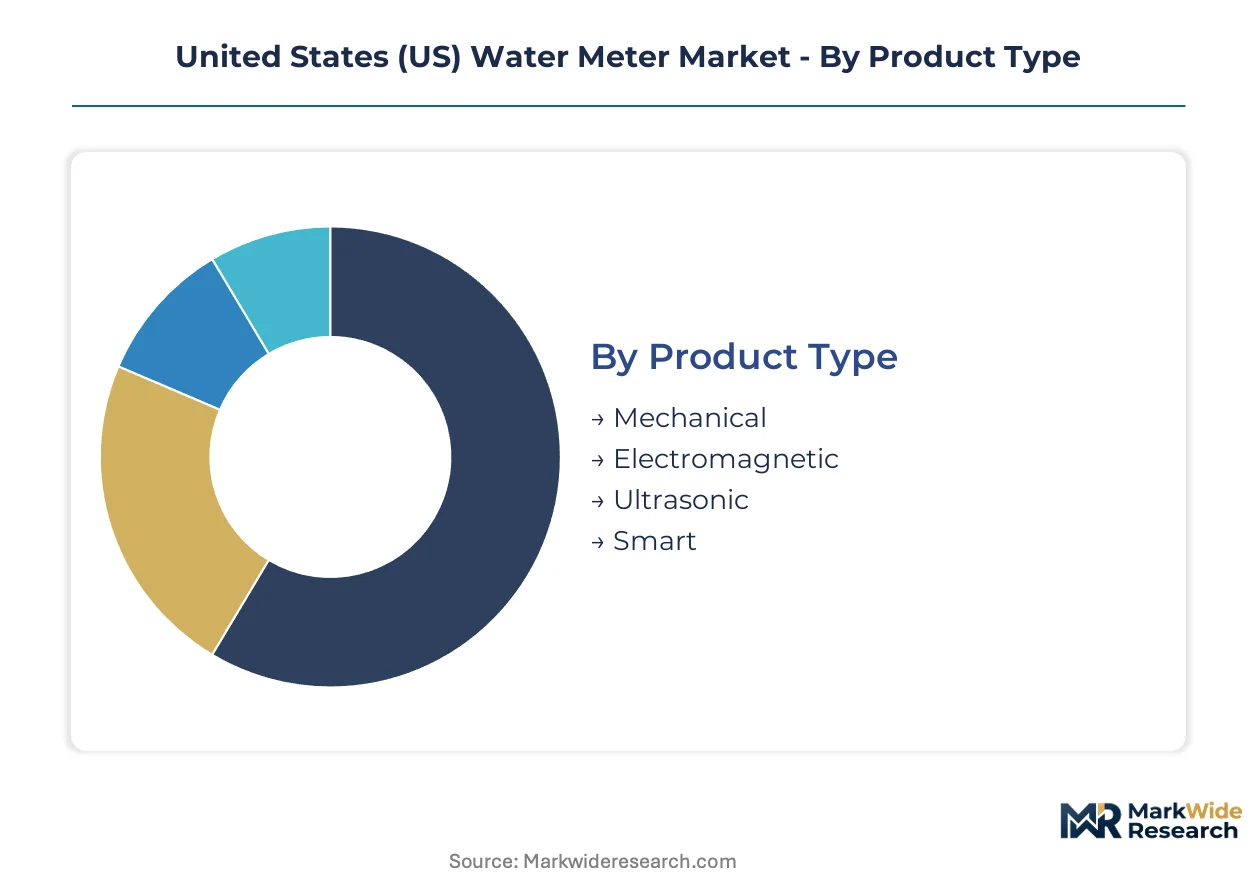
Water meter procurement patterns diverge sharply across product architectures, communication protocols, and installation environments. Understanding these fault lines reveals where capital budgets concentrate and which specifications dominate utility RFPs.
Product Type:
Mechanical units still dominate unit shipments while smart meters capture the value premium in municipal AMI rollouts.
- Mechanical:Positive-displacement and turbine mechanisms with bronze or composite housings deliver revenue-grade accuracy at sub-$100 price points. Demand concentrates in rural Texas and Midwest water districts with limited capital budgets and deferred infrastructure cycles.
- Smart:Solid-state meters with integrated radio modules enable real-time consumption monitoring and remote shutoff. California drought mandates and Florida hurricane resilience grants accelerate deployment across Los Angeles, San Diego, Miami-Dade, and Tampa Bay service territories.
- Ultrasonic:Time-of-flight acoustic sensing eliminates wear-prone components, cutting maintenance costs in hard-water environments across Arizona and Nevada.
- Electromagnetic:Faraday's law-based flow measurement serves industrial bulk applications where minimal head loss and corrosion resistance justify premium positioning.
Today's leader: Mechanical. Tomorrow's challenger: Smart.
Technology:
Communication sophistication separates capital-intensive AMI deployments from transitional AMR upgrades and legacy manual reads.
- AMI:Two-way cellular or mesh-network infrastructure supports demand response, leak alerts, and remote service disconnect. Texas Water Development Board revolving funds and California PUC rate-case requirements channel investment toward Houston, Dallas, and Los Angeles metropolitan districts.
- AMR:Drive-by or walk-by radio frequency collection bridges mechanical infrastructure toward digital billing without full network deployment. Mid-sized Midwest and Southeast utilities favor this transitional path.
- Manual:Visual dial reading persists in cash-constrained rural systems with sparse customer density and limited IT infrastructure.
- Analog:Pulse-output modules retrofit existing mechanical registers for basic telemetry without meter replacement.
AMI infrastructure locks in the highest lifetime value per endpoint. AMR serves the budget-constrained middle.
End User:
Customer scale dictates accuracy requirements, communication needs, and procurement authority concentration.
- Municipalities:Consolidated metropolitan water districts in Texas and Florida negotiate enterprise-scale contracts covering dozens of member systems. The North Texas Municipal Water District centralizes specifications for over seventy cities.
- Residential:Single-family and multi-unit dwellings generate the highest endpoint volumes. California's AMI readiness mandate applies primarily to this segment.
- Commercial:Office buildings, retail, and hospitality require submetering accuracy for tenant billing and sustainability reporting. Integration with building management systems creates bundled service opportunities.
- Industrial:Manufacturing campuses and processing facilities demand bulk-flow measurement with minimal pressure loss and material compatibility for aggressive chemistries.
Municipal procurement concentrates buying power. Industrial specifications command the highest per-unit margins.
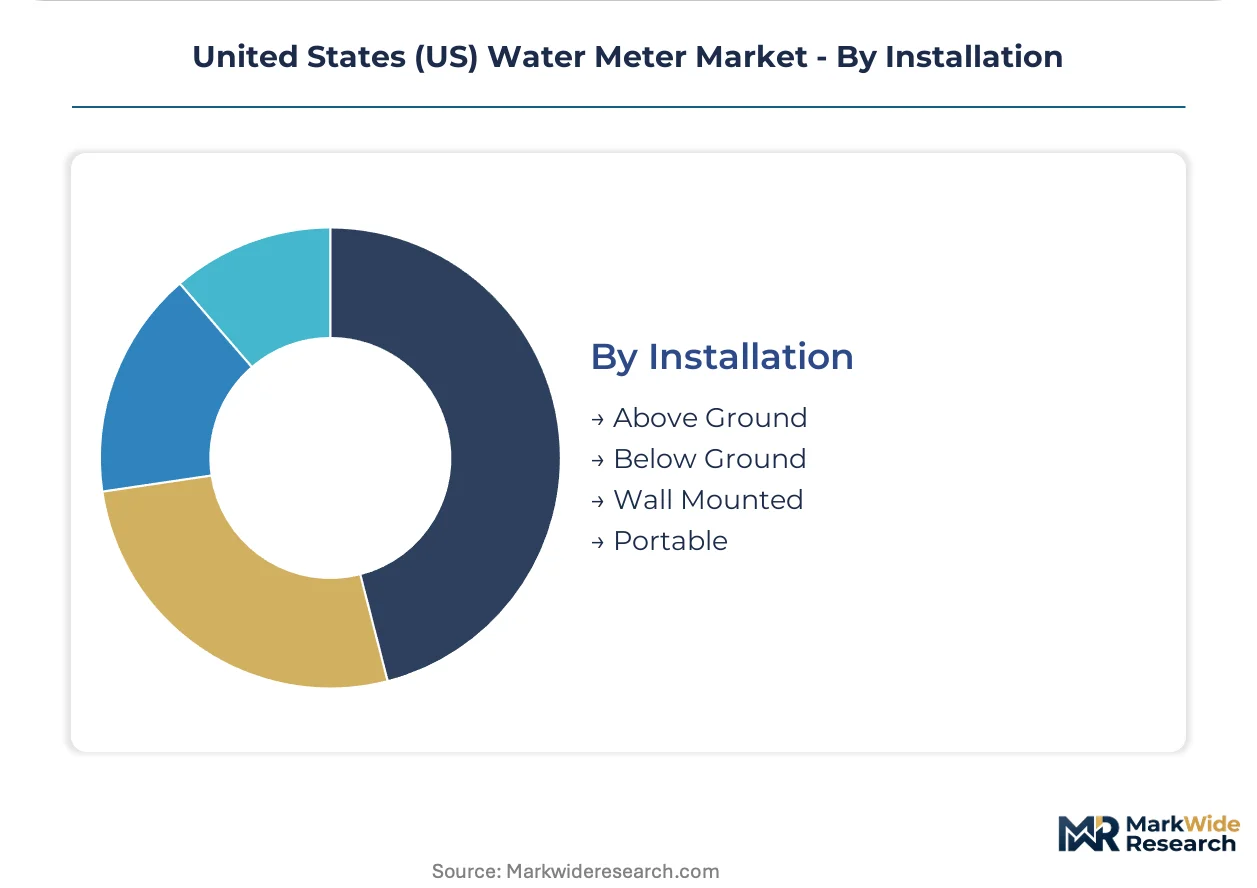
Installation:
Physical mounting environment determines housing durability, access protocols, and labor specialization requirements.
- Below Ground:Pit-set meters in frost-prone northern climates and hurricane-exposed Florida require corrosion-resistant enclosures and flooded-meter recovery capability. Federal disaster mitigation grants prioritize hardened infrastructure in Miami-Dade.
- Above Ground:Baseline configuration for temperate regions with straightforward technician access and standard weatherproofing.
- Wall Mounted:Indoor installations in multi-unit residential and commercial buildings protect meters from environmental exposure while enabling centralized utility rooms.
- Portable:Temporary deployment for construction dewatering, agricultural irrigation audits, and emergency response where permanent installation is impractical.
Below-ground specifications absorb the steepest climate-driven cost premiums. Wall-mounted units simplify submetering retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's drought-driven AMI mandates contrast with Texas's infrastructure revolving fund approach, revealing how federalism produces divergent procurement rhythms across state regulatory environments.
California
Chronic drought conditions and municipal bankruptcy exposure drive Los Angeles and San Diego water districts toward accelerated smart meter capital cycles. The state's public utility commission mandates AMI readiness for all rate-case approvals, compressing vendor selection timelines. Silicon Valley technology clusters supply data analytics platforms that integrate with municipal billing systems.
Texas
Houston and Dallas metropolitan districts channel Texas Water Development Board revolving funds toward non-revenue water reduction programs. The state's permissive regulatory environment allows rapid pilot-to-scale transitions for ultrasonic meter deployments. The Dallas-Fort Worth Metroplex anchors consolidated procurement through the North Texas Municipal Water District.
Florida
Hurricane resilience grants from federal disaster mitigation programs prioritize hardened below-ground metering infrastructure in Miami-Dade and Tampa Bay service territories. The state's public service commission requires cybersecurity documentation for networked meter deployments. Orlando's utility corridor concentrates vendor demonstration sites.
Arizona
Hard-water mineral conditions degrade mechanical meter accuracy, pushing Phoenix and Tucson utilities toward solid-state ultrasonic specifications. State-level water conservation mandates require real-time consumption visibility for rate-tier enforcement. The Colorado River shortage declarations accelerate replacement funding from the Central Arizona Project.
Illinois
Lead and Copper Rule compliance deadlines force Chicago and suburban Cook County utilities to replace legacy brass-bodied meters before October 2024 thresholds. The state's environmental protection agency enforces stricter lead-content standards than federal minimums. Rockford and Peoria manufacturing clusters supply bronze alloy castings for regional meter assembly.
United States (US) Water Meter Market Competitive Landscape
Midwestern producers anchor one tier; European specialists hold premium positioning through ultrasonic technology leadership. The vendor base concentrates around vertically integrated manufacturers with captive foundry operations and dedicated public-sector sales organizations. Two strategic archetypes dominate: full-service AMI integrators with end-to-end platform capabilities, and component specialists focused on solid-state sensing modules. Competitive moves center on enterprise-scale contract consolidation with metropolitan water districts and cybersecurity certification investments for NIST framework compliance.
Within the full-service tier, Badger Meter, Inc. and Mueller Systems, LLC exemplify domestically anchored manufacturers with deep municipal relationships across Midwest and Southeast procurement cycles. Kamstrup Water Metering LLC represents European technology-led positioning, occupying the ultrasonic specialization vector against traditional mechanical incumbents. These three entities collectively illustrate the geographic and technological fault lines shaping vendor selection criteria.
| Leading Market Players |
|---|
| Itron, Inc. |
| Mueller Systems, LLC |
| Badger Meter, Inc. |
| Diehl Stiftung & Co. KG |
| Kamstrup Water Metering LLC |
| Sensus USA Inc. (Xylem Inc.) |
| Aclara (Hubbell) |
| Flows.com |
| Neptune Technology Group Inc. |
| Others |
Value Network & Pricing Analysis
AMI-ready certification tiers bifurcate the market into premium solid-state suppliers and commodity mechanical vendors, with EPA lead-free mandates and state-level rate-case requirements driving procurement toward qualified manufacturers while copper alloy volatility compresses margins for non-integrated producers. This divergence concentrates pricing power among vertically integrated Midwest foundries and European ultrasonic specialists, leaving smaller mechanical assemblers exposed to raw material swings and enterprise contract consolidation.
Pricing Analysis
Capacity additions in Wisconsin and Illinois are reshaping price floors for lead-free bronze housings as captive foundry operators defend margin structures against spot-market dependent competitors. Three-tier pricing structure across premium AMI-integrated, standard AMR-transitional, and economy mechanical-replacement levels reflects certification depth and telemetry sophistication. Cost compression in the mechanical tier is intensifying because metropolitan water districts bundle volume across dozens of member systems. Rural Midwest utilities exhibit highest price sensitivity; California municipal buyers prioritize NIST cybersecurity compliance over unit cost.
Supply Chain Analysis
EPA lead-free certification and AWWA accuracy testing documentation gate supplier eligibility, forcing dual inventory streams for California and Illinois state-level thresholds. Domestic production clusters in Wisconsin, Illinois, and Michigan draw from regional bronze alloy foundries and electronics assembly corridors. Supply chain risk centers on single-source vulnerability for ultrasonic sensor modules sourced from European specialists. Distribution runs through dedicated public-sector sales organizations and regional water district procurement consortia rather than traditional industrial distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor solid-state meter architectures as ultrasonic technology eliminates aftermarket service revenue and extends replacement cycles beyond twenty years, compressing lifetime cost models for municipal buyers.
For Market Incumbents: Lock in enterprise-scale AMI contracts with metropolitan water districts in Texas and Florida before procurement consolidation accelerates. Deepen backward integration into lead-free bronze casting to insulate against copper cathode volatility. Prioritize NIST cybersecurity framework certification to command price premiums from risk-averse California and Illinois utilities facing state-level mandates. For New Entrants and Emerging Players: Direct-to-utility digital sales channels bypass established distributor relationships and accelerate pilot-to-scale transitions in permissive regulatory environments. Target hard-water Arizona and Nevada utilities with ultrasonic specialization against degraded mechanical accuracy. Pursue industrial submetering convergence opportunities with building management system integrators for campus and manufacturing facility bundled contracts. For Investors and Strategic Acquirers: Asymmetric upside sits with solid-state sensing module specialists possessing captive ultrasonic transducer fabrication and software analytics platforms. Long-term viability hinges on AMI infrastructure lock-in across the analysis window rather than mechanical replacement cycles. Monitor Texas Water Development Board revolving fund allocation velocity as inflection indicator for non-revenue water reduction program scaling.| Strategic Initiative | Industry Significance |
|---|---|
| AMI Platform Integration | Consolidated metropolitan water districts in Dallas-Fort Worth and Los Angeles demand end-to-end telemetry and billing interoperability. |
| Lead-Free Manufacturing Scale-Up | EPA October 2024 LCRR deadlines force foundry capacity expansion for certified bronze alloy meter housings. |
| Cybersecurity Certification Investment | NIST framework compliance unlocks California PUC rate-case approvals and Florida PSC networked deployment authorizations. |
| Ultrasonic Technology Licensing | Time-of-flight acoustic sensing transfers from European specialists to domestic assemblers seeking hard-water market positioning. |
| Regional Sales Organization Expansion | Dedicated public-sector teams capture enterprise-scale contracts displacing fragmented municipal purchasing. |
Research Methodology
Bottom-up municipal utility procurement modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with water district capital planning directors, AMI program managers, state public utility commission rate-case analysts, and bronze foundry procurement leads combined with secondary validation from EPA enforcement databases, AWWA standards documentation, Texas Water Development Board revolving fund disbursement records, and California PUC regulatory filings. Triangulation across utility capital expenditure surveys and vendor order backlog disclosures anchored volume estimates.
Input-output matrices map meter unit shipments to AMI infrastructure deployment rates, lead-free alloy consumption patterns, and regional regulatory compliance timelines across the analysis window. Segmentation dimensions include product architecture, communication protocol sophistication, end-user scale tier, and installation environment exposure. CAGRs derive from replacement cycle compression driven by EPA mandates and drought emergency declarations, with ultrasonic technology substitution curves and copper alloy price elasticity as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state meter penetration would alter the outlook if mechanical unit longevity exceeds projected obsolescence timelines or if cybersecurity insurance requirements accelerate beyond NIST baseline compliance. Forecasts reflect assumptions about state-level rate-case approval velocity and federal disaster mitigation grant continuity. A model refresh is warranted upon material change in EPA enforcement posture or copper cathode supply disruption magnitude.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Global Smart Water Meter Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
LNG Metering Skids Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
North America Smart Meters Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Smart Gas Meter Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
Smart Meters Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Watt Meter Market
Smart Meters
Smart Utility Solutions Market
Smart Meters
Water Meter Market
Smart Meters
Single-Phase Anti-Theft Meter Market
Smart Meters
Plug in Power Meter Market
Smart Meters
Power Metering Market