
 Home Energy Monitor Market | 2026-2036
Home Energy Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Home Energy Monitor Market Insights
Utility buyers is bifurcating from early adopter households toward mass-market residential consumers across deregulated electricity markets. Schneider Electric leverages its circuit breaker integration and B2B channel depth to anchor the commercial building segment. Sense Labs competes on disaggregation algorithms and direct-to-consumer branding. Emporia Corp. specializes in cost-accessible hardware with solar-ready monitoring, occupying the retrofit installation niche.
A home energy monitor is a distributed sensing and communications device that measures real-time electrical consumption at the panel, circuit, or appliance level, typically sampling at sub-second intervals and transmitting data via Wi-Fi, Zigbee, or Bluetooth protocols to cloud analytics platforms or local displays. Its primary commercial purpose is to enable load visibility, demand response participation, and behavioral efficiency programs for residential and small commercial electricity consumers. Smart meters represent the largest installed base and generate recurring data revenue for utilities, while energy management software captures the fastest growth as platform vendors bundle AI-driven insights with third-party thermostat and EV charger control. Plug load monitors serve a mature accessory market with thin margins, whereas in-home displays face displacement by smartphone apps despite their standalone simplicity.
US utilities must comply with FERC Order 2222 aggregation standards and state-level net metering reforms that mandate interoperable consumer access to interval data. The EU F-Gas Regulation and Ecodesign requirements indirectly shape monitor specifications by pressuring HVAC efficiency verification, while Japan's METI drives adoption through the Top Runner program and residential demand response subsidies. Stakeholders should monitor whether utility-owned meter gateways or consumer-purchased third-party devices win the platform control point for home energy data.
Market Dynamics
Wi-Fi and Zigbee open protocols are dismantling proprietary ecosystems, forcing incumbent hardware vendors to abandon closed-stack architectures or surrender platform control to cloud-native software providers.
Growth Catalysts
- State Decarbonization Mandates:Utilities in California, New York, and Germany face binding residential electrification targets that require granular consumption visibility for demand response orchestration.
- FERC Order 2222:This US federal standard mandates interoperable consumer access to interval meter data, compelling utilities to open APIs for third-party monitor integration.
- Time-of-Use Rate Expansion:Dynamic electricity pricing structures in Japan, Australia, and Texas create direct financial incentives for real-time load monitoring.
Market Restraints
- Semiconductor Supply Concentration:Wi-Fi and Zigbee chip fabrication concentrates in Taiwan, exposing monitor manufacturers to geopolitical disruption and allocation delays.
- Installation Skill Scarcity:Panel-level monitors require licensed electrician intervention, constraining retrofit penetration in markets with contracting electrical trades.
- Smart Meter Substitution:Utility-owned advanced metering infrastructure provides baseline consumption data at zero marginal cost to consumers, compressing addressable market for standalone devices.
Strategic Opportunities
- India Residential Electrification:Rural electrification programs and rising AC penetration create first-mover advantage for cost-optimized plug-load monitors.
- EV-Home Integration:Bidirectional charger monitoring converges with solar inverter data streams, opening unified energy management platforms.
- EU Ecodesign Verification:HVAC efficiency disclosure requirements position circuit-level monitors as compliance tools for building energy performance certificates.
Industry Challenges
- Data Interoperability Standards:Fragmented APIs across smart thermostat, EV charger, and solar inverter vendors force monitor manufacturers to maintain multiple integration pipelines.
- Cybersecurity Certification Timelines:UL 2900 and IEC 62443 compliance testing extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Energy Monitor Market |
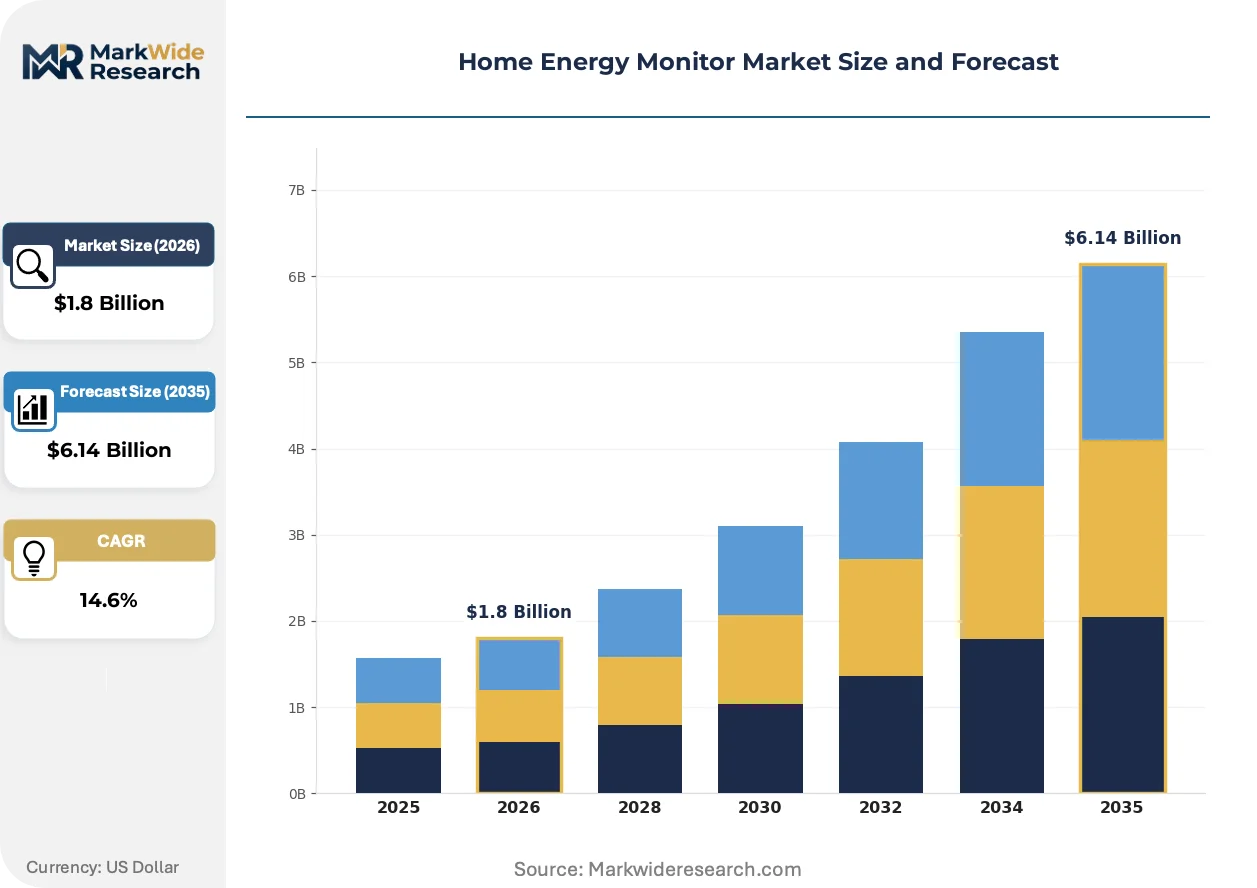
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plug Load Monitors, Smart Meters, In-Home Displays, Energy Management Software End User: Residential Consumers, Property Managers, Utilities, Energy Consultants Technology: Zigbee, Wi-Fi, Bluetooth, Cellular Application: Energy Consumption Tracking, Demand Response, Cost Monitoring, Renewable Integration |
| Companies Covered | Schneider Electric, Sense Labs, Emporia Corp., Honeywell International, Siemens AG, OWL Intuition Ltd, Rainforest Automation, Blue Line Innovations, Ecobee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Energy Monitor Market Trends and Innovations
Machine learning inference at the edge is compressing cloud dependency while non-intrusive load monitoring algorithms achieve appliance-level resolution without distributed sensors.
Non-intrusive load monitoring (NILM) algorithms process high-frequency voltage and current signatures at the main electrical panel to disaggregate individual appliance consumption without submetering hardware. Residential solar adopters and multi-unit property managers are deploying NILM-enabled monitors at accelerating rates to isolate production from consumption patterns. This software-defined approach is supplanting circuit-level hardware installations, collapsing installation costs and expanding retrofit addressability.
The EU F-Gas Regulation and accompanying Ecodesign requirements now mandate verifiable HVAC efficiency performance in residential buildings. Monitor vendors are embedding refrigerant cycle detection algorithms to validate heat pump coefficient of performance claims. German and Dutch building retrofit programs now specify interval data logging as prerequisite for subsidy eligibility.
Direct-to-consumer hardware brands are bypassing electrical contractor channels through retail partnerships and self-installation designs. Big-box home improvement retailers in the United States and Australia now stock Wi-Fi-enabled clamp-on monitors alongside smart thermostats. This channel compression is most visible in deregulated electricity markets where consumers bear direct price exposure and seek autonomous demand management tools.
Home Energy Monitor Market Segmentation
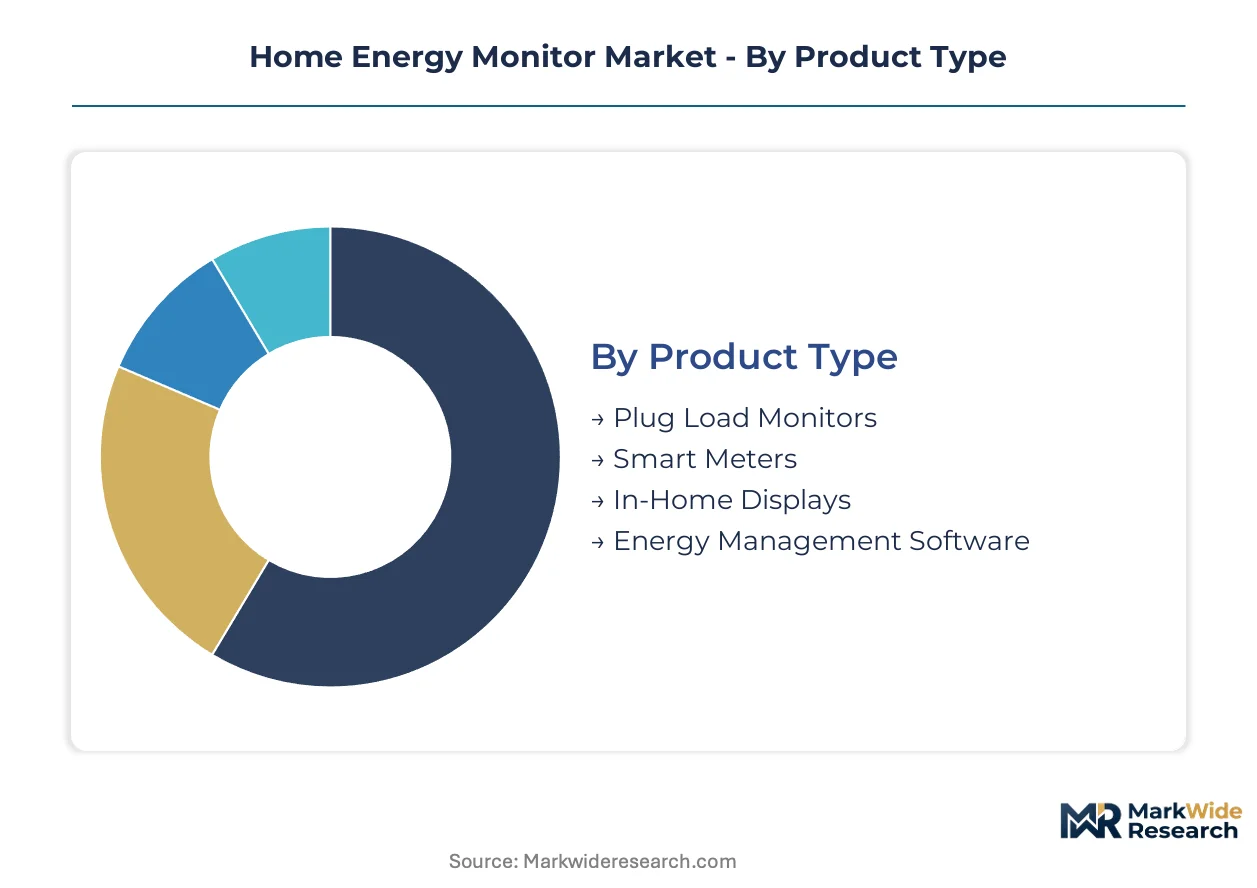
Home energy monitor vendors route distinct product configurations through divergent channel architectures. Utility procurement teams, electrical contractors, and direct-to-consumer retail each favor different specification bundles, creating four parallel demand streams with minimal overlap.
Product Type:
Channel mix varies sharply: utilities bulk-purchase smart meters through RFP processes, while energy management software flows via SaaS subscriptions to integrators and ESCOs. Retail shelves carry plug load monitors and in-home displays for self-installation markets.
- Smart Meters:These utility-owned devices embed metrology-grade sensing, interval data logging, and encrypted backhaul to distribution management systems. Procurement concentrates among state-regulated utilities in California, New York, and Texas where decarbonization mandates require AMI 2.0 deployment. FERC Order 2222 compliance deadlines accelerate replacement cycles.
- Energy Management Software:Cloud-native platforms aggregate multi-source data streams from solar inverters, EV chargers, and thermostats to deliver AI-driven load forecasts. Demand clusters among property managers operating multi-unit buildings in deregulated electricity markets where time-of-use rate exposure justifies subscription spend. This segment climbs the fastest as vendors bundle control automation with monitoring.
- Plug Load Monitors:Self-contained outlet-level sensors serve the retrofit accessory market through big-box retail and Amazon marketplace channels.
- In-Home Displays:Standalone touchscreen units face displacement by smartphone apps despite their plug-and-play simplicity for non-technical users.
Smart meters dominate installed base. Energy management software is where expansion concentrates.
End User:
Margin structure inverts across customer types: utilities negotiate volume discounts on hardware, while residential consumers pay retail markup for installation simplicity. Property managers occupy the middle tier, purchasing mid-scale deployments through electrical contractor channels.
- Utilities:These buyers mandate IP68 enclosure ratings, 20-year operational lifespans, and API interoperability for third-party aggregator access. Procurement concentrates among IOUs and municipal utilities in Germany and Japan where regulatory frameworks mandate consumer data portability. State-level renewable portfolio standards drive refresh cycles.
- Residential Consumers:Homeowners and renters prioritize self-installation, smartphone app integration, and sub-$200 price points. Adoption clusters in Texas, Australia, and the United Kingdom where dynamic pricing exposes consumers to real-time rate volatility. Solar-plus-storage adopters generate disproportionate demand for circuit-level visibility.
- Property Managers:Multi-unit operators require tenant-billing granularity and centralized portfolio dashboards. Sub-metering regulations in California and the EU drive specification requirements.
- Energy Consultants:Third-party auditors and retrofit specialists specify professional-grade hardware with certified accuracy for utility incentive program documentation.
Utilities anchor hardware volume. Residential consumers represent the steepest expansion trajectory for direct-to-consumer brands.
Technology:
Protocol selection determines ecosystem lock-in versus interoperability tradeoffs. Wi-Fi and Zigbee adoption curves diverge based on installation context and existing smart home infrastructure.
- Wi-Fi:Ubiquitous household coverage eliminates gateway requirements, enabling direct cloud connectivity for consumer-purchased devices. Deployment concentrates in North American and Australian markets where broadband penetration supports always-on backhaul. Chipset cost compression from smartphone supply chain spillover accelerates adoption.
- Zigbee:Mesh networking topology extends range across large homes and multi-unit properties without router dependency. Utility smart meter deployments in Germany and the United Kingdom favor this protocol for its low-power profile and standardized application profiles. SEP 2.0 interoperability certification reduces integration friction.
- Bluetooth:Low-energy variants serve battery-powered portable monitors and temporary installation scenarios.
- Cellular:LTE-M and NB-IoT modules enable standalone deployment in locations lacking broadband infrastructure, common in rural electrification programs.
Wi-Fi captures consumer channel volume. Zigbee retains utility procurement preference where mesh reliability matters.
Application:
Use case specificity shapes sensor sampling rates, data retention policies, and pricing model design. High-frequency monitoring for demand response commands premium positioning against basic consumption tracking.
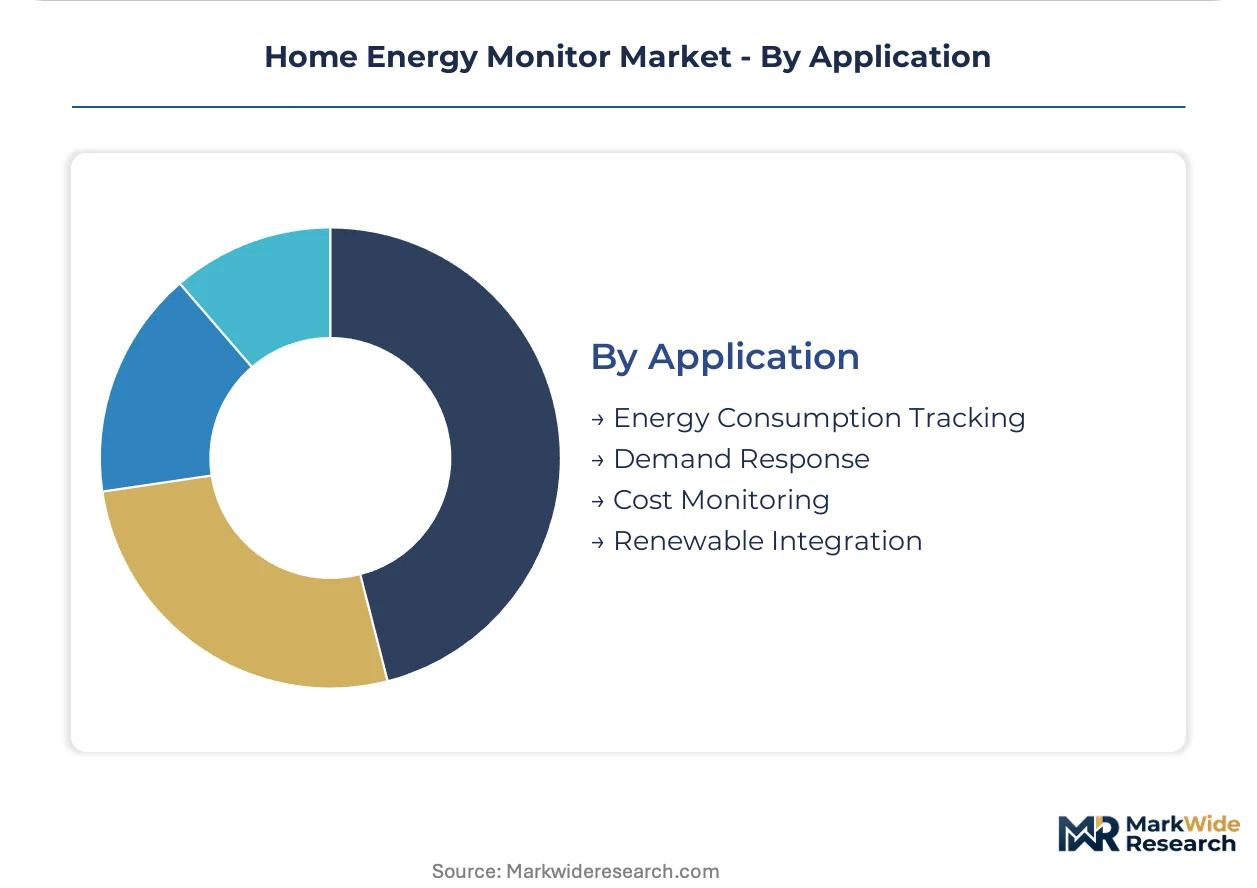
- Demand Response:Sub-second load telemetry enables automated curtailment signals for grid stability services. Adoption concentrates among utilities in Texas, California, and Japan where wholesale price volatility and capacity constraints create monetizable flexibility. FERC Order 2222 aggregation rules expand third-party participation.
- Renewable Integration:Bidirectional monitoring synchronizes solar production, battery state-of-charge, and EV charging schedules. German and Australian markets lead deployment where high retail electricity rates and export tariff structures reward self-consumption optimization.
- Energy Consumption Tracking:Baseline visibility applications serve behavioral efficiency programs with lower hardware specifications and cloud processing overhead.
- Cost Monitoring:Time-of-use rate visualization drives consumer engagement in deregulated markets with dynamic pricing exposure.
Energy consumption tracking dominates unit shipments. Demand response commands the highest revenue per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific DC intertie and Texas ERCOT grid infrastructure anchor North American demand for real-time consumption visibility, while submarine cable interconnects in the North Sea and METI-subsidized smart city deployments in Japan shape procurement patterns elsewhere.
United States
Texas and California utilities drive demand response procurement under FERC Order 2222 aggregation rules. The Inflation Reduction Act residential electrification incentives accelerate solar-plus-storage adopter purchases of circuit-level monitors. Austin and San Antonio clusters concentrate utility pilot programs for EV-integrated home energy management.
Germany
Building Energy Act retrofit mandates and Ecodesign HVAC efficiency verification requirements create compliance-driven procurement. The EU F-Gas Regulation pressures heat pump performance documentation. North Rhine-Westphalia and Bavaria housing cooperatives deploy sub-metering for tenant billing granularity.
Japan
METI Top Runner program subsidies and residential demand response auctions expand addressable market. Time-of-use rate structures in Tokyo Electric Power territory create consumer price exposure. Kanto and Kansai metropolitan areas concentrate smart home platform integration pilots.
Australia
National Electricity Market price volatility and distributed energy resource export tariffs reward self-consumption optimization. State-level solar feed-in tariff reductions shift value toward load-shifting visibility. New South Wales and Victoria lead retail channel penetration of Wi-Fi-enabled clamp-on monitors.
India
Rural electrification under Saubhagya scheme and rising air-conditioning penetration create first-mover opportunity for cost-optimized plug-load devices. Bureau of Indian Standards energy labeling expansion pressures appliance-level tracking. Maharashtra and Gujarat urban clusters concentrate property manager sub-metering trials.
Home Energy Monitor Market Competitive Landscape
Concentration sits with diversified electrical equipment conglomerates that leverage circuit breaker integration and utility channel relationships. The vendor base spans three tiers: integrated industrial conglomerates with panel-level hardware depth, cloud-native software specialists with NILM algorithm differentiation, and cost-optimized hardware assemblers targeting retail self-installation. Strategic moves center on protocol standardization alliances and backward integration into sensor semiconductor sourcing.
Within the integrated equipment tier, Schneider Electric and Siemens AG exemplify conglomerate positioning through electrical infrastructure channel control. Sense Labs occupies a specialist position emphasizing disaggregation software and direct-to-consumer brand building. Emporia Corp. represents the cost-accessible hardware archetype with solar-ready retrofit configurations.
| Leading Market Players |
|---|
| Schneider Electric |
| Sense Labs |
| Emporia Corp. |
| Honeywell International |
| Siemens AG |
| OWL Intuition Ltd |
| Rainforest Automation |
| Blue Line Innovations |
| Ecobee |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day lead times for Zigbee and Wi-Fi chipsets from Taiwan-based foundries concentrate pricing power among semiconductor distributors, compressing margins for monitor assemblers while amplifying volume-tier advantages for utility-scale procurement teams negotiating multi-year smart meter contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates utility-grade smart meters with IP68 enclosures and 20-year lifespans from self-install consumer clamps and basic plug-load accessories. Price differentiation hinges on certification grade—UL 2900 and IEC 62443 compliance adds 8-14 months to launch cycles—and volume scale, with utilities extracting 40-60% discounts on bulk AMI deployments. Cost compression in the consumer tier is intensifying because Wi-Fi chipset spillover from smartphone supply chains collapses hardware BOMs. Residential consumers in deregulated electricity markets exhibit highest price sensitivity, while utilities demonstrate lowest sensitivity given regulatory-mandated refresh cycles and total-cost-of-ownership procurement frameworks.
Supply Chain Analysis
Inventory buffers for RF front-end modules and metrology-grade current transformers typically stretch 60-90 days, exposing assemblers to allocation shocks when foundry capacity tightens. Manufacturing concentrates in Taiwan for Wi-Fi/Zigbee silicon, China for PCB assembly and enclosure molding, and Mexico for final integration serving North American utility contracts. Raw material dependencies include rare-earth magnets for current sensors, copper for precision windings, and flame-retardant plastics for panel-rated housings. Single-source vulnerability concentrates in Taiwan semiconductor fabrication, where geopolitical disruption threatens component flow. Distribution runs through electrical contractor channels for utility and property manager segments, while direct-to-consumer brands bypass intermediaries via Amazon and big-box retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware monetization in home energy monitoring is flattening as energy management software subscriptions and demand response aggregator fees expand at multiples of device revenue, making service-attach economics the defining investment thesis.
For Market Incumbents: Consolidate circuit breaker integration capabilities and utility channel relationships to defend against cloud-native software vendors disintermediating hardware margins. Acquire NILM algorithm specialists to offset displacement risk from non-intrusive load monitoring supplanting distributed sensor networks. Deepen backward integration into sensor semiconductor sourcing to mitigate Taiwan foundry concentration.
For New Entrants and Emerging Players: AI-driven disaggregation APIs for third-party thermostat and EV charger control represent a service-layer gap where incumbents under-serve mid-market property managers. Target India's rural electrification programs with cost-optimized plug-load monitors priced below utility smart meter substitution thresholds. Pursue white-label partnerships with solar inverter manufacturers seeking unified energy management platforms.
For Investors and Strategic Acquirers: Long-term, this sits as a data-platform play because interval consumption telemetry becomes the foundation for virtual power plant aggregation and carbon accounting verification. Acquisition candidates with FERC Order 2222-compliant APIs and established utility integration pipelines command strategic premium. Monitor state-level net metering reform timelines as inflection indicator for standalone monitor demand displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Standardization Alliance | Zigbee SEP 2.0 and Wi-Fi HaLow certification reduces integration friction for multi-vendor smart home deployments. |
| Backward Integration into Sensor Semiconductors | Captive supply of metrology-grade ADCs insulates margins from Taiwan foundry allocation volatility. |
| Energy Management Software Acquisition | Cloud-native platforms with AI load forecasting capture recurring revenue streams beyond hardware replacement cycles. |
| Direct-to-Consumer Channel Expansion | Big-box retail partnerships in Texas and Australia bypass electrical contractor scarcity constraining retrofit penetration. |
| Demand Response Aggregator Partnership | FERC Order 2222 compliance enables third-party participation in wholesale capacity markets through utility API integration. |
Research Methodology
A standing panel of utility procurement officers, electrical contractor operations managers, smart home platform engineers, and residential solar installer owners provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against FERC filings, EIA smart meter deployment databases, METI subsidy program disclosures, and EU Ecodesign regulatory texts. Bottom-up unit economics from hardware BOM analysis and top-down utility RFP aggregation were triangulated to reconcile volume estimates.
Consistency checks against external benchmarks validated projection outputs against observed AMI 2.0 replacement cycles and SaaS platform subscriber growth in deregulated electricity markets. The analytical framework modeled demand across product type, end user archetype, connectivity protocol, and application use case throughout the forecast period. CAGRs were derived from segment-level growth trajectory convergence, incorporating FERC Order 2222 compliance deadlines, state decarbonization mandate timelines, and time-of-use rate expansion patterns as industry-specific demand drivers.
Forecasts assume regulatory continuity in US state-level renewable portfolio standards, EU F-Gas Regulation enforcement, and Japan METI demand response subsidy frameworks; material policy shifts would require re-modeling. Outputs reflect assumptions of stable Taiwan semiconductor supply, electrician labor availability, and smart meter substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Power Monitoring System Market
Smart Meters
Asia-Pacific Smart Meter Data Management Market
Smart Meters
United States Smart Meter Market
Smart Meters
Smart Utility Solutions Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
LNG Metering Skids Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Digital Water Meters Market
Smart Meters
US Water Meter Market
Smart Meters
North America Gas Meter Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Solar Meter Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Single-Phase Anti-Theft Meter Market