
 Solid Recovered Fuel Market | 2026-2036
Solid Recovered Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Recovered Fuel Market Analysis
The EU Green Deal's waste-to-energy targets is rebalancing procurement priorities across European heavy industry. Veolia leverages integrated waste collection and fuel preparation infrastructure across France and the Benelux region. Renewi sustains scale advantages in mechanical treatment and refuse-derived fuel upgrading through dedicated Dutch and Belgian facilities. SUEZ competes on thermal treatment expertise and long-term supply contracts with cement manufacturers.
Solid recovered fuel comprises processed non-hazardous waste streams—primarily paper, plastics, textiles, and wood residues—refined to achieve specified calorific values, chlorine limits, and particle size distributions for direct combustion in industrial kilns and boilers. The fuel substitutes fossil coal in cement production and power generation, delivering measurable CO2 reductions per tonne of clinker or electricity output. Paper waste and plastic waste fractions command structural priority in procurement due to higher energy density and more predictable combustion profiles. Mechanical treatment dominates installed processing capacity, though thermal treatment segments attract capital for producing higher-grade outputs with tighter contaminant thresholds. Cement production anchors end-use demand, while power generation segments show faster growth as utilities retrofit coal units for co-firing under emissions trading pressure.
EMA, ECHA, and the EU F-Gas Regulation collectively shape product standards, emissions limits, and cross-border waste shipment protocols for SRF trade within Europe. REACH compliance requirements for chlorine and heavy metal content directly determine fuel acceptance at cement kilns and influence preprocessing technology selection. Stakeholders must monitor evolving EU taxonomy criteria for waste-derived fuels and national implementation timelines for the revised Waste Framework Directive.
Market Dynamics
EU ETS carbon pricing is compressing coal economics in cement manufacturing, redirecting capital toward SRF preprocessing infrastructure and long-term offtake agreements with waste processors.
Growth Catalysts
- EU ETS carbon pricing:Cement manufacturers face escalating compliance costs for fossil coal combustion, accelerating fuel-switching investments toward waste-derived alternatives.
- Mechanical treatment capacity:Refining technologies for paper and plastic fractions now achieve calorific consistency that satisfies kiln operator specifications without secondary thermal processing.
- Poland:New cement kiln retrofits and waste collection network expansions create integrated supply corridors linking municipal waste streams to industrial fuel demand.
Market Restraints
- Chlorine content volatility:PVC contamination in plastic waste streams creates batch-to-batch thermal performance variation, requiring costly preprocessing or fuel blending.
- German preprocessing concentration:Advanced mechanical treatment infrastructure clusters in the Rhine-Ruhr and Bavaria regions, creating logistics bottlenecks for peripheral cement plants.
- REACH compliance timelines:Heavy metal testing and certification protocols delay cross-border fuel shipments between member states, extending inventory cycles.
Strategic Opportunities
- Italian power generation:Coal-to-biomass retrofit programs at utilities create new SRF demand outside traditional cement kiln channels.
- EU Green Deal waste-to-energy targets:Mandatory landfill diversion timelines force municipal waste authorities to expand fuel preparation partnerships with industrial offtakers.
- Near-infrared sorting and optical separation:Converging sensor technologies enable real-time contaminant removal, upgrading lower-grade waste streams to cement kiln specifications.
Industry Challenges
- Waste characterization expertise:Shortage of technicians trained in calorific value testing and chlorine limit verification creates quality control gaps at preprocessing facilities.
- Kiln integration complexity:Cement plants must reconfigure feed systems, combustion air management, and emissions monitoring to accommodate variable SRF fuel properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Recovered Fuel Market |
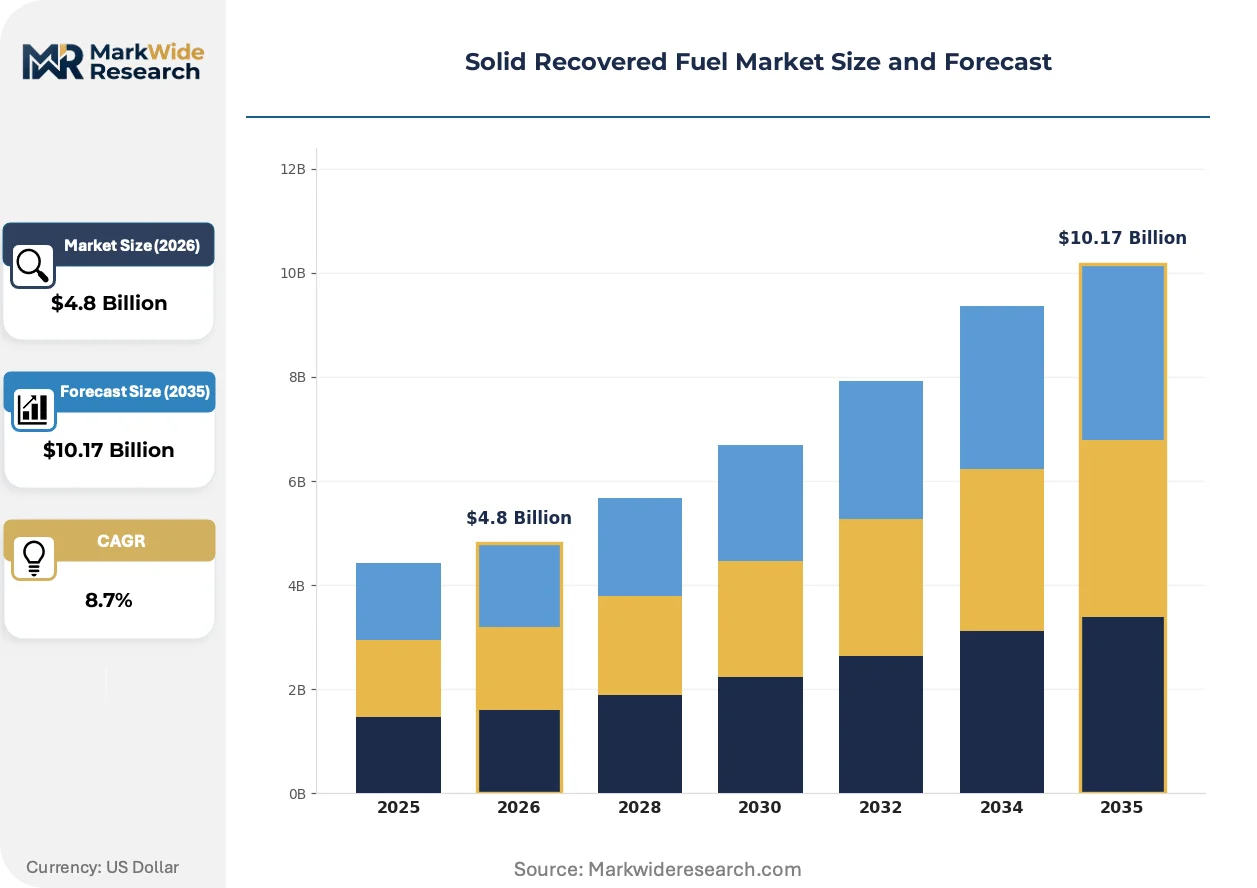
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Waste, Plastic Waste, Paper Waste, Textiles End Use Industry: Cement Production, Power Generation, Industrial Heating, Waste Treatment Processing Technology: Mechanical Treatment, Biological Treatment, Chemical Treatment, Thermal Treatment Quality Grade: High Calorific, Medium Calorific, Low Calorific, Industrial Grade |
| Companies Covered | Covanta, Renewi, Veolia, Dalkia, FCC Environment, SUEZ, Biffa, Recology, Waste Management, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Recovered Fuel Market Emerging Trajectories
Processing technology and regulatory enforcement are converging to standardize fuel quality at scale, reducing the performance gap between waste-derived and fossil alternatives in high-temperature combustion applications.
Advanced optical sorting is consolidating preprocessing economics. Near-infrared and X-ray transmission systems now separate plastics by polymer type and chlorine content in real-time. Dutch and Belgian waste processors deploy these systems to produce cement-grade SRF without capital-intensive thermal treatment. The technology is consolidating market share toward integrated operators capable of consistent fuel specification.
REACH enforcement is tightening cross-border fuel circulation. ECHA's updated guidance on persistent organic pollutants and heavy metal thresholds requires batch-level documentation for SRF shipments between member states. Cement manufacturers in Germany and Poland now demand certified fuel preparation protocols that extend upstream to waste collection contractors. The regulation is compressing informal supply relationships and favoring contracted volume arrangements.
Buyer concentration is reshaping procurement leverage. Major cement groups now consolidate SRF purchasing across multiple kiln sites, replacing fragmented local sourcing with centralized fuel quality management. This pattern concentrates volume commitments toward preprocessing operators with multi-site supply capability. The shift is most visible in the United Kingdom, where national cement producers have reduced supplier counts by half over the past contract renewal cycle.
Solid Recovered Fuel Market Segmentation
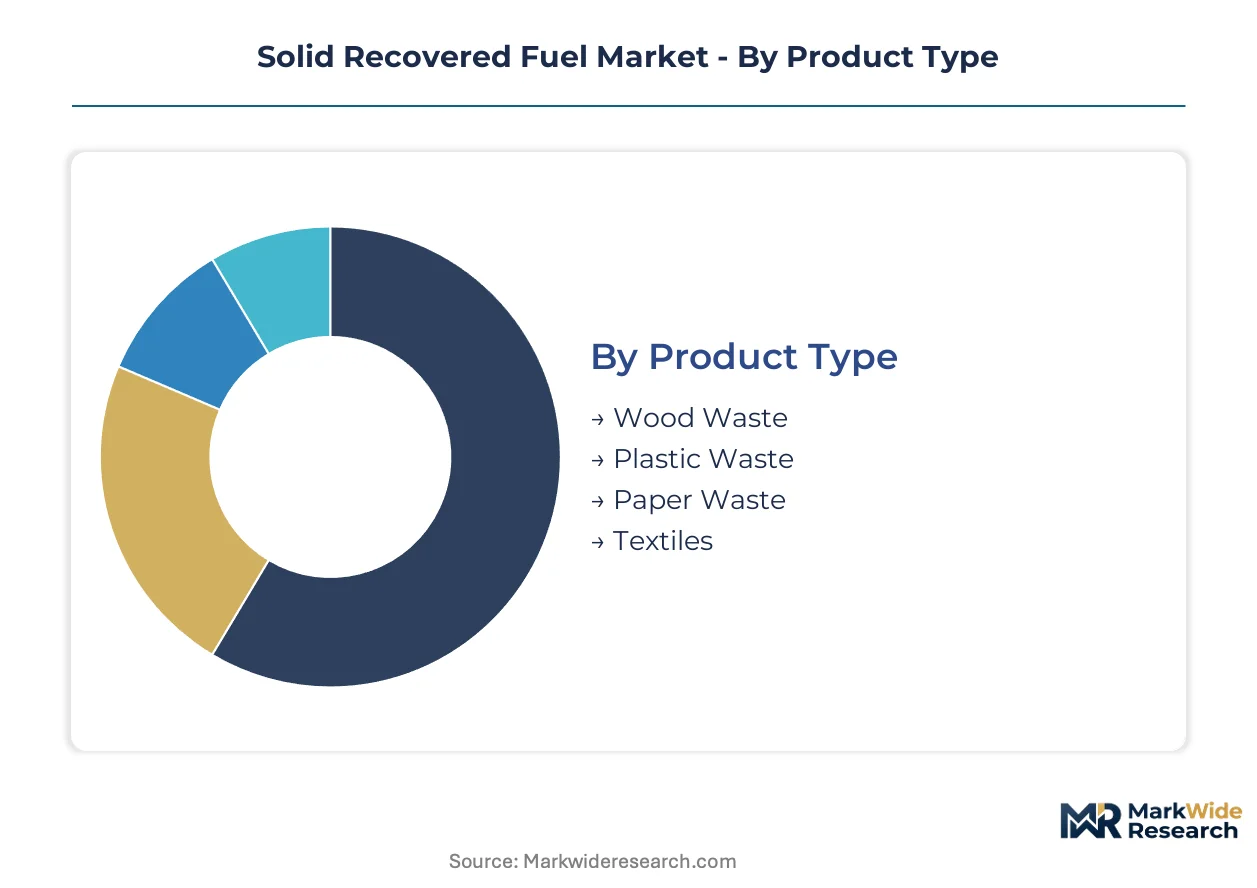
Segmentation in the solid recovered fuel market tracks how waste stream composition, processing investment, and end-use specifications create divergent margin structures across the value chain. Understanding these divisions reveals where capital is concentrating and which technology pathways are capturing procurement volume from cement manufacturers and utilities.
Product Type:
Supply concentration in waste collection networks directly shapes which feedstock fractions achieve scale in fuel preparation. Regions with established commercial recycling infrastructure generate predictable volumes of specific waste streams, enabling dedicated preprocessing lines and consistent kiln specifications.
- Wood Waste:Processed wood residues from construction, demolition, and manufacturing deliver high calorific value with low chlorine contamination. Demand concentrates in German and Polish cement kilns where operators seek direct coal replacement without secondary treatment. EU Waste Framework Directive diversion targets are expanding collection infrastructure for this fraction.
- Plastic Waste:Mixed post-consumer plastics require intensive sorting to remove PVC and achieve chlorine limits acceptable for cement combustion. Italian power generation retrofits and German cement plants are the primary offtakers, though batch variability forces blending strategies or thermal upgrading investments.
- Paper Waste:Commercial and industrial paper streams offer predictable combustion profiles but lower energy density than plastics or wood. United Kingdom cement producers source this fraction heavily due to established commercial collection networks.
- Textiles:Post-industrial textile residues from garment manufacturing regions provide consistent fiber-based fuel input. Benelux preprocessing facilities specialize in this fraction for regional cement supply.
Today's leader: Plastic waste. Tomorrow's challenger: Wood waste.
End Use Industry:
Application-driven procurement specifications split the market between high-temperature kiln requirements and lower-grade thermal demand. Cement production imposes the strictest fuel quality thresholds, creating premium pricing tiers that other segments cannot access without upgrading investment.
- Cement Production:Clinker manufacturing requires precise calorific consistency, chlorine limits below 0.5%, and controlled particle size for stable flame characteristics. German, Polish, and United Kingdom cement groups dominate procurement volume, consolidating purchasing across multi-site operations under centralized quality management.
- Power Generation:Coal-to-biomass retrofit programs at Italian utilities are expanding SRF acceptance for co-firing applications with less stringent fuel specifications than cement. This segment is expanding most quickly as emissions trading pressure accelerates fuel-switching timelines beyond cement industry adoption rates.
- Industrial Heating:Manufacturing boilers in paper, steel, and chemical sectors utilize medium-grade SRF for process heat where flame stability requirements are less demanding than cement kilns. Regional supply contracts predominate due to logistics constraints.
- Waste Treatment:Dedicated waste-to-energy facilities consume lower-grade fuel fractions that fail cement or power generation specifications, operating under distinct emissions permitting frameworks.
Cement production commands specification premiums. Power generation is scaling fastest.
Processing Technology:
Capital intensity and output quality separate mechanical preprocessing from thermal and chemical upgrading alternatives. Dutch and Belgian operators have achieved cement-grade output through advanced mechanical sorting alone, compressing the addressable market for costlier thermal treatment.
- Mechanical Treatment:Shredding, screening, and optical sorting systems refine waste streams to specified particle sizes and remove contaminants without energy-intensive thermal processing. Near-infrared and X-ray transmission deployment in the Netherlands and Belgium enables real-time polymer separation and chlorine control.
- Thermal Treatment:Pyrolysis and gasification systems produce higher-grade outputs with tighter contaminant thresholds for premium cement applications. Capital requirements limit deployment to integrated waste operators with secured long-term offtake agreements.
- Biological Treatment:Anaerobic digestion and composting of biodegradable fractions reduces moisture content and stabilizes organic components prior to fuel preparation. Limited penetration in SRF-specific applications due to competing waste management pathways.
- Chemical Treatment:Solvent-based or chemical washing processes for chlorine and heavy metal reduction remain developmental, with pilot installations in Germany testing commercial viability against mechanical and thermal alternatives.
Mechanical treatment holds installed base dominance. Thermal treatment captures premium upgrade demand.
Quality Grade:
Calorific value stratification determines which end-use applications a fuel batch can serve and which preprocessing investments are required to achieve compliance. Higher grades command substantial price premiums that reward consistent quality control.
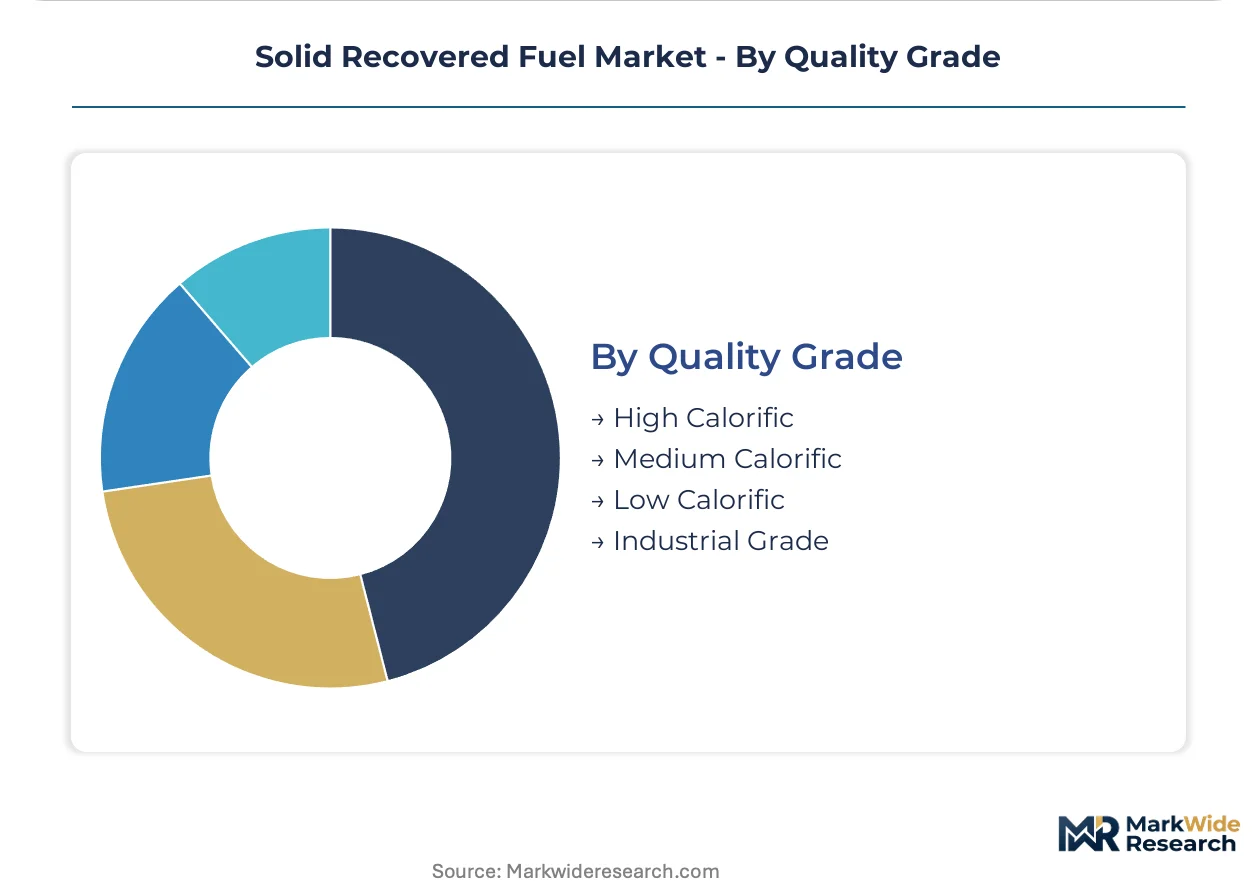
- High Calorific:Exceeding 20 MJ/kg with strict chlorine and heavy metal limits, this grade serves cement kiln substitution for coal in Germany and Poland. REACH compliance documentation requirements add administrative cost but secure premium pricing tiers.
- Medium Calorific:15-20 MJ/kg specifications suit power generation co-firing and industrial heating applications where flame stability requirements are less demanding. Italian utility retrofits are expanding procurement of this grade.
- Low Calorific:Below 15 MJ/kg with higher moisture and contaminant levels, this grade supplies waste-to-energy facilities and basic industrial boilers with limited alternative fuel options.
- Industrial Grade:Variable specifications negotiated per contract for dedicated industrial users with customized combustion equipment and emissions controls. United Kingdom manufacturing clusters utilize this grade for captive energy production.
High calorific grade captures margin premiums. Medium calorific is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale SRF production during the 1990s landfill diversion push, establishing the preprocessing standards and quality protocols that shaped European fuel certification frameworks.
Germany
Cement manufacturers in the Rhine-Ruhr and Bavaria regions drive procurement volume as EU ETS carbon pricing compresses coal economics. The Federal Immission Control Act implements Industrial Emissions Directive thresholds for waste-derived fuels. Mechanical treatment infrastructure clusters around Cologne and Munich, creating logistics bottlenecks for peripheral cement plants seeking consistent supply.
Poland
New cement kiln retrofits and waste collection network expansions create integrated supply corridors linking municipal streams to industrial demand. The country's national environmental regulator enforces tightening landfill diversion timelines under EU Waste Framework Directive implementation. Silesian cement producers are scaling co-firing capacity fastest among Eastern European markets.
United Kingdom
National cement groups consolidate SRF purchasing across multi-site operations under centralized quality management. Environment Agency permitting requirements for waste-derived fuels drive documentation standards upstream to collection contractors. Commercial paper waste networks in the Midlands and North England anchor feedstock supply for regional fuel preparation facilities.
Italy
Coal-to-biomass retrofit programs at utilities create SRF demand outside traditional cement kiln channels. The national environmental ministry transposes EU taxonomy criteria for waste-derived fuels into domestic procurement guidelines. Northern industrial clusters around Milan and Turin concentrate both preprocessing capacity and power generation offtake agreements.
Netherlands
Dutch waste processors deploy near-infrared and X-ray transmission systems to produce cement-grade SRF without thermal treatment investment. The Human Environment and Transport Inspectorate enforces REACH compliance documentation for cross-border fuel shipments. Rotterdam-area preprocessing facilities leverage port logistics to serve German and Belgian cement manufacturers.
Solid Recovered Fuel Market Vendor Landscape
Capital-heavy integrated waste operators compete with specialized fuel preparation contractors for long-term offtake agreements. Market structure tilts toward consolidation as cement manufacturers reduce supplier counts by half over recent contract cycles. Three archetypes dominate: multi-service environmental conglomerates with collection-to-fuel vertical control, dedicated mechanical treatment specialists with optical sorting capabilities, and regional waste-to-energy operators diversifying into fuel export. Competitive moves center on multi-site supply capability investments and centralized quality management system deployment.
Among European integrated operators, Veolia, SUEZ, and Renewi exemplify contrasting strategic positions. Veolia anchors the conglomerate archetype with waste collection infrastructure spanning France and Benelux. SUEZ occupies a position emphasizing thermal treatment expertise and industrial contract structures. Renewi represents dedicated mechanical treatment scale advantages through Dutch and Belgian facility concentration.
| Leading Market Players |
|---|
| Covanta |
| Renewi |
| Veolia |
| Dalkia |
| FCC Environment |
| SUEZ |
| Biffa |
| Recology |
| Waste Management |
| Others |
Supply Flow & Price Mechanics
EU ETS carbon permit pricing cascades through SRF procurement contracts, compressing coal substitution economics and stratifying fuel premiums across quality grades. Cement manufacturers in Germany and Poland now index long-term offtake agreements to carbon market benchmarks, transferring price volatility risk upstream to preprocessing operators.
Pricing Analysis
Long-term contract pricing with quality-adjusted escalators dominates cement procurement, separating high-calorific REACH-certified fuel from medium-grade utility co-firing supply. Price differentiation hinges on chlorine certification thresholds and multi-site supply capability. Cost compression in medium-calorific tiers is intensifying because Italian power generators are aggregating demand for less stringent specifications. Waste-to-energy facilities show highest price sensitivity; cement kiln operators least.
Supply Chain Analysis
Single-source vulnerability sits with German mechanical treatment infrastructure concentrated in the Rhine-Ruhr and Bavaria regions. Feedstock supply draws from municipal collection networks in Germany, the United Kingdom, and Poland, while preprocessing capacity rests on optical sorting equipment manufactured in the Netherlands and Belgium. Tariff exposure on cross-border waste shipments under revised Waste Framework Directive implementation creates regulatory friction. Distribution runs through dedicated bulk logistics corridors linking preprocessing facilities to cement plant storage silos.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Cement manufacturers are consolidating procurement around REACH-certified fuel specifications that only integrated operators can reliably deliver.
For Market Incumbents: Cement multi-site supply capability through backward integration into waste collection networks in Poland and Italy. Optical sorting capacity additions in the Benelux region defend against thermal treatment competitors. EU ETS price escalation threatens fragmented local suppliers lacking centralized quality management systems. For New Entrants and Emerging Players: Capture Italian power generation retrofit demand where fuel specifications remain less stringent than cement applications. Near-infrared sorting technology deployment offers a go-to-market angle for medium-calorific supply without thermal treatment capital requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with mechanical treatment specialists possessing optical separation IP and secured municipal collection contracts. Five-to-ten year viability favors operators with REACH compliance documentation systems already deployed. Watch for EU taxonomy criteria finalization as the inflection signal for premium grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Secures feedstock supply certainty for preprocessing facilities in Germany and Poland. |
| Optical Sorting Capacity Expansion | Enables cement-grade SRF production without capital-intensive thermal treatment investment. |
| REACH Compliance Certification Program | Unlocks premium pricing tiers and cross-border shipment eligibility under ECHA guidance. |
| Long-term Offtake Agreements with Cement Manufacturers | Locks in volume commitments as buyer concentration reduces supplier counts by half. |
| Multi-site Supply Capability Investment | Matches centralized procurement patterns of national cement groups in the United Kingdom. |
Methodological Framework
Multiple input streams — executive interviews with cement procurement directors, waste processor operations managers, and EU regulatory affairs specialists; secondary validation through ECHA guidance documents, EU Waste Framework Directive implementation timelines, and national environmental agency permitting records; plus customs data on cross-border waste shipments — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across supply-side capacity buildouts and demand-side fuel-switching investments anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include waste stream composition, processing technology tier, end-use industry specifications, and quality grade calorific thresholds. CAGRs were derived from facility-level capacity expansion announcements and cement kiln retrofit timelines. Forecast inputs incorporated EU ETS price trajectory assumptions and landfill diversion target enforcement schedules.
Carbon market volatility, REACH enforcement timing, and optical sorting technology cost curves are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about regulatory implementation and industrial fuel acceptance rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Europe Bunker Fuel Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
Marine Fuel Filter Market
Fuels
Liquid Propellants Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Gas Hydrates Market
Fuels
United States Coal Market
Fuels
South Africa Bunker Fuel Market
Fuels
South Korea LNG Bunkering Market
Fuels
Italy Automotive Engine Oils Market
Fuels
India LNG Market
Fuels
Oil Dispensing Stations Market
Fuels
LPG Vaporizer Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
Global Chemical Logistics Market
Fuels
Petroleum Fuel Dyes Sales Market