
 Smart Gas Metering Market | 2026-2036
Smart Gas Metering Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Gas Metering Market Insights
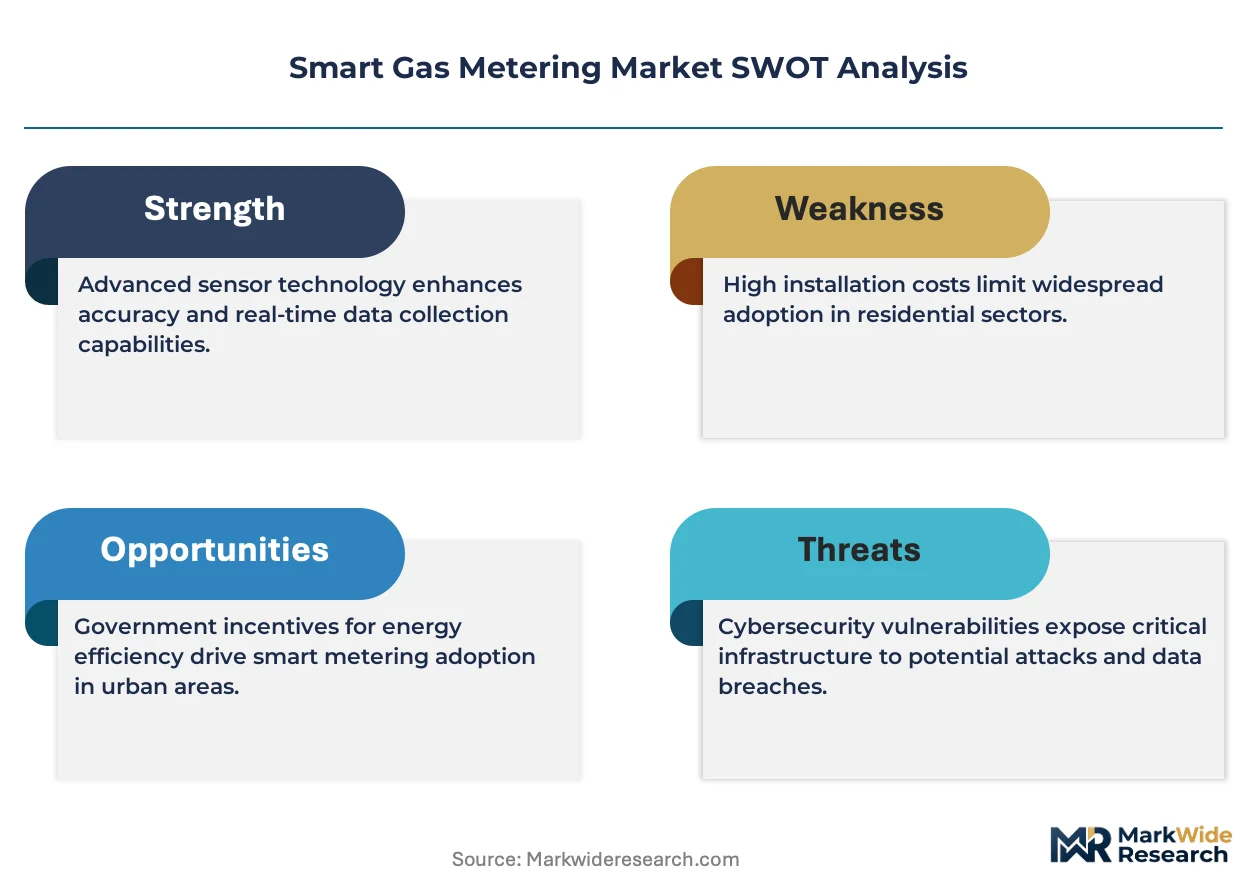
Embedded systems engineering talent is bifurcating the competitive landscape as vendors race to secure firmware and RF design capabilities for next-generation meter platforms. Honeywell International Inc. leverages its aerospace-derived sensor expertise to dominate high-precision residential meter segments. Itron Inc. sustains its North American channel control through deep utility relationships and end-to-end AMI software integration. Landis+Gyr anchors European market presence with manufacturing scale across Switzerland and Poland.
Smart gas metering encompasses automated measurement systems that combine diaphragm or ultrasonic flow sensors with integrated communication modules to transmit consumption data at 15-minute to hourly intervals to utility back-office systems. These devices enable remote reading, leak detection, and demand-response coordination while eliminating manual site visits. Residential Meters occupy the largest volume share as mass replacement cycles advance across mature utility markets. IoT-Enabled platforms represent the fastest-expanding technology segment as cellular NB-IoT and LoRaWAN radios displace legacy walk-by AMR systems. Commercial Meters concentrate margin pools where higher flow rates justify premium ultrasonic sensing and advanced pressure monitoring.
The EU Green Deal and F-Gas Regulation shape product roadmaps by mandating methane leak detection integration and refrigerant-free component specifications across European deployments. FDA cybersecurity guidance for networked industrial devices and FCC Part 15 radio certifications create dual compliance burdens for vendors selling into United States utility frameworks. Stakeholders must weigh cellular module standardization against proprietary mesh protocols as utilities lock in decade-long infrastructure commitments.
Market Dynamics
EU Green Deal mandates are forcing municipal gas utilities across Germany, Italy, and the United Kingdom to accelerate meter replacement cycles while cellular NB-IoT modules displace legacy walk-by AMR infrastructure, compressing procurement timelines and fragmenting vendor relationships.
Growth Catalysts
- EU Green Deal methane mandates:European utilities must integrate leak detection sensors into new meter deployments, creating pull for ultrasonic flow sensing platforms.
- AMI infrastructure rollout:Germany's SWM and Italy's Hera Group are expanding back-office integration, driving demand for end-to-end software-hardware bundles.
- Cellular module cost curves:NB-IoT radio prices are falling as semiconductor foundries scale production for European utility tenders.
Market Restraints
- Semiconductor supply concentration:RF transceiver fabrication depends on a handful of East Asian foundries, exposing meter vendors to allocation risk.
- FCC Part 15 certification friction:United States market entry requires extended radio equipment authorization timelines that delay revenue recognition.
- Legacy diaphragm meter substitution:Existing mechanical meters in Eastern European housing stock resist replacement due to sunk capital and installation labor constraints.
Strategic Opportunities
- Poland manufacturing scale:Landis+Gyr's Swiss-Polish production corridor offers tariff-advantaged export positioning into EU accession markets.
- Commercial meter premium tier:Ultrasonic sensing with pressure monitoring commands higher margins in industrial boiler applications across the United Kingdom.
- LoRaWAN-Cellular convergence:Hybrid radio architectures are opening private network deployments for Italian utilities seeking operator independence.
Industry Challenges
- Firmware engineering scarcity:Embedded systems talent with RF stack expertise commands premium compensation, constraining vendor R&D throughput.
- Legacy system integration complexity:Utilities in Germany require backward compatibility with decades-old billing platforms, extending deployment timelines.
- Cybersecurity certification burden:FDA guidance for networked industrial devices and GDPR data protection rules create overlapping compliance audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Gas Metering Market |
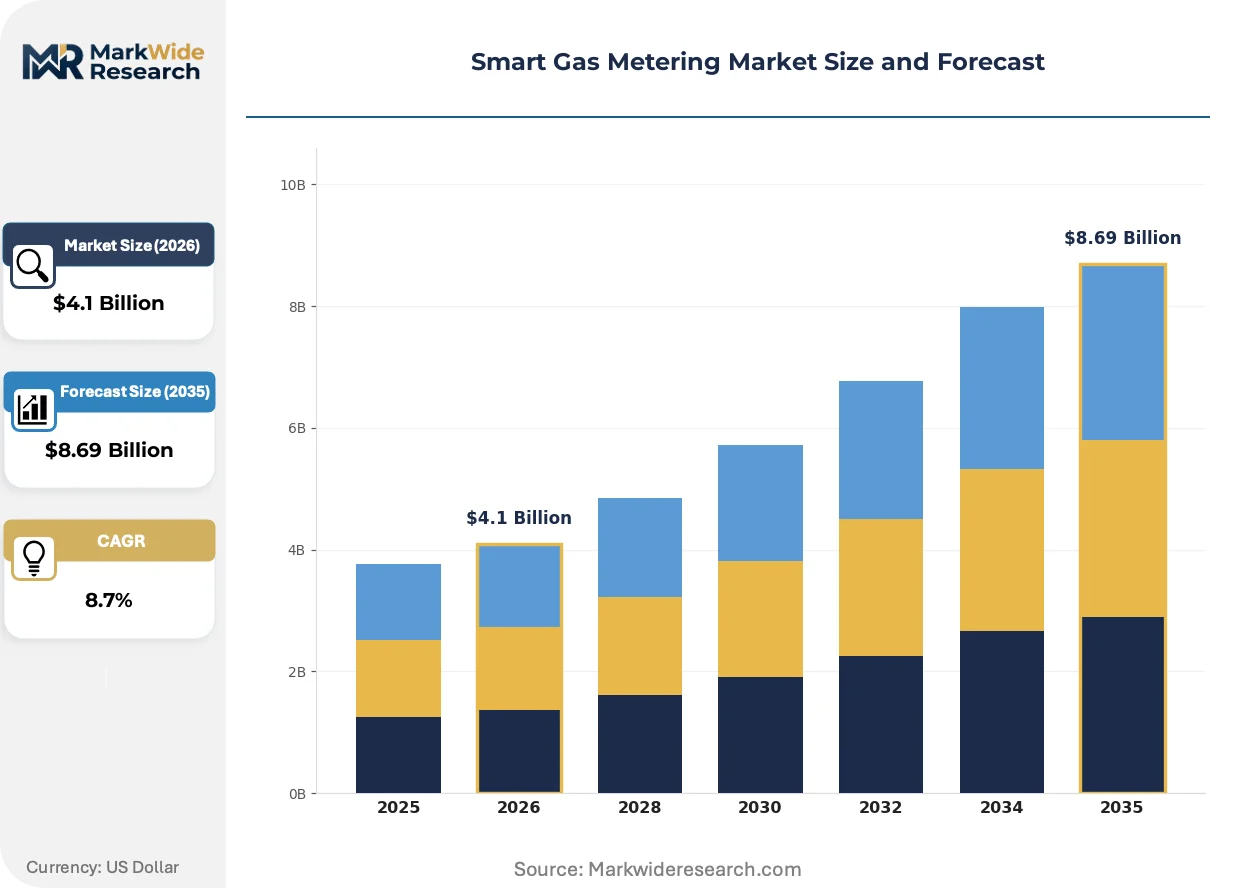
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Meters, Commercial Meters, Industrial Meters, Smart Modules Technology: Wireless Communication, Wired Communication, Hybrid Solutions, IoT-Enabled End User: Utility Companies, Industrial Facilities, Residential Customers, Commercial Establishments Deployment: Cloud-Based, On-Premises, Hybrid Model, Remote Monitoring |
| Companies Covered | Honeywell International Inc., Itron Inc., Landis+Gyr, Diehl Stiftung & Co. KG, Apator S.A., Sensus, ABB Ltd, Schneider Electric, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Gas Metering Market Trends and Innovations
Wireless communication architectures are fragmenting competitive positioning as utilities abandon proprietary mesh protocols for standardized cellular radios, while regulatory pressure on methane emissions forces sensor fusion into meter hardware.
Ultrasonic flow sensing is fragmenting the residential meter landscape. These solid-state devices measure gas velocity without mechanical wear, eliminating diaphragm replacement cycles. German utilities E.ON and EnBW are piloting ultrasonic platforms in high-turnover rental housing. The technology is fragmenting vendor tiers by rewarding RF-integrated firmware capabilities over mechanical engineering heritage.
F-Gas Regulation refrigerant-free mandates are reshaping European product roadmaps. The rule bans hydrofluorocarbon components in meter electronics, forcing vendors to redesign thermal management. Swiss and Polish manufacturing lines are retooling for compliant component sourcing. Meter suppliers serving Italy and the United Kingdom face compressed redesign timelines ahead of enforcement deadlines.
Utility procurement is consolidating around AMI software integration requirements. German municipal utilities now specify end-to-end platform compatibility as a gate criterion, displacing standalone hardware bids. Systems integrators with back-office software assets are capturing tender evaluation weight. This pattern is most visible in the United Kingdom, where Ofgem regulatory reporting requirements favor unified data architectures.
Smart Gas Metering Market Segmentation
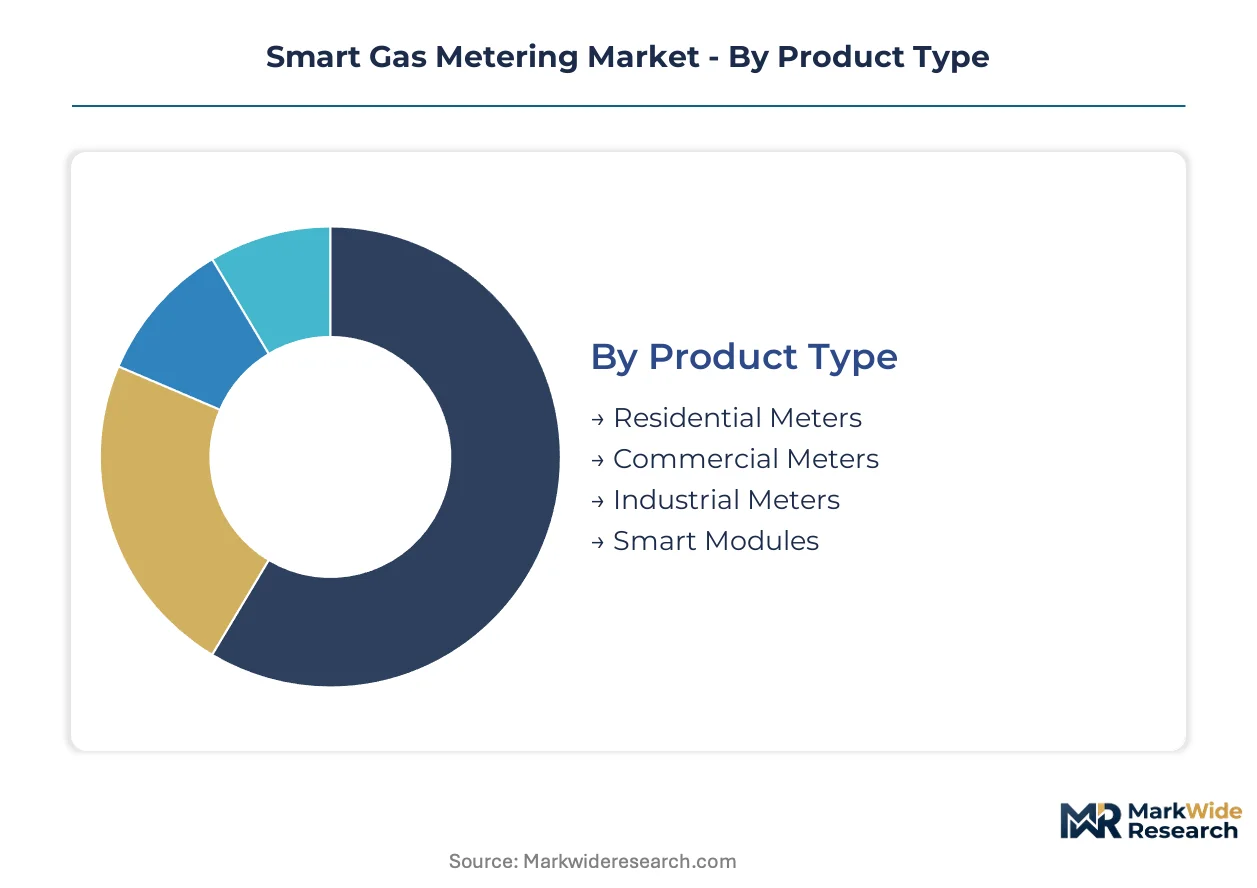
Segmentation in smart gas metering reveals how procurement patterns diverge across utility archetypes and infrastructure maturity levels. Vendors must align R&D portfolios with the specific compliance burdens and connectivity requirements that define each category.
Product Type:
Diaphragm meter displacement pressure varies sharply across segments, with ultrasonic platforms threatening mechanical incumbent positions in high-turnover housing markets.
- Residential Meters:Diaphragm and ultrasonic flow sensors integrate with NB-IoT or LoRaWAN modules to enable 15-minute interval data transmission. Mass replacement cycles across German municipal utilities concentrate procurement volume here, though F-Gas refrigerant-free mandates compress redesign timelines for electronics thermal management.
- Commercial Meters:Higher flow rates justify premium ultrasonic sensing with integrated pressure monitoring for industrial boiler applications. United Kingdom utilities specify these for Ofgem regulatory reporting compliance, creating margin pools that reward advanced firmware capabilities over mechanical heritage.
- Industrial Meters:High-capacity flow measurement with redundant sensor arrays for safety-critical petrochemical feed lines.
- Smart Modules:Retrofit communication attachments extending legacy diaphragm meter lifecycles in Eastern European housing stock with sunk capital constraints.
Residential Meters anchors the volume base while Smart Modules gains share at the steepest rate as utilities defer full fleet replacement.
Technology:
Radio architecture choices lock utilities into decade-long infrastructure commitments, with proprietary mesh protocols facing accelerated displacement.
- Wireless Communication:Cellular NB-IoT and LoRaWAN radios eliminate manual walk-by reading requirements. Germany's SWM and Italy's Hera Group are consolidating procurement around these standards as AMI back-office integration becomes a tender gate criterion.
- IoT-Enabled:Cloud-native meter platforms with edge computing capabilities for real-time leak detection and demand-response coordination. EU Green Deal methane mandates are pulling these into new deployments across United Kingdom and Italian utility frameworks.
- Wired Communication:Power-line carrier and RS-485 bus architectures for high-security industrial sites with electromagnetic interference constraints.
- Hybrid Solutions:Dual-radio configurations combining cellular primary with mesh fallback for Italian utilities seeking operator independence.
Wireless Communication dominates current procurement volumes while IoT-Enabled platforms are climbing the fastest as regulatory pressure intensifies.
End User:
Customer sophistication tiers determine whether vendors sell standalone hardware or end-to-end platform bundles.
- Utility Companies:Municipal gas distributors with AMI software integration requirements that displace standalone hardware bids. German utilities now specify backward compatibility with legacy billing platforms as mandatory, extending deployment timelines.
- Commercial Establishments:Property management groups and retail chains seeking submetering for tenant billing transparency. United Kingdom deployment patterns concentrate here due to Ofgem market opening regulations.
- Industrial Facilities:Petrochemical and food processing plants with high-availability requirements and SCADA integration needs.
- Residential Customers:Individual homeowners in new-build housing where developer-installed meters precede utility takeover.
Utility Companies command the procurement volume while Commercial Establishments show the steepest expansion trajectory as submetering regulations spread.
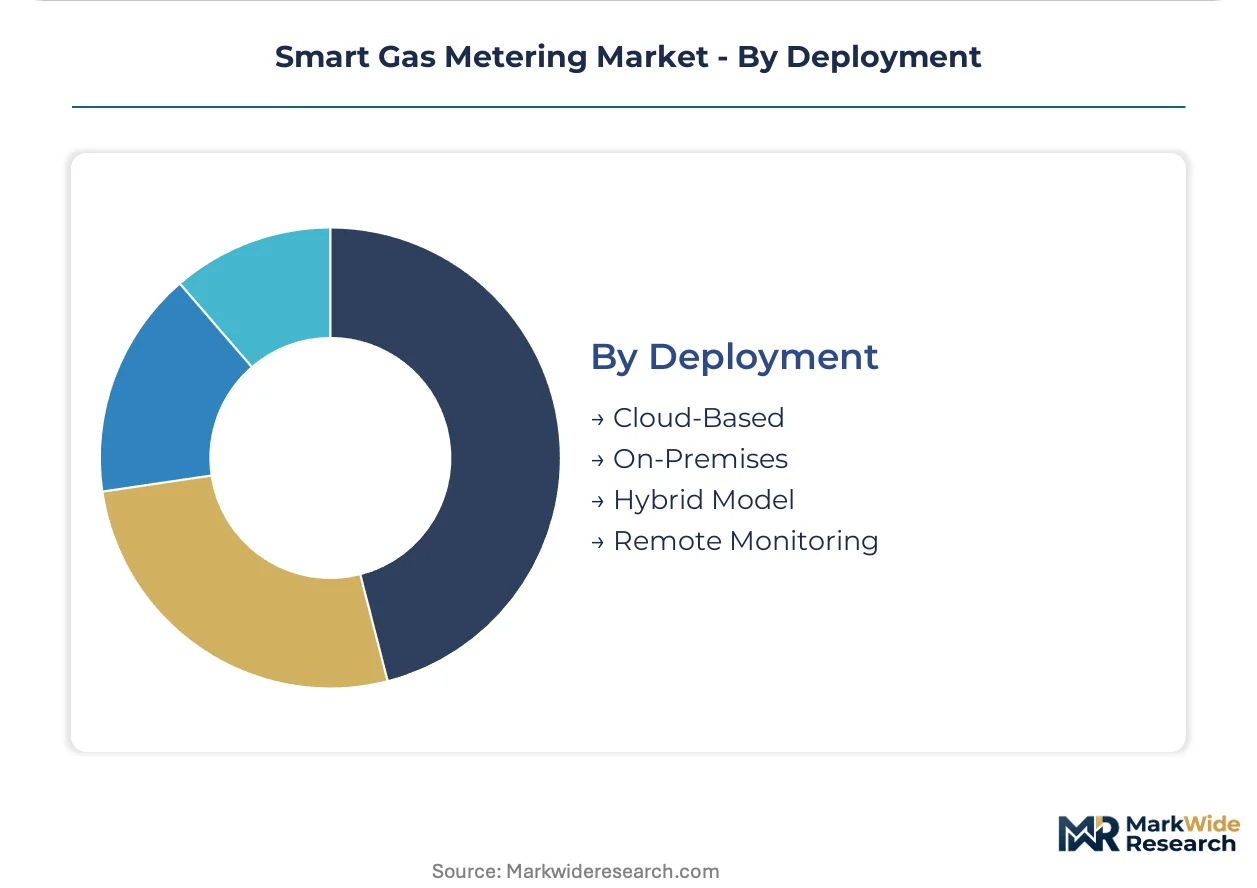
Deployment:
Data sovereignty requirements and cybersecurity certification burdens are fragmenting architecture choices across European national frameworks.
- Cloud-Based:Utility-managed SaaS platforms with GDPR-compliant EU data residency. German municipal utilities favor these for reduced IT overhead, though FDA cybersecurity guidance for networked industrial devices creates dual compliance audits for vendors.
- On-Premises:Air-gapped server installations for critical infrastructure operators with national security mandates. Italian and Polish utilities specify these where data localization laws apply.
- Hybrid Model:Edge processing with cloud analytics tier for bandwidth-constrained rural networks.
- Remote Monitoring:Third-party managed service contracts with SLA-backed uptime guarantees for smaller UK utilities lacking internal IT capacity.
Cloud-Based deployments anchor current investment while Hybrid Model configurations are expanding most quickly as utilities balance sovereignty with scalability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal methane mandates are concentrating deployment momentum in European municipal gas utilities, while FCC Part 15 certification timelines shape vendor entry into North American frameworks.
Germany
SWM Munich and EnBW Stuttgart are piloting ultrasonic platforms in high-turnover rental housing under accelerated replacement schedules. The country's national energy regulator mandates backward compatibility with legacy billing platforms, extending procurement cycles. Manufacturing clusters in Bavaria and North Rhine-Westphalia host retooling operations for F-Gas refrigerant-free component specifications.
United Kingdom
Ofgem market opening regulations are driving submetering demand among property management groups and retail chains. The national energy regulator requires unified data architectures for regulatory reporting compliance. London and Southeast England concentrate commercial meter deployments where premium ultrasonic sensing with pressure monitoring commands higher margins.
Italy
Hera Group and other municipal utilities are consolidating procurement around NB-IoT and LoRaWAN standards as AMI back-office integration becomes mandatory. The country's data protection authority enforces GDPR-compliant data residency for cloud-based deployments. Northern industrial clusters around Milan and Turin anchor hybrid radio architecture pilots combining cellular primary with mesh fallback.
United States
FERC grid modernization incentives and state-level decarbonization targets are pulling smart gas metering into utility capital plans. FDA cybersecurity guidance for networked industrial devices creates dual compliance audits alongside FCC Part 15 radio equipment authorization requirements. Texas and California municipal utilities lead procurement volume, though extended certification timelines delay vendor revenue recognition.
Poland
EU accession market access and tariff-advantaged export positioning are attracting manufacturing scale investments. The country's national standards body aligns certification requirements with EU Green Deal implementation timelines. Swiss-Polish production corridors serving Eastern European housing stock concentrate smart module retrofits where full meter replacement faces sunk capital constraints.
Smart Gas Metering Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the smart gas metering landscape. The vendor base organizes into three tiers: diversified industrial conglomerates with aerospace-derived sensor expertise, pure-play metering specialists with deep utility software integration, and regional fabricators with manufacturing scale advantages. Consolidation pressure is intensifying as AMI procurement shifts from standalone hardware to end-to-end platform bundles. Strategic moves center on RF firmware capability acquisition and cellular module supply partnerships.
Within the diversified industrial tier, Honeywell International Inc. and ABB Ltd occupy positions anchored by cross-divisional technology transfer. Among metering specialists, Itron Inc. and Landis+Gyr exemplify archetypes differentiated by geographic channel control and manufacturing footprint configuration. Diehl Stiftung & Co. KG represents the European family-owned fabrication model with integrated component sourcing.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Itron Inc. |
| Landis+Gyr |
| Diehl Stiftung & Co. KG |
| Apator S.A. |
| Sensus |
| ABB Ltd |
| Schneider Electric |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Foundry scale economies in Taiwan and South Korea are compressing NB-IoT radio module costs while simultaneously concentrating vendor bargaining power among a handful of semiconductor suppliers. This dual dynamic establishes price floors for smart meter OEMs and shapes procurement strategies across European utility tenders.
Pricing Analysis
Geographic price spreads of 15-25 percent separate Swiss-manufactured ultrasonic platforms from Polish-assembled diaphragm units across EU accession markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FCC Part 15 and EU Green Deal compliance tiers commanding substantial premiums. Pricing pressure stems from cellular module commoditization as semiconductor foundries scale production for utility tenders. Municipal utilities in Eastern Europe exhibit highest price sensitivity due to sunk capital constraints, while German SWM-class operators prioritize AMI integration over unit cost.
Supply Chain Analysis
Inventory lead times for RF transceivers have extended to 26-32 weeks as East Asian foundries allocate capacity to automotive and consumer electronics. Semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China, with meter electronics assembly anchored in Switzerland, Poland, and Mexico. Raw material dependencies span silicon wafers, lithium primary cells, and fluoropolymer-free thermal interface materials under F-Gas Regulation mandates. Single-source vulnerability in 5G NB-IoT modem chipsets exposes vendors to allocation risk during demand surges. Distribution runs through authorized utility channel partners with decade-long framework agreements rather than open distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as AMI procurement shifts from standalone hardware to end-to-end platform bundles, creating service-layer niches where pure-play software integrators can outmaneuver diversified industrial conglomerates.
For Market Incumbents: Consolidate firmware engineering capabilities through targeted acquisition of RF stack specialists, as embedded systems talent scarcity constrains R&D throughput. Secure captive supply agreements with Taiwan-based foundries to mitigate semiconductor allocation risk during demand surges. Deepen backward integration into ultrasonic sensor fabrication to defend margin position against commercial meter challengers. For New Entrants and Emerging Players: Firmware customization services for legacy billing platform integration represent a service-layer gap where incumbents under-serve German municipal utilities with decades-old infrastructure. Target Polish manufacturing corridors for tariff-advantaged export positioning into EU accession markets with deferred full-fleet replacement cycles. Pursue white-label smart module partnerships with Eastern European utilities seeking retrofit alternatives to sunk capital constraints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among AMI software platform providers with decade-long utility framework agreements and SaaS-tiered service contracts. Long-term viability favors vendors with demonstrated EU Green Deal compliance roadmaps and F-Gas Regulation-ready thermal management redesigns. Acquisition target archetype: mid-cap metering specialists with cellular module supply partnerships but underdeveloped back-office software assets. Watch for inflection in LoRaWAN-Cellular hybrid procurement patterns as Italian utilities seek operator independence.| Strategic Initiative | Industry Significance |
|---|---|
| RF Firmware Capability Acquisition | Embedded systems talent scarcity constrains vendor R&D throughput across ultrasonic platform development. |
| Cellular Module Supply Partnership | Foundry allocation risk in Taiwan and South Korea threatens production continuity for European tenders. |
| AMI Software Platform Integration | German municipal utilities now specify end-to-end compatibility as mandatory tender gate criterion. |
| F-Gas Regulation Compliance Redesign | Refrigerant-free thermal management mandates force component sourcing retooling across Swiss-Polish corridors. |
| Commercial Meter Premium Tier Expansion | United Kingdom Ofgem reporting requirements reward advanced pressure monitoring in industrial boiler applications. |
Research Methodology
Desk research of EU regulatory filings, FCC equipment authorization databases, and utility tender documentation preceded structured interviews with municipal utility planning officers, AMI systems integrators, semiconductor procurement leads, and embedded firmware engineering directors. Primary fieldwork across Germany, Italy, the United Kingdom, and Poland validated secondary data on replacement cycle timelines and technology adoption patterns. Bottom-up unit shipment estimates triangulated against top-down utility capital expenditure disclosures.
Variance decomposition across product type, technology architecture, end-user sophistication, and deployment model dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from logistic diffusion curves fitted to AMI infrastructure rollout schedules and cellular module cost trajectories. Forecast inputs incorporated EU Green Deal methane mandate enforcement timelines, F-Gas Regulation redesign deadlines, and NB-IoT network coverage expansion by national operators.
Forecasts assume regulatory continuity in EU Green Deal implementation and FCC Part 15 certification regimes; material policy shifts would require re-modeling deployment timelines and compliance cost burdens. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
Smart Gas Meter Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Smart Meter Battery Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
United States Smart Meter Market
Smart Meters
Power Quality Meter Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
Solar Meter Market
Smart Meters
Global Smart Electricity Meter Market
Smart Meters
Europe Smart Meters Market
Smart Meters
North America Gas Meter Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
United States (US) Residential Smart Meters Market