
 Polysulfide Elastomers Market | 2026-2036
Polysulfide Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Polysulfide Elastomers Market Intelligence
The specialized chemical formulation expertise for high-performance sealants is bifurcating the available talent pool between polymer synthesis and application-specific compounding. PPG Industries leverages its deep history in aerospace coatings to develop advanced sealant solutions. Toray Fine Chemicals specializes in the production of core thiol-based polymers, a critical precursor. Sika AG sustains a strong position in construction markets through its extensive channel access.
Polysulfide elastomers are synthetic polymers characterized by alternating sulfur-sulfur linkages within their main chain, providing exceptional fuel and chemical resistance. This unique structure allows for flexibility at low temperatures, making them ideal for sealing applications in harsh environments. Liquid polysulfide formulations constitute the largest product type, primarily for producing high-performance sealants. The aerospace end-user segment represents a high-margin area, driven by rigorous performance and safety certifications.
Product formulation and market access are shaped by stringent chemical control policies, including the EU's REACH regulation and VOC limits set by the US EPA. Adherence to performance specifications, such as ISO 11600 for construction sealants, is also mandatory for market entry in many regions. Stakeholders must now balance the need for high-performance materials against an increasingly complex and fragmented regulatory landscape to maintain market position.
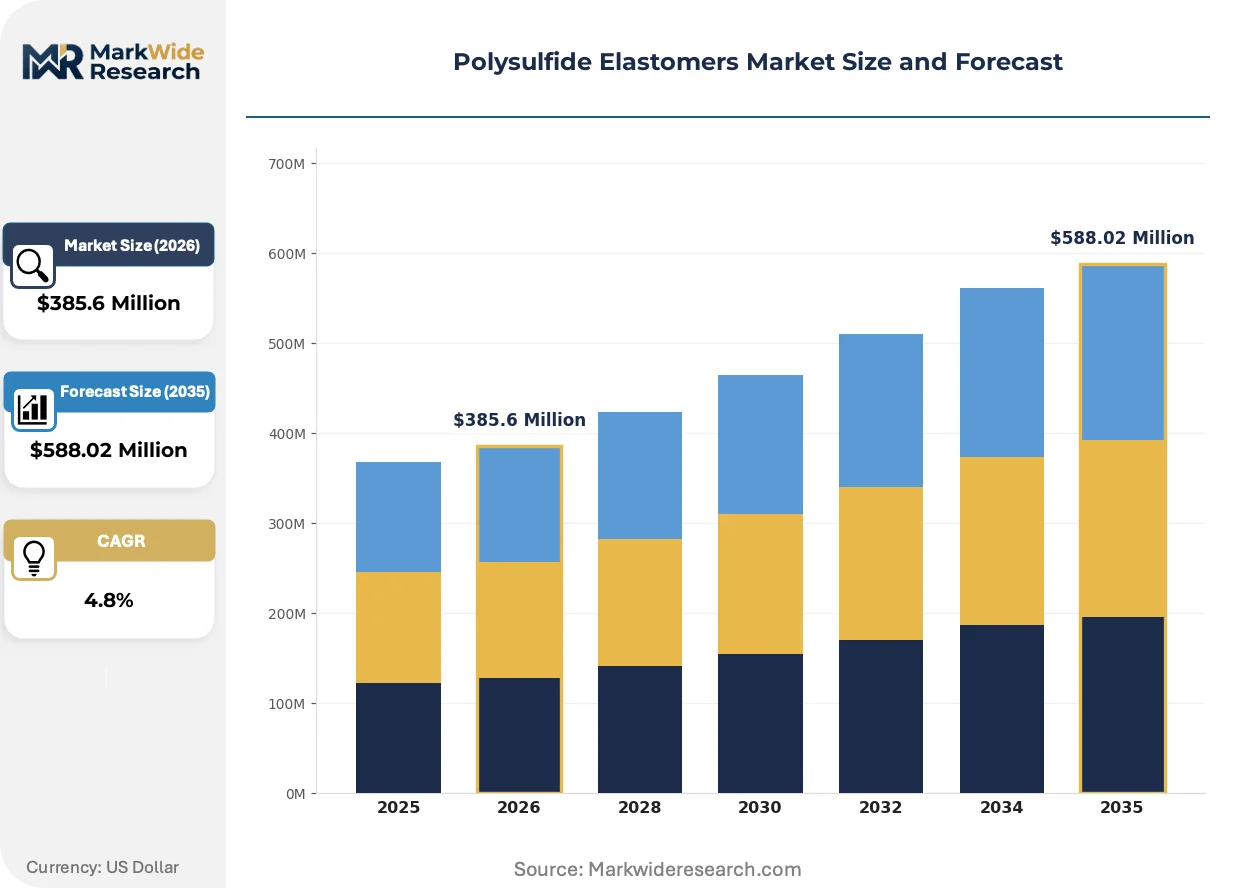
Market Dynamics
The push for high-performance characteristics in aerospace and automotive applications is running parallel to intensifying chemical substance regulations under frameworks like the EU's REACH. This dual pressure defines formulation innovation and market access strategies for polysulfide elastomers, forcing a balance between material capability and environmental compliance.
Growth Catalysts
- Aerospace Sector Demand:The global aerospace industry requires high-performance sealants with exceptional fuel and chemical resistance for applications in aircraft wing tanks and fuselage structures, providing a consistent demand stream for polysulfide-based products.
- German Construction Standards:Advanced construction and civil engineering projects in Germany mandate the use of durable joint sealants that comply with performance specifications like ISO 11600, favoring high-performance polysulfide formulations.
- VOC Regulations:Increasingly strict volatile organic compound (VOC) limits established by the US EPA are promoting the adoption of high-solid, liquid polysulfide formulations as alternatives to traditional solvent-based sealant technologies.
Market Restraints
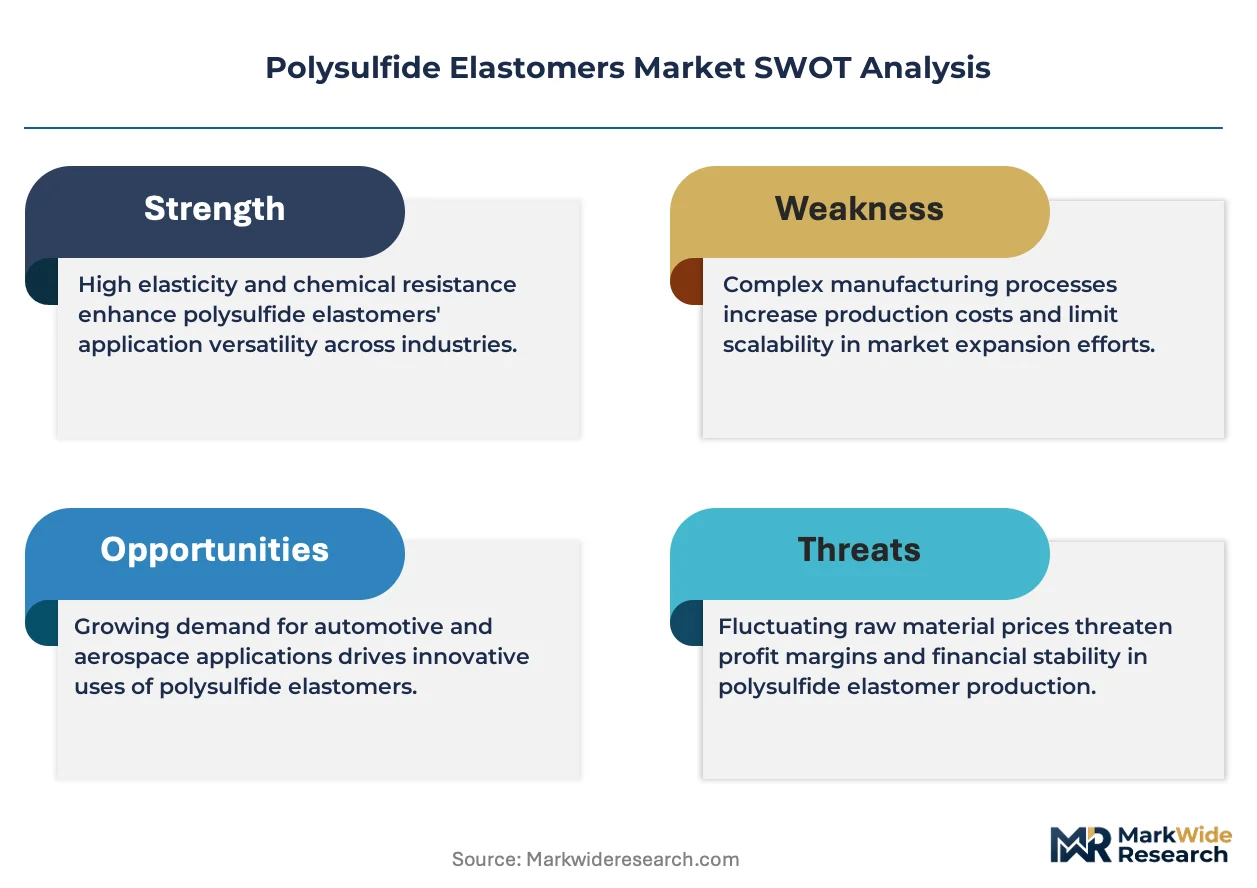
- Raw Material Volatility:Price fluctuations in sulfur, a fundamental raw material for polysulfide polymer synthesis, introduce cost instability and margin pressure for manufacturers, impacting overall product pricing strategies.
- Substitution from Alternatives:In less demanding construction and general industrial applications, lower-cost silicone and polyurethane sealants present a significant substitution threat, constraining the market scope for premium polysulfide products.
- Regulatory Compliance Burden:The complex registration and authorization processes for thiol-based precursors under the EU's REACH framework create substantial compliance costs and administrative hurdles, acting as a barrier to market entry.
Strategic Opportunities
- Energy-Efficient Buildings:Formulation of polysulfide-based sealants for insulating glass units (IGUs) creates an opportunity to penetrate the growing market for energy-efficient windows and building facades.
- Middle East Infrastructure:Large-scale infrastructure and construction developments in countries like Saudi Arabia and the UAE represent an underpenetrated geographic market for high-performance construction and civil engineering sealants.
- Automated Application Systems:Developing low-viscosity, fast-curing polysulfide formulations compatible with robotic application systems can unlock efficiencies for automotive manufacturers on their assembly lines.
Industry Challenges
- Specialized Talent Scarcity:A shortage of polymer chemists and formulation scientists with dual expertise in thiol polymer synthesis and application-specific sealant compounding creates a significant human capital constraint for product development.
- Aerospace Certification Timelines:The lengthy and rigorous testing and certification process required to qualify new sealant materials for aerospace applications can significantly delay new product introductions and revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysulfide Elastomers Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Polysulfide, Solid Polysulfide, Semi-Solid Polysulfide, Coatings End User: Aerospace, Automotive, Construction, Electronics Application: Adhesives, Sealants, Gaskets, Moldings Delivery Mode: Chemical Distribution, Direct Supply, Retail, Others |
| Companies Covered | LANXESS, Nouryon, PPG Industries, Sika AG, Akzo Nobel N.V., Toray Fine Chemicals, Henkel AG & Co., LORD Corporation, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysulfide Elastomers Market Strategic Shifts & Innovations
Formulation science is advancing towards materials that meet stringent performance criteria while addressing environmental and health regulations. This evolution is most visible in the development of next-generation precursors and sealant systems designed for both manufacturing efficiency and in-service compliance.
Liquid thiol-based polymers are the critical precursors for two-part sealant formulations, enabling the cure reaction that provides flexibility and chemical resistance. The aerospace sector rapidly adopts these for high-performance fuel tank sealants, while the construction sector's adoption is more gradual and cost-sensitive. This differential adoption rate, driven by performance requirements, is bifurcating the available talent pool between polymer synthesis experts and application-specific compounders.
The European Union's REACH regulation imposes strict controls on the use of certain chemical substances, including some catalysts and plasticizers used in polysulfide formulations. This forces manufacturers to invest heavily in research for compliant alternatives without compromising sealant performance, such as fuel resistance or low-temperature flexibility. European construction and automotive segments are most affected, leading to a reformulation cycle focused on REACH-compliant materials.
A shift towards performance-based specifications is altering procurement criteria within the construction industry. Generic, low-cost sealants are being displaced in high-rise and infrastructure projects by products that can demonstrate long-term durability and adherence to standards like ISO 11600. This trend is particularly evident in Germany and other parts of Western Europe with advanced building codes that prioritize structural longevity.
Polysulfide Elastomers Market Segmentation
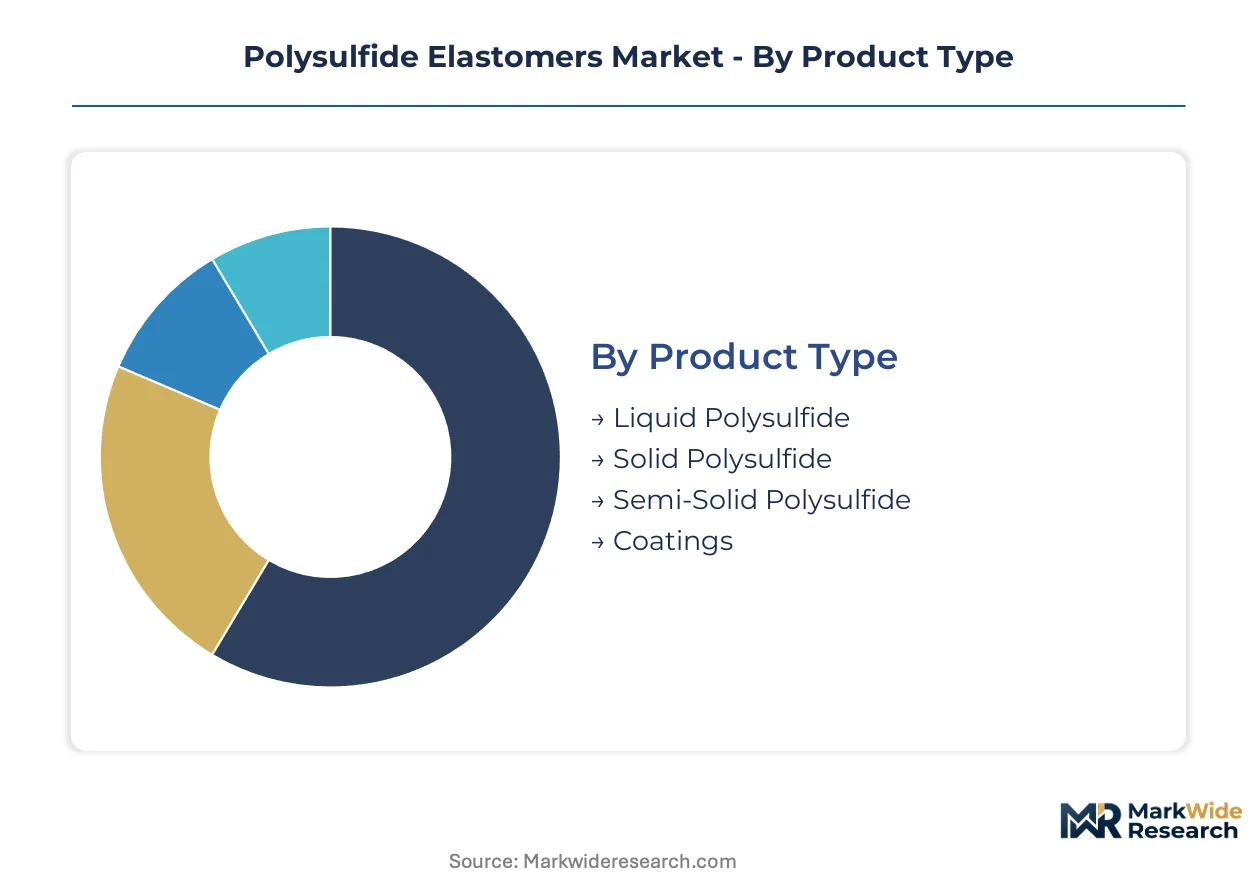
Understanding the polysulfide elastomers market through detailed segmentation reveals distinct value propositions and competitive landscapes. Each segment reflects unique material requirements, processing demands, and regulatory compliance pathways for manufacturers. This granular view assists stakeholders in identifying high-growth niches and formulating targeted market strategies.
Product Type:
Regulatory frameworks significantly influence product type development within the polysulfide elastomers market.
- Liquid Polysulfide:These are low-viscosity, two-part systems, curing at room temperature to form flexible elastomers. The aerospace sector consistently demands liquid polysulfide for high-performance fuel tank sealants, driven by rigorous safety certifications.
- Solid Polysulfide:These high molecular weight polymers are processed as rubber, offering high tensile strength and abrasion resistance. German automotive manufacturers utilize solid polysulfides for durable seals and gaskets, ensuring longevity in vehicle components.
- Semi-Solid Polysulfide:These formulations bridge the gap between liquid and solid types, offering enhanced thixotropy for specific sealing applications.
- Coatings:Polysulfide-based coatings provide exceptional chemical and corrosion resistance, protecting surfaces in harsh industrial environments.
Liquid Polysulfide handles the majority of throughput; Coatings is the fastest mover on share.
End User:
Application-specific performance demands dictate the suitability of polysulfide elastomers across diverse end-user sectors.
- Aerospace:This sector requires polysulfide elastomers for fuel-resistant sealants and adhesives in aircraft structures. The global aerospace industry's stringent performance and safety standards drive high-margin demand for specialized polysulfide products.
- Construction:Polysulfide sealants offer long-term durability and weather resistance for building joints and infrastructure projects. Advanced construction projects in Germany mandate polysulfide formulations for durable joint sealants, adhering to ISO 11600 specifications.
- Automotive:Polysulfide elastomers provide chemical resistance and flexibility for automotive gaskets, hoses, and sealants, especially in fuel systems.
- Electronics:In the electronics industry, polysulfide compounds are used for encapsulants and potting materials, protecting sensitive components from environmental factors.
Construction end users generate significant volume; Aerospace end users command premium value.
Application:
The volume of polysulfide elastomer consumption varies considerably across different application areas.
- Sealants:Polysulfide sealants form flexible, chemically resistant barriers, preventing leaks and protecting against environmental degradation. The aerospace industry is a primary consumer of high-performance polysulfide sealants for integral fuel tanks, requiring extreme chemical resistance.
- Adhesives:Polysulfide-based adhesives offer strong bonding with excellent fuel and chemical resistance, suitable for demanding industrial assemblies. Automotive manufacturing uses polysulfide adhesives for bonding dissimilar materials, enhancing structural integrity and durability.
- Gaskets:Polysulfide elastomers are formulated into resilient gaskets that provide effective sealing in environments exposed to oils, fuels, and solvents.
- Moldings:Polysulfide compounds are molded into custom shapes for specialized components requiring chemical resistance and low-temperature flexibility.
Sealants show broad market penetration; Gaskets are expanding most quickly.
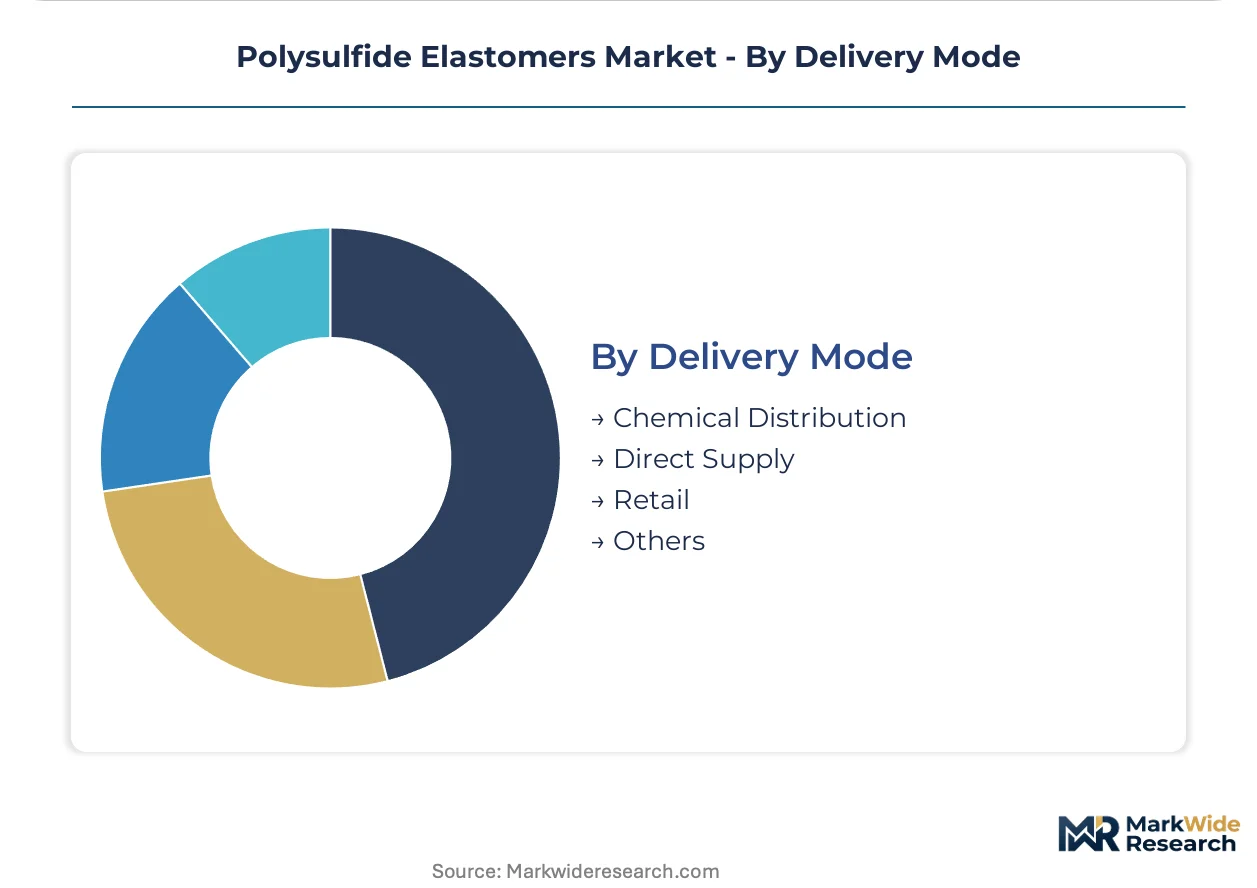
Delivery Mode:
Different customer types necessitate varied delivery modes for polysulfide elastomers.
- Chemical Distribution:This mode involves third-party distributors stocking and supplying polysulfide raw materials and formulated products to various end-users. Smaller manufacturers and specialized formulators often rely on chemical distribution for efficient access to diverse polysulfide grades.
- Direct Supply:Large-volume customers procure polysulfide elastomers directly from manufacturers, often under long-term contracts. Major aerospace and automotive OEMs frequently engage in direct supply agreements to ensure consistent material quality and supply chain control.
- Retail:Retail channels offer smaller quantities of polysulfide-based sealants and repair kits to individual consumers and small businesses.
- Others:This category encompasses specialized delivery methods, including custom blending services and just-in-time delivery for specific industrial clients.
Direct Supply offers efficiency for large clients; Chemical Distribution provides extensive market reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global consumption patterns for polysulfide elastomers vary significantly by region. While some geographies prioritize high-performance aerospace applications, others focus on construction durability or automotive chemical resistance. This regional divergence in end-use drives distinct material formulation and market access strategies.
Germany
Demand for polysulfide sealants in Germany stems from its advanced automotive and construction sectors. German building codes, like those referenced in ISO 11600, mandate durable joint sealants for infrastructure projects. The automotive manufacturing hubs in Bavaria and Baden-Württemberg utilize solid polysulfides for critical sealing components.
United States
Aerospace and specialized industrial applications drive significant polysulfide elastomer demand in the United States. The US EPA's stringent VOC limits encourage the adoption of high-solid liquid polysulfide formulations. Aerospace clusters in Washington State and California continuously seek advanced fuel tank sealants.
United Arab Emirates
Large-scale infrastructure and construction developments in the United Arab Emirates create opportunities for high-performance sealants. The Dubai Municipality's building regulations emphasize long-term material durability for new projects. Major construction sites in Dubai and Abu Dhabi require robust polysulfide formulations for extreme environmental conditions.
China
China's expanding construction and industrial manufacturing sectors fuel a growing demand for polysulfide elastomers. The Ministry of Environmental Protection (MEE) regulations increasingly influence material specifications for sealants. Industrial parks in the Yangtze River Delta integrate polysulfide products into diverse applications, from automotive to electronics.
Japan
Japanese automotive and electronics industries require specialized polysulfide formulations for high-reliability components. METI guidelines promote material innovation for improved performance and environmental compliance in manufacturing. The industrial regions around Tokyo and Nagoya integrate polysulfide elastomers into advanced sealing and encapsulation solutions.
Polysulfide Elastomers Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the polysulfide elastomers market. This tiered structure reflects the capital intensity of polymer synthesis and the specialized formulation expertise required for end-use applications. Strategic archetypes include large chemical conglomerates, dedicated sealant formulators, and niche polymer producers. Companies pursue competitive advantage through capacity expansion and strategic partnerships to secure raw material supply or expand market access.
On the premium-tier vector, PPG Industries exemplifies a company leveraging its deep history in high-performance coatings to develop advanced sealant solutions. Toray Fine Chemicals, a Japanese chemical manufacturer, occupies a position as a critical precursor producer specializing in thiol-based polymers for a global customer base. Sika AG, a Swiss multinational, anchors the construction market segment through its extensive channel access for specialized building materials. These entities collectively represent the varied strategic approaches required to succeed in both upstream polymer supply and downstream application-specific formulation.
| Leading Market Players |
|---|
| LANXESS |
| Nouryon |
| PPG Industries |
| Sika AG |
| Akzo Nobel N.V. |
| Toray Fine Chemicals |
| Henkel AG & Co. |
| LORD Corporation |
| Arkema |
| Others |
Cost & Logistics Intelligence
Substitution from lower-cost silicone and polyurethane sealants reshapes supply geography and pricing economics for polysulfide elastomers. This dynamic forces manufacturers to balance material capability with cost efficiency, particularly in less demanding applications.
Pricing Analysis
Long-term offtake agreements characterize pricing for specialized polysulfide elastomers in aerospace and automotive sectors. Price differentiation stems from rigorous performance certifications and application-specific customization requirements. Raw material volatility, particularly for sulfur, contributes to pricing softness. Construction and general industrial end-users demonstrate higher price sensitivity compared to the aerospace segment.
Supply Chain Analysis
Inbound logistics costs, influenced by global shipping rates and container availability, impact the polysulfide elastomer supply chain. Key manufacturing and consumption centers include Germany, the United States, and China, drawing critical thiol-based polymers from specialists like Toray Fine Chemicals in Japan. Commodity price volatility for sulfur presents a structural risk. Distribution runs through direct supply for major clients and chemical distributors for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polysulfide elastomers market sits at a platform-economics inflection, driven by the tightening ecosystem of performance specifications and chemical substance regulations. This shift demands integrated solutions for material development and application.
For Market Incumbents: Secure long-term supply agreements for critical thiol-based precursors to mitigate raw material volatility. Incumbents must invest heavily in research and development for REACH-compliant formulations, countering the threat of regulatory restrictions and substitution from alternative sealants. Deepening vertical integration into specialized polymer synthesis helps maintain a competitive edge. Pursuing advanced aerospace certifications reinforces high-margin segment control.
For New Entrants and Emerging Players: Expedited certification pathways for construction-grade sealants offer a tangible entry point into the polysulfide market. New entrants should target underpenetrated geographic markets like the Middle East infrastructure developments. Focusing on low-viscosity, fast-curing formulations compatible with automated application systems provides a distinct go-to-market angle for automotive and construction. This strategy allows for efficient scaling in less regulated segments.
For Investors and Strategic Acquirers: The market sits at a maturation phase that favors specialists with proprietary formulation expertise and regulatory compliance capabilities. Long-term viability rests on polysulfide elastomers' indispensable role in aerospace and demanding construction applications. Acquisition targets include niche polymer producers specializing in REACH-compliant thiol-based precursors or regional formulators with strong channel access in Germany's advanced construction sector. Increased M&A activity around precursor technology signals market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures supply for growing demand in aerospace and advanced construction. |
| Backward Integration | Ensures consistent access to critical thiol-based polymer precursors. |
| Green Manufacturing Transition | Aligns production with evolving environmental regulations and customer preferences. |
| Long-term Supply Agreement | Stabilizes raw material costs amidst market volatility for sulfur. |
| Joint Venture | Expands market access in new geographies like the Middle East infrastructure sector. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU REACH documentation, US EPA guidelines, and ISO 11600 standards. This approach involved extensive interviews with polymer chemists, R&D directors at sealant manufacturers, and procurement leads from aerospace OEMs. Bottom-up and top-down triangulation ensured data accuracy. Chemical distributors and construction project managers also provided critical insights.
Product type, end-user, application, delivery mode, and regional regulatory landscape formed the segmentation dimensions modeled. The analytical framework projects market evolution across the analysis window. Compound Annual Growth Rates derived from historical trends, market drivers, and expert projections. Raw material price forecasts and aerospace build rates served as key quantitative inputs.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in sudden shifts in chemical substance regulations or raw material supply. Forecasts reflect these assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Middle-East and Africa Fluoroelastomers Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
Medical Styrenic Block Copolymer (SBC) Market
Elastomeric Membrane
Global Thermoplastic Elastomers (TPE) Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market