
 Global Fluoroelastomers Market | 2026-2036
Global Fluoroelastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fluoroelastomers Market Foresight
ASTM D2000 qualification is redrawing competitive boundaries for compound suppliers seeking automotive and aerospace tier-one approval. Solvay leverages its integrated fluorochemical chain to sustain feedstock security across European and North American production sites. The Chemours Company anchors its position through captive hexafluoropropylene supply and specialized compounding expertise in high-purity semiconductor grades.
Fluoroelastomers are synthetic rubber materials containing vinylidene fluoride and hexafluoropropylene units, typically formulated to withstand continuous operating temperatures exceeding 200°C while resisting aggressive fuels, acids, and solvents. Their primary purpose centers on sealing, gasketing, and flexible containment in systems where hydrocarbon-based elastomers degrade rapidly. Vinylidene fluoride copolymers occupy the dominant volume position due to established processing economics and broad chemical compatibility, while perfluoromethylvinylether variants command premium positioning in semiconductor fabrication where ultralow outgassing specifications apply. Aerospace seals and O-rings represent concentrated margin pools as qualification cycles and lot-traceability requirements limit viable supplier pools.
EPA oversight of per- and polyfluoroalkyl substance emissions constrains manufacturing expansion in the United States, while ECHA's REACH restrictions on fluorinated polymer precursors tighten raw material access across European Union member states. Japan's METI chemical substance reporting framework adds compliance layers for exporters targeting electronics manufacturing customers. Stakeholders must monitor evolving polymer-of-concern designations and pre-position alternative chemistries before regulatory thresholds harden into supply disruptions.
Market Dynamics
REACH and F-Gas Regulation compliance costs are forcing compound suppliers to requalify formulations faster than certification cycles traditionally allow, compressing R&D amortization windows and favoring producers with captive fluorochemical feedstock.
Growth Catalysts
- Semiconductor capital expansion:Advanced node fabrication in Taiwan, South Korea, and the United States requires ultralow-outgassing perfluoroelastomer seals for vacuum chamber integrity. Wafer processing equipment OEMs specify lot-traceable compounds with sub-ppm metallic contamination.
- REACH authorization deadlines:ECHA's sunset dates for legacy plasticizers in automotive fuel systems accelerate substitution toward fluorinated sealing grades. Tier-one suppliers pre-qualify alternative compounds to avoid supply disruption.
- SAF blending mandates:The EU ReFuelEU Aviation program and corresponding FAA guidance require fuel system elastomers compatible with synthetic aromatic kerosene blends. Aerospace seal manufacturers reformulate for hydroperoxide resistance.
Market Restraints
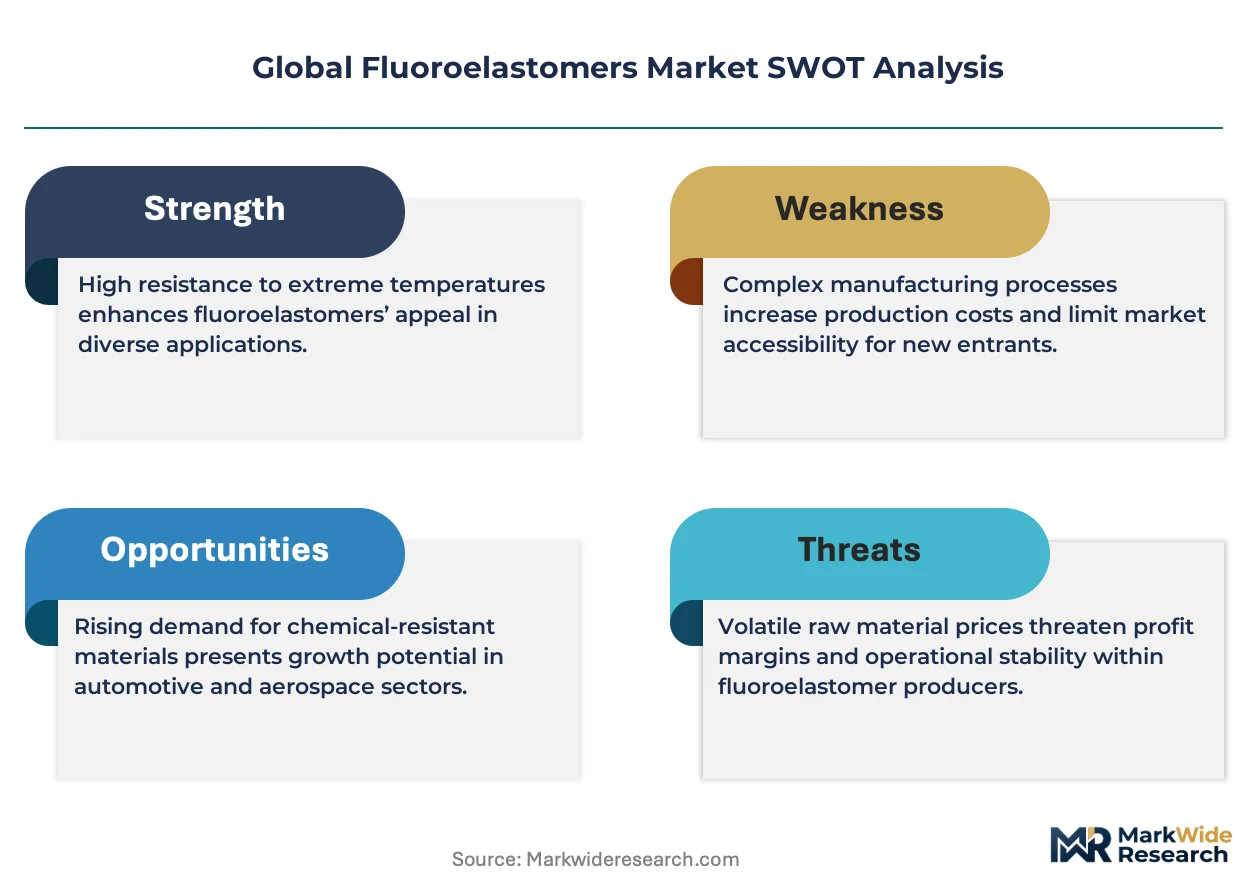
- Hexafluoropropylene supply concentration:Captive production of this critical monomer concentrates among integrated chemical majors, limiting independent compounders' feedstock security and pricing leverage.
- EPA PFAS manufacturing constraints:New source review requirements and discharge permitting delays constrain capacity expansion at US production sites, extending lead times for domestic aerospace programs.
- Perfluoroalkoxy alkane substitution in static seals:Melt-processible fluoroplastics displace elastomeric solutions in non-dynamic fuel system applications where compression set tolerance permits rigid materials.
Strategic Opportunities
- India automotive emission tightening:BS-VI Stage II implementation and proposed real-driving emissions monitoring create demand for high-temperature turbocharger hose compounds. Domestic formulation capabilities remain underdeveloped.
- Hydrogen infrastructure sealing:High-pressure gaseous hydrogen containment in German and Japanese refueling stations requires specialized permeation-resistant grades. No established compound specifications exist for 700-bar service.
- AI-driven formulation optimization:Machine learning models trained on property databases accelerate compound development cycles. Materials informatics platforms reduce experimental iterations for aerospace qualification.
Industry Challenges
- Fluoropolymer chemist scarcity:Specialized expertise in free-radical polymerization kinetics and cure system design concentrates among retiring practitioners. University programs deemphasize fluorine chemistry.
- ASTM D2000 lot certification timelines:Full qualification protocols for new automotive compounds require 18-24 months of accelerated aging and fluid immersion testing, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fluoroelastomers Market |
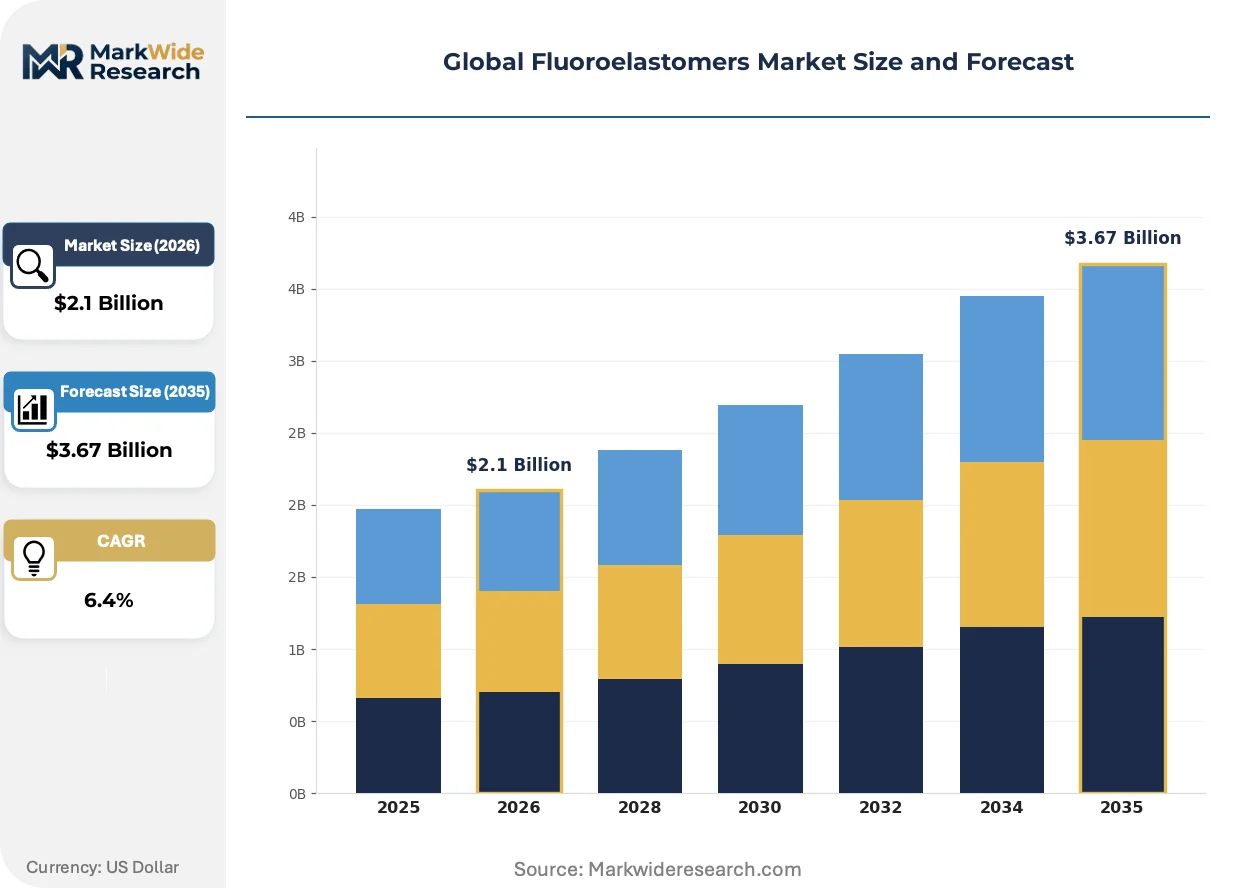
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinylidene Fluoride, Hexafluoropropylene, Tetrafluoroethylene, Perfluoromethylvinylether, Elastomer Blends Application: Seals, Gaskets, Fuel Hoses, O-rings, Diaphragms, Tubing End User Industry: Aerospace, Chemical Processing, Semiconductor Fabrication, Oilfield Equipment, Automotive Suppliers, Electronics Manufacturing Form: Raw Polymer, Compounded Material, Molded Components, Extruded Profiles, Sheets |
| Companies Covered | Solvay, Shin-Etsu Chemical Co., Ltd., The Chemours Company, DuPont, Gujarat Fluorochemicals Limited, DAIKIN INDUSTRIES, Ltd., AGC Inc., Syensqo, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fluoroelastomers Market Shifts & Advancements
Formulation science, regulatory chemistry, and procurement digitization are converging to redefine how fluoroelastomer specifications propagate through automotive, aerospace, and semiconductor supply chains.
Perfluoromethylvinylether-based terpolymers are fragmenting the high-purity sealant landscape. Semiconductor equipment OEMs in Japan and the United States specify these grades for EUV lithography vacuum systems where total outgassing must remain below 1E-9 Torr-liter/sec. The technology compresses viable supplier pools to compounders with dedicated cleanroom compounding lines.
ECHA's PFAS restriction proposal under REACH is reshaping raw material access across EU member states. The draft ban on perfluoroalkyl substances would eliminate certain cure site monomers and processing aids from formulated compounds. German automotive suppliers accelerate qualification of alternative ionic cure systems to maintain supply continuity.
Direct mill-to-mold digital procurement platforms are disintermediating traditional distributor channels for standard-grade compounds. Tier-two automotive suppliers in Michigan and Bavaria now specify compounds through cloud-based specification databases rather than regional stocking distributors. The shift concentrates volume with compounders offering real-time inventory visibility and certificate-of-analysis automation.
Global Fluoroelastomers Market Segmentation
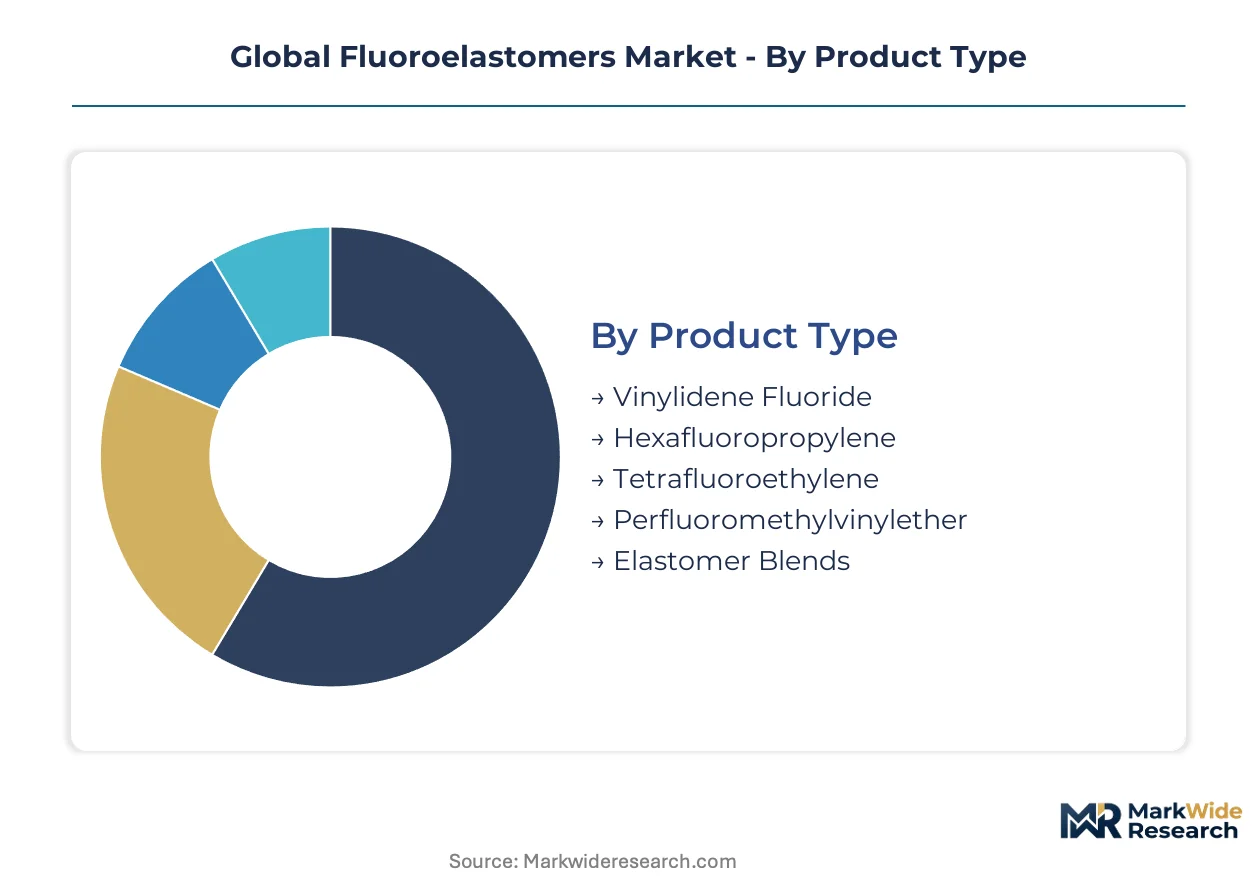
Fluoroelastomer procurement patterns diverge sharply across product chemistries and end-use specifications. Semiconductor fabs demand lot-traceable perfluoro grades while automotive suppliers prioritize cost-optimized vinylidene fluoride compounds. Understanding these segment boundaries clarifies where formulation investments concentrate versus where price competition dominates.
Product Type:
Domestic consumption of fluoropolymer feedstocks concentrates in Germany, Japan, and the United States where integrated chemical majors operate captive monomer plants. Export-led demand for specialized grades flows from these production clusters to semiconductor fabrication sites in Taiwan and South Korea.
- Vinylidene Fluoride:Copolymers containing vinylidene fluoride and hexafluoropropylene units deliver the baseline balance of chemical resistance and processing economy. Automotive fuel system manufacturers in Michigan and Bavaria specify these grades for turbocharger hoses and emission control seals under ASTM D2000 classifications. The segment absorbs volume-driven procurement from tier-one suppliers seeking qualified alternatives to hydrocarbon elastomers.
- Perfluoromethylvinylether:Terpolymers incorporating this monomer achieve ultralow outgassing specifications required for EUV lithography vacuum chambers. Japanese semiconductor equipment OEMs and US wafer processing tool builders limit supplier pools to compounders with certified cleanroom compounding capabilities. ECHA's draft PFAS restrictions threaten cure site monomer availability, accelerating qualification of alternative ionic cure systems.
- Hexafluoropropylene:Serves as the critical comonomer across most fluoroelastomer grades rather than a standalone product category.
- Tetrafluoroethylene:Provides backbone rigidity in specialized aerospace sealing compounds.
- Elastomer Blends:Custom formulations combining fluorinated and hydrocarbon elastomers for cost-sensitive industrial applications.
Vinylidene fluoride commands the established base. The steepest expansion runs through perfluoromethylvinylether.
Application:
Cost tiers separate static sealing applications where fluoroplastics compete from dynamic sealing where elastomeric recovery remains mandatory. Aerospace programs tolerate 18-24 month qualification timelines; automotive procurement demands immediate certificate-of-analysis availability.
- Seals:Dynamic shaft seals in aircraft fuel systems and chemical process pumps require compression set resistance across temperature swings from -40°C to 230°C. Aerospace manufacturers in Toulouse and Seattle specify lot-traceable compounds with full polymerization history documentation.
- O-rings:Static sealing applications in semiconductor vacuum chambers and hydrogen refueling infrastructure demand permeation resistance at pressure differentials exceeding 700 bar. German and Japanese station operators currently lack established compound specifications for gaseous hydrogen containment.
- Gaskets:Flange sealing in chemical processing equipment.
- Fuel Hoses:Turbocharger and fuel delivery lines in automotive applications.
- Diaphragms:Pressure sensing and fluid control in process instrumentation.
- Tubing:Flexible containment for aggressive chemical transfer.
Seals absorb the majority of qualification investment. O-rings are climbing the fastest as hydrogen infrastructure deployment accelerates.
End User Industry:
Customer concentration patterns align with manufacturing cluster geography. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States; automotive sealing procurement centers on Germany, Japan, and Michigan.
- Semiconductor Fabrication:Advanced node production in Hsinchu and Pyeongtaek requires perfluoroelastomer seals with sub-ppm metallic contamination limits. Equipment OEMs specify compounds through cloud-based specification databases that disintermediate traditional distributor channels.
- Aerospace:Airframe and engine manufacturers in Toulouse, Hamburg, and Seattle drive demand for high-temperature sealing qualified to AMS specifications. ReFuelEU Aviation SAF blending mandates force reformulation for hydroperoxide resistance.
- Automotive Suppliers:Tier-one sealing specialists in Stuttgart and Detroit convert to fluorinated grades as ECHA sunset dates eliminate legacy plasticizers.
- Chemical Processing:Refinery and specialty chemical plant maintenance cycles.
- Oilfield Equipment:Downhole sealing in high-pressure sour gas environments.
- Electronics Manufacturing:Consumer device assembly requiring solvent-resistant gasketing.
Automotive suppliers provide the volume foundation. Semiconductor fabrication is gaining share fastest.
Form:
Supply chain configuration separates raw polymer producers with captive monomer positions from independent compounders and finished component molders. Digital procurement platforms now connect tier-two automotive suppliers directly to compounders, bypassing regional distributors.
- Compounded Material:Pre-formulated batches with curative packages and fillers integrated for specific ASTM D2000 callouts. Bavarian and Michigan automotive suppliers increasingly specify compounds through real-time inventory platforms rather than stocking distributors.
- Molded Components:Finished seals and gaskets delivered to aerospace OEMs with full lot traceability. Long qualification cycles limit viable supplier pools to established compounders with dedicated aerospace certification staff.
- Raw Polymer:Base copolymer supplied to captive compounders.
- Extruded Profiles:Continuous shapes for door seals and chemical transfer lines.
- Sheets:Flat stock for gasket cutting and fabrication.
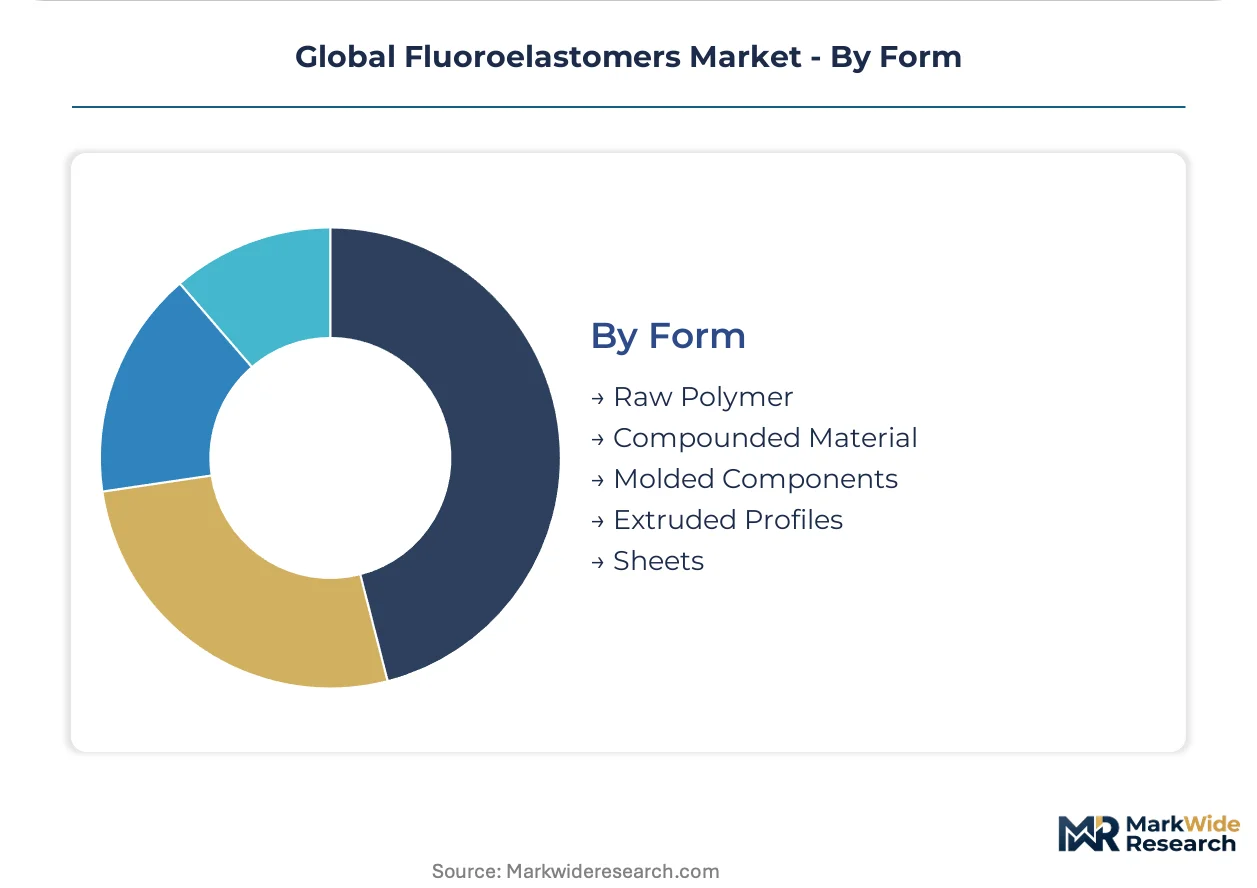
Compounded material anchors procurement volume. Molded components are expanding most quickly as OEMs outsource finished seal manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's petrochemical corridor underwrites United States fluoroelastomer production capacity, while Rotterdam's chemical cluster anchors European feedstock distribution for fluoropolymer manufacturers serving automotive and aerospace supply chains.
United States
Gulf Coast petrochemical infrastructure supports captive hexafluoropropylene production for domestic compounders. EPA PFAS manufacturing constraints under New Source Review requirements extend permitting timelines for capacity expansion. Aerospace seal manufacturers in Seattle and Wichita face elongated lead times for AMS-qualified compounds as domestic production struggles to match program demand.
Germany
Automotive tier-one suppliers in Stuttgart and Munich drive specification shifts toward fluorinated grades as ECHA REACH sunset dates eliminate legacy fuel system plasticizers. The F-Gas Regulation compels material substitutions in high-temperature sealing applications. Bavarian compounders operate integrated formulation laboratories serving both domestic OEMs and export markets across Central Europe.
Japan
Semiconductor equipment OEMs in Tokyo and Osaka specify ultralow-outgassing perfluoroelastomer seals for EUV lithography systems. METI chemical substance reporting frameworks add compliance documentation layers for exporters targeting electronics manufacturing customers. Nagoya-based automotive suppliers convert turbocharger hose specifications to fluorinated grades under domestic emission tightening schedules.
South Korea
Advanced node fabrication in Pyeongtaek and Hwaseong demands perfluoroelastomer seals with sub-ppm metallic contamination limits for vacuum chamber integrity. Domestic chemical producers lack captive fluoromonomer capacity, forcing reliance on Japanese and German feedstock imports. Seoul-based equipment OEMs specify compounds through cloud-based procurement platforms that bypass traditional distributor channels.
China
Yangtze River Delta semiconductor fabrication clusters import specialized perfluoro grades for wafer processing equipment despite domestic fluoropolymer capacity expansion. MIIT industrial standards for fluorinated materials remain less stringent than ASTM D2000 or JIS specifications, limiting export qualification for domestic compounders. Shanghai automotive suppliers accelerate fluorinated seal adoption under Stage VIb emission implementation timelines.
Global Fluoroelastomers Market Competitive Landscape
Listed leaders compete with private specialists across integrated versus non-integrated business models. Captive fluorochemical feedstock production concentrates among vertically integrated chemical majors, while independent compounders rely on merchant monomer supply. Three archetypes dominate: integrated fluoropolymer producers with captive monomer positions, specialized compounders with cleanroom certification capabilities, and regional formulators serving cost-sensitive industrial applications. Capacity expansion and qualification acceleration represent the dominant competitive moves as certification timelines compress.
Within the integrated producer tier, Solvay and The Chemours Company exemplify archetypes defined by captive feedstock security. Solvay's European and North American production sites leverage integrated fluorochemical chains. The Chemours Company anchors positioning through specialized compounding expertise. Among Asia-Pacific-based manufacturers, Shin-Etsu Chemical Co., Ltd. and DAIKIN INDUSTRIES, Ltd. occupy positions reflecting Japanese industrial conglomerate structures. Gujarat Fluorochemicals Limited represents emerging-market participation in fluoropolymer value chains.
| Leading Market Players |
|---|
| Solvay |
| Shin-Etsu Chemical Co., Ltd. |
| The Chemours Company |
| DuPont |
| Gujarat Fluorochemicals Limited |
| DAIKIN INDUSTRIES, Ltd. |
| AGC Inc. |
| Syensqo |
| 3M |
| Others |
Supply & Pricing Matrix
Captive hexafluoropropylene production at Gulf Coast and Antwerp facilities generates scale economies that compress unit costs for integrated majors while elevating price floors for merchant-dependent compounders. This concentration pattern transmits directly into tiered procurement structures where aerospace lot-traceability specifications command substantial premiums over automotive volume grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates semiconductor perfluoroelastomer seals from automotive fuel system compounds and industrial blending grades. Price differentiation hinges on ASTM D2000 certification tier and cleanroom compounding capability. Cost compression in standard vinylidene fluoride copolymers is intensifying because Japanese and German automotive suppliers are consolidating qualified vendor lists. Tier-two automotive procurement teams exhibit highest price sensitivity; semiconductor equipment OEMs demonstrate lowest sensitivity due to vacuum chamber failure costs.
Supply Chain Analysis
Extended lead times for AMS-qualified aerospace compounds now stretch 18-24 months as EPA PFAS permitting delays constrain domestic capacity expansion. Supply concentrates in the United States, Germany, and Japan where integrated producers operate captive fluoromonomer plants. Merchant compounders draw from Chinese and Indian fluorochemical intermediates, exposing formulations to REACH authorization volatility. Distribution runs through direct mill-to-mold digital platforms that disintermediate regional stocking distributors for standard automotive grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as hydrogen infrastructure deployment and EU ReFuelEU Aviation mandates create first-mover qualification opportunities for permeation-resistant sealing grades.
For Market Incumbents: Consolidate feedstock security through backward integration into hexafluoropropylene or long-term offtake agreements with Gulf Coast producers. Accelerate cleanroom compounding capacity in Japan and Germany before ECHA PFAS restrictions harden cure site monomer access. Defensive positioning requires preemptive qualification of alternative ionic cure systems. For New Entrants and Emerging Players: ASTM D2000 fast-track programs for BS-VI Stage II turbocharger hose specifications in India offer the most penetrable entry point. Target domestic automotive suppliers lacking qualified fluorinated compound sources. Go-to-market leverage rests on cloud-based specification databases with real-time certificate-of-analysis automation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with dual aerospace-semiconductor certification capabilities and captive European fluorochemical feedstock. Long-term viability hinges on navigating regulatory chemistry transitions without customer qualification disruption. Monitor ECHA PFAS restriction implementation timelines as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hexafluoropropylene | Captive monomer supply secures formulation autonomy against REACH authorization disruptions. |
| Cleanroom Compounding Capacity Expansion | Dedicated lines qualify compounders for EUV lithography vacuum seal specifications at Japanese OEMs. |
| Alternative Cure System Qualification | Ionic cure platforms maintain supply continuity under ECHA PFAS cure site monomer restrictions. |
| Digital Procurement Platform Deployment | Real-time inventory visibility concentrates automotive volume with responsive compounders. |
| Hydrogen Infrastructure Compound Development | 700-bar permeation-resistant grades address specification gaps in German and Japanese refueling stations. |
Research Methodology
Desk research of customs trade data, SEC chemical sector filings, and ECHA regulatory databases preceded structured interviews with fluoropolymer plant managers, automotive tier-one procurement leads, semiconductor equipment OEM technical directors, and aerospace seal qualification engineers. Primary fieldwork validated secondary estimates through bottom-up capacity assessments and top-down demand triangulation across end-use industries.
Variance decomposition across product chemistry, application specification, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories indexed to semiconductor capital expenditure cycles, automotive emission implementation schedules, and aerospace program delivery timelines. Forecast inputs incorporated hexafluoropropylene capacity utilization rates and ASTM D2000 qualification pipeline visibility.
Decision-makers should treat outputs as directional under stable regulatory chemistry assumptions; material deviation through accelerated PFAS restrictions or feedstock disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Rubber Membrane Market
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
Cold Cast Elastomers Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Middle-East and Africa Fluoroelastomers Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Global Elastomeric Coating Market