
 Polyolefin Elastomer Market | 2026-2036
Polyolefin Elastomer Market Size, Share, and Industry Trends Forecast 2026-2036
Polyolefin Elastomer Market Intelligence
Direct supply agreements between resin producers and tier-one automotive suppliers is narrowing as compounders seek captive offtake arrangements. Dow, Inc. leverages its integrated polyethylene backbone to secure long-term automotive contracts. Mitsui Chemicals, Inc. anchors its position through advanced catalyst technology for precise elastomer architecture. Borealis AG differentiates via European-based production with strong REACH documentation capabilities.
Polyolefin elastomers comprise copolymers of ethylene or propylene with alpha-olefins, typically exhibiting Shore A hardness between 60 and 90 and melting points ranging from 50°C to 100°C depending on comonomer ratio and density. These materials serve primarily as impact modifiers, flexible hinges, and soft-touch surfaces where vulcanized rubber would impose excessive weight or recycling complexity. TPO formulations command the largest volume share due to their cost-performance balance in automotive bumper fascias and interior skins, while PEBA grades capture premium margin pools in medical tubing and high-performance footwear midsoles. POE growth concentrates in photovoltaic encapsulant films where UV resistance and thermal stability requirements intensify.
FDA biocompatibility standards govern healthcare-grade elastomer qualification timelines in the United States, while ECHA REACH registration obligations constrain non-European suppliers seeking European automotive certification. China's SAMR enforces GB standards for automotive interior emissions that directly influence copolymer selection in domestic vehicle programs. Stakeholders must monitor regulatory divergence between major automotive-producing jurisdictions when planning regional formulation strategies and capacity investments.
Market Dynamics
Automotive lightweighting mandates and photovoltaic capacity expansion are pulling polyolefin elastomer volumes toward high-performance grades, while catalyst technology advances compress the cost gap between commodity TPO and specialty PEBA formulations.
Growth Catalysts
- China's SAMR GB standards on automotive interior emissions:Domestic vehicle programs now specify low-VOC polyolefin skins, accelerating copolymer qualification timelines for Shanghai-based compounders serving BYD and NIO supply chains.
- Photovoltaic encapsulant film demand:POE grades with enhanced UV resistance and thermal stability are capturing volume from EVA in utility-scale solar installations across Rajasthan and Gujarat processing clusters.
- Advanced metallocene catalyst systems:Precise control over comonomer distribution enables tailored Shore A hardness and melting point combinations for medical tubing applications requiring FDA biocompatibility certification.
Market Restraints
- Alpha-olefin feedstock volatility:1-octene and 1-butene prices track ethylene cracker margins, compressing compounder margins when naphtha costs spike in Rotterdam and Singapore trading hubs.
- East Asian supply concentration:Over half of global POE capacity sits within 500 kilometers of Shanghai and Osaka, creating geographic risk exposure for European automotive suppliers seeking REACH-compliant material security.
- Cross-linked rubber substitution in high-temperature seals:Vulcanized EPDM retains performance advantages above 120°C in under-hood applications, limiting TPO penetration in powertrain thermal management systems.
Strategic Opportunities
- India's polymer processing corridor expansion:Dahej and Mundra petrochemical complexes offer greenfield compounding capacity for suppliers targeting PLI scheme beneficiaries in domestic electric vehicle manufacturing.
- Convergence of POE with recycled content streams:Mechanical recycling compatibility enables post-consumer automotive bumper feedstock integration into next-generation TPO formulations without property degradation.
- EU Green Deal circular economy requirements:REACH registration holders with documented mass-balance certification can capture premium positioning in German OEM sustainability scorecards.
Industry Challenges
- Metallocene catalyst specialist scarcity:Polymerization process engineers with single-site catalyst expertise command premium compensation in Osaka and Houston hiring markets, constraining technology transfer to new production facilities.
- FDA 510(k) biocompatibility timeline compression:Healthcare-grade PEBA qualification cycles extend 18-24 months, delaying revenue recognition for compounders pivoting from automotive to medical tubing segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyolefin Elastomer Market |
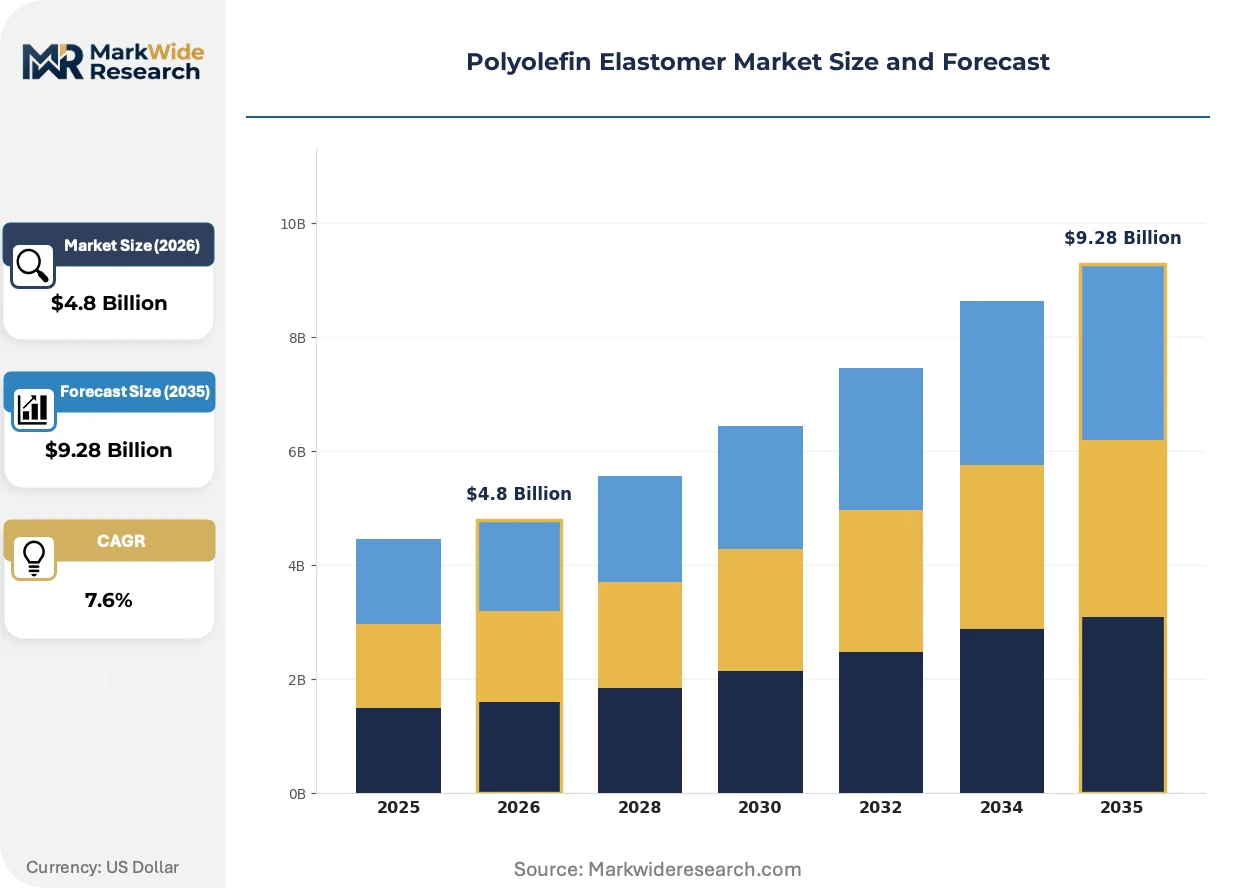
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEBA, POE, TPO, SEBS End User: Automotive, Healthcare, Consumer Goods, Footwear Application: Seals, Adhesives, Coatings, Films Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Borealis AG, Mitsui Chemicals, Inc., Dow, Inc., INEOS Group Holdings S.A., SABIC, ExxonMobil Corporation, LG Chem, Arkema S.A., LyondellBasell Industries Holdings B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyolefin Elastomer Market Strategic Shifts & Innovations
Digital process control and predictive quality systems are redefining how polyolefin elastomer producers manage molecular architecture precision, while regulatory documentation automation accelerates multi-jurisdictional certification timelines.
Metallocene-based reactor control systems is digitizing real-time comonomer ratio adjustments during polymerization. Automotive tier-one suppliers in Stuttgart and Nagoya now specify batch-to-batch consistency metrics that legacy Ziegler-Natta catalyst lines cannot meet. This capability compression is forcing compounders to retrofit existing assets or exit specification-sensitive interior skin contracts.
ECHA REACH Article 33 substance of very high concern screening is extending automotive material qualification documentation requirements. Suppliers must now trace octylphenol ethoxylate content through three tiers of subcomponent sourcing. German OEM sustainability offices are rejecting TPO formulations lacking SCIP database registration, shifting procurement preference toward European-based compounders with established compliance infrastructure.
Long-term offtake contracting with embedded price adjustment mechanisms is displacing spot market purchasing for photovoltaic encapsulant grades. Module manufacturers in Xiamen and Ho Chi Minh City now negotiate three-year POE supply agreements indexed to ethylene futures. This channel consolidation concentrates volume with resin producers offering integrated logistics and technical service support, marginalizing independent distributors in Southeast Asian solar supply chains.
Polyolefin Elastomer Market Segmentation

Polyolefin elastomer procurement patterns diverge sharply across product grades and end-use sectors, with automotive qualification timelines and medical certification requirements creating distinct service intensity profiles. Technical support demands, regulatory documentation burdens, and formulation customization needs vary by segment, directly influencing supplier relationship structures and margin capture potential.
Product Type:
After-sales service intensity escalates from commodity TPO through specialty PEBA, with catalyst technology complexity and application-critical performance requirements dictating technical support depth.
- PEBA:Polyether block amide copolymers deliver Shore A hardness from 75 to 90 with exceptional flex fatigue resistance and chemical resilience. Medical tubing manufacturers in Massachusetts and Minnesota drive specification intensity for FDA-compliant grades, where batch certification documentation and biocompatibility traceability command premium service contracts.
- POE:Metallocene-catalyzed ethylene-alpha-olefin copolymers provide UV-stable encapsulation for photovoltaic modules with thermal stability exceeding 85°C. Utility-scale solar developers in Rajasthan and Gujarat specify three-year technical service agreements covering module degradation testing and warranty support.
- TPO:Cost-optimized bumper fascia and interior skin formulations dominate automotive procurement volumes with standardized Shore A ranges of 60-80.
- SEBS:Hydrogenated styrenic block copolymers serve soft-touch consumer electronics and medical device overmolding applications requiring clarity and sterilization compatibility.
By volume, TPO leads. By growth pace, POE is ahead.
End User:
Customer concentration and contract structuring vary dramatically, with automotive OEMs demanding captive supply arrangements while healthcare buyers prioritize regulatory documentation over volume commitments.
- Automotive:Tier-one suppliers in Stuttgart, Nagoya, and Shanghai specify low-VOC interior skins under GB standards and REACH protocols. BYD and NIO supply chains in Shanghai compounder networks require embedded technical service teams for color-matching and texture development.
- Healthcare:FDA 510(k) biocompatibility certification cycles of 18-24 months dominate procurement timelines for medical tubing and device manufacturers. PEBA grades for catheter shafts and surgical instruments command dedicated regulatory affairs support from resin suppliers.
- Consumer Goods:Appliance soft-touch grips and power tool overmolds drive specification diversity with shorter qualification cycles than automotive or medical segments.
- Footwear:High-performance midsole applications for running and basketball shoes concentrate demand with premium athletic brands specifying energy return and durability metrics.
Automotive captures the largest revenue pool. Healthcare delivers the steepest expansion trajectory.
Application:
Performance requirements and failure cost exposure determine formulation precision demands, with film applications requiring molecular architecture control that seals specifications rarely match.
- Films:Photovoltaic encapsulant layers demand POE grades with precise comonomer distribution for UV resistance and thermal stability. Module manufacturers in Xiamen and Ho Chi Minh City negotiate long-term offtake agreements with integrated logistics and technical service support.
- Seals:Automotive door and glass run channel formulations balance compression set resistance with cost targets, though vulcanized EPDM retains advantage above 120°C in powertrain applications.
- Adhesives:Hot-melt and pressure-sensitive formulations for packaging and hygiene products leverage POE tackifier compatibility.
- Coatings:Powder coating flexibilizers and textile lamination binders utilize TPO and SEBS grades for durability and process efficiency.
Films command the highest growth rate. Seals retain the largest installed base.
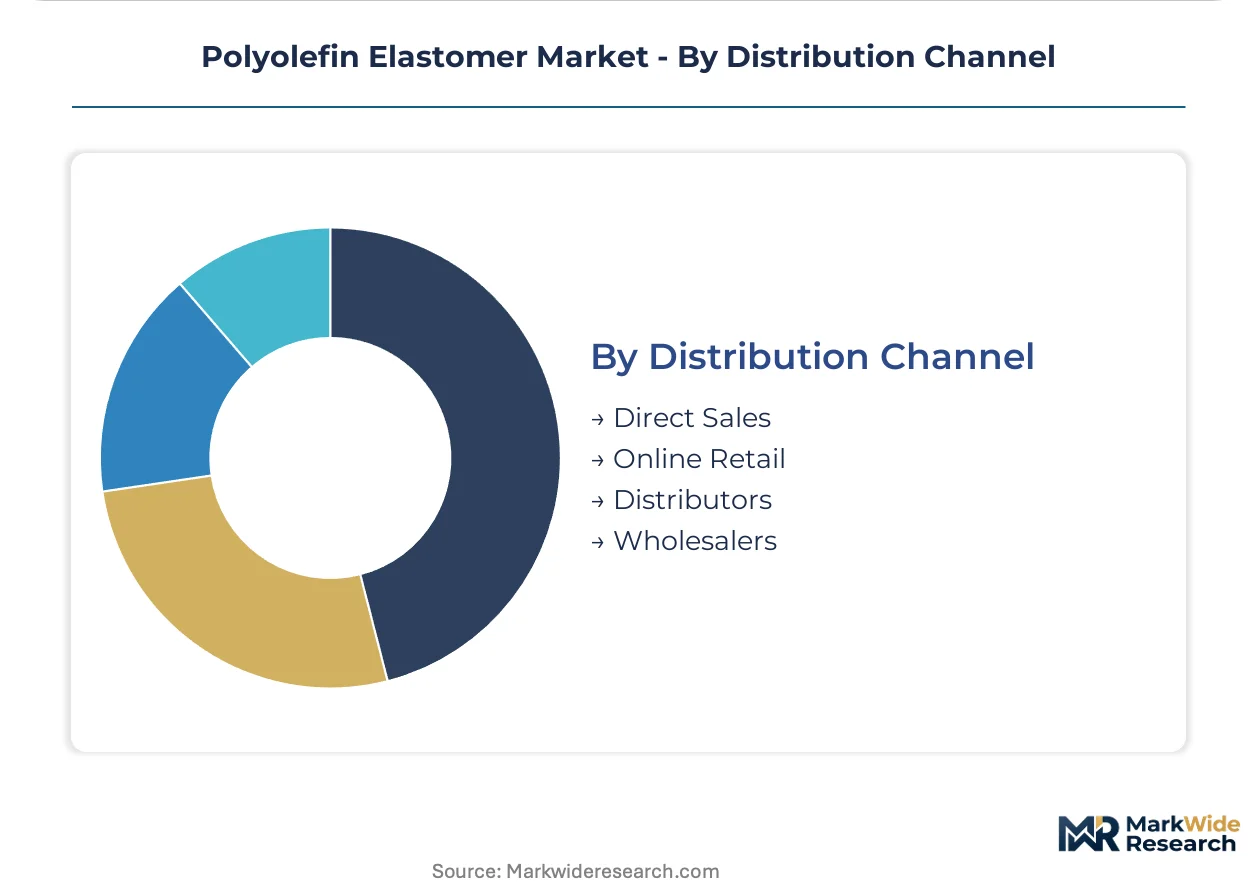
Distribution Channel:
Channel selection reflects order scale, technical complexity, and geographic proximity to compounding infrastructure, with direct relationships consolidating around high-volume automotive and solar accounts.
- Direct Sales:Resin producers engage tier-one automotive suppliers and photovoltaic module manufacturers through dedicated account teams. Dow and Mitsui Chemicals structure three-year supply agreements with price adjustment mechanisms tied to ethylene futures.
- Distributors:Regional compounders and mid-tier processors rely on inventory-positioned distributors for smaller lot sizes and technical consultation.
- Online Retail:Specialty grades in drum quantities serve research institutions and prototype developers with accelerated procurement timelines.
- Wholesalers:Commodity TPO volumes for general industrial applications move through bulk material wholesalers with limited technical service attachment.
Direct sales dominate value capture. Distributors handle the widest SKU breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port anchors East Asia's polyolefin elastomer trade, handling bulk resin shipments for compounding clusters across the Yangtze River Delta. This maritime infrastructure underwrites the region's dominance in both automotive TPO formulation and photovoltaic POE encapsulant production.
China
Domestic electric vehicle manufacturers BYD and NIO drive specification intensity for low-VOC interior skins under SAMR GB standards. Shanghai compounder networks now embed technical service teams for color-matching and texture development. The Yangtze River Delta processing corridor concentrates over half of national TPO compounding capacity.
Germany
Stuttgart-based tier-one suppliers specify REACH-compliant TPO formulations for bumper fascia and interior components. ECHA Article 33 substance screening extends material qualification documentation through three tiers of subcomponent sourcing. Bavarian OEM sustainability offices reject formulations lacking SCIP database registration.
United States
FDA 510(k) biocompatibility certification governs healthcare-grade PEBA procurement timelines for Massachusetts and Minnesota medical tubing manufacturers. Houston petrochemical corridors supply alpha-olefin feedstocks to domestic compounders. Gulf Coast ethylene cracker margins directly impact 1-octene and 1-butene pricing for regional formulators.
Japan
Osaka polymerization facilities leverage advanced metallocene catalyst systems for precise elastomer architecture control. Nagoya automotive suppliers demand batch-to-batch consistency metrics that legacy Ziegler-Natta lines cannot satisfy. METI industrial standards shape catalyst technology licensing protocols for domestic producers.
India
Dahej and Mundra petrochemical complexes offer greenfield compounding capacity for suppliers targeting PLI scheme beneficiaries in domestic electric vehicle manufacturing. Rajasthan and Gujarat utility-scale solar installations specify POE encapsulant grades with enhanced UV resistance. BIS polymer standards increasingly align with automotive OEM qualification requirements.
Polyolefin Elastomer Market Key Industry Players
On the supply side, the industry is consolidating around integrated resin producers with captive catalyst technology and established regulatory documentation capabilities. Three strategic archetypes dominate: petrochemical majors with polyethylene backbone integration, specialty compounders with metallocene process expertise, and regional formulators with REACH or FDA certification infrastructure. Capacity expansion and long-term offtake contracting represent the two dominant competitive moves, particularly for photovoltaic encapsulant grade supply.
Within the integrated petrochemical tier, Dow, Inc. and Mitsui Chemicals, Inc. exemplify producers leveraging upstream ethylene control to secure automotive and solar supply chains. Borealis AG occupies a position representing European-based compounders with established REACH documentation capabilities and SCIP database registration infrastructure. These three entities anchor distinct geographic and regulatory positioning strategies without overlapping core competence claims.
| Leading Market Players |
|---|
| Borealis AG |
| Mitsui Chemicals, Inc. |
| Dow, Inc. |
| INEOS Group Holdings S.A. |
| SABIC |
| ExxonMobil Corporation |
| LG Chem |
| Arkema S.A. |
| LyondellBasell Industries Holdings B.V. |
| Others |
Cost & Logistics Intelligence
Overcapacity signals in East Asian polymerization facilities are compressing supplier pricing power while simultaneously accelerating captive offtake contracting as compounders seek volume security. This utilization dynamic rewards integrated producers with backward ethylene control and pressures standalone formulators into margin-sacrificing spot market participation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified PEBA medical grades from automotive TPO formulations and commodity industrial volumes. Price differentiation hinges on certification tier and volume scale, with biocompatibility documentation commanding substantial premiums over REACH-compliant automotive grades. Pricing pressure stems from alpha-olefin feedstock volatility tracking Rotterdam and Singapore ethylene cracker margins. Photovoltaic module manufacturers exhibit lowest price sensitivity due to encapsulant film performance warranty requirements, while general industrial buyers drive aggressive commoditization.
Supply Chain Analysis
Upstream 1-octene and 1-butene availability draws from Houston, Rotterdam, and Singapore ethylene cracker complexes, with comonomer distribution directly constraining POE grade production flexibility. Geographic supply concentration centers on China, Japan, and Germany, where Shanghai, Osaka, and Stuttgart anchor compounding infrastructure for automotive and solar end-uses. Single-source vulnerability persists for advanced metallocene catalyst systems licensed through METI protocols and Osaka technology corridors. Distribution runs through direct long-term offtake agreements for tier-one automotive and photovoltaic accounts, with regional distributors serving mid-tier processors requiring smaller lot sizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are proliferating as regulatory divergence between SAMR GB standards, ECHA REACH protocols, and FDA biocompatibility requirements creates specialized service niches that integrated majors cannot efficiently address.
For Market Incumbents: Pre-empt specialty compounder encroachment by embedding technical service teams within BYD and NIO supply chains in Shanghai, while securing three-year photovoltaic encapsulant offtake agreements indexed to ethylene futures. Backward integration into alpha-olefin production buffers margin compression during naphtha cost spikes. REACH documentation infrastructure and SCIP database registration capabilities defend European automotive positioning against non-compliant Asian suppliers. For New Entrants and Emerging Players: Build out greenfield compounding capacity at Dahej and Mundra petrochemical complexes to capture PLI scheme beneficiaries in India's domestic electric vehicle manufacturing corridor. Medical tubing applications in Massachusetts and Minnesota offer penetrable white space given 18-24 month FDA 510(k) qualification cycles that deter commodity producers. Lead with regulatory affairs outsourcing partnerships that compress healthcare-grade PEBA certification timelines for catheter shaft manufacturers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across photovoltaic encapsulant grade production as module manufacturers demand integrated logistics and technical service support. Long-term viability favors acquiring metallocene catalyst specialists with single-site process expertise rather than commodity TPO compounders facing margin erosion. Watch for ethylene futures backwardation as inflection signal indicating feedstock cost relief and margin expansion window.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Olefin Production | Houston and Rotterdam cracker control secures comonomer supply during naphtha volatility episodes. |
| Long-term Supply Agreement with Embedded Price Adjustment | Xiamen and Ho Chi Minh City module manufacturers index POE contracts to ethylene futures. |
| REACH Documentation Infrastructure Investment | SCIP database registration satisfies Bavarian OEM sustainability office procurement requirements. |
| Metallocene Catalyst Technology Licensing | Osaka polymerization facilities leverage METI protocols for precise elastomer architecture control. |
| Technical Service Team Embedding | Shanghai compounder networks deploy color-matching specialists for BYD and NIO interior skin programs. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, ACC and Cefic industry reports, and ECHA REACH registration databases. Interviews with polymer plant managers, automotive tier-one procurement leads, photovoltaic module manufacturing executives, and medical device regulatory affairs directors informed demand-side validation. Bottom-up grade-level volume estimates triangulated against top-down ethylene derivative consumption models.
Forecast inputs span grade tier, end-use industry, regional production hub, and certification requirement intensity across the analysis window. CAGRs derive from segmented growth rate reconciliation against macroeconomic drivers and industry-specific demand elasticity factors. Photovoltaic capacity expansion trajectories, automotive lightweighting mandate compliance timelines, and medical device approval pipeline data inform projection boundaries.
Stress conditions across alpha-olefin feedstock price volatility, regulatory protocol divergence, and catalyst technology transfer constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from SAMR GB standard updates, ECHA substance screening expansions, or metallocene process engineering labor market shifts. Cross-checking against IHS Markit polymer trade flow data and vehicle production registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Global Thermoplastic Elastomers (TPE) Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Elastic Laminates Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
North America Performance Elastomer Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market