
 Butyl Elastomers Market | 2026-2036
Butyl Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Butyl Elastomers Market Analysis
Singapore is rewriting regional supply dynamics through expanded butyl rubber production at Jurong Island petrochemical complexes. ExxonMobil Corporation leverages its integrated refinery-polymer operations to sustain feedstock cost advantages across Southeast Asian markets. Arlanxeo Holding B.V. anchors European supply security with dedicated bromobutyl lines serving tire OEMs. Sinopec Corporation dominates domestic distribution channels through direct mill partnerships with Chinese automotive manufacturers.
Butyl elastomers are synthetic rubbers polymerized from isobutylene with small amounts of isoprene, valued for near-zero gas permeability, vibration damping, and chemical resistance across temperatures from minus fifty to plus one hundred fifty degrees Celsius. Halogenated butyl variants, particularly brominated and chlorinated grades, command premium positioning due to their cured adhesion properties essential for tubeless tire inner liners. Tires absorb the dominant volume share of butyl elastomer offtake, while adhesives and sealants represent faster-growing application segments driven by construction activity in emerging economies. The automotive end-user category maintains mature, high-volume demand patterns, whereas construction and consumer goods applications exhibit more elastic growth tied to infrastructure cycles.
REACH in Europe restricts certain halogenated compound formulations, compelling reformulation investments from compounders serving medical and food-contact segments. EPA guidelines in the United States govern emissions from butyl rubber production facilities, affecting plant upgrade timelines and capital allocation decisions. China's GB standards and MEE oversight shape import qualification protocols for foreign material entering domestic tire supply chains. Stakeholders must track regulatory divergence between jurisdictions to optimize product registration strategies and avoid stranded formulation investments.
Market Dynamics
Halogenated butyl capacity expansion by tire manufacturers is redrawing feedstock procurement patterns and regional trade flows across East Asian petrochemical corridors.
Growth Catalysts
- Tubeless tire penetration:Automotive OEM specifications for inner liner performance are tightening, pulling premium bromobutyl grades into standard equipment configurations.
- REACH compliance differentiation:European compounders reformulating halogenated stocks for medical and food-contact segments are creating certified-grade premiums that reshape margin structures.
- Construction adhesives:Emerging economy infrastructure cycles are accelerating sealant offtake faster than mature automotive demand patterns.
Market Restraints
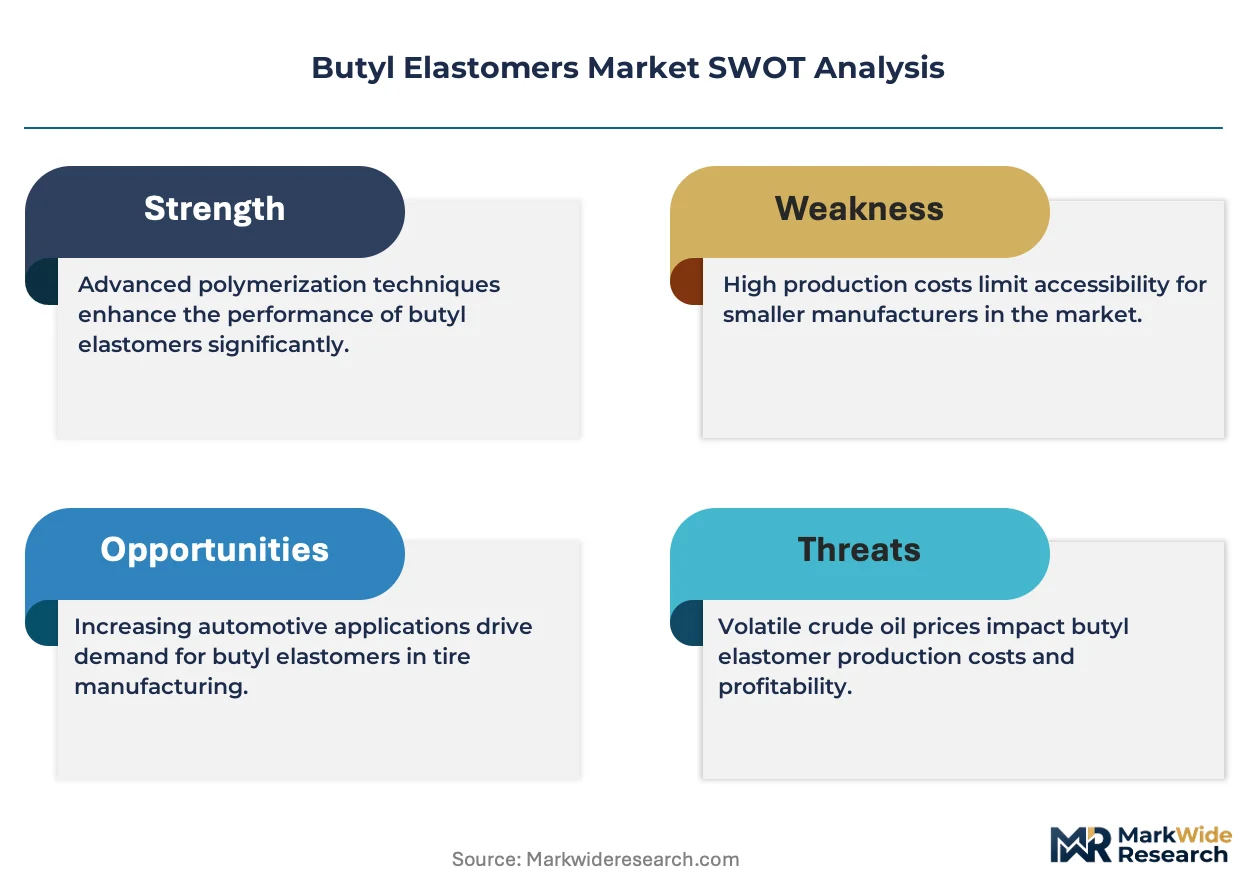
- Isoprene feedstock volatility:Crude-linked pricing for C4 stream derivatives compresses compounder margins during upstream energy shocks.
- East Asian supply concentration:Integrated petrochemical complexes in China and Singapore concentrate 60-plus percent of merchant halobutyl availability.
- Thermoplastic vulcanizate substitution:TPV advances in vibration damping applications threaten traditional butyl compounds in non-tire industrial seals.
Strategic Opportunities
- India tire localization:Domestic automotive production growth under PLI scheme incentives is opening qualified-supplier slots for halogenated grades.
- Green hydrogen infrastructure:Electrolyzer gasket and seal applications represent unpenetrated demand for high-purity butyl formulations.
- Digital compounding platforms:AI-driven formulation tools are compressing R&D cycles for custom halobutyl blends in specialty medical devices.
Industry Challenges
- Polymerization catalyst expertise:Shortages of technicians trained in Ziegler-Natta systems for high-molecular-weight isobutylene control constrain capacity ramp rates.
- Multijurisdictional registration:Divergent EPA, REACH, and GB standard timelines for halogenated compound approvals strand reformulation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butyl Elastomers Market |
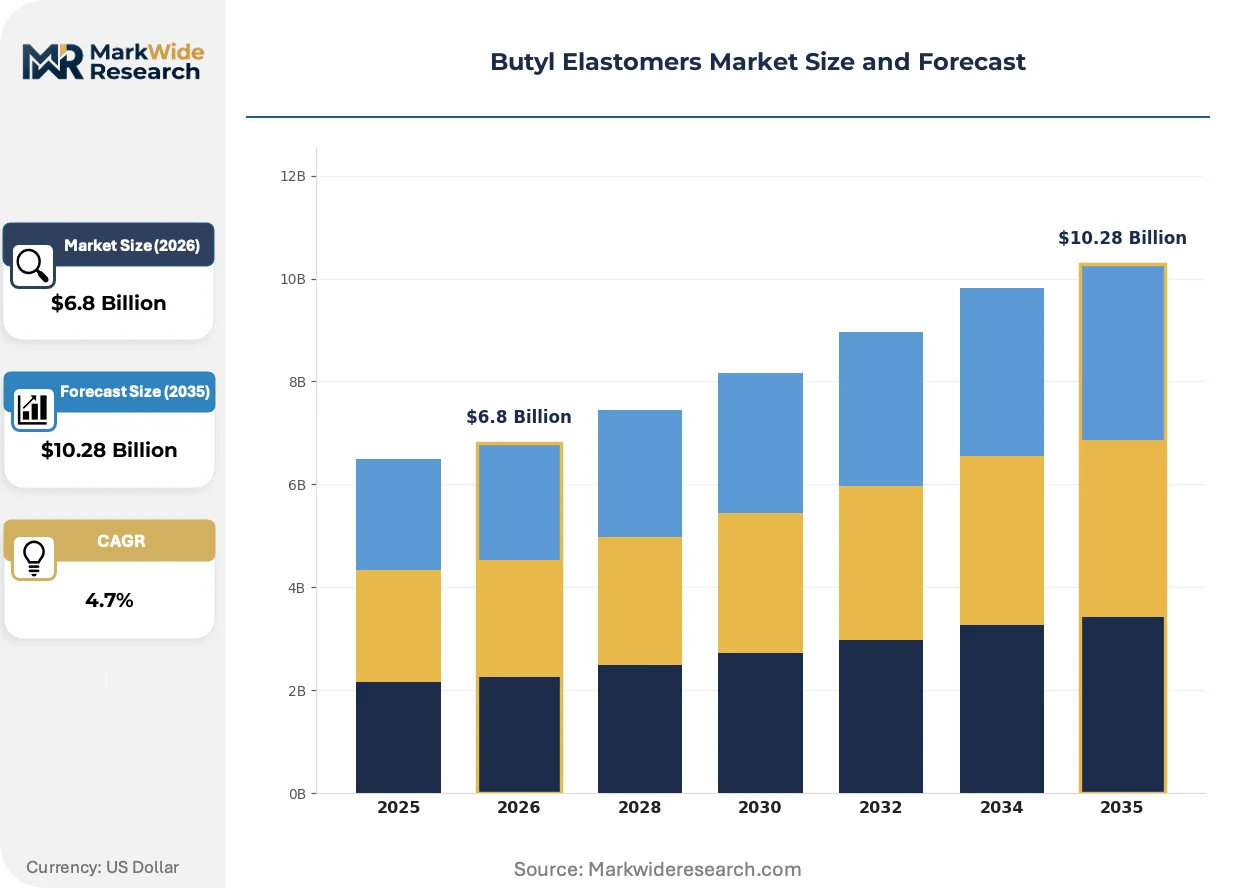
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Butyl, Brominated Butyl, Chlorinated Butyl, Halogenated Butyl Application: Tires, Adhesives, Sealants, Protective Coatings End User: Automotive, Construction, Footwear, Consumer Goods Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | ExxonMobil Corporation, LANXESS AG, PJSC Nizhnekamskneftekhim, Sinopec Corporation, Reliance Industries Limited, Arlanxeo Holding B.V., SIBUR International GmbH, Lion Elastomers, Petronas Chemicals Group Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butyl Elastomers Market Emerging Trajectories
Process intensification and regulatory digitization are converging to compress formulation-to-approval cycles while fragmenting traditional supply hierarchies.
Advanced process control systems are digitizing reactor temperature and pressure monitoring across continuous polymerization lines. Tire compounders in Germany and Japan are adopting these platforms fastest, cutting batch-to-batch variation by half. Real-time viscosity tracking is digitizing quality assurance workflows, enabling direct mill integration without intermediate testing.
ECHA's SCIP database requirements for articles containing substances of very high concern are forcing downstream traceability investments. Compounders serving European medical device manufacturers must now document bromobutyl sourcing through three supply tiers. This regulatory layer is compressing spot-market flexibility and favoring long-term offtake contracts with integrated producers.
Specification-driven procurement is consolidating buyer power among tier-one automotive suppliers. Chinese tire OEMs are bypassing traditional distributors to contract directly with Singapore and Saudi production complexes for certified halobutyl volumes. This channel compression is visible most acutely in East Asian markets where mill-direct relationships now capture majority premium-grade offtake.
Butyl Elastomers Market Segmentation
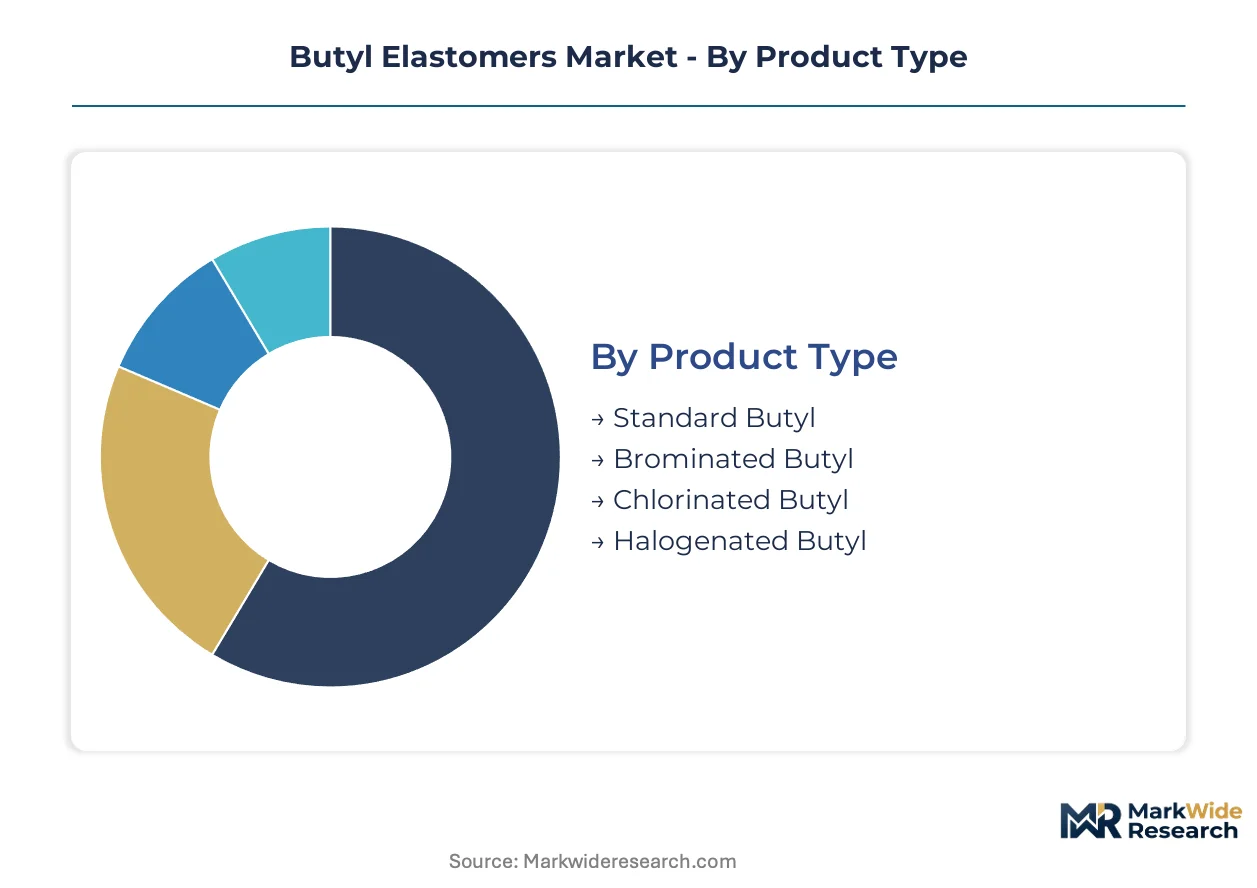
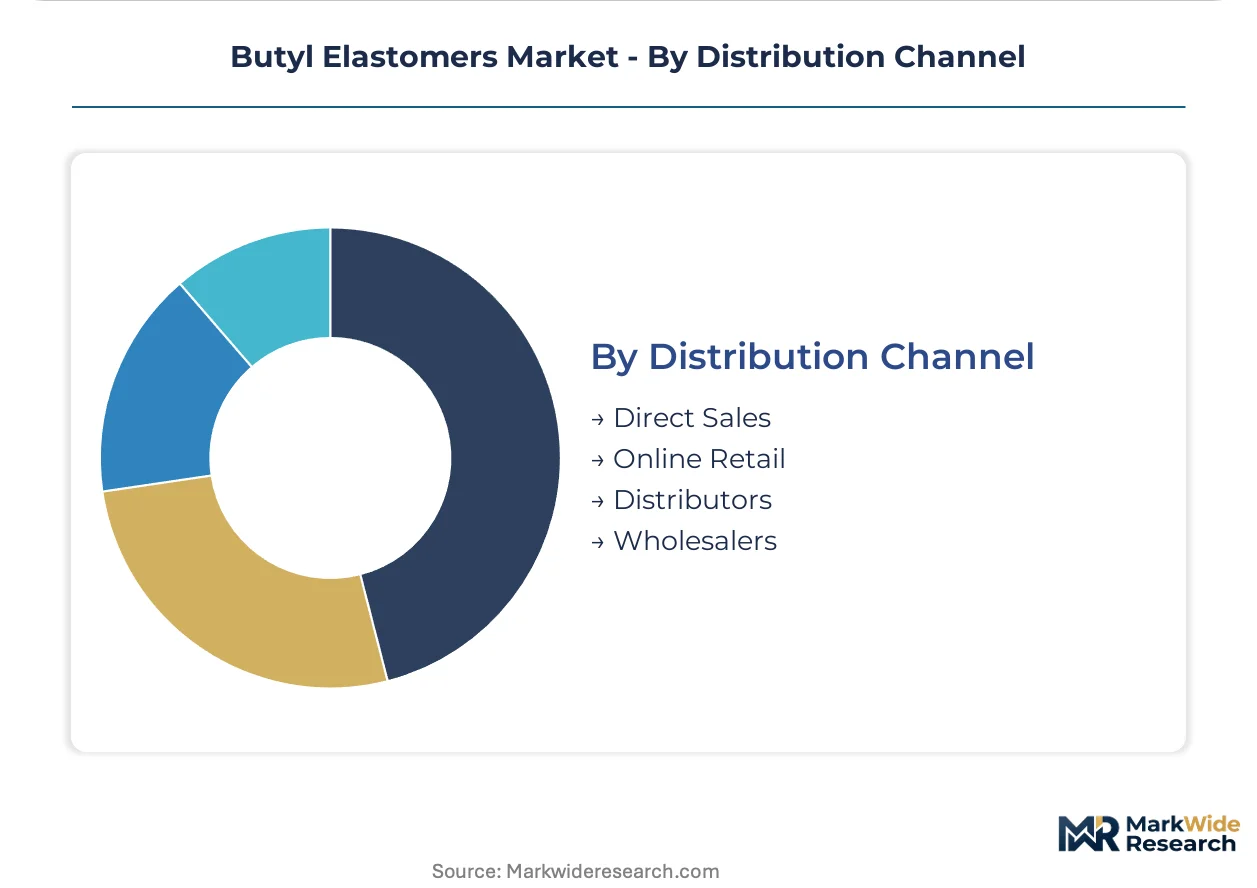
Butyl elastomer value pools fragment sharply across product chemistry and end-use specifications. Tire manufacturers command premium-grade offtake through direct mill contracts, while construction and consumer segments trade through layered distribution channels with divergent margin structures.
Product Type:
Mature commodity grades anchor volume throughput, whereas halogenated variants capture expanding specification premiums in automotive and medical applications.
- Standard Butyl:Polymerized from isobutylene with one to three percent isoprene, this grade delivers the baseline gas-barrier properties that established butyl rubber's commercial viability. Demand concentrates in inner tubes, curing bladders, and general-purpose seals across Indian and Southeast Asian tire retreading operations where cost sensitivity overrides performance premiums.
- Brominated Butyl:Post-polymer bromination creates reactive cure sites that bond aggressively to tire carcass compounds, enabling the air-retention performance that tubeless tire architectures require. Automotive OEMs in Germany and Japan specify brominated grades exclusively for passenger vehicle inner liners, pulling certified volumes through mill-direct procurement channels.
- Chlorinated Butyl:Chlorination delivers comparable adhesion properties with slightly faster cure kinetics, finding preference in industrial adhesive formulations and pharmaceutical stoppers where processing speed matters.
- Halogenated Butyl:This umbrella classification captures specialty brominated and chlorinated grades engineered for medical device and food-contact applications, subject to REACH and FDA compliance tiers that stratify pricing.
Standard Butyl retains volume leadership; Brominated Butyl holds the steepest expansion curve.
Application:
Cost-tier differentiation separates commodity tire compounds from specialty adhesive and coating formulations commanding formulation service premiums.
- Tires:Inner liners, sidewalls, and curing bladders absorb the dominant share of butyl elastomer offtake, with brominated grades specified for tubeless passenger and commercial vehicle architectures. Chinese tire OEMs now contract directly with Singapore and Saudi production complexes, compressing traditional distributor margins.
- Adhesives:Pressure-sensitive and structural adhesive formulations exploit butyl's tack and chemical resistance, with construction activity in Indonesia and Vietnam accelerating sealant offtake faster than mature automotive demand patterns.
- Sealants:Building envelope and infrastructure applications favor halogenated grades for weathering resistance, particularly in Middle Eastern megaproject developments where specification consultants mandate certified compound traceability.
- Protective Coatings:Marine and industrial coatings leverage butyl's moisture barrier properties, though this segment faces displacement pressure from advanced polyurethane and polysiloxane alternatives in corrosion-critical applications.
Tires command absolute volume dominance; Adhesives are expanding most quickly on construction cycle momentum.
End User:
Customer-type segmentation separates specification-driven automotive procurement from price-elastic construction and consumer goods purchasing.
- Automotive:Tier-one tire suppliers and OEMs enforce rigorous compound certification protocols, with mill-direct relationships now capturing majority premium-grade offtake in East Asian markets. REACH and GB standard compliance documentation requirements favor integrated producers with captive feedstock and in-house testing laboratories.
- Construction:Infrastructure project cycles drive volatile butyl sealant demand, with Indian PLI scheme incentives accelerating domestic automotive production and pulling construction adhesives into qualified-supplier qualification pipelines.
- Footwear:Athletic and industrial boot manufacturers specify butyl rubber for outsole compounds requiring chemical resistance and vibration damping, though thermoplastic vulcanizate substitution threatens traditional compounds in this price-sensitive segment.
- Consumer Goods:Pharmaceutical stoppers, sporting equipment, and household products represent fragmented, specification-diverse demand with regulatory divergence between EPA, REACH, and GB standards stranding reformulation investments for multinational compounders.
Automotive end-use retains volume leadership; Construction holds the steepest expansion curve on emerging economy infrastructure investment.
Distribution Channel:
Supply concentration patterns reshape channel economics, with integrated producers bypassing traditional intermediaries to capture specification premiums directly.
- Direct Sales:Mill-direct contracts between Singapore and Saudi production complexes and Chinese tire OEMs now dominate premium halogenated grade offtake, eliminating distributor markups and enabling real-time formulation customization.
- Online Retail:Digital platforms serve small-batch specialty compounders and research laboratories with rapid-turn, certificate-of-analysis documented shipments, particularly for medical device prototyping applications in Germany and Switzerland.
- Distributors:Regional chemical distributors retain relevance in standard-grade spot markets and geographic territories lacking integrated petrochemical infrastructure, though margin compression from producer direct-selling erodes their traditional value proposition.
- Wholesalers:Volume resellers concentrate in construction adhesive supply chains, where project-based procurement patterns and fragmented contractor bases sustain intermediary roles despite specification-driven consolidation elsewhere.
Direct Sales channels are gaining share fastest; Distributors retain residual relevance in standard-grade spot markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE oversight in China anchors the dominant geography for butyl elastomer demand, with GB standards shaping import qualification protocols for tire supply chains. Singapore's Jurong Island complexes and Saudi Arabia's integrated refineries are expanding merchant halobutyl availability across Asian and Middle Eastern corridors.
China
Tire OEMs in Shandong and Jiangsu provinces are expanding domestic halogenated butyl capacity under PLI scheme incentives for automotive localization. MEE environmental inspections and GB standards compliance documentation constrain foreign material entry into domestic supply chains. Zhejiang's Ningbo petrochemical cluster hosts integrated isobutylene-isoprene feedstock operations serving specialty elastomer production.
Germany
Automotive OEMs in Stuttgart and Munich specify brominated butyl grades exclusively for passenger vehicle inner liners, pulling certified volumes through mill-direct channels. REACH compliance and ECHA SCIP database requirements force compounders to document bromobutyl sourcing through three supply tiers. The Ruhr industrial corridor maintains compounding expertise for high-performance tire architectures.
United States
Gulf Coast petrochemical complexes supply feedstock for domestic tire and adhesive compounders facing EPA emissions guidelines from production facilities. NHTSA tire performance standards and FDA medical device regulations create divergent compliance tiers for halogenated grades. Texas and Louisiana host the majority of integrated butyl rubber manufacturing capacity.
India
Domestic automotive production growth under PLI scheme incentives is opening qualified-supplier slots for halogenated butyl grades in Gujarat and Maharashtra tire plants. BIS certification requirements and DGFT import protocols shape foreign material qualification timelines. The Chennai-Sriperumbudur automotive cluster is accelerating localization of inner liner compound supply.
Singapore
Jurong Island petrochemical complexes are rewriting regional supply dynamics through expanded butyl rubber production serving Southeast Asian tire manufacturers. The country's national environmental regulator enforces emissions standards affecting plant upgrade timelines and capital allocation decisions. Integrated refinery-polymer operations sustain feedstock cost advantages across Indonesian and Thai markets.
Butyl Elastomers Market Vendor Landscape
Capability concentration sits with integrated petrochemical majors possessing captive isobutylene feedstock and polymerization expertise; scale advantage sits with diversified chemical conglomerates operating across multiple elastomer chemistries. The market structures around three archetypes: integrated refinery-polymer operators, specialty rubber compounders, and regional tire-captive producers. Dominant competitive moves include backward integration into C4 stream derivatives and geographic expansion through joint ventures in high-growth automotive corridors.
Among integrated petrochemical operators, ExxonMobil Corporation and Sinopec Corporation exemplify the refinery-polymer archetype with feedstock-advantaged positioning across Singapore and Chinese markets. Arlanxeo Holding B.V. represents the European specialty tier with dedicated halogenated lines serving tire OEM compliance requirements. These three anchors illustrate how capability depth in Ziegler-Natta polymerization systems separates sustainable margin structures from commodity-competitive positions.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| LANXESS AG |
| PJSC Nizhnekamskneftekhim |
| Sinopec Corporation |
| Reliance Industries Limited |
| Arlanxeo Holding B.V. |
| SIBUR International GmbH |
| Lion Elastomers |
| Petronas Chemicals Group Berhad |
| Others |
Supply Flow & Price Mechanics
Singapore-Jurong Island freight corridors carry halogenated butyl volumes whose shipping cost dynamics amplify the pricing power of integrated petrochemical complexes while squeezing distributor margins in downstream spot markets. This logistics concentration enables producers to enforce three-tier pricing structures across premium certified grades, standard mill-direct volumes, and economy spot-tier material.
Pricing Analysis
East Asian price spreads between Singapore-sourced bromobutyl and Indian standard-grade butyl reflect certification premiums for REACH-compliant medical grades versus construction-tier material. Contract-based long-term offtake dominates tire OEM procurement, with price differentiation driven by GB standard compliance documentation and volume scale commitments. Cost compression in standard-grade spot markets is intensifying because Chinese tire manufacturers are bypassing distributors for mill-direct contracts. Construction adhesive compounders exhibit highest price sensitivity, while German automotive OEMs accept premium positioning for certified inner liner grades.
Supply Chain Analysis
Isobutylene feedstock from C4 stream crackers in China, Singapore, and Saudi Arabia anchors global butyl elastomer production, with polymerization operations drawing from integrated refinery-polymer complexes. Raw material dependencies center on isobutylene monomer, isoprene comonomer, and halogenation reagents. Single-source vulnerability concentrates in Ziegler-Natta catalyst supply chains controlled by limited specialty chemical producers. Distribution runs through mill-direct channels for premium tire grades and regional chemical distributors for construction sealant spot purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Butyl elastomer demand fragmentation across tubeless tire specifications, green hydrogen infrastructure gaskets, and medical device compliance tiers creates specialist niches that favor focused entrants over diversified commodity producers.
For Market Incumbents: Entrench feedstock-advantaged positions through captive isobutylene supply expansion at Jurong Island and Ningbo petrochemical clusters. Thermoplastic vulcanizate substitution in industrial seals threatens traditional vibration damping compounds, requiring incumbents to deepen Ziegler-Natta polymerization expertise for high-molecular-weight grades that TPVs cannot replicate.
For New Entrants and Emerging Players: Build out electrolyzer gasket formulation capabilities targeting green hydrogen infrastructure projects in Saudi Arabia and the UAE, where specification consultants mandate certified compound traceability but incumbent supply relationships remain unformed. Digital compounding platforms offer the most penetrable entry vector, enabling rapid custom halobutyl blend development for specialty medical device prototyping without legacy reactor infrastructure.
For Investors and Strategic Acquirers: Regional tire-captive producers with qualified-supplier status under India's PLI scheme represent the most attractive acquisition archetype, combining localization advantages with unexploited halogenated grade potential. Watch for MEE environmental inspection intensity in Shandong province as an inflection signal—tightening enforcement would accelerate import substitution demand and validate domestic production bets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Stream Derivatives | Captive isobutylene supply insulates margin structures from crude-linked volatility in East Asian corridors. |
| REACH-Compliant Grade Certification | Medical and food-contact premiums stratify pricing tiers beyond commodity tire-grade competition. |
| Joint Venture in Indian Tire Corridor | PLI scheme incentives and BIS qualification pipelines open qualified-supplier slots for halogenated volumes. |
| Digital Compounding Platform Deployment | AI-driven formulation tools compress R&D cycles for custom medical device blends in German and Swiss markets. |
| Green Hydrogen Infrastructure Partnership | Electrolyzer gasket applications represent unpenetrated demand for high-purity butyl formulations in Middle Eastern megaprojects. |
Methodological Framework
Operator-level perspectives from tire compound procurement managers, petrochemical plant operations directors, medical device regulatory affairs leads, and construction adhesive formulation chemists anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from customs trade data, SEC 10-K filings of integrated petrochemical majors, REACH registration databases, and GB standard compliance documentation. Bottom-up volume modeling across grade tiers and end-use segments triangulated against top-down macroeconomic elasticity assumptions.
Scenario-bracketing around isoprene feedstock volatility bands and regulatory enforcement intensity variations shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry grade, application specification tier, end-user industry vertical, and regional production hub cluster. CAGRs derived from elasticity-adjusted volume trajectory analysis incorporating automotive production forecasts, construction cycle indicators, and medical device approval pipeline data.
Stress conditions across crude price shocks, MEE inspection intensity escalations, and TPV substitution acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about PLI scheme continuation and REACH compliance timeline stability. Material shifts in halogenated compound multijurisdictional registration divergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Medical Styrenic Block Copolymer (SBC) Market
Elastomeric Membrane
Hot Cast Elastomers Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
North America Performance Elastomer Market
Elastomeric Membrane
Global Elastomeric Coating Market
Elastomeric Membrane
Global Elastomeric Foam Market