
 Medical Styrenic Block Copolymer (SBC) Market | 2026-2036
Medical Styrenic Block Copolymer (SBC) Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Styrenic Block Copolymer (SBC) Market Intelligence
The gap between pharmaceutical-grade SBC and general-purpose compounds is rebalancing as medical device OEMs impose stricter extractables and leachables protocols. Kraton Corporation leverages its hydrogenated styrenic block copolymer portfolio to serve high-purity tubing applications. Dynasol Group anchors European supply through its Spanish manufacturing base. TSRC Corporation specializes in customized SEBS grades for wound care films.
Medical styrenic block copolymers are thermoplastic elastomers synthesized by living anionic polymerization of styrene and diene monomers into A-B-A triblock architectures, typically exhibiting Shore A hardness of 30–90 and elastomeric recovery above 90 percent for medical-grade formulations; these materials replace PVC, latex, and silicone in devices requiring clarity, sterilization resistance, and absence of plasticizers. Thermoplastic elastomers command the dominant volume position due to their versatility across tubing and seal applications. Drug delivery systems represent the fastest-expanding application segment as wearable injectors and auto-injectors proliferate. Polyisoprene-based SBC occupies a defensible niche in surgical glove and wound closure strips where synthetic rubber purity exceeds natural latex standards.
FDA enforces biocompatibility testing under ISO 10993 for all patient-contact SBC components, while EU MDR requires notified body intervention for Class IIa and above devices incorporating these polymers. The EPA scrutinizes residual monomer content in manufacturing effluent, particularly styrene and butadiene traces. REACH compliance for European medical device exports now extends to full substance-of-very-high-concern screening across SBC supply chains. Stakeholders must monitor evolving polymer notification requirements under the EU Green Deal's sustainable chemistry framework as regulators link medical material approvals to circularity credentials.
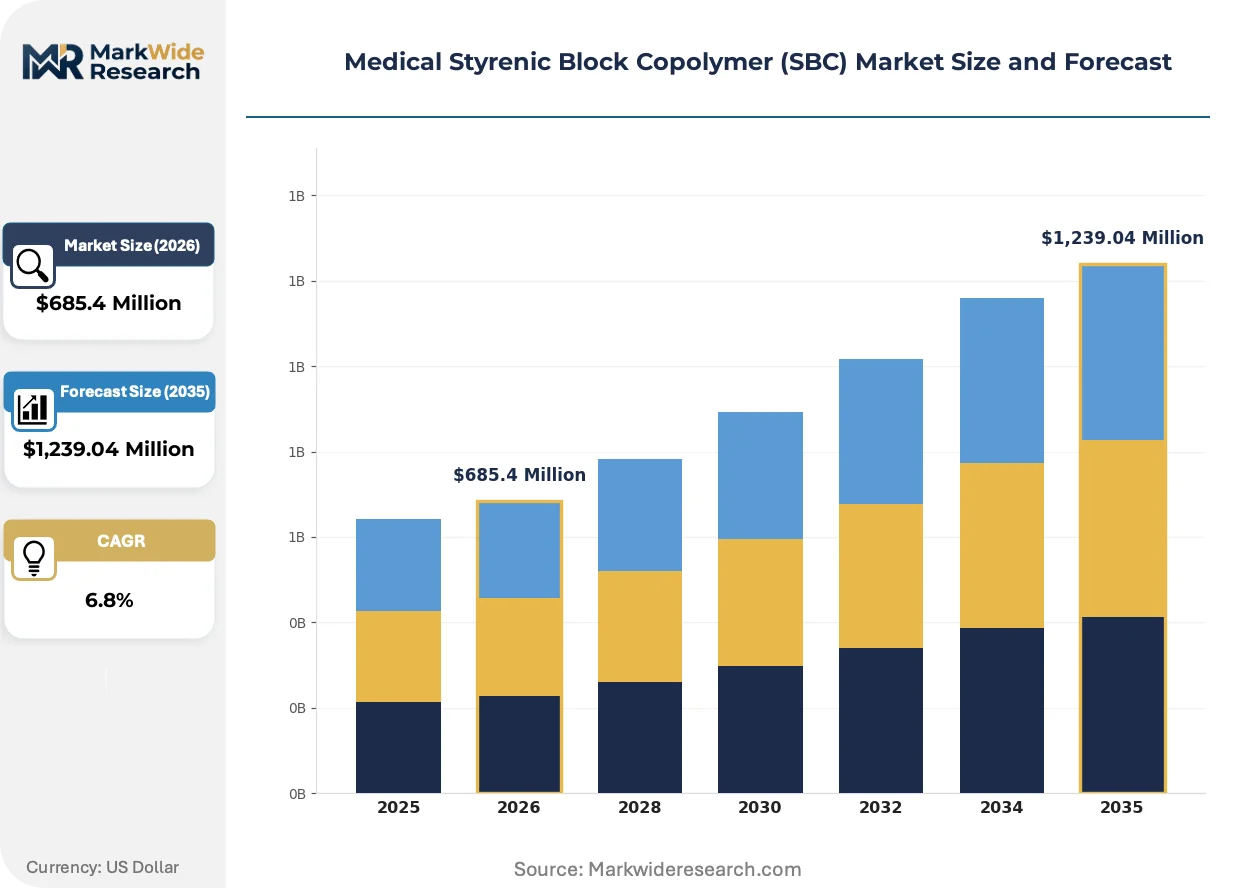
Market Dynamics
EU MDR and FDA biocompatibility mandates are compressing the supply base for patient-contact polymers, forcing medical device OEMs to abandon commodity elastomers in favor of certified SBC grades with documented extractables profiles.
Growth Catalysts
- EU MDR Class IIa intervention:Notified body scrutiny for tubing and seals drives substitution of PVC and latex with hydrogenated SBC formulations that carry pre-validated biocompatibility dossiers.
- Wearable drug delivery expansion:Auto-injector and patch-pump OEMs specify SEBS-based overmolded housings for chemical resistance and gamma sterilization stability.
- Styrene purification advances:Polymerization control technologies reduce residual monomer below 50 ppm, satisfying EPA effluent limits while qualifying materials for long-term implantable applications.
Market Restraints
- Butadiene feedstock volatility:SBR and SBS production competes with tire manufacturing for butadiene monomer, exposing medical compounders to petrochemical price swings.
- Hydrogenation capacity concentration:High-purity SEBS for pharmaceutical tubing relies on specialized hydrogenation assets concentrated in Germany and the United States.
- Silicone substitution persistence:Platinum-cured silicone retains preference in peristaltic pump tubing where ultra-low extractables specifications exceed current SBC capabilities.
Strategic Opportunities
- Indian medical device manufacturing:CDSCO production-linked incentive schemes attract tubing extruders to Gujarat and Karnataka, creating demand for imported SBC compound grades.
- Closed-loop recycling mandates:EU Green Deal sustainable chemistry frameworks reward SBC recyclability versus thermoset silicone, opening preference in single-use device procurement.
- 3D-printed surgical models:Photopolymerizable SBC resins enable patient-specific anatomical replicas for preoperative planning, converging elastomer processing with additive manufacturing.
Industry Challenges
- ISO 10993-18 analytical chemistry capacity:Extractables identification requires mass spectrometry expertise that contract laboratories struggle to scale for polymer qualification timelines.
- Legacy PVC validation burden:Device manufacturers face 18-24 month revalidation cycles when switching tubing formulations, delaying SBC adoption despite regulatory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Styrenic Block Copolymer (SBC) Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Elastomers, Polystyrene-Based SBC, Polybutadiene-Based SBC, Polyisoprene-Based SBC, SBS, SIS Application: Medical Tubing, Drug Delivery Systems, Wound Care, Surgical Instruments, Diagnostic Equipment, Orthopedic Devices End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Medical Device Manufacturers, Rehabilitation Centers Technology: Injection Molding, Extrusion, Blow Molding, Compression Molding, Thermoforming |
| Companies Covered | Kumho Petrochemical, TSRC Corporation, Kraton Corporation, China Petroleum & Chemical Corporation, Dynasol Group, LG Chem, Asahi Kasei Corporation, Zeon Corporation, Trinseo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Styrenic Block Copolymer (SBC) Market Strategic Shifts & Innovations
Material science convergence with digital manufacturing is compressing development cycles for patient-specific devices, while regulatory chemistry requirements reshape formulation priorities across the polymer supply chain.
Hydrogenated styrenic block copolymer compounding is unifying clarity, sterilization resistance, and plasticizer-free performance in a single thermoplastic platform. Drug delivery device manufacturers in Germany and the United States adopt these grades at accelerated qualification paces. This unification enables thinner-wall tubing designs that reduce material intensity per device while maintaining burst pressure ratings.
REACH substance-of-very-high-concern screening now extends to full SBC supply chain disclosure for European medical device exports. The regulation forces compounders to document monomer origins and catalyst residues across tier-two suppliers. Tubing extruders serving EU markets respond by consolidating procurement onto pre-audited polymer grades with bundled regulatory dossiers.
Hospital procurement consortiums increasingly specify certified sustainable content in elastomer purchasing agreements. Group purchasing organizations in the United States now require recycled content documentation or mass-balance certificates for single-use device polymers. This specification shift concentrates contract awards toward SBC suppliers with ISCC PLUS or equivalent chain-of-custody certifications.
Medical Styrenic Block Copolymer (SBC) Market Segmentation
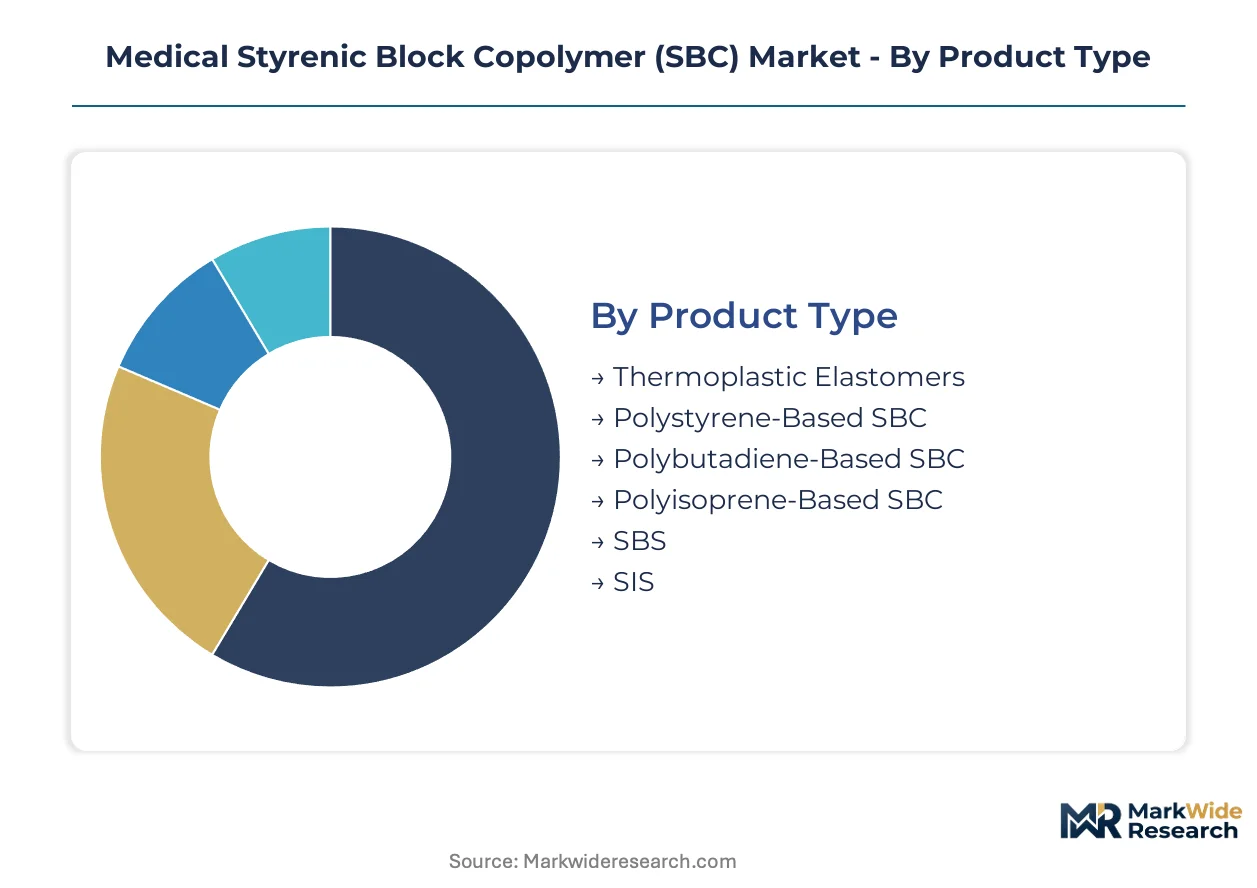
Segmentation in medical SBC markets reveals how polymer architecture, processing technology, and end-use requirements intersect to determine qualification pathways and commercial viability. Device OEMs prioritize segments offering pre-validated biocompatibility dossiers to compress regulatory timelines.
Product Type:
Thermoplastic elastomers operate as standalone materials in finished devices, while polystyrene-based and polybutadiene-based grades typically embed within multi-layer constructions requiring interface compatibility.
- Thermoplastic Elastomers:Hydrogenated SEBS formulations deliver Shore A 30–90 hardness with gamma sterilization stability. German tubing extruders specify these grades for auto-injector housings where clarity and plasticizer-free performance are mandatory.
- Polystyrene-Based SBC:Rigid styrenic end-blocks provide structural integrity in diagnostic equipment housings. United States device manufacturers integrate these polymers into overmolded grips requiring chemical resistance to disinfectants.
- Polybutadiene-Based SBC:Butadiene mid-blocks supply elastomeric recovery in compression seals. These grades compete with natural rubber in peristaltic pump applications.
- Polyisoprene-Based SBC:Synthetic isoprene purity exceeds natural latex standards for surgical glove films. Japanese wound care manufacturers specify these grades for hypoallergenic adhesive strips.
- SBS:Styrene-butadiene-styrene triblock architecture balances cost and performance in general medical tubing. Non-hydrogenated grades face substitution pressure from SEBS in patient-contact applications.
- SIS:Styrene-isoprene-styrene polymers offer superior tack for pressure-sensitive adhesive coatings in transdermal patches.
Thermoplastic elastomers lead volumes today; polyisoprene-based SBC is gaining share fastest in premium wound care segments.
Application:
Application segmentation tracks the migration from commodity elastomers toward certified SBC grades as FDA and EU MDR tighten extractables protocols for patient-contact surfaces.
- Medical Tubing:Thin-wall SEBS extrusions replace PVC in infusion sets and drainage lines. United States compounders qualify hydrogenated grades for gamma-stable fluid pathways with documented leachables profiles.
- Drug Delivery Systems:Auto-injector and patch-pump OEMs specify overmolded SBC housings for chemical resistance to drug formulations. Wearable device proliferation concentrates demand in Massachusetts and Bavaria manufacturing clusters.
- Wound Care:Breathable SBC films enable moisture-vapor transmission in advanced dressings. These materials displace polyurethane in hydrocolloid adhesive layers.
- Surgical Instruments:Overmolded SBC grips provide tactile feedback and sterilization durability. German instrument manufacturers validate these components for autoclave cycles.
- Diagnostic Equipment:Rigid SBC housings protect electromechanical components in point-of-care devices. Clarity grades support optical detection windows.
- Orthopedic Devices:Cushioning SBC layers absorb impact in prosthetic liners and bracing systems.
Medical tubing commands the largest installed base; drug delivery systems are expanding most quickly as wearable platforms proliferate.
End User:
End user segmentation reflects procurement concentration among integrated device manufacturers versus fragmented hospital purchasing, with regulatory qualification burdens falling disproportionately on direct manufacturers.
- Medical Device Manufacturers:OEMs in Germany and the United States drive specification of pharmaceutical-grade SBC with bundled ISO 10993 dossiers. These buyers consolidate supply onto audited compounders to streamline FDA and EU MDR submissions.
- Hospitals:Group purchasing organizations increasingly specify sustainable content certificates for single-use device elastomers. United States procurement consortiums reward ISCC PLUS documentation in contract awards.
- Ambulatory Surgical Centers:Cost-sensitive outpatient facilities prioritize standard-grade SBC in disposable instruments.
- Diagnostic Laboratories:Automated analyzer manufacturers specify rigid SBC housings for chemical resistance to reagents.
- Rehabilitation Centers:Orthotic and prosthetic providers demand cushioning SBC grades for patient comfort in long-wear devices.
Medical device manufacturers dominate procurement volumes today; diagnostic laboratories are climbing the fastest as automation expands.
Technology:
Processing technology segmentation determines which SBC grades achieve commercial scale, with injection molding and extrusion commanding dedicated compounding lines while blow molding and thermoforming occupy specialized niches.
- Injection Molding:High-cavitation tooling produces drug delivery components with tight dimensional tolerances. United States molders qualify hydrogenated SEBS for multi-shot overmolding of auto-injector triggers.
- Extrusion:Continuous profile production dominates medical tubing and film applications. German extruders operate dedicated cleanrooms for pharmaceutical-grade SBC processing.
- Blow Molding:Limited adoption in collapsible reservoir bottles for enteral feeding systems.
- Compression Molding:Niche use in thick-section seals and gaskets requiring low residual stress.
- Thermoforming:Shallow-draw trays and blisters from SBC sheet for device packaging applications.
Extrusion leads volumes today; injection molding is gaining share fastest as complex drug delivery devices proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer chemists and regulatory affairs specialists concentrate in Germany, the United States, and Japan, anchoring the highest-value SBC qualification workflows. Device manufacturers in these markets impose extractables protocols that compounders elsewhere struggle to replicate.
United States
FDA biocompatibility mandates under ISO 10993-18 compress supplier qualification timelines for drug delivery device OEMs. Massachusetts and Minnesota manufacturing clusters specify hydrogenated SEBS grades for auto-injector housings requiring gamma sterilization stability. EPA scrutiny of residual styrene in manufacturing effluent drives purification investments at compounding facilities.
Germany
EU MDR notified body intervention for Class IIa tubing devices accelerates substitution of PVC with pharmaceutical-grade SBC formulations. Bavarian extruders operate dedicated cleanrooms for medical-grade hydrogenated block copolymer processing. REACH substance-of-very-high-concern screening now extends to full SBC supply chain disclosure for device exports.
Japan
PMDA quality management system audits enforce documented leachables profiles for patient-contact polymers. Osaka-based wound care manufacturers specify polyisoprene-based SBC grades for hypoallergenic adhesive strips. METI industrial standards for medical device materials align with international biocompatibility frameworks.
China
NMPA medical device registration requirements tighten for imported elastomer components in infusion sets. Yangtze River Delta compounders expand hydrogenation capacity to serve domestic drug delivery device assembly. GB standards for medical-grade thermoplastic elastomers converge with ISO 10993 testing protocols.
India
CDSCO production-linked incentive schemes attract tubing extruders to Gujarat and Karnataka manufacturing corridors. Domestic device manufacturers qualify imported SBC compound grades for infusion set production. Central government medical device park initiatives concentrate polymer conversion capacity near pharmaceutical clusters.
Medical Styrenic Block Copolymer (SBC) Market Key Industry Players
Top-tier vendors anchor hydrogenation capacity and pharmaceutical-grade qualification dossiers, while regional compounders compete on standard-grade tubing formulations. Market structure reflects concentration in high-purity SEBS production alongside fragmentation in general medical elastomer compounding. Strategic archetypes include integrated petrochemical producers with captive monomer supply, specialized hydrogenation houses with FDA master files, and regional compounders serving cost-sensitive disposable markets. Dominant competitive moves center on backward integration into styrene purification and geographic expansion through qualified toll compounding partnerships.
Within the integrated petrochemical tier, Kumho Petrochemical and LG Chem represent scale-driven positions with styrene-butadiene raw material access. Kraton Corporation exemplifies the specialized hydrogenation archetype, while TSRC Corporation occupies a position among Asia-Pacific compounders with customized SEBS capabilities. Dynasol Group anchors European supply through its Spanish manufacturing presence.
| Leading Market Players |
|---|
| Kumho Petrochemical |
| TSRC Corporation |
| Kraton Corporation |
| China Petroleum & Chemical Corporation |
| Dynasol Group |
| LG Chem |
| Asahi Kasei Corporation |
| Zeon Corporation |
| Trinseo SA |
| Others |
Cost & Logistics Intelligence
Backward integration into styrene purification anchors pricing power for hydrogenated SEBS producers serving FDA and EU MDR qualified tubing markets. Compounders with captive monomer supply and in-house hydrogenation assets in Germany and the United States command premium positioning against toll-dependent competitors.
Pricing Analysis
Bundled regulatory dossiers versus unbundled raw polymer supply defines the pricing architecture. Three-tier pricing structure across pharmaceutical-grade, medical-grade, and standard-grade levels reflects ISO 10993 certification depth and extractables documentation completeness. Cost compression in standard tubing grades intensifies because Indian and Chinese compounders expand hydrogenation capacity. Hospital procurement consortiums show lowest price sensitivity for pre-validated SEBS grades with bundled FDA master files, while ambulatory surgical centers prioritize economy-tier formulations.
Supply Chain Analysis
Single-source vulnerability sits with specialized hydrogenation assets concentrated in Germany and the United States. Butadiene feedstock draws from petrochemical complexes in South Korea, Japan, and Thailand, while styrene monomer feeds from integrated crackers in the United States and Europe. Tariff exposure on imported hydrogenated grades threatens compounders serving Indian device manufacturers. Distribution runs through qualified toll compounders with FDA-registered facilities before reaching medical device OEMs in Massachusetts and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical SBC functions as a regulatory compounder where EU MDR Class IIa notified body intervention forces device OEMs toward certified grades with pre-submitted biocompatibility dossiers.
For Market Incumbents: Anchor hydrogenation capacity expansion in Germany and the United States to defend against emerging Indian compounders capturing standard-grade tubing contracts. Consolidate supply relationships with auto-injector OEMs in Massachusetts and Bavaria through dedicated cleanroom compounding lines. Certification investment in REACH substance-of-very-high-concern screening capabilities protects European export positioning. For New Entrants and Emerging Players: Capture CDSCO production-linked incentive corridors in Gujarat and Karnataka by qualifying imported SEBS compound grades for domestic infusion set manufacturers. Target diagnostic laboratory automation as the most penetrable end-use segment where rigid SBC housing demand outpaces established supplier qualification capacity. Pursue toll compounding partnerships with FDA-registered facilities as the primary go-to-market pathway. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with ISO 10993 testing capabilities because device OEM procurement consolidation favors bundled regulatory dossiers over fragmented raw polymer sourcing. Five-to-ten year viability hinges on hydrogenation asset scarcity and expanding EU MDR compliance burdens. Watch CDSCO medical device park development timelines as the signal indicating when Indian domestic compounding reaches import substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Styrene Purification | Captive monomer supply secures sub-50 ppm residual specifications for long-term implantable grades. |
| FDA Master File Expansion | Pre-submitted biocompatibility dossiers compress OEM qualification timelines for drug delivery components. |
| EU MDR Notified Body Partnership | Early engagement with German and Spanish notified bodies accelerates Class IIa device approvals. |
| ISCC PLUS Certification | Mass-balance credentials satisfy United States GPO sustainable content requirements for single-use devices. |
| Indian Toll Compounding Network | CDSCO-registered facilities enable local conversion of imported SBC compounds for domestic device assembly. |
Research Approach
Multiple input streams — primary interviews with polymer chemists, regulatory affairs specialists, and medical device procurement managers, alongside secondary validation through FDA 510(k) filings, EU MDR notified body guidance documents, and customs trade data — were reconciled through bottom-up tubing volume estimates and top-down elastomer market sizing.
Historical capacity utilization patterns were cross-referenced against expert panel inputs on hydrogenation asset expansion timelines across the projection horizon. Segmentation dimensions modeled include polymer architecture, processing technology, application end-use, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections for auto-injector and wearable pump platforms, with butadiene feedstock pricing volatility incorporated as a sensitivity input.
Regulatory timeline delays, feedstock price spikes, and OEM formulation revalidation cycles are the dominant revision risks to demand forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
High Temperature Elastomers Market
Elastomeric Membrane
Stretchable Conductive Material Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market