
 Vinyl Terminated Polydimethylsiloxane Market | 2026-2036
Vinyl Terminated Polydimethylsiloxane Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Terminated Polydimethylsiloxane Market Outlook
Fluorosilicone is broadening its addressable market as vinyl terminated polydimethylsiloxane captures cost-performance advantages in high-temperature sealant applications. Wacker Chemie AG leverages integrated siloxane production from quartz through downstream functional polymers to sustain margin control across European and Asian supply corridors. GELEST anchors its position through specialty organosilicon R&D intensity, offering custom molecular weights that competitors struggle to replicate at comparable lead times.
Vinyl terminated polydimethylsiloxane denotes a linear siloxane polymer capped with vinyl functional groups, typically ranging from 100 to 65,000 centistokes in viscosity, manufactured via equilibration polymerization of dimethylsiloxane cyclic oligomers with vinyl-terminated end-blockers. The material serves as a reactive intermediate for platinum-catalyzed addition curing in liquid silicone rubber, adhesives, and conformal coatings where precise crosslink density governs elastomer performance. Among product type segments, sealants command the dominant volume position due to infrastructure durability specifications, while coatings represent the fastest-expanding margin pool as electronics miniaturization drives thin-film thermal management demand. Application segmentation shows automotive consuming the largest share of high-viscosity grades for gasketing, with electronics pulling lower-viscosity formulations for potting and encapsulation where ionic purity requirements exceed 10 ppm thresholds.
REACH registration through ECHA mandates full toxicological dossiers for siloxane imports above one tonne annually, elevating compliance costs for non-European suppliers and reshaping competitive access to European automotive OEM qualified vendor lists. China's SAMR enforces GB standards on volatile content in silicone intermediates used in food-contact and medical applications, creating divergent purity certification requirements that fragment formulation strategies across export markets. FDA device master file expectations for implant-grade silicones further complicate qualification pathways for medical end uses. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation customization or unified global specifications yield superior returns on compliance investment.
Market Dynamics
Platinum-catalyzed addition curing specifications from automotive electronics manufacturers are compressing formulation tolerances for vinyl-terminated PDMS intermediates, forcing suppliers to tighten viscosity control within narrower centistoke bands or lose qualified vendor status.
Growth Catalysts
- Automotive sensor module expansion:German and Chinese OEMs are expanding silicone encapsulation procurement for ADAS components, pulling high-purity vinyl-terminated grades into safety-critical supply chains.
- REACH registration thresholds:ECHA mandates above one tonne annually are elevating compliance costs for non-European suppliers, advantaging ECHA-registered incumbents in European automotive qualified vendor lists.
- Thin-film thermal management:Electronics miniaturization is overtaking traditional potting methods, creating specification pull for low-viscosity vinyl-terminated formulations in conformal coating applications.
Market Restraints
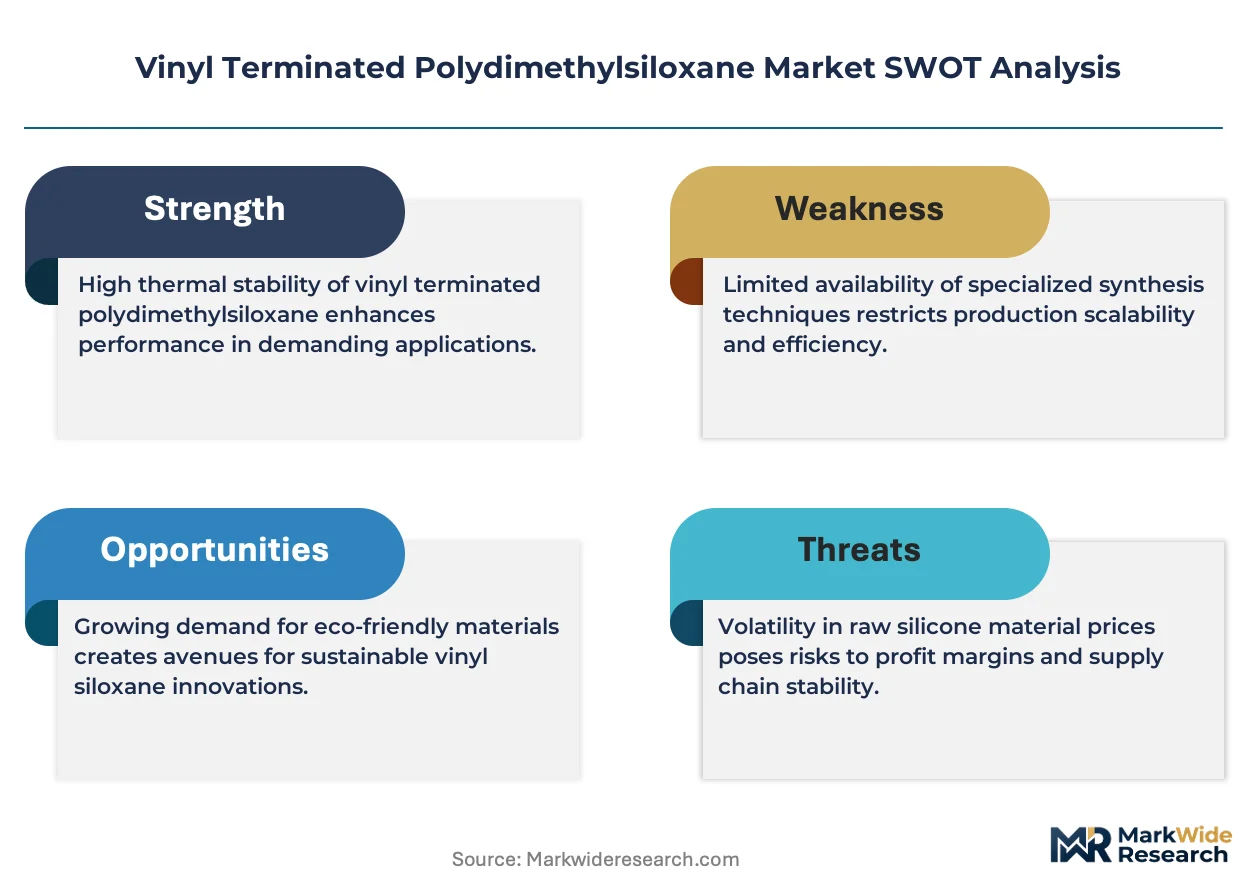
- Siloxane cyclic oligomer feedstock volatility:D4/D5/D6 raw material costs fluctuate with energy pricing, compressing margin predictability for equilibration polymerization operations.
- Qualified supplier concentration:FDA device master file holders for implant-grade silicones number fewer than twelve globally, creating single-source risk for medical device formulators.
- Fluorosilicone substitution pressure:Fuel-resistant fluorosilicone grades are capturing select automotive sealing applications where hydrocarbon exposure exceeds PDMS tolerance thresholds.
Strategic Opportunities
- India medical device manufacturing:CDSCO regulatory harmonization with FDA pathways is enabling faster qualification of implant-grade silicone intermediates for domestic and export production.
- GB standard alignment services:SAMR volatility specifications for food-contact silicones create consulting and certification revenue streams for laboratories assisting Western suppliers entering Chinese markets.
- Hybrid thermal interface materials:Convergence of vinyl-terminated PDMS with boron nitride fillers is opening specification windows in data center thermal management where grease-to-pad transitions are accelerating.
Industry Challenges
- Organosilicon synthesis expertise scarcity:Platinum catalyst handling and equilibration kinetics require specialized chemists whose training pipelines lag demand expansion in Asian manufacturing hubs.
- Dual jurisdiction qualification timelines:Simultaneous FDA device master file and ECHA REACH dossier preparation stretches regulatory affairs capacity, delaying market entry for mid-cap suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Terminated Polydimethylsiloxane Market |
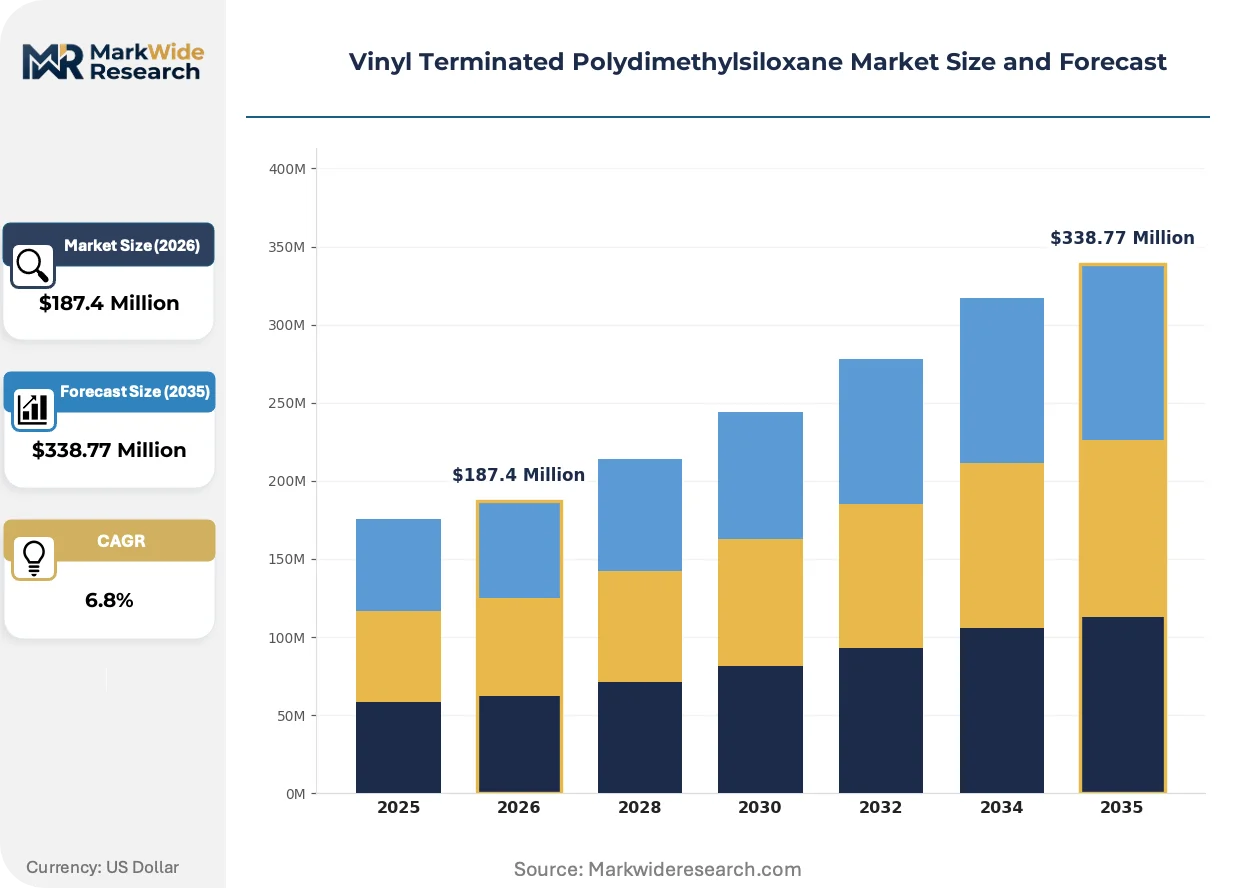
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Sealants, Coatings, Compounds Application: Automotive, Electronics, Construction, Consumer Goods End User: Manufacturers, Contractors, Distributors, Retailers Form: Liquid, Paste, Solid, Gel |
| Companies Covered | PCC Group, GELEST, DyStar, Siltech, Milliken Chemical, AB Specialty Silicones, BRB International, Wacker Chemie AG, BlueStar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Terminated Polydimethylsiloxane Market Strategic Shifts
Specification compression across automotive and medical end uses is fragmenting the vinyl-terminated PDMS market into performance-tiered supply tiers, with purity certification becoming the primary competitive differentiator over commodity pricing.
Low-viscosity vinyl-terminated grades below 1,000 centistokes serve conformal coating applications where ionic purity below 10 ppm governs corrosion resistance in miniaturized electronics. Japanese electronics contract manufacturers are adopting these formulations at accelerated qualification cycles compared to traditional potting compounds. Thin-film deposition equipment compatibility is overtaking bulk viscosity as the primary specification driver, compressing addressable supply base to polymerization operations with sub-batch molecular weight control.
China's SAMR enforcement of GB standards on volatile content in silicone intermediates is fragmenting formulation strategies between export and domestic Chinese medical device markets. Western suppliers face divergent purity certification requirements that prevent unified global specifications, elevating regional customization costs. Medical-grade vinyl-terminated PDMS manufacturers are responding with parallel product lines certified to FDA, EMA, and NMPA standards simultaneously.
Specification-driven purchasing from Tier 1 automotive electronics suppliers is consolidating procurement authority away from compounders toward qualified raw material vendors with direct OEM relationships. Distributor intermediaries are losing specification influence as automotive buyers demand direct polymerization traceability for lot-level viscosity certification. This channel compression is most visible in German automotive clusters where KBA safety documentation requirements mandate supplier identity preservation through the value chain.
Vinyl Terminated Polydimethylsiloxane Market Segmentation
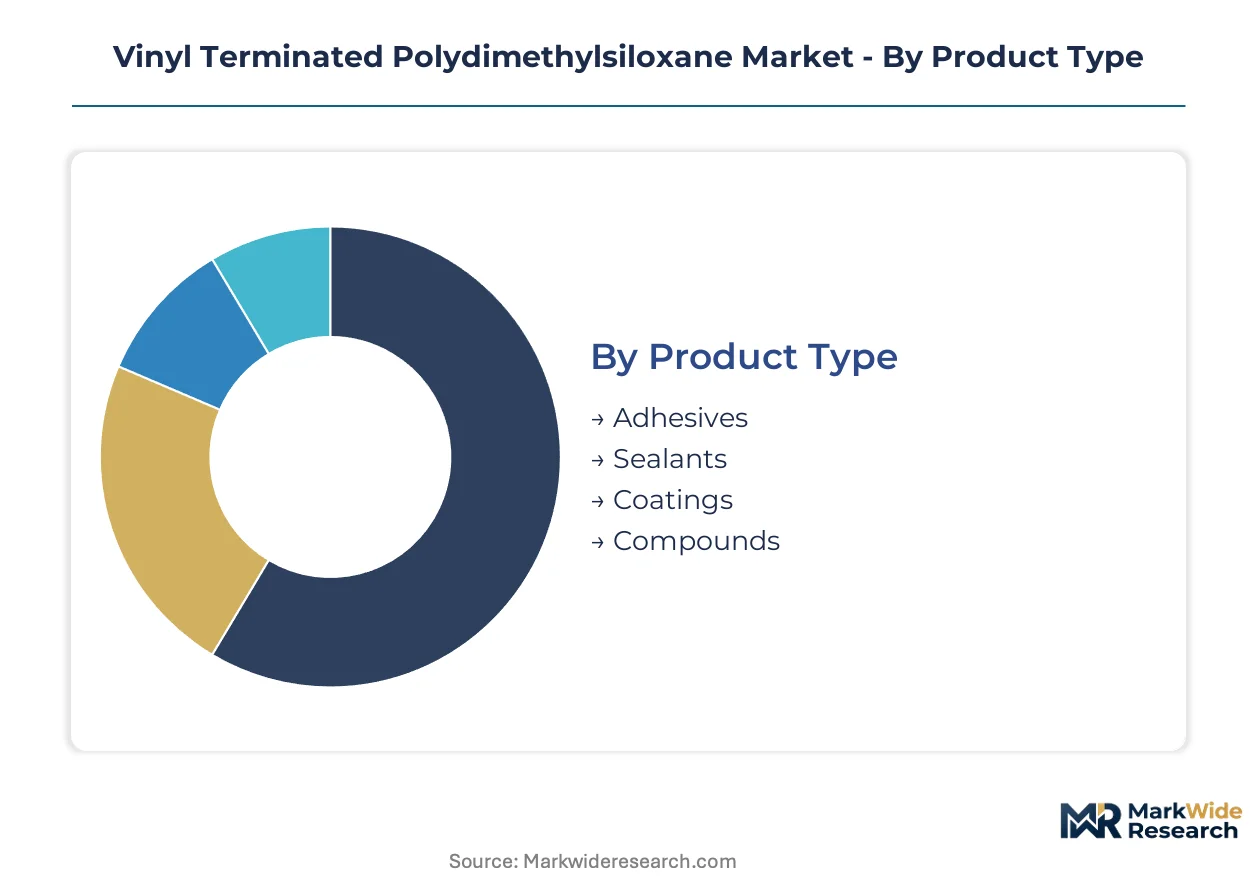
Segmentation in vinyl-terminated PDMS reveals how specification requirements fragment supply tiers. Automotive and electronics buyers demand traceable viscosity certification that commodity grades cannot satisfy. Understanding these divisions exposes where margin pools concentrate versus where price competition dominates.
Product Type:
Viscosity bands and curing chemistry specifications differentiate performance tiers across formulation categories.
- Sealants:High-viscosity grades from 10,000 to 65,000 centistokes dominate infrastructure and automotive gasketing where compression set resistance governs specification. German automotive OEMs specify lot-level viscosity certification within 5% tolerance bands for powertrain sealing applications.
- Coatings:Low-viscosity formulations below 1,000 centistokes enable thin-film conformal deposition for thermal management in miniaturized electronics. Japanese contract manufacturers are accelerating qualification cycles for ionic purity below 10 ppm to prevent corrosion in dense circuit assemblies.
- Adhesives:Medium-viscosity intermediates balance wetting and green strength for assembly bonding in medical device manufacturing.
- Compounds:Pre-formulated blends with fillers serve molders lacking in-house compounding capability for specialty elastomer production.
Sealants lead on scale; coatings lead on momentum.
Application:
End-use specifications compress formulation tolerances to degrees that eliminate non-specialized suppliers from qualified vendor lists.
- Automotive:Platinum-catalyzed addition curing requirements from Tier 1 electronics suppliers mandate viscosity control within narrow centistoke bands. KBA safety documentation in Germany preserves supplier identity through the value chain, compressing channel intermediaries.
- Electronics:Potting and encapsulation demand ionic purity exceeding 10 ppm thresholds for corrosion resistance in sensor modules. ADAS component expansion in China and Germany is pulling high-purity grades into safety-critical supply chains.
- Construction:Infrastructure durability specifications favor high-viscosity sealants for expansion joint and glazing applications.
- Consumer Goods:Personal care and household product formulations utilize lower-specification grades where cost sensitivity outweighs performance certification.
Automotive commands premium pricing; electronics expands most quickly.
End User:
Procurement authority concentrates differently across buyer types, determining whether specification or price dominates purchasing decisions.
- Manufacturers:Direct OEM relationships and qualified vendor status requirements give polymerization operations with ECHA registration and FDA device master files preferred access to automotive and medical supply chains.
- Contractors:Construction and installation firms prioritize availability and delivery reliability over molecular weight precision for field-applied sealant applications.
- Distributors:Channel intermediaries are losing specification influence as automotive buyers demand direct polymerization traceability, compressing their role to logistics rather than technical selection.
- Retailers:Consumer-facing sales of DIY sealant and adhesive products operate on brand recognition and price positioning with minimal technical differentiation.
Manufacturers capture specification premium; distributors face margin compression.
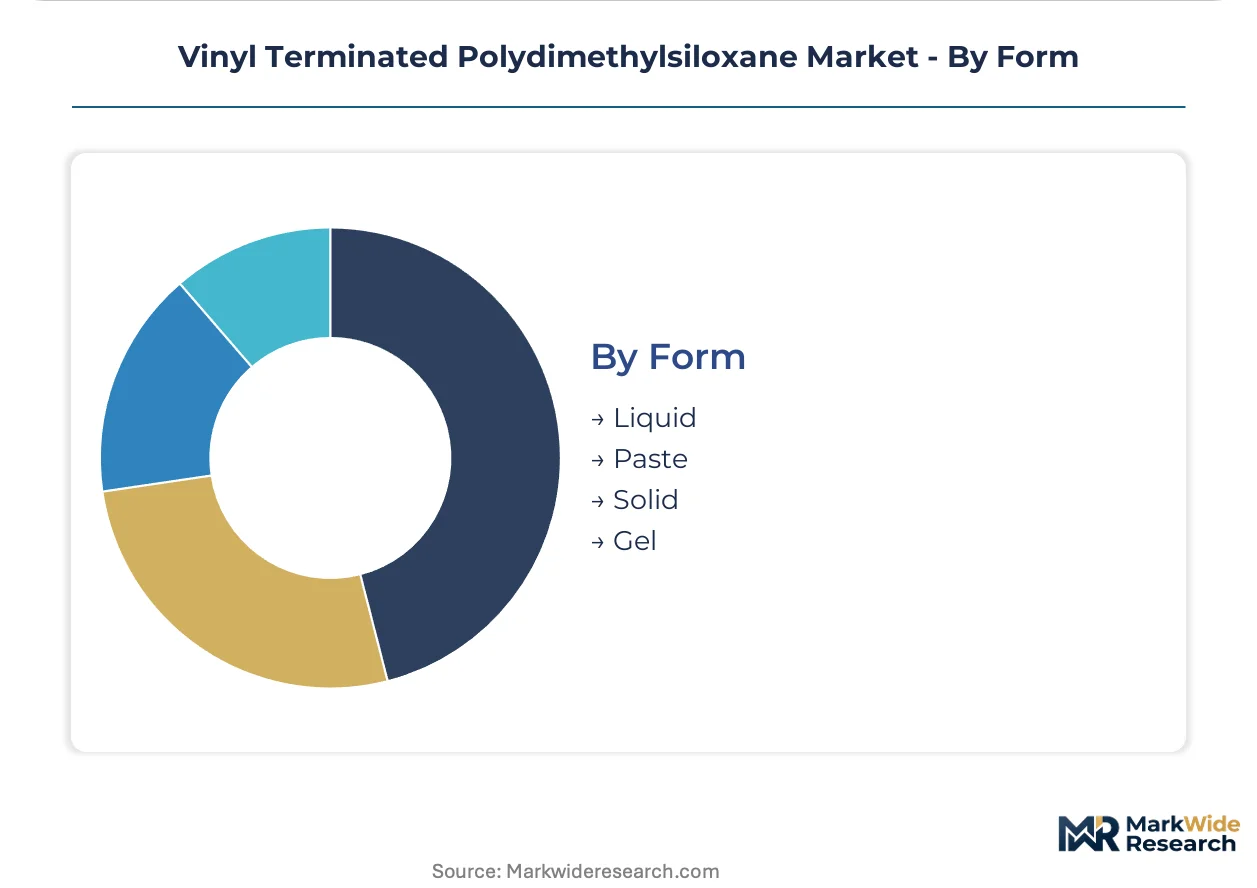
Form:
Physical state determines equipment compatibility and application method, segmenting addressable markets by processing infrastructure.
- Liquid:Pumpable low-viscosity grades enable automated dispensing in electronics potting and conformal coating lines where thin-film deposition equipment compatibility governs selection.
- Paste:Thixotropic formulations resist sag in vertical joint sealing and automotive gasket applications requiring controlled flow under compression.
- Solid:Pre-formed sheets and profiles serve compression molding operations for custom elastomer components in medical device manufacturing.
- Gel:Soft, low-modulus materials provide vibration damping and environmental protection for delicate electronic assemblies in automotive sensor modules.
Liquid dominates volume throughput; gel gains share fastest in emerging thermal management specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive electronics clusters in Stuttgart and Munich generate concentrated procurement of high-viscosity vinyl-terminated PDMS grades for ADAS sensor encapsulation. ECHA REACH registration requirements above one tonne annually reshape competitive access across European supply chains.
United States
FDA device master file expectations for implant-grade silicones compress qualified supplier lists for medical device formulators. EPA oversight of siloxane manufacturing emissions elevates compliance investment for domestic polymerization operations. Michigan and Ohio automotive corridors pull high-purity grades into powertrain sealing applications with lot-level viscosity certification requirements.
China
SAMR enforcement of GB standards on volatile content fragments formulation strategies between export and domestic medical device markets. Dual carbon goals from MEE accelerate energy efficiency mandates for equilibration polymerization operations. Yangtze River Delta electronics manufacturers in Suzhou and Shanghai adopt low-viscosity formulations below 1,000 centistokes for conformal coating deposition.
Japan
METI industrial standards for electronics-grade silicones specify ionic purity thresholds below 10 ppm for corrosion resistance in dense circuit assemblies. PMDA alignment with FDA pathways streamlines qualification for implant-grade intermediates in domestic medical device production. Kanto region contract manufacturers accelerate qualification cycles for thin-film thermal management specifications.
India
CDSCO regulatory harmonization with FDA pathways enables faster qualification of implant-grade silicone intermediates for domestic and export production. PLI scheme incentives for medical device manufacturing attract formulation investments to Gujarat and Maharashtra clusters. Mumbai-Pune corridor specialty chemical operations expand organosilicon synthesis capacity to serve regional electronics and automotive demand.
South Korea
MFDS pharmaceutical-grade silicone standards create parallel certification requirements for medical device exports to European and North American markets. Seoul Capital Area electronics manufacturers specify sub-batch molecular weight control for automated dispensing compatibility. Busan-Ulsan chemical complexes develop backward integration into siloxane cyclic oligomer feedstock production.
Vinyl Terminated Polydimethylsiloxane Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers respond to specification compression from automotive and medical end users. The vendor base stratifies across three performance tiers: ECHA-registered integrated producers with quartz-to-polymer operations, FDA device master file holders serving implant-grade markets, and regional compounders lacking direct OEM qualification. Strategic archetypes include integrated siloxane manufacturers controlling feedstock costs, specialty organosilicon R&D houses offering custom molecular weights, and distribution-focused intermediaries losing specification influence. M&A activity and geographic expansion represent the dominant competitive vectors as mid-cap suppliers seek ECHA registration and FDA dossier capabilities.
Among integrated German producers, Wacker Chemie AG exemplifies the archetype of quartz-through-polymer operations sustaining margin control across European and Asian supply corridors. GELEST occupies a position within the specialty R&D tier, representing custom molecular weight capabilities that competitors struggle to replicate at comparable lead times. BRB International anchors the regional European specialist category, serving qualified vendor lists with targeted formulation support.
| Leading Market Players |
|---|
| PCC Group |
| GELEST |
| DyStar |
| Siltech |
| Milliken Chemical |
| AB Specialty Silicones |
| BRB International |
| Wacker Chemie AG |
| BlueStar |
| Others |
Value Chain & Pricing Dynamics
D4/D5/D6 siloxane cyclic oligomer spot prices cascade through equilibration polymerization operations into three distinct formulation tiers, with energy-indexed feedstock contracts compressing margin predictability for non-integrated compounders serving automotive and medical end users.
Pricing Analysis
Input-cost pass-through from D4/D5/D6 cyclic oligomer feedstock anchors contract-based long-term offtake agreements between integrated producers and German automotive OEMs, with pricing stratifying across implant-grade FDA master file tiers, automotive-qualified ECHA-registered grades, and uncertified commodity volumes. Price differentiation rests on certification level and viscosity precision, with ionic purity below 10 ppm commanding substantial premiums over standard industrial grades. Cost compression in commodity tiers intensifies as Chinese manufacturers expand equilibration capacity, while medical and automotive buyers show minimal price sensitivity due to qualified vendor list constraints and safety-critical application requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale procurement from German and Chinese automotive electronics manufacturers, bypassing traditional distributor intermediaries that previously held specification influence. Geographic supply concentrates in Germany, China, and the United States, with raw material dependencies on siloxane cyclic oligomer feedstock, platinum catalyst systems, and vinyl-terminated end-blockers. Single-source vulnerability pervades FDA device master file holders for implant-grade silicones, where fewer than twelve qualified suppliers globally create concentration risk for medical device formulators. Distribution runs through qualified raw material vendors with direct polymerization traceability rather than compounder intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vinyl-terminated PDMS functions as a stable compounder anchored by automotive electronics specification compression that perpetually renews demand for certified high-purity grades across replacement cycles and platform generations.
For Market Incumbents: To counter fluorosilicone substitution in fuel-resistant automotive sealing applications, deepen backward integration into siloxane cyclic oligomer production and accelerate ECHA REACH dossier completion for sub-one-tonne registration thresholds that competitors have not yet crossed. Priority rests on securing KBA safety documentation pathways that preserve supplier identity through German automotive value chains. For New Entrants and Emerging Players: Launch via CDSCO-aligned regulatory consulting services targeting Indian medical device manufacturers seeking faster FDA pathway qualification for implant-grade silicone intermediates. White-space concentrates in hybrid thermal interface materials combining vinyl-terminated PDMS with boron nitride fillers for data center thermal management, and in GB standard alignment services for Western suppliers entering Chinese food-contact silicone markets under SAMR enforcement. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap suppliers lack simultaneous FDA device master file and ECHA REACH registration capabilities, stretching regulatory affairs capacity beyond internal resources. Long-term viability favors acquisition of ECHA-registered European specialists with custom molecular weight R&D infrastructure and direct OEM relationships in automotive electronics clusters. The signal to watch is qualification timeline compression in Japanese electronics contract manufacturers adopting sub-batch molecular weight control specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstock | Captive D4/D5/D6 supply insulates margin control from energy price volatility affecting German and Asian competitors. |
| ECHA REACH Dossier Completion | Full toxicological registration above one tonne annually secures qualified vendor status with Stuttgart and Munich automotive clusters. |
| Custom Molecular Weight R&D Expansion | Sub-batch viscosity precision addresses Japanese electronics manufacturers' thin-film deposition equipment compatibility requirements. |
| CDSCO Regulatory Pathway Investment | FDA-aligned qualification infrastructure captures PLI scheme incentives attracting medical device manufacturing to Gujarat clusters. |
| Hybrid Thermal Interface Material Development | Boron nitride filler convergence opens specification windows in data center thermal management where grease-to-pad transitions accelerate. |
Study Parameters
Direct dialogue with silicone polymerization plant managers, automotive Tier 1 procurement leads, medical device regulatory affairs directors, and specialty chemical distribution channel partners grounded qualitative assessment, validated against customs trade data, ECHA registration databases, FDA device master file listings, and SEC filings from integrated siloxane producers. Bottom-up volume triangulation across viscosity bands and application segments converged with top-down value estimates derived from end-use consumption patterns.
Segment-level projections across sealant, coating, adhesive, and compound formulations incorporated automotive electronics content-per-module trajectories, medical device implant-grade certification timelines, and electronics miniaturization-driven conformal coating adoption curves throughout the forecast period. CAGRs emerged from regression analysis of historical equilibration capacity expansion, feedstock cost pass-through elasticities, and regulatory qualification lag structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SAMR GB standard enforcement volatility, platinum catalyst supply disruptions, and fluorosilicone substitution acceleration in hydrocarbon-exposed automotive applications. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
High Temperature Elastomers Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Rubber Membrane Market
Elastomeric Membrane
Global Thermoplastic Elastomers (TPE) Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Water Soluble Elastomers Market