
 Polydimethylsiloxane (PDMS) Market | 2026-2036
Polydimethylsiloxane (PDMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Polydimethylsiloxane (PDMS) Market Analytics
Multi-sourcing of silicone precursors is broadening as formulators reduce dependence on single-region supply chains. Dow sustains captive chlorosilane production across North American and European sites. Shin-Etsu Chemical Co., Ltd dominates ultra-high-purity grades for semiconductor encapsulation. Wacker Chemie AG anchors European supply through its integrated siloxane network in Germany.
Polydimethylsiloxane is a siloxane polymer with repeating (CH₃)₂SiO units, typically manufactured via ring-opening polymerization of octamethylcyclotetrasiloxane (D4) with acid or base catalysts, valued for its thermal stability, low surface tension, and gas permeability across industrial and medical systems. Liquid PDMS leads volume consumption in personal care and coating formulations where flow control and spreadability determine performance. Vulcanized PDMS captures premium positioning in healthcare and automotive sealing where cross-linked elastomeric properties withstand sterilization cycles and temperature extremes. Block copolymer PDMS occupies emerging niches in drug delivery matrices and soft lithography templates as microfluidic device complexity rises.
FDA enforces biocompatibility testing under ISO 10993 for PDMS used in long-term implantable devices, while EPA monitors volatile methylsiloxane emissions under TSCA Section 5 premanufacture review. EMA's MDR and REACH restrictions on cyclic siloxanes (D4/D5/D6) are redirecting formulation chemistry toward low-cyclics content grades. Stakeholders must track regulatory divergence between US and European purity thresholds to avoid dual-certification costs and supply disqualification.
Market Dynamics
Medical-grade PDMS certification requirements are compressing supplier qualification timelines while semiconductor encapsulation demand pulls ultra-high-purity volumes toward dedicated production lines. Formulators face simultaneous pressure to reduce cyclic siloxane content for REACH compliance and scale output for healthcare electronics manufacturing.
Growth Catalysts
- EU MDR traceability mandates:Implantable device manufacturers now require batch-level material genealogy, forcing PDMS suppliers to upgrade quality systems and locking in premium pricing for certified grades.
- Soft lithography expansion:Microfluidic device fabrication is consuming precision-molded PDMS membranes at accelerating rates as diagnostic platform complexity multiplies.
- China healthcare electronics manufacturing:Domestic silicone production capacity expansion is reducing import dependency for medical device OEMs operating in Shenzhen and Suzhou clusters.
Market Restraints
- D4/D5/D6 cyclics restrictions:ECHA REACH limitations on volatile methylsiloxanes are forcing reformulation investments and disqualifying legacy product lines from European medical applications.
- Chlorosilane supply concentration:Captive production of silicon metal precursors remains concentrated among integrated chemical conglomerates, limiting new entrant access to cost-competitive feedstock.
- Fluorosilicone substitution:Fuel-resistant sealing applications in automotive are migrating toward fluorinated elastomers where hydrocarbon exposure exceeds PDMS thermal stability thresholds.
Strategic Opportunities
- Drug delivery matrix expansion:Block copolymer PDMS architectures are enabling controlled-release formulations that pharmaceutical formulators are qualifying for biologic stability applications.
- India medical device PLI scheme:Production-linked incentives for domestic implantable device manufacturing are creating localized demand for biocompatible silicone supply chains.
- ISO 10993-5 cytotoxicity harmonization:Converging biocompatibility testing standards across FDA and notified body frameworks are reducing dual-certification burdens for multi-regional suppliers.
Industry Challenges
- Cleanroom molding capacity scarcity:ISO 14644 Class 7 certified elastomer processing facilities face 18-month qualification backlogs for new medical-grade production lines.
- Legacy analytical method obsolescence:Gas chromatography protocols for cyclic siloxane detection are failing to meet revised ECHA detection limits, forcing capital-intensive equipment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polydimethylsiloxane (PDMS) Market |
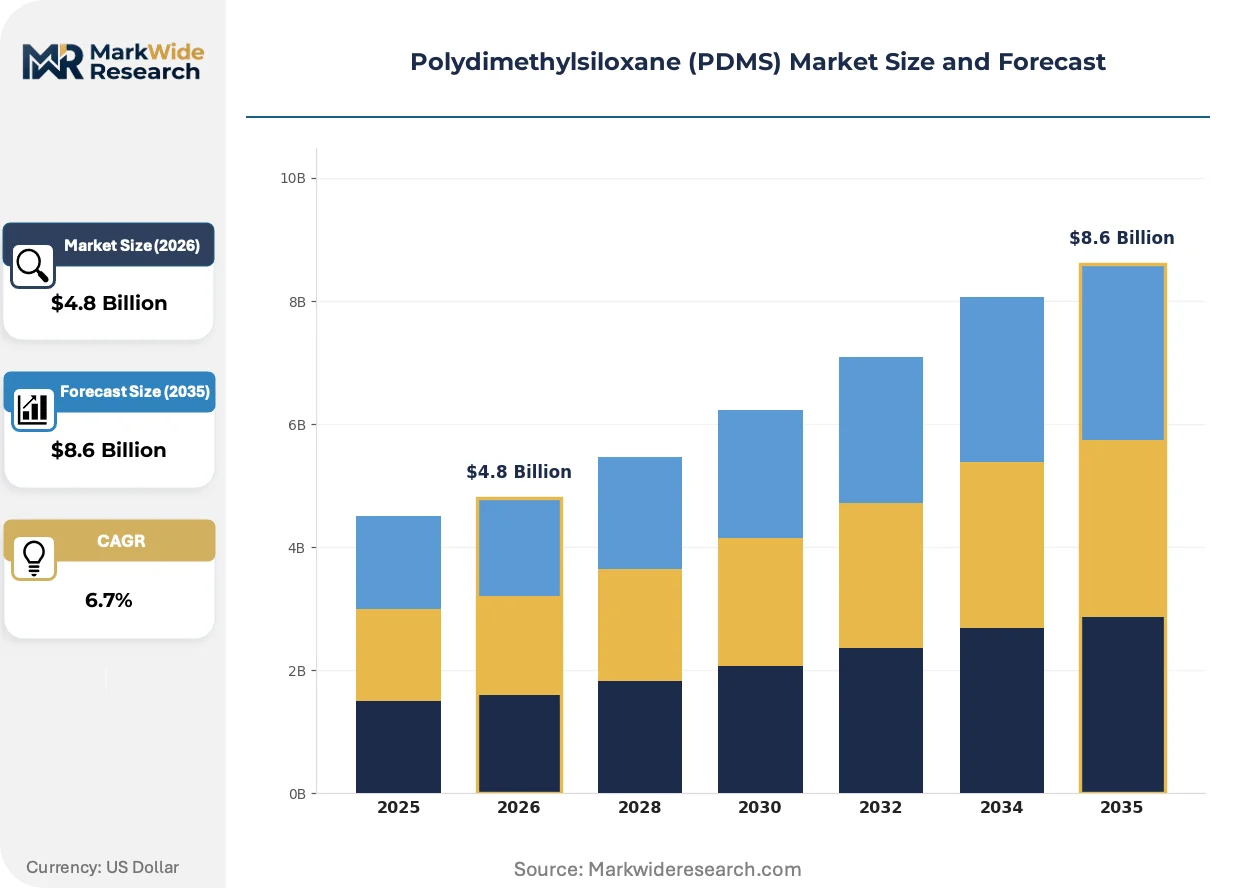
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid PDMS, High Viscosity PDMS, Vulcanized PDMS, Block Copolymer PDMS Application: Personal Care Products, Adhesives, Coatings, Sealants End User: Cosmetics, Healthcare, Automotive, Electronics Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Elkem ASA, Evonik Industries AG, Dow, Dongyue Group Limited, KCC Corporation, Shin-Etsu Chemical Co., Ltd, DuPont, Avantor, Inc., Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polydimethylsiloxane (PDMS) Market Evolving Landscape
Process intensification and regulatory chemistry convergence are redefining competitive capability requirements across PDMS value chains. Formulators must now synchronize purity upgrades with automation investments to maintain qualification status.
Plasma surface activation systems are automating permanent hydrophilic modification of PDMS microchannels for cell culture applications. Organ-on-chip manufacturers are adopting these treatments at pilot scale to eliminate manual oxygen plasma processing bottlenecks. This automation is compressing device fabrication cycle times from days to hours while improving channel-to-channel consistency.
REACH Annex XVII restrictions on D4/D5/D6 cyclics are redirecting European formulation chemistry toward low-cyclics polymerization catalysts. Medical device suppliers are qualifying these grades ahead of 2026 compliance deadlines to avoid supply discontinuity. The transition imposes 15-20% raw material cost premiums that implantable device OEMs are absorbing through supply agreements.
Consolidated procurement of silicone precursors is displacing spot-market purchasing among mid-scale formulators. Personal care compounders are negotiating multi-year chlorosilane supply contracts directly with integrated producers, bypassing traditional distributor networks. This pattern is most visible in German and French cosmetic manufacturing clusters where volume commitments secure priority allocation during feedstock tightness.
Polydimethylsiloxane (PDMS) Market Segmentation
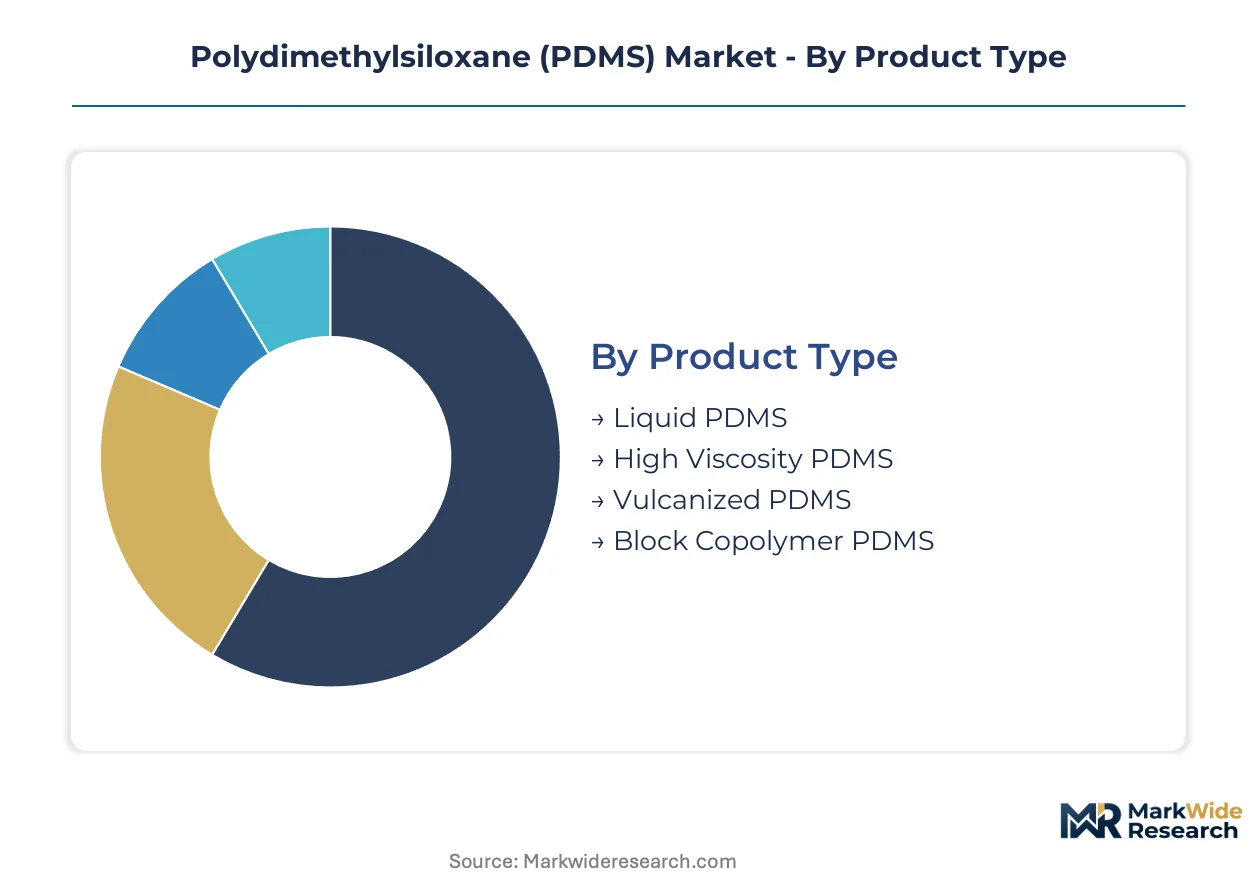
PDMS segmentation reflects divergent purity requirements and processing economics across medical, electronics, and industrial applications. Formulators select grades based on regulatory certification burden, end-use performance thresholds, and supply chain proximity to chlorosilane producers.
Product Type:
Supply concentration favors integrated producers with captive chlorosilane assets, creating tiered access to ultra-high-purity and standard industrial grades.
- Liquid PDMS:Low-viscosity siloxane fluid manufactured via ring-opening polymerization of D4, serving as the foundational feedstock for personal care emulsions and coating formulations. Personal care compounders in Germany and France negotiate direct chlorosilane contracts to secure priority allocation during feedstock tightness. Liquid grades absorb the bulk of installed capacity; block copolymer PDMS is expanding most quickly.
- Vulcanized PDMS:Cross-linked elastomer produced through platinum-catalyzed hydrosilylation or peroxide curing, delivering sterilization-resistant sealing for implantable devices and automotive gaskets. Healthcare OEMs in the United States and Switzerland require ISO 10993-5 cytotoxicity certification and batch-level genealogy under EU MDR traceability mandates.
- High Viscosity PDMS:Long-chain linear polymer with elevated molecular weight, supplying lubricant and damping fluid applications where shear stability determines performance.
- Block Copolymer PDMS:Architectures incorporating hydrophilic or biodegradable segments, enabling controlled-release matrices for biologic stability in pharmaceutical formulations.
Integrated producers with backward control over silicon metal precursors dominate high-viscosity and vulcanized grade supply.
Application:
Cost tier differentiation separates commodity coating applications from premium medical-grade formulations requiring extensive analytical documentation.
- Personal Care Products:Silicone fluids and emulsions delivering spreadability, skin feel, and water resistance in cosmetic formulations. REACH Annex XVII restrictions on D4/D5/D6 cyclics are forcing European formulators toward low-cyclics catalyst systems at 15-20% raw material cost premiums.
- Adhesives:Pressure-sensitive and structural bonding systems leveraging PDMS low surface tension and thermal stability for electronics and medical device assembly.
- Coatings:Weather-resistant and anti-fouling surface treatments where gas permeability and UV stability determine service life. Coatings absorb the bulk of installed capacity; sealants are expanding most quickly.
- Sealants:High-performance elastomeric joints for automotive and construction applications, facing substitution pressure from fluorosilicones in fuel-exposed environments.
Personal care and coatings command volume leadership; sealant applications gain share fastest as automotive electrification intensifies thermal management requirements.
End User:
Customer type segmentation reveals divergent procurement patterns between regulated medical device OEMs and price-sensitive industrial buyers.
- Healthcare:Implantable device and diagnostic platform manufacturers requiring ISO 14644 Class 7 cleanroom molding and FDA biocompatibility validation. Plasma surface activation systems are automating hydrophilic modification of PDMS microchannels for organ-on-chip applications, compressing fabrication cycles from days to hours.
- Electronics:Semiconductor encapsulation and microfluidic device producers pulling ultra-high-purity volumes toward dedicated production lines. Shin-Etsu Chemical dominates ultra-high-purity grades for this segment.
- Cosmetics:Personal care formulators consolidating chlorosilane procurement through multi-year direct contracts with integrated producers, bypassing traditional distributor networks.
- Automotive:Sealing and thermal management component suppliers migrating toward fluorinated elastomers in hydrocarbon-exposed fuel system applications.
Healthcare and electronics absorb the bulk of premium-grade capacity; healthcare is climbing the fastest as diagnostic platform complexity multiplies.
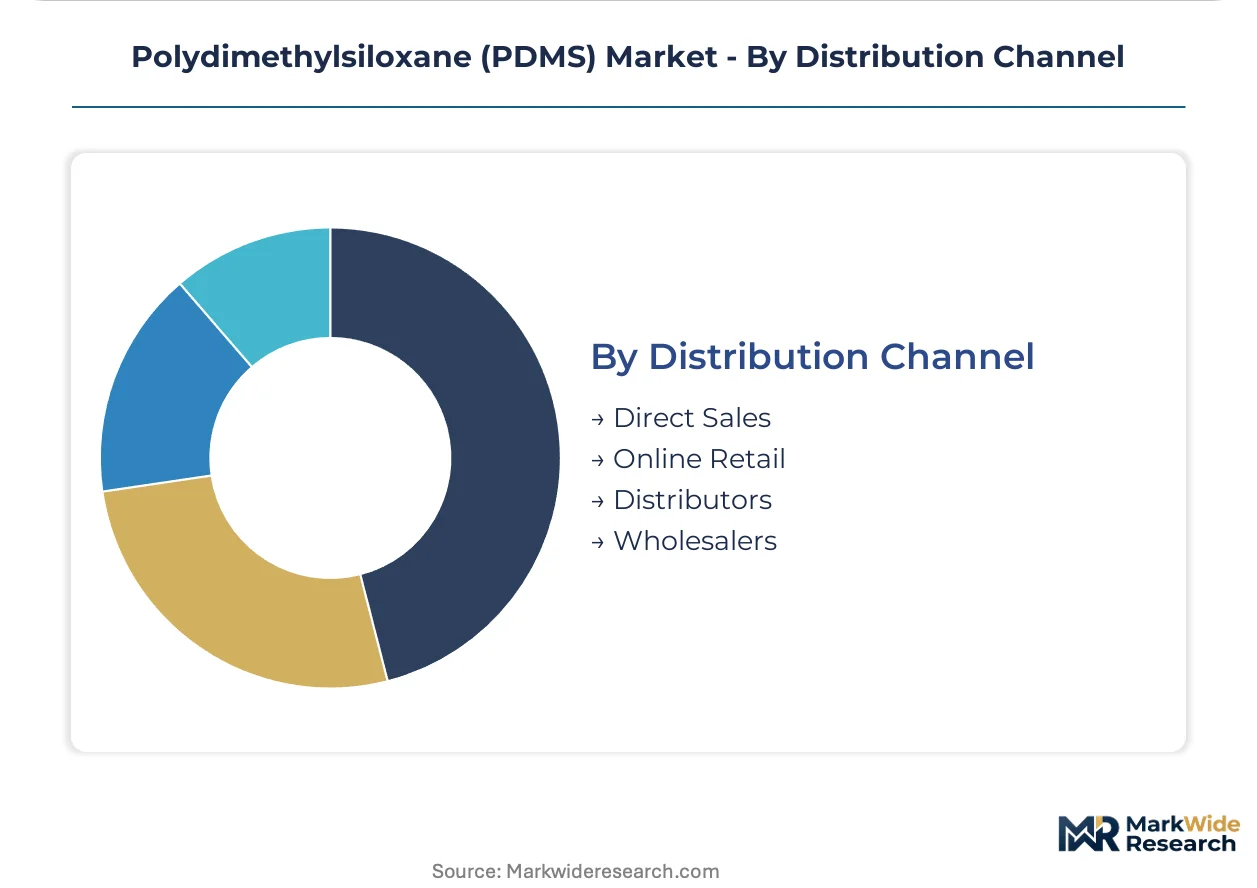
Distribution Channel:
Geography of demand concentration shapes channel selection, with clustered manufacturing hubs favoring direct procurement over fragmented wholesale networks.
- Direct Sales:Volume contracts between integrated PDMS producers and large-scale formulators in German cosmetic clusters and Shenzhen electronics manufacturing zones, securing priority allocation and customized specification.
- Distributors:Technical service intermediaries serving mid-scale compounders with formulation support and smaller lot sizes across European and North American industrial markets.
- Online Retail:E-commerce platforms supplying research-scale quantities and standardized grades to academic laboratories and startup device developers.
- Wholesalers:Bulk commodity handlers moving standard-viscosity fluids to price-sensitive industrial accounts with limited technical service requirements.
Direct sales absorb the bulk of transaction value; online retail is gaining share fastest as research-scale microfluidic prototyping expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the bulk of incremental PDMS demand as domestic silicone production capacity expansion aligns with healthcare electronics manufacturing scaling in Shenzhen and Suzhou. Medical device OEMs and semiconductor packaging facilities are absorbing volumes previously sourced from import channels.
United States
Implantable device manufacturers in Minneapolis and Boston clusters are compressing supplier qualification timelines under FDA ISO 10993 enforcement. The EPA monitors volatile methylsiloxane emissions through TSCA Section 5 premanufacture review. Healthcare OEMs require batch-level genealogy documentation as EU MDR traceability mandates extend to US-exporting facilities.
Germany
Wacker Chemie's integrated siloxane network anchors European supply for vulcanized grades serving automotive sealing applications. ECHA REACH Annex XVII restrictions on D4/D5/D6 cyclics are redirecting formulation chemistry toward low-cyclics catalyst systems. Personal care compounders in the Ruhr region negotiate multi-year chlorosilane contracts directly with integrated producers.
Japan
Shin-Etsu Chemical dominates ultra-high-purity PDMS grades for semiconductor encapsulation serving Tokyo-Osaka electronics corridors. METI industrial standards align with converging biocompatibility testing frameworks. Precision molding facilities in Nagoya face capacity constraints as microfluidic device complexity multiplies diagnostic platform demand.
Switzerland
Swissmedic certification requirements lock in premium pricing for medical-grade PDMS supplied to Basel pharmaceutical and device manufacturing clusters. Healthcare OEMs absorb 15-20% raw material cost premiums for REACH-compliant low-cyclics grades. Cleanroom molding capacity scarcity extends qualification backlogs for new production lines serving implantable applications.
India
Production-linked incentives under the PLI scheme for domestic implantable device manufacturing are creating localized demand for biocompatible silicone supply chains. CDSCO alignment with ISO 10993-5 cytotoxicity standards reduces dual-certification burdens. Maharashtra and Karnataka medical device parks are attracting formulators seeking proximity to hospital procurement networks.
Polydimethylsiloxane (PDMS) Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated producers scale chlorosilane assets to capture healthcare and electronics demand. The vendor base concentrates around chemical conglomerates with backward integration into silicon metal precursors, limiting new entrant access to cost-competitive feedstock. Three archetypes define positioning: integrated multinationals with captive precursor production, regional specialists serving pharmaceutical-grade niches, and Asian conglomerates leveraging domestic demand scale. Competitive intensity centers on cleanroom molding capacity addition and low-cyclics catalyst technology licensing.
Among integrated multinationals, Dow sustains captive chlorosilane production across North American and European sites, while Shin-Etsu Chemical Co., Ltd exemplifies ultra-high-purity specialization for semiconductor encapsulation. Wacker Chemie AG occupies a position anchoring European supply through its integrated siloxane network in Germany. These three represent the tier commanding premium positioning through regulatory certification depth and precursor control.
| Leading Market Players |
|---|
| Elkem ASA |
| Evonik Industries AG |
| Dow |
| Dongyue Group Limited |
| KCC Corporation |
| Shin-Etsu Chemical Co., Ltd |
| DuPont |
| Avantor, Inc. |
| Wacker Chemie AG |
| Others |
Value Network & Pricing Analysis
Cleanroom molding technician concentration in Swiss and German medical device clusters widens pricing-tier spreads, as labor-cost differentials between ISO 14644 Class 7 certified facilities and standard industrial compounders separate premium medical-grade PDMS from commodity fluid grades.
Pricing Analysis
Warranty and batch-level genealogy documentation are bundled into premium medical-grade contracts while standard industrial fluids sell unbundled. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant low-cyclics grades from legacy formulations and commodity spot purchases. Price differentiation hinges on certification depth and after-sales technical support intensity. Cost compression in standard industrial tiers is intensifying because Chinese domestic capacity expansion feeds oversupply into spot markets. Personal care compounders in European cosmetic clusters exhibit highest price sensitivity; implantable device OEMs in Swiss and US healthcare corridors absorb premiums with limited negotiation leverage.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive sealant manufacturers and Shenzhen healthcare electronics clusters, while distributor networks serve mid-scale compounders requiring technical formulation support. Geographic supply concentration centers on Germany, Japan, and China, with Wacker Chemie, Shin-Etsu Chemical, and Dongyue Group commanding chlorosilane precursor control. Raw material dependencies rest on silicon metal, methyl chloride, and platinum catalyst feedstocks. Single-source vulnerability from captive chlorosilane production among integrated chemical conglomerates limits new entrant access to cost-competitive supply. Distribution runs through multi-year direct contracts consolidating procurement away from spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into silicon metal and chlorosilane precursors defines competitive positioning as players race to secure feedstock autonomy and lock in medical-grade certification depth.
For Market Incumbents: To counter fluorosilicone substitution in automotive fuel-system sealing, Dow and Wacker Chemie should deepen captive chlorosilane production across North American and European sites while accelerating low-cyclics catalyst licensing to European formulators facing REACH Annex XVII deadlines. Capacity addition in Swiss cleanroom molding facilities represents the priority lever to capture implantable device OEM demand. For New Entrants and Emerging Players: E-commerce platforms supplying research-scale quantities to academic microfluidic laboratories offer the most penetrable entry vector, bypassing entrenched distributor relationships and multi-year qualification barriers that protect integrated incumbents. Target online retail channels serving organ-on-chip prototyping demand in Boston and Tokyo innovation corridors, then ladder into pilot-scale supply agreements with diagnostic platform developers. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists possessing ISO 10993-5 cytotoxicity certification and existing cleanroom molding capacity given accelerating healthcare electronics demand and qualification backlog scarcity. Long-term viability over the five-to-ten year window favors acquisition targets with demonstrated regulatory navigation across FDA and EMA frameworks. Watch for CDSCO alignment completion in India as the signal indicating PLI scheme momentum and localized supply chain buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Precursors | Captive silicon metal supply secures cost position and medical-grade certification priority allocation. |
| Low-Cyclics Catalyst Technology Licensing | REACH Annex XVII compliance enables continued European medical device market access ahead of deadlines. |
| Cleanroom Molding Capacity Expansion | ISO 14644 Class 7 certification captures implantable device OEM demand facing eighteen-month qualification backlogs. |
| Direct Procurement Contract Consolidation | Multi-year volume agreements with German cosmetic and Shenzhen electronics clusters displace distributor intermediaries. |
| Plasma Surface Activation Automation | Permanent hydrophilic modification systems compress organ-on-chip fabrication cycles from days to hours. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with PDMS plant managers, procurement leads at medical device OEMs, technical R&D directors at silicone formulators, and distribution channel partners across European and North American markets. Secondary sources included ECHA REACH restriction documentation, FDA 510(k) submissions for silicone-containing devices, SEC 10-K disclosures from integrated chemical producers, and Cefic silicone industry reports. Bottom-up volume modeling triangulated against top-down value estimates derived from chlorosilane trade flow analysis.
Production volume and value outputs were reconciled across shipment data, capacity utilization disclosures, and end-use consumption surveys throughout the projection horizon. Segmentation dimensions modeled encompassed grade tier, end-use industry, and regional production hub. CAGRs were derived from regression analysis of historical chlorosilane consumption patterns and forward projections of healthcare electronics manufacturing scaling. Forecast inputs incorporated REACH Annex XVII compliance timeline assumptions and FDA biocompatibility enforcement intensity.
The model holds under stable regulatory enforcement timelines and continued chlorosilane feedstock availability; deviation in ECHA restriction scope or silicon metal supply disruptions would shift trajectory. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Rubber Membrane Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Hot Cast Elastomers Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market