
 Silicone Elastomers Market | 2026-2036
Silicone Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Elastomers Market Analysis
Specialized polymer compounding expertise is bifurcating the competitive landscape into integrated material science houses and regional formulation specialists. Dow Inc. leverages captive silicone monomer production to sustain cost leadership across liquid and solid elastomer grades. Wacker Chemie AG anchors European supply through its Burghausen manufacturing complex, while Shin-Etsu Chemical Co., Ltd. dominates Asian electronics-grade silicone with proprietary high-purity refining protocols.
Silicone elastomers are cross-linked polydimethylsiloxane polymers cured via platinum-catalyzed hydrosilylation or peroxide initiation, delivering thermal stability from -60°C to 230°C alongside dielectric strength exceeding 20 kV/mm. Liquid silicone rubber leads medical device and automotive sealing applications due to injection molding efficiency and biocompatibility certification pathways. Solid silicone competes in industrial gasket and construction membrane segments where compression set resistance and weatherability command premium pricing over organic elastomers.
FDA 21 CFR Part 177.2600, EU MDR, and REACH shape material qualification timelines and restrict certain platinum catalyst residues in implantable grades. Healthcare and automotive end users now require batch-level traceability documentation that extends from raw siloxane through finished component. Stakeholders must monitor evolving perfluorinated substance restrictions under ECHA proposals and assess captive silicone recycling capabilities before committing capacity expansion decisions.
Market Dynamics
Medical-grade silicone elastomer qualification timelines now extend 18-24 months as FDA and EU MDR impose batch-level traceability mandates from raw siloxane monomer through finished implantable component.
Growth Catalysts
- Automotive electrification:Battery pack sealing and thermal management systems in Germany, China, and the United States are consuming liquid silicone rubber for flame-retardant gaskets and conformal coatings.
- EU MDR implantable device mandates:Class III medical device manufacturers must source platinum-catalyzed grades with sub-10 ppm catalyst residue limits, locking in premium silicone elastomer procurement.
- High-purity electronics refining:Shin-Etsu Chemical's proprietary protocols for semiconductor-grade silicone are enabling advanced packaging applications in Asian electronics manufacturing clusters.
Market Restraints
- Methyl chloride and silicon metal volatility:Feedstock price swings for silicone monomer production compress margin predictability for non-integrated compounders.
- Burghausen supply concentration:Wacker Chemie anchors European silicone elastomer supply through its Bavarian manufacturing complex, creating geographic single-point vulnerability.
- Thermoplastic elastomer substitution:TPEs displace solid silicone in industrial gasket applications where compression set resistance requirements fall below 25% threshold.
Strategic Opportunities
- Indian medical device manufacturing:CDSCO regulatory harmonization with ISO 13485 is attracting contract manufacturers seeking lower-cost silicone elastomer conversion for export markets.
- Silicone recycling infrastructure:Pyrolysis-based siloxane recovery from post-industrial scrap enables circular material flows for non-implantable grades.
- MEE dual carbon compliance:China's Ministry of Ecology and Environment emissions mandates are accelerating demand for solventless liquid silicone rubber processing technologies.
Industry Challenges
- Platinum catalyst chemist scarcity:Formulation expertise for hydrosilylation-cured medical grades concentrates among retiring technical specialists in European and Japanese compounding houses.
- Cleanroom molding capex:ISO 14644 Class 7 injection molding cell qualification requires capital outlays exceeding standard industrial silicone processing by 3-4x.
- FDA 510(k) pathway compression:Predicate device substantiation for new silicone elastomer formulations faces heightened scrutiny, extending regulatory submission cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Elastomers Market |
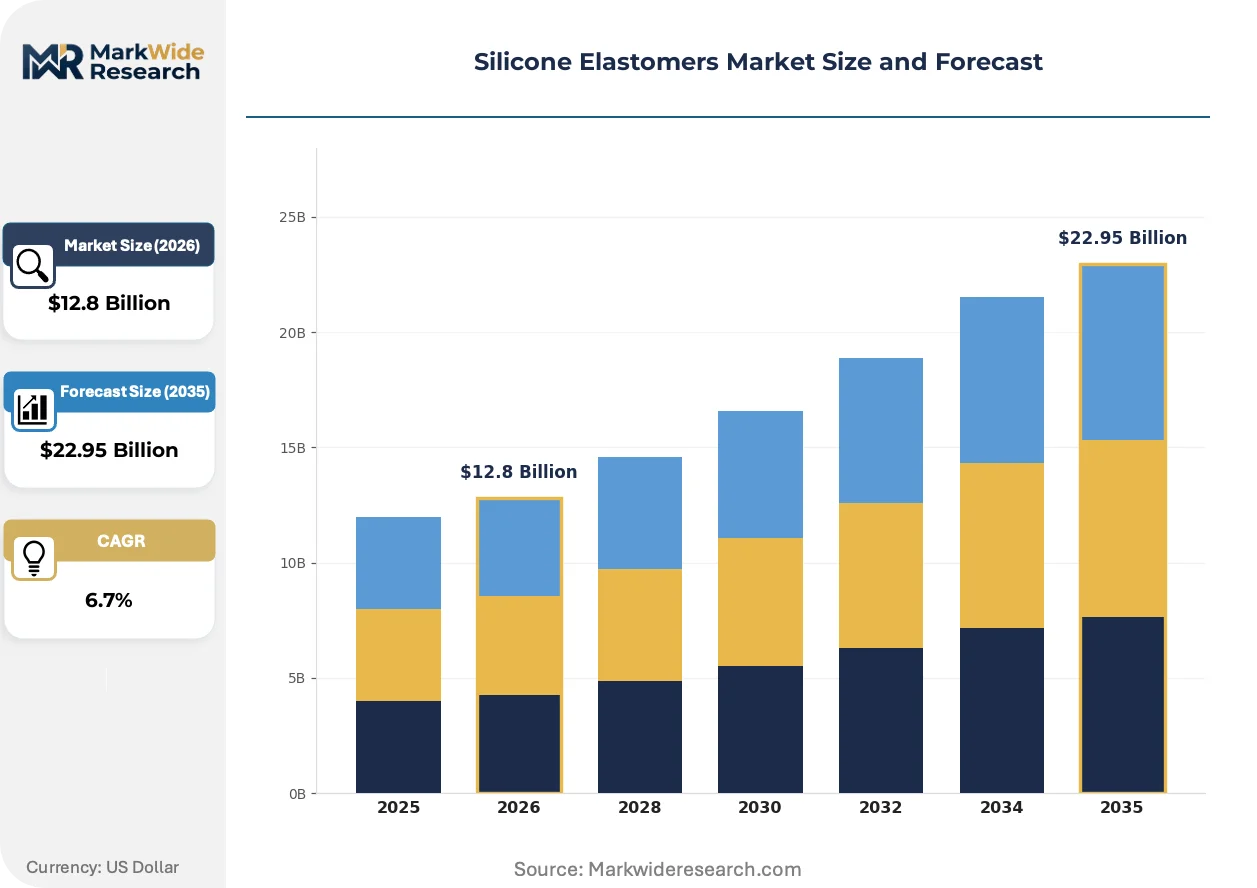
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Silicone, Solid Silicone, Foam Silicone, Gel Silicone Application: Automotive Seals, Medical Devices, Consumer Goods, Electronics Form: Extruded, Molded, Compression Molding, 3D Printed End User: Aerospace, Healthcare, Construction, Industrial |
| Companies Covered | Dow Inc., Wacker Chemie AG, Momentive Performance Materials Inc., Shin-Etsu Chemical Co., Ltd., China National Bluestar (Group) Co., Ltd., Elkem ASA, KCC Corporation, DuPont de Nemours, Inc., Reiss Manufacturing Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Elastomers Market Emerging Trajectories
Silicone elastomer technology trajectories center on purity escalation for implantable applications, regulatory-driven traceability architecture, and molding efficiency gains that compress per-part economics for high-volume automotive and healthcare conversion.
Self-healing silicone elastomers incorporating dynamic covalent bond chemistry are miniaturizing wearable device form factors by eliminating mechanical fasteners and enabling stretchable circuit integration. Medtronic and Philips Healthcare procurement teams are qualifying these grades for continuous glucose monitor housings and cardiac patch electrodes. The technology is compressing device thickness below 2mm while maintaining IP67 sealing performance.
REACH perfluorinated substance restrictions under ECHA consultation are forcing reformulation of fluorosilicone grades used in aerospace fuel sealing and semiconductor fabrication equipment. Compounders must validate alternative fluorine-free chemistries for -40°C cold flexibility without sacrificing hydrocarbon resistance. German automotive suppliers face the most acute timeline pressure given 2026 restriction implementation windows.
Healthcare OEMs now mandate lot-level siloxane chain length distribution certificates from silicone elastomer suppliers, replacing annual material master file updates with per-shipment analytical data packages. This documentation burden is consolidating qualified supplier bases toward integrated producers with captive analytical laboratories. The shift is most pronounced in Minnesota and Massachusetts medical device manufacturing corridors where FDA inspection intensity has intensified post-MDR transition.
Silicone Elastomers Market Segmentation
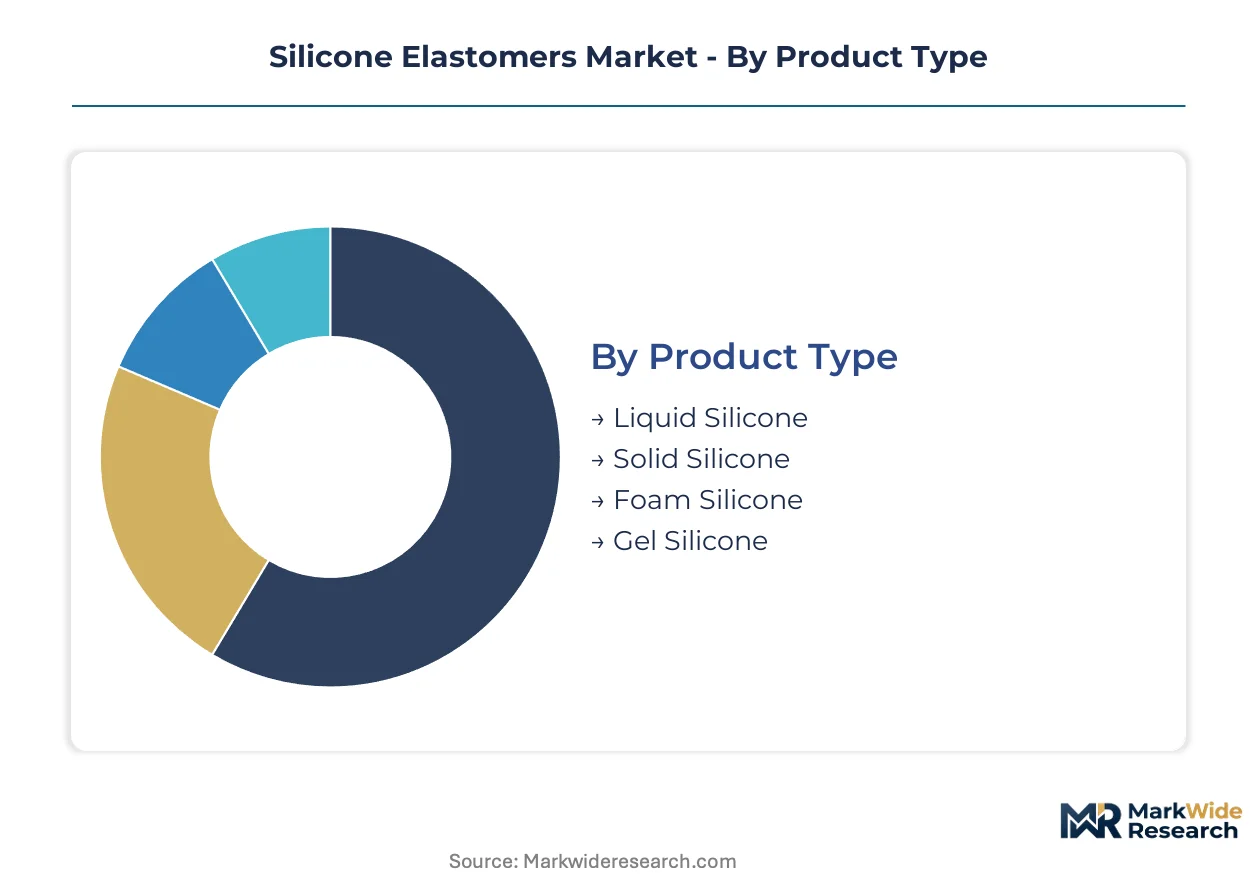
Silicone elastomer procurement decisions hinge on curing chemistry, part geometry complexity, and regulatory certification pathways. Manufacturers segment supply strategies across product families, application verticals, and conversion technologies to align material properties with end-use performance mandates.
Product Type:
Thermoplastic elastomer substitution pressure concentrates in solid silicone grades where compression set thresholds permit lower-cost alternatives, while liquid and gel formulations defend position through biocompatibility lock-in.
- Liquid Silicone:Platinum-catalyzed two-part systems with viscosity below 500,000 cP enable micro-molding precision for Class III implantable components. Demand concentrates in Minnesota and Massachusetts medical device corridors where FDA 510(k) predicate substantiation requires locked material master files.
- Solid Silicone:Peroxide-cured high-consistency rubber delivers compression set resistance below 15% for industrial gasket applications. Thermoplastic elastomers from Kraiburg and Kraton displace solid silicone in automotive weatherstripping where specifications permit 25% compression set thresholds.
- Foam Silicone:Cellular structures with density gradients from 200-500 kg/m³ provide thermal and acoustic insulation for battery pack enclosures.
- Gel Silicone:Ultra-soft formulations below 00-30 Shore hardness cushion prosthetic interfaces and wearable device skin contact surfaces.
Liquid silicone retains volume leadership in healthcare procurement; gel silicone holds the steepest expansion curve as continuous glucose monitor and cardiac patch form factors miniaturize.
Application:
Cost tier stratification separates implantable medical grades commanding platinum-catalyzed premiums from automotive sealing volumes competing on per-part economics.
- Automotive Seals:Flame-retardant liquid silicone rubber gaskets for battery thermal management systems require UL 94 V-0 certification. Procurement concentrates in Germany and China where MEE dual carbon compliance accelerates solventless processing adoption.
- Medical Devices:Implantable grades demand sub-10 ppm platinum catalyst residue documentation per EU MDR Class III mandates. Wacker Chemie's Burghausen complex anchors European supply for pacemaker lead insulation and intraocular lens haptics.
- Consumer Goods:Food-contact formulations under FDA 21 CFR Part 177.2600 seal baby bottle nipples and kitchenware.
- Electronics:Semiconductor-grade high-purity silicones enable advanced packaging substrates in Asian manufacturing clusters.
Automotive seals dominate tonnage consumption; medical devices capture the widest margin spreads.
Form:
Processing technology selection pivots on part complexity, volume scale, and cleanroom requirements that multiply capital intensity across conversion methods.
- Extruded:Continuous profile production for tubing and cord stock achieves lowest per-meter economics at scale. Demand concentrates in industrial hose and medical catheter applications where tight dimensional tolerances require vacuum-calibrated die systems.
- Molded:Liquid injection molding delivers cycle times under 30 seconds for high-volume automotive and healthcare components. Shin-Etsu's proprietary high-purity refining protocols enable electronics-grade molded parts with ionic contamination below 10 ppm.
- Compression Molding:Solid silicone preform placement suits low-volume industrial gaskets and aerospace seals where tooling amortization spans extended production runs.
- 3D Printed:Direct ink writing of photocurable silicone enables patient-specific prosthetic geometries and rapid medical device prototyping without hard tooling investment.
Molded forms command the largest installed equipment base; 3D printed formats are climbing the fastest as digital manufacturing penetrates medical device development cycles.
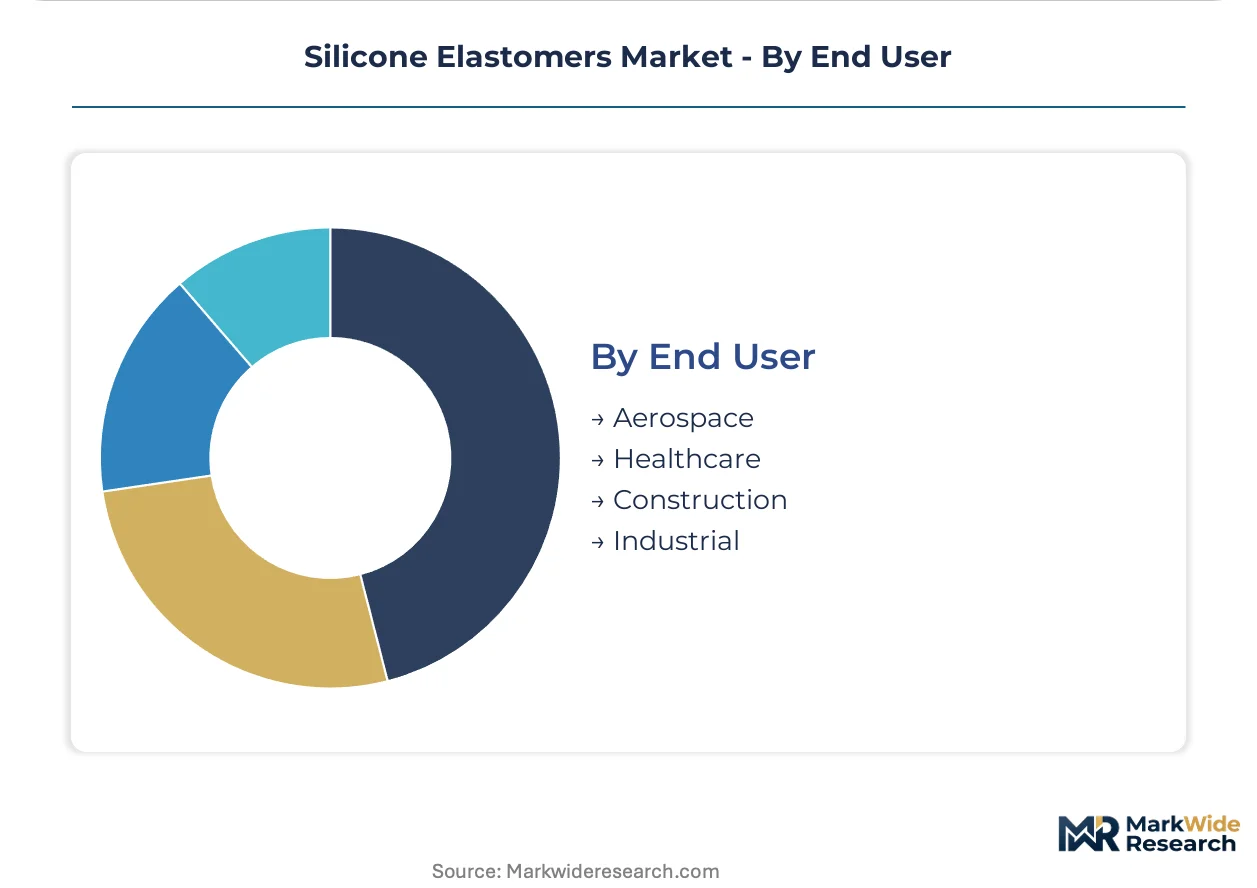
End User:
Customer type determines certification burden intensity, with healthcare and aerospace imposing batch-level traceability that regional compounders cannot support.
- Aerospace:Fluorosilicone grades for fuel system sealing face REACH perfluorinated substance restriction deadlines under ECHA consultation. German suppliers confront acute reformulation pressure for -40°C cold flexibility without hydrocarbon resistance degradation.
- Healthcare:CDSCO regulatory harmonization with ISO 13485 attracts contract manufacturers to Indian conversion facilities for export market supply. FDA and EU MDR lot-level siloxane chain length documentation now replaces annual material master file updates.
- Construction:Weather-resistant membrane applications compete with EPDM and TPO on installed cost for roofing and facade systems.
- Industrial:Gasket and hose applications tolerate broader material substitution where compression set and chemical resistance specifications permit organic elastomer alternatives.
Healthcare end users drive premium grade development; industrial consumption absorbs the highest substitution elasticity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA biocompatibility standards and EU MDR traceability mandates anchor procurement patterns in the United States and Germany, while China's MEE dual carbon compliance accelerates solventless processing adoption across Asian manufacturing clusters.
United States
Minnesota and Massachusetts medical device corridors concentrate demand for platinum-catalyzed liquid silicone rubber with sub-10 ppm catalyst residue documentation. FDA 510(k) pathway compression extends qualification timelines to 18-24 months for implantable grades. Boston-area cleanroom molding facilities absorb capital outlays three to four times standard industrial silicone processing costs.
Germany
Bavaria's Burghausen manufacturing complex anchors European supply for automotive battery sealing and pacemaker lead insulation applications. ECHA perfluorinated substance restrictions force fluorosilicone reformulation for aerospace fuel system sealing by 2026. Stuttgart automotive suppliers accelerate solventless liquid silicone rubber adoption to meet MEE-equivalent emissions benchmarks.
China
Yangtze River Delta electronics manufacturers consume semiconductor-grade high-purity silicones for advanced packaging substrates. Ministry of Ecology and Environment dual carbon mandates push conversion toward solventless processing technologies. Shenzhen battery pack producers source flame-retardant liquid silicone rubber gaskets for thermal management systems.
India
Maharashtra and Gujarat contract manufacturers expand silicone elastomer conversion capacity for export market supply. CDSCO regulatory harmonization with ISO 13485 attracts medical device OEMs seeking lower-cost procurement alternatives. Mumbai-Pune corridor facilities target European and North American healthcare end users with batch-level traceability documentation.
Japan
Kanto region electronics-grade silicone refining dominates Asian semiconductor fabrication equipment sealing applications. METI industrial standards shape high-purity siloxane chain length distribution certification requirements. Shin-Etsu Chemical's proprietary protocols enable ionic contamination levels below 10 ppm for advanced packaging substrates.
Silicone Elastomers Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding captive silicone monomer production and the lower tier competing on regional formulation expertise. The market structure bifurcates between material science houses with backward integration into siloxane feedstocks and regional compounders serving industrial gasket segments. Two dominant archetypes emerge: integrated producers leveraging cost leadership across liquid and solid elastomer grades, and high-purity specialists defending position through proprietary refining protocols. Competitive moves concentrate on capacity expansion in medical-grade cleanroom facilities and technology licensing for solventless processing systems.
Within the integrated tier, Dow Inc. and Wacker Chemie AG exemplify archetypes of captive monomer production and regional supply anchoring respectively. Shin-Etsu Chemical Co., Ltd. occupies a position representing high-purity electronics-grade specialization. These three entities collectively illustrate the competitive spectrum from cost-driven liquid and solid elastomer coverage to proprietary semiconductor-grade refining capabilities.
| Leading Market Players |
|---|
| Dow Inc. |
| Wacker Chemie AG |
| Momentive Performance Materials Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| China National Bluestar (Group) Co., Ltd. |
| Elkem ASA |
| KCC Corporation |
| DuPont de Nemours, Inc. |
| Reiss Manufacturing Inc. |
| Others |
Supply Flow & Price Mechanics
Eighteen-month medical-grade qualification timelines compress inventory turns and amplify pricing power for integrated producers with captive siloxane supply. The interdependence between platinum catalyst traceability mandates and batch-level documentation burdens concentrates procurement decisions toward backward-integrated compounders who can absorb compliance costs without margin erosion.
Pricing Analysis
Geographic price spreads of 15-25 percent separate German medical-grade liquid silicone from Indian contract-manufactured equivalents, reflecting EU MDR certification premiums against CDSCO-harmonized cost structures. Three-tier pricing structure across implantable, industrial, and consumer grades anchors differentiation on FDA 21 CFR Part 177.2600 compliance status and platinum catalyst residue thresholds. Cost compression in automotive sealing tiers intensifies as thermoplastic elastomers from Kraiburg and Kraton displace solid silicone in weatherstripping applications. Industrial gasket buyers exhibit highest price sensitivity, while Class III implantable device manufacturers lock in long-term offtake agreements with minimal volume elasticity.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp chemical corridors and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for non-integrated compounders sourcing siloxane monomer. Supply concentrates in Germany, China, and Japan, with Wacker Chemie's Burghausen complex, China National Bluestar's Zhangjiagang facilities, and Shin-Etsu's Niigata refineries anchoring regional availability. Methyl chloride and silicon metal feedstock volatility rests on energy-intensive carbothermal reduction processes concentrated in southwestern China and Norwegian hydroelectric smelters. Single-source vulnerability around Burghausen creates European geographic concentration risk. Distribution runs through authorized distributor networks for medical grades and direct mill relationships for automotive volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise for hydrosilylation-cured medical grades concentrates among retiring technical specialists in European and Japanese compounding houses, creating a capability scarcity that reshapes competitive mobility. This talent gap limits new entrant qualification success rates and extends incumbent pricing power in implantable segments.
For Market Incumbents: Fortify backward integration into siloxane monomer production to sustain cost leadership against regional formulation specialists. Expand cleanroom molding capacity in Minnesota and Massachusetts corridors to capture FDA 510(k) pathway compression premiums. Lock in long-term platinum catalyst supply agreements before chemist scarcity intensifies formulation bottlenecks. For New Entrants and Emerging Players: Rapid silicone prototyping services for medical device development cycles represent a service-layer gap where incumbents under-serve. Target Indian contract manufacturing clusters seeking ISO 13485 certification for export market supply. Deploy direct ink writing capabilities to bypass hard tooling investments that block incumbent response times. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with under-optimized silicone elastomer divisions lacking medical-grade certification infrastructure. Five-to-ten-year viability hinges on CDSCO regulatory harmonization completion and MEE dual carbon compliance technology licensing potential. Watch for FDA inspection intensity escalation in Minnesota and Massachusetts as inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomer | Dow Inc.'s captive production sustains cost leadership across liquid and solid elastomer grades. |
| Cleanroom Molding Capacity Expansion | ISO 14644 Class 7 qualification captures FDA 510(k) pathway compression premiums in implantable segments. |
| Platinum Catalyst Supply Security | Long-term offtake agreements hedge against formulation chemist scarcity in European compounding houses. |
| Solventless Processing Technology Licensing | MEE dual carbon compliance accelerates demand for emissions-reduced liquid silicone rubber conversion systems. |
| Silicone Recycling Infrastructure Development | Pyrolysis-based siloxane recovery enables circular material flows for non-implantable industrial grades. |
Methodological Framework
Cross-validation between primary interviews with medical device procurement managers, automotive Tier 1 supplier technical directors, and silicone compounding house R&D leads anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, and SEC 10-K disclosures from integrated producers. Customs and trade data from Germany, China, and the United States triangulate volume flows with bottom-up facility capacity assessments and top-down end-use consumption models.
Sensitivity analysis around platinum catalyst price volatility, methyl chloride feedstock cost swings, and regulatory timeline compression shapes the analytical framework across the projection horizon. Segmentation dimensions include curing chemistry, application vertical, processing technology, and geographic regulatory cluster. CAGRs derive from elasticity-adjusted demand curves for automotive electrification and healthcare infrastructure investments, with semiconductor-grade purity escalation and implantable biocompatibility certification as industry-specific forecast inputs.
Material uncertainties — ECHA perfluorinated substance restriction implementation scope, CDSCO harmonization completion timelines, and MEE enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and feedstock cost normalization that sustained deviation would revise. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Medical Styrenic Block Copolymer (SBC) Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Cold Cast Elastomers Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Elastomeric Membrane Market