
 Middle-East and Africa (EMEA) Elastomers Market | 2026-2036
Middle-East and Africa (EMEA) Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa (EMEA) Elastomers Market Foresight
Maintenance contracts for predictive seal replacement in oilfield infrastructure is realigning how elastomer value gets captured in EMEA. BASF SE leverages its Ludwigshafen technical center to transfer compounding expertise into Saudi downstream facilities. Lanxess AG anchors its regional position through captive butyl rubber supply to Gulf tire manufacturers. Dow Chemical Company specializes in silicone formulations serving Egypt's expanding medical device assembly sector.
Elastomers are polymeric materials exhibiting reversible elastic deformation under stress, typically comprising cross-linked polymer chains with glass transition temperatures below room temperature and elongation-at-break values exceeding 100 percent; they function primarily as seals, gaskets, vibration dampers, and flexible barriers across industrial and consumer systems. Thermosets retain dominant volume share in EMEA automotive underhood applications where heat resistance and compression set performance command premium positioning. Liquid Silicone Rubber represents the fastest-expanding product category, driven by Gulf medical device manufacturers seeking biocompatible molding compounds for surgical instrument components and respiratory seals. Polyurethane elastomers occupy a mature but profitable niche in industrial equipment rollers and mining conveyor belting across South African and Moroccan operations.
REACH-equivalent chemical registration frameworks under development in Gulf Cooperation Council jurisdictions are elevating compliance costs for non-certified compound imports while creating preference for locally tested formulations. South Africa's National Regulator for Compulsory Specifications enforces SABS-approved elastomer grades in mining safety equipment, directly shaping procurement specifications for domestic suppliers and importers. EMEA stakeholders must monitor divergence between EU REACH alignment timelines in the Gulf and South Africa's SABS-centric approach, as regulatory fragmentation will determine which compounders can serve both sub-regions without dual certification burdens.
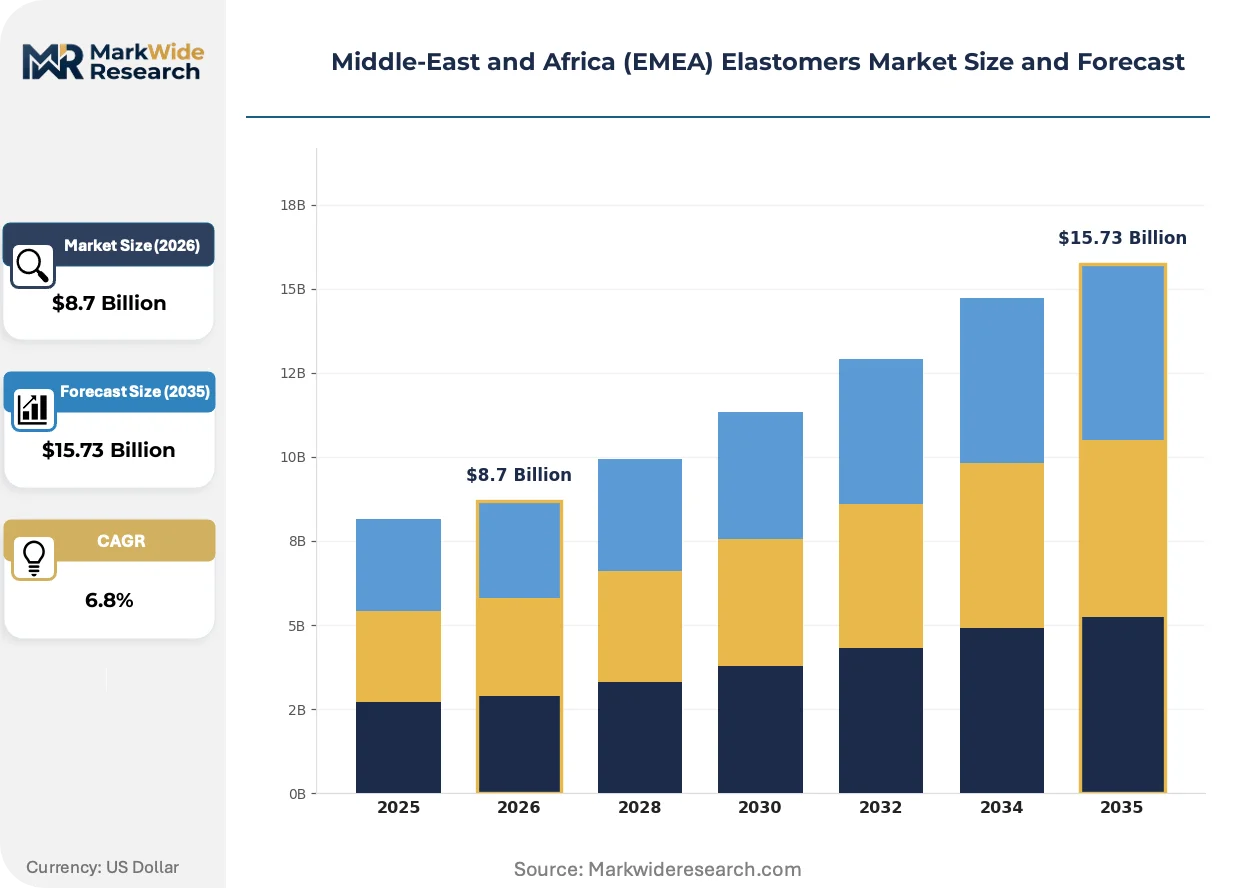
Market Dynamics
REACH-equivalent frameworks under development across Gulf Cooperation Council states are tightening material certification requirements and forcing compounders to relocate testing capabilities or surrender market access.
Growth Catalysts
- Automotive OEM localization:Saudi Arabia's industrial cities are attracting seal and gasket manufacturing as petrochemical downstream integration enables localized compounding operations with reduced import dependency.
- Biocompatible molding demand:Gulf medical device manufacturers are expanding surgical instrument and respiratory seal production using liquid silicone rubber compounds that meet stringent healthcare standards.
- SABS enforcement in mining:South Africa's National Regulator for Compulsory Specifications mandates approved elastomer grades in safety equipment, creating captive demand for certified domestic suppliers.
Market Restraints
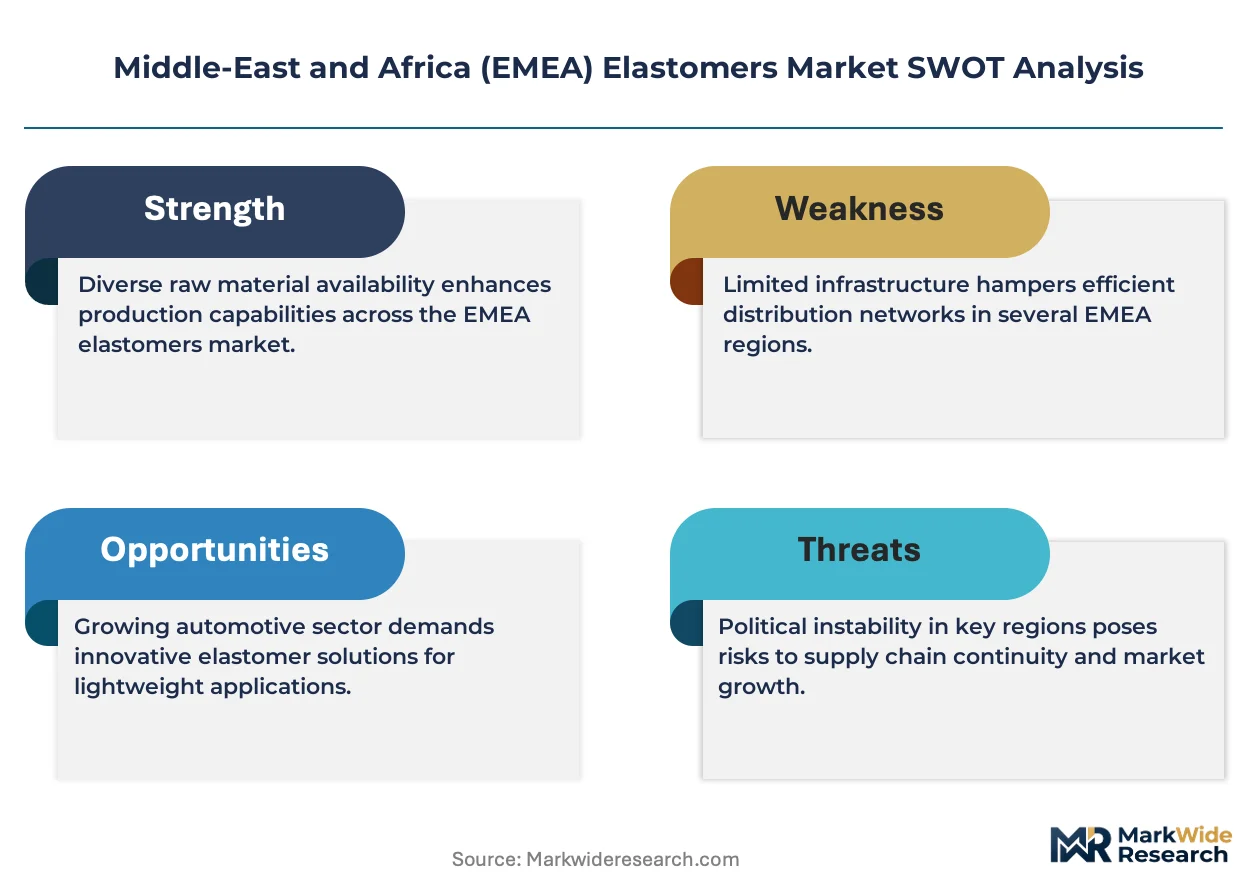
- Feedstock volatility:Crude oil price swings directly compress margins for synthetic rubber producers dependent on naphtha and butadiene derivatives.
- Import concentration:Specialty silicone formulations remain concentrated in European and Asian supply bases, exposing buyers to currency and logistics risk.
- Technical substitution:Thermoplastic elastomers are encroaching on traditional vulcanized rubber applications in automotive interior components where heat resistance requirements have softened.
Strategic Opportunities
- Egypt medical device expansion:Cairo's emerging surgical instrument cluster lacks qualified local silicone compounders, creating first-mover advantage for technical entrants.
- Digital predictive maintenance:Oilfield operators are unbundling seal replacement from bundled service contracts, enabling compounders to capture recurring revenue through condition monitoring partnerships.
- REACH-GCC convergence:Early alignment with Gulf chemical registration frameworks positions suppliers to serve both European and regional markets without dual certification.
Industry Challenges
- Compounding chemist scarcity:Formulation expertise for high-performance fluoroelastomers and perfluoroelastomers concentrates in European technical centers, constraining Gulf knowledge transfer.
- Testing infrastructure gaps:Accelerated aging and compression set validation facilities remain underdeveloped outside South Africa and the UAE, extending product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa (EMEA) Elastomers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Thermosets, Liquid Silicone Rubber, Polyurethane Application: Automotive Components, Consumer Goods, Medical Devices, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores |
| Companies Covered | BASF SE, DuPont, ARLANXEO, Trinseo SA, Synthos SA, Lanxess AG, Dow Chemical Company, SABIC, ExxonMobil Chemical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa (EMEA) Elastomers Market Shifts & Advancements
Digital process control and regulatory harmonization are compressing development cycles while redirecting value capture toward predictive service models and certified local production.
Closed-loop injection molding with integrated cavity pressure monitoring is automating quality assurance in liquid silicone rubber processing for medical device components. Gulf manufacturers are adopting these systems to reduce scrap rates and accelerate FDA and SFDA submission timelines. The technology is automating defect detection that previously required manual inspection, compressing labor costs and enabling lights-out production shifts.
REACH-equivalent chemical registration frameworks under development in Gulf Cooperation Council jurisdictions are elevating compliance costs for non-certified compound imports. Industrial consequence includes preference shifts toward locally tested formulations that bypass European certification backlogs. Medical device and automotive seal segments are responding by qualifying Saudi and UAE-based compounders ahead of formal mandate deadlines.
Maintenance contracts for predictive seal replacement in oilfield infrastructure are realigning how elastomer value gets captured across the value chain. Integrated service providers are disintermediating traditional distributors by combining compound supply with installation and monitoring. This pattern is most visible in Saudi Arabia's onshore production facilities where Aramco's supplier consolidation programs favor full-service partnerships over component-only vendors.
Middle-East and Africa (EMEA) Elastomers Market Segmentation
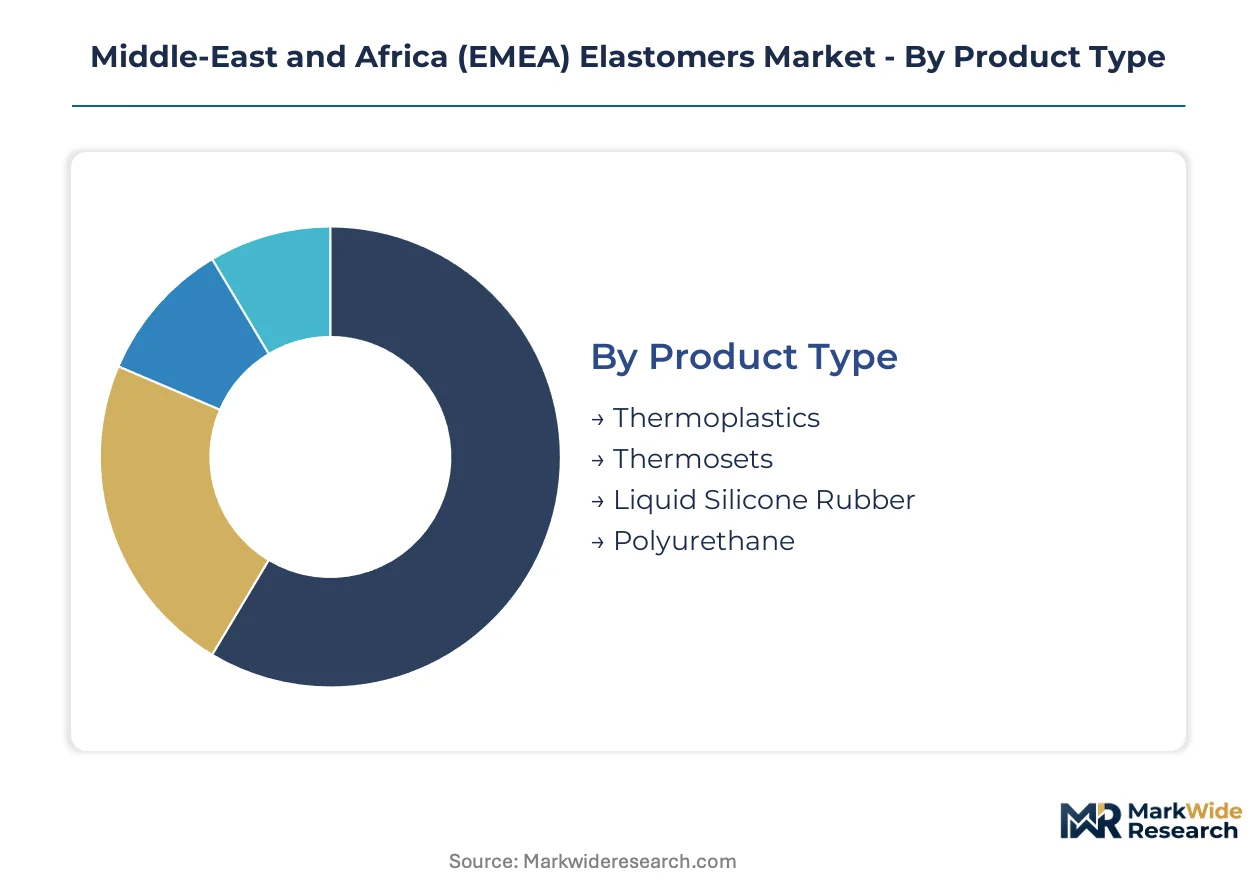
Segmentation in the EMEA elastomers market reveals how capital deployment, regulatory exposure, and supply chain proximity fragment procurement behavior across material grades and customer tiers. Understanding these divisions exposes where compounders can defend margin through technical differentiation versus where volume scale dominates.
Product Type:
Thermosets demand the heaviest upfront investment in curing infrastructure and compression molding presses, while liquid silicone rubber processing requires cleanroom-grade facilities that concentrate capacity in Gulf industrial zones.
- Thermoplastics:These materials process without vulcanization, enabling rapid cycle times and recyclability that appeals to automotive interior manufacturers seeking cost containment. Demand clusters in Moroccan and Egyptian injection molding operations serving European automotive Tier-1 suppliers facing sustainability mandates.
- Thermosets:Cross-linked polymer networks deliver superior heat resistance and compression set performance essential for underhood seals and gaskets. Saudi Arabia's industrial cities host the bulk of regional compounding capacity due to feedstock integration with SABIC's petrochemical complexes.
- Liquid Silicone Rubber:Two-part platinum-cured systems serve Gulf medical device manufacturers requiring biocompatible respiratory seals and surgical instrument components.
- Polyurethane:Castable and thermoplastic variants dominate mining conveyor belting and industrial rollers across South African and Moroccan operations.
Thermosets absorb the bulk of installed capacity; Liquid Silicone Rubber is expanding most quickly.
Application:
Application segmentation tracks how performance requirements and certification burdens concentrate value in medical and automotive tiers versus commoditized consumer segments.
- Automotive Components:Underhood seals, gaskets, and vibration dampers must survive continuous thermal cycling and fluid exposure. Saudi OEM localization programs are redirecting procurement toward domestically compounded fluoroelastomers and HNBR grades.
- Medical Devices:Biocompatibility testing under SFDA and Egypt's drug authority frameworks elevates barrier-to-entry for respiratory seals, surgical tubing, and implantable components. Cairo's emerging instrument cluster lacks qualified local compounders.
- Consumer Goods:Footwear, sporting equipment, and household products utilize standard EPDM and natural rubber formulations with minimal technical differentiation.
- Industrial Equipment:Mining safety equipment in South Africa faces mandatory SABS certification, creating captive demand for approved domestic suppliers.
Automotive Components command the highest technical premiums; Medical Devices show the steepest expansion trajectory.
End User:
End user structure determines whether compounders capture value through direct technical partnerships or surrender margin to distribution intermediaries.
- OEMs:Direct relationships with Saudi Aramco, Renault-Nissan's Moroccan assembly operations, and South African mining equipment builders require dedicated formulation development and just-in-time logistics.
- Tier-1 Suppliers:Seal and gasket specialists serving automotive OEMs demand compounded materials with pre-validated compression set and aging performance.
- Aftermarket Providers:Replacement seal distributors in Egypt and Nigeria prioritize price competitiveness and inventory availability over technical specification.
- Manufacturers:Industrial rollers, conveyor belting, and molded goods producers across South Africa and Morocco source standard grades through established distributor networks.
OEMs concentrate the highest value contracts; Tier-1 Suppliers are gaining procurement influence fastest.
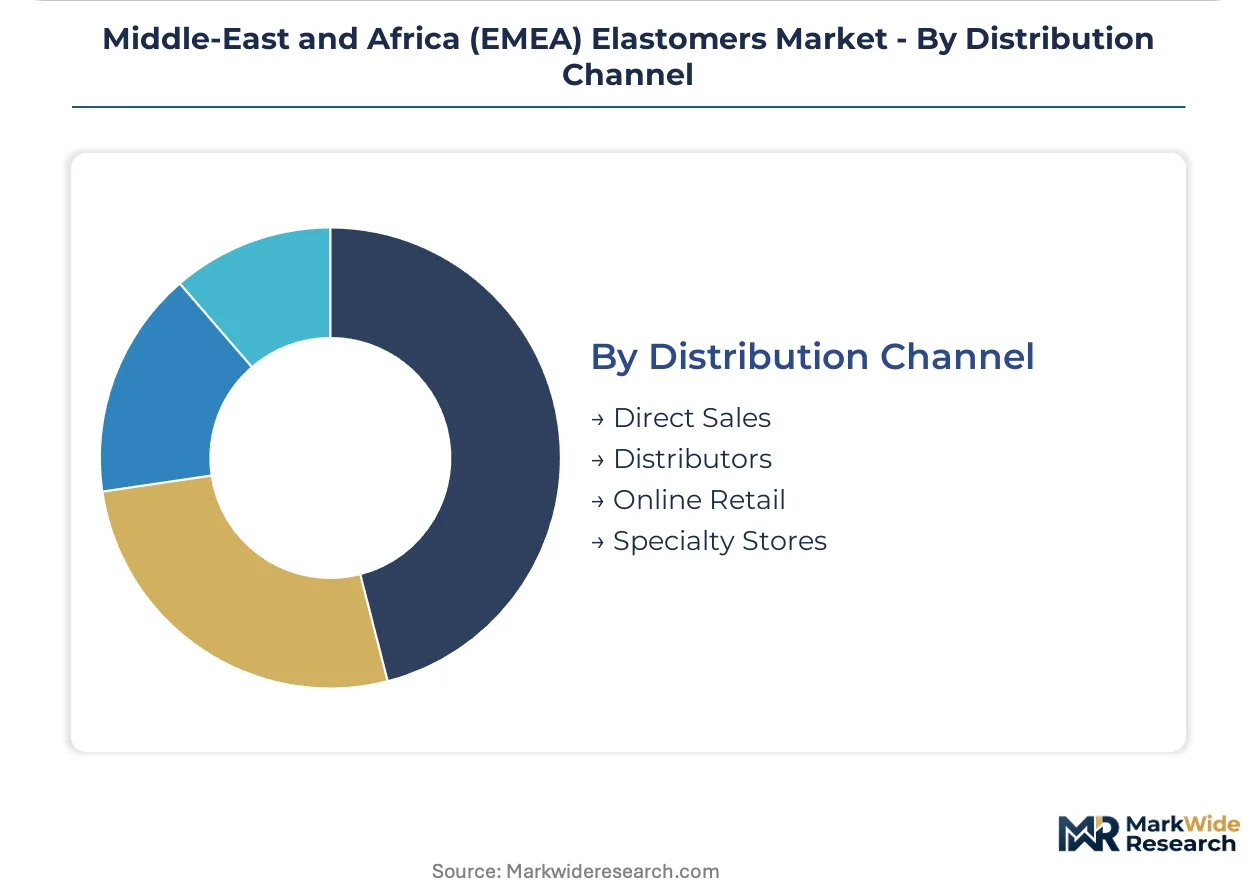
Distribution Channel:
Channel structure reflects the tension between technical service requirements and logistics cost minimization across the region's fragmented geography.
- Direct Sales:Technical compounding houses maintain direct relationships with large automotive and oilfield accounts requiring formulation customization and application engineering support.
- Distributors:Pan-African and Gulf-based industrial distributors stock standard grades for mid-tier manufacturers lacking volume to justify direct procurement.
- Online Retail:Small-lot specialty grades and replacement compounds for maintenance operations are migrating to B2B platforms serving Egyptian and Nigerian industrial buyers.
- Specialty Stores:Localized outlets in South African mining regions and Saudi industrial cities provide immediate availability for emergency seal replacement.
Direct Sales captures the majority of premium compound volume; Online Retail is penetrating fastest among small and mid-sized accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City anchors regional elastomer compounding capacity through SABIC's petrochemical feedstock integration. Saudi Arabia's automotive OEM localization programs are redirecting procurement toward domestically produced seals and gaskets. REACH-equivalent frameworks under development across Gulf Cooperation Council states are tightening material certification requirements.
Saudi Arabia
Automotive underhood seals and oilfield gaskets drive demand for heat-resistant fluoroelastomers and HNBR grades. SFDA biocompatibility standards for medical devices are elevating compliance costs for imported silicone compounds. Jubail and Yanbu industrial cities host concentrated compounding operations serving Aramco's supplier consolidation programs.
United Arab Emirates
Logistics and re-export hubs in Dubai and Jebel Ali handle specialty silicone formulations for Gulf medical device manufacturers. MOHAP pharmaceutical and medical device regulations are accelerating local testing infrastructure investment. Dubai Industrial City is attracting liquid silicone rubber processors seeking SFDA pre-certification capabilities.
South Africa
Mining safety equipment and industrial conveyor belting sustain demand for SABS-certified polyurethane and natural rubber grades. The National Regulator for Compulsory Specifications enforces mandatory elastomer approvals in underground safety applications. Gauteng and Mpumalanga provinces concentrate domestic compounding capacity serving platinum and gold mining operations.
Egypt
Cairo's emerging surgical instrument cluster lacks qualified local silicone compounders for respiratory seals and tubing components. The Egyptian drug authority's biocompatibility framework is creating first-mover opportunities for technical entrants with FDA or CE-marked formulations. New Cairo and 10th of Ramadan City industrial zones are targeting medical device assembly investment.
Morocco
Automotive interior components and industrial rollers sustain thermoplastic elastomer and polyurethane demand from European Tier-1 suppliers. Renault-Nissan's Tangier assembly operations are localizing procurement for vibration dampers and sealing systems. Casablanca-Settat region concentrates injection molding capacity serving sustainability-mandated European automotive supply chains.
Middle-East and Africa (EMEA) Elastomers Market Competitive Landscape
Capital-heavy petrochemical-integrated producers compete with asset-light specialty compounders across the EMEA elastomers landscape. The market structure fragments between feedstock-advantaged Gulf producers and European technical centers with formulation expertise. Three archetypes dominate: integrated petrochemical majors with captive rubber supply, European specialty compounders leveraging technical service relationships, and regional distributors bridging logistics gaps. Competitive dynamics center on backward integration into feedstock and forward integration into predictive maintenance service contracts.
Among European-based specialty compounders, BASF SE and Lanxess AG exemplify technical service-driven positioning. BASF SE leverages its Ludwigshafen technical center for knowledge transfer into Saudi downstream facilities. Lanxess AG anchors regional presence through captive butyl rubber supply relationships. Dow Chemical Company represents the multinational diversified archetype with silicone formulation capabilities. These three occupy distinct competitive positions without direct overlap in core elastomer grades.
| Leading Market Players |
|---|
| BASF SE |
| DuPont |
| ARLANXEO |
| Trinseo SA |
| Synthos SA |
| Lanxess AG |
| Dow Chemical Company |
| SABIC |
| ExxonMobil Chemical |
| Others |
Supply & Pricing Matrix
Compounding chemist scarcity in European technical centers widens labor-cost differentials that separate premium fluoroelastomer formulations from standard EPDM grades across the EMEA elastomers market. REACH-equivalent certification requirements in Gulf Cooperation Council states amplify these spreads by forcing dual-testing investments on non-local suppliers.
Pricing Analysis
Outcome-based pricing tied to seal uptime performance in Saudi Aramco oilfield contracts anchors value capture for high-performance grades. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-certified medical silicones from industrial EPDM and commodity natural rubber. Cost compression in standard grades is intensifying because Egyptian and Nigerian aftermarket buyers prioritize inventory availability over technical specification. Tier-1 automotive suppliers exhibit lowest price sensitivity due to pre-validated compression set requirements, while replacement seal distributors in North Africa remain most cost-conscious.
Supply Chain Analysis
Synthetic rubber feedstock supply rests on Saudi petrochemical complexes, South Korean butadiene derivatives, and German specialty chemical producers. Naphtha, butadiene, and platinum-cured silicone precursors feed regional compounding operations with varying degrees of backward integration. Single-source vulnerability concentrates in liquid silicone rubber formulations where European and Asian supply bases dominate medical-grade certification. Distribution runs through pan-Gulf industrial distributors for standard grades, while direct technical partnerships serve Saudi Aramco and Renault-Nissan Moroccan assembly operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH-equivalent framework convergence across Gulf Cooperation Council jurisdictions is compressing margins for non-compliant compounders and forcing consolidation among import-dependent distributors.
For Market Incumbents: Hedge certification exposure by accelerating local testing infrastructure investment in Dubai Industrial City and Jubail ahead of formal mandate deadlines. Deepen captive butyl rubber supply relationships with Gulf tire manufacturers to defend against European specialty compounders transferring technical service capabilities. Lock in long-term offtake agreements with SABIC feedstock operations to secure margin stability against naphtha price volatility. For New Entrants and Emerging Players: Launch via technical partnerships with Cairo's emerging surgical instrument cluster, exploiting the absence of qualified local silicone compounders for respiratory seals and biocompatible tubing. Target Egypt's medical device assembly sector with FDA or CE-marked formulations that preempt domestic regulatory qualification timelines. Establish direct sales relationships with oilfield operators unbundling predictive seal replacement contracts from bundled service providers. For Investors and Strategic Acquirers: The window for entry favors asset-light specialty compounders with proven biocompatibility testing capabilities and established Gulf distributor relationships. Mid-cap European technical service providers face succession pressure as founders age and knowledge transfer to Saudi facilities accelerates. Watch SFDA pre-certification backlog clearance rates as the inflection signal for medical-grade silicone demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | SABIC partnerships secure naphtha supply for Saudi compounding operations against margin compression. |
| Local Testing Infrastructure Investment | Dubai and Jubail facilities bypass European certification backlogs for Gulf medical device manufacturers. |
| Predictive Maintenance Service Partnership | Aramco supplier consolidation programs favor compounders bundling condition monitoring with seal supply. |
| Biocompatibility Certification Acceleration | SFDA and Egyptian drug authority alignment opens Cairo surgical instrument cluster to qualified entrants. |
| Joint Venture with Tier-1 Automotive Supplier | Renault-Nissan Tangier localization creates captive demand for pre-validated HNBR and fluoroelastomer grades. |
Research Methodology
Independent corroboration across primary interviews with compound plant managers, procurement leads at Saudi Aramco and Renault-Nissan, distribution channel partners in Dubai and Casablanca, and technical R&D directors at European specialty houses underwrites the qualitative findings. Secondary validation draws from customs and trade data tracking butadiene and silicone precursor flows, Gulf petrochemical industry association reports, SEC 10-K filings of multinational chemical producers, and SABS certification registries. Bottom-up demand modeling across automotive, medical, and industrial end-uses triangulates against top-down petrochemical capacity assessments.
Comparable-period anchoring to historical elastomer consumption patterns across the analysis window enables projection of substitution effects between thermosets and thermoplastic elastomers. The modeling framework segments by material grade tier, end-use industry concentration, regional production hub proximity, and certification burden intensity. CAGRs derive from elasticity-adjusted demand curves incorporating automotive OEM localization timelines and medical device assembly investment trajectories. Feedstock price volatility bands and regulatory implementation delay scenarios bound the forecast range.
Crude oil price swings, REACH-GCC framework divergence timelines, and thermoplastic elastomer substitution rates in automotive interiors are the dominant revision risks. Forecasts embed assumptions about Saudi downstream integration pace and Egyptian regulatory alignment with FDA protocols. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Hot Cast Elastomers Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Medical Styrenic Block Copolymer (SBC) Market
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market