
 Egypt Automotive OEM Coatings Market | 2026-2036
Egypt Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Automotive OEM Coatings Market Foresight
Commercial vehicle fleet operators is collapsing as a buyer archetype while passenger vehicle OEMs gain procurement share in Egypt's automotive coatings market. Axalta Coating Systems leverages its color-matching technology leadership to serve European-brand assembly plants in Suez Canal Economic Zone. BASF SE anchors its position through backward integration into resin production, reducing import dependency for Egyptian customers. PPG Industries Inc competes on technical service density, stationing application engineers at major OEM facilities in 10th of Ramadan City.
Egypt Automotive OEM Coatings are formulated systems comprising pigmented base coats, protective clear coats, corrosion-resistant primers, and functional specialty layers applied to vehicle bodies during original manufacturing, typically requiring bake cycles between 120°C and 160°C to achieve film properties. Waterborne technology leads volume adoption among multinational OEMs operating in Egypt due to volatile organic compound compliance pressures, while solventborne systems still dominate local commercial vehicle assembly where capital retrofit costs deter conversion. Electric vehicle application represents the fastest-growing segment as BYD and local partners establish battery-assembly capacity requiring specialized battery pack coatings with dielectric properties.
Egypt's Ministry of Environment enforces air quality standards that limit solvent emissions from automotive paint shops, compelling coating selection toward compliant chemistries. The Egyptian Organization for Standardization and Quality (EOS) aligns automotive material specifications with UN ECE regulations to facilitate export-oriented vehicle production. Stakeholders must monitor how Egypt's developing carbon accounting rules reshape supplier qualification criteria for OEM coating contracts.
Market Dynamics
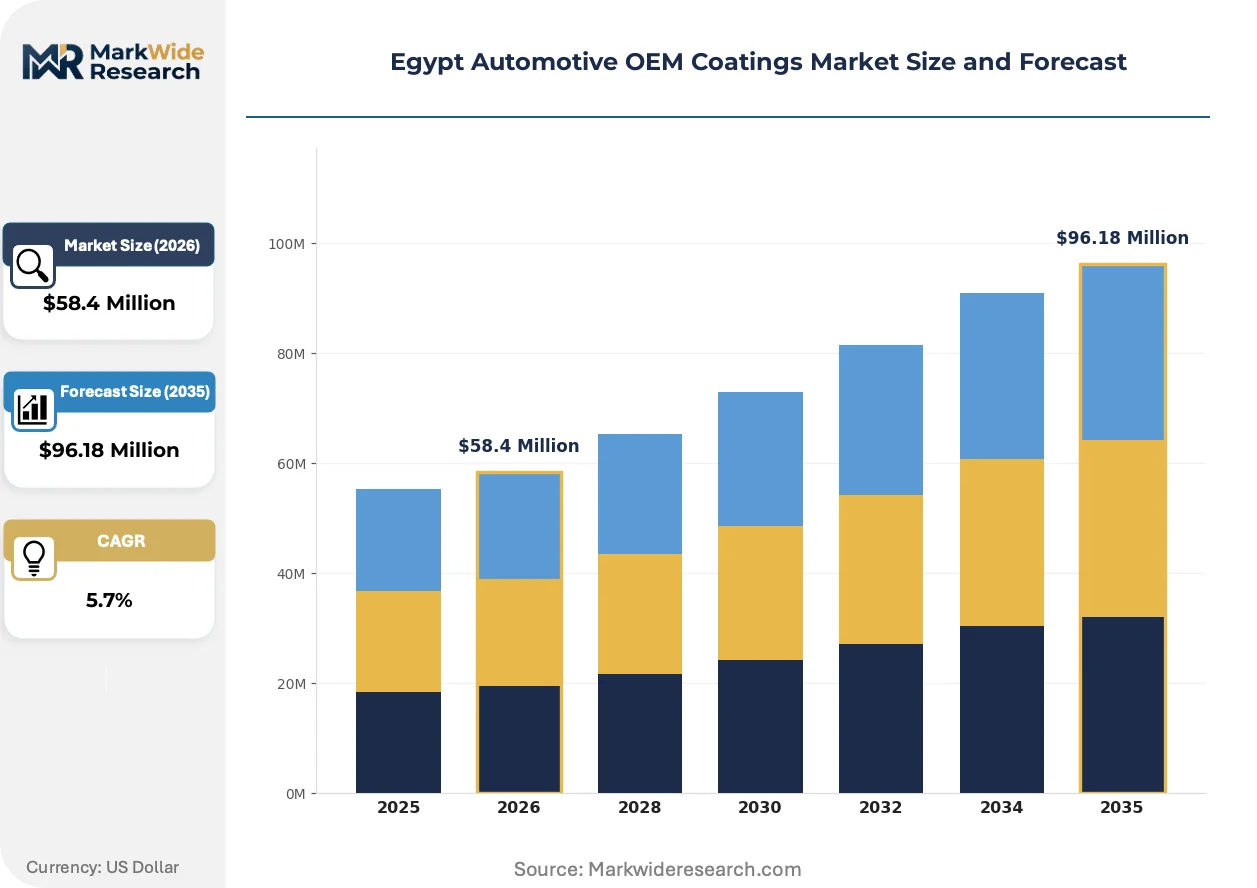
Egypt's Ministry of Environment air quality enforcement is forcing OEM paint shops toward waterborne coating systems, while passenger vehicle assembly expansion in the Greater Cairo corridor pulls procurement volume from commercial vehicle fleets.
Growth Catalysts
- Domestic Assembly Expansion:Passenger vehicle OEMs are scaling coating procurement as local assembly volumes rise, concentrated in the Greater Cairo industrial corridor where most plants operate.
- Waterborne Technology Mandate:Egypt's environmental compliance framework under the Ministry of Environment is pushing converters away from solventborne systems toward compliant chemistries.
- Electric Vehicle Battery Coatings:Specialized dielectric coating demand is emerging as battery-assembly capacity establishes locally, creating new functional layer requirements.
Market Restraints
- Capital Retrofit Costs:Commercial vehicle assembly operations face prohibitive investment requirements to convert solventborne paint shops, slowing technology transition in this segment.
- Resin Import Dependency:Local formulators remain exposed to supply chain volatility for key raw materials, with backward integration limited to multinational anchors.
- Technical Service Density Requirements:OEM qualification demands on-site application engineering support, creating barriers for suppliers without localized technical presence.
Strategic Opportunities
- Suez Canal Economic Zone:European-brand assembly plants in this corridor present concentrated demand for advanced color-matching and premium coating systems.
- Carbon Accounting Integration:Egypt's developing carbon accounting rules are reshaping supplier qualification criteria, creating first-mover advantage for compliant formulators.
- Dielectric Coating Convergence:Battery pack protection requirements are merging automotive and electronics coating technologies, opening specialty formulation white space.
Industry Challenges
- Application Engineering Talent Scarcity:Qualified paint shop technicians and color-matching specialists remain concentrated with multinational suppliers, constraining local competitor scale.
- Dual-Certification Burden:Export-oriented vehicle production requires simultaneous compliance with Egyptian Organization for Standardization and Quality specifications and UN ECE regulations, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Automotive OEM Coatings Market |
| Market Size in 2026 | $58.4 Million |
| Market Size in 2035 | $96.18 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Coats, Clear Coats, Primer Coats, Specialty Coatings Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles Technology: Waterborne, Solventborne, Powder Coatings, UV-Cured End User: OEM Manufacturers, Aftermarket Suppliers, Vehicle Assemblers, Component Providers |
| Companies Covered | Akzo Nobel N.V., Axalta Coating Systems, BASF SE, PPG Industries Inc, Nippon Paint Holdings Co. Ltd., RPM International, El Gammal, Southeast Auto Paint, Kansai Paint Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Automotive OEM Coatings Market Shifts & Advancements
Coating technology selection is bifurcating between multinational OEMs pursuing environmental compliance and local commercial assemblers optimizing capital efficiency, with innovation concentrating in functional layers for electrified powertrains.
Waterborne base coat systems are displacing solventborne alternatives in passenger vehicle assembly plants serving European and Asian brand owners. Multinational OEMs operating in the Greater Cairo corridor have completed or initiated paint shop conversions to meet Ministry of Environment volatile organic compound limits. This displacement is compressing the addressable market for traditional solventborne suppliers while expanding service revenue streams for waterborne technical specialists.
Egypt's Ministry of Environment enforcement of air quality standards is tightening allowable solvent emissions from automotive paint operations. Industrial consequence includes mandatory technology assessment for existing facilities and permit conditioning for greenfield investments. Passenger vehicle assembly plants in 10th of Ramadan City and Suez Canal Economic Zone are responding with accelerated capital allocation to compliant coating infrastructure.
Buyer concentration among passenger vehicle OEMs is compressing supplier negotiation leverage and extending contract durations. Technical service density and color-matching capability are displacing price-based selection criteria in procurement evaluations. This behavioral shift is most visible in European-brand assembly operations where specification adherence and just-in-time delivery reliability outweigh unit cost considerations.
Egypt Automotive OEM Coatings Market Segmentation
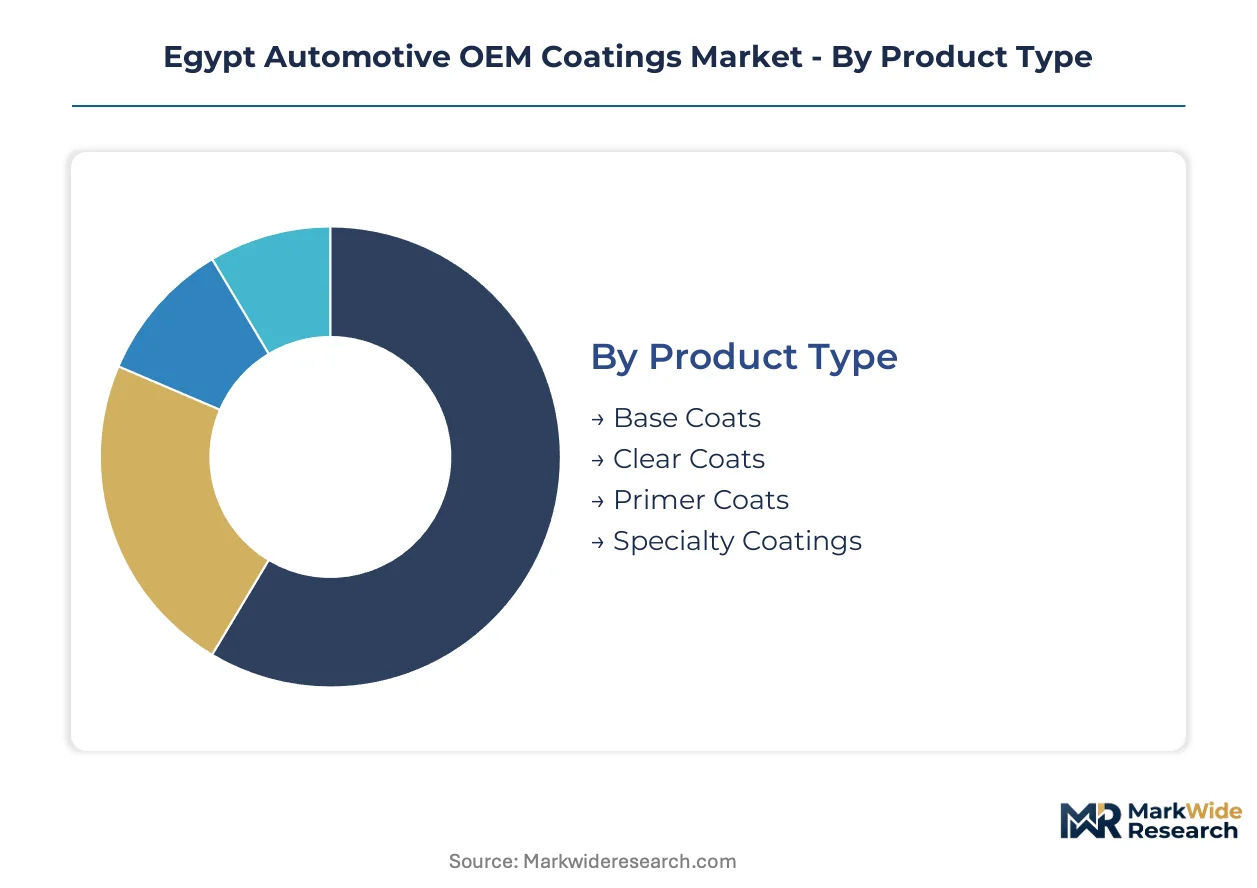
Egypt's automotive OEM coatings market segments along four intersecting dimensions that determine procurement patterns, technology selection, and margin capture. Product type and application layers define volume allocation, while technology and end-user categories shape channel economics and supplier qualification requirements.
Product Type:
Channel flow varies sharply by coating layer, with base and clear coats moving through OEM direct contracts while specialty coatings route through component providers serving battery and powertrain applications.
- Base Coats:Pigmented layers providing color and aesthetic finish to vehicle exteriors, typically applied over primers in wet-on-wet processes. Demand concentrates at European-brand passenger vehicle plants in the Suez Canal Economic Zone where color-matching precision requirements exceed local formulation capabilities.
- Clear Coats:Transparent protective top layers delivering gloss retention, UV resistance, and scratch protection through polyurethane or acrylic chemistries. Procurement is accelerating at BYD's local battery-assembly partnerships where dielectric-grade clear coats protect high-voltage components from environmental degradation.
- Primer Coats:Corrosion-resistant underlayers ensuring substrate adhesion and stone-chip protection.
- Specialty Coatings:Functional formulations including battery pack dielectrics, underbody sealants, and heat-resistant exhaust coatings.
Base coats dominate installed base by volume. Specialty coatings are where expansion concentrates as electrification creates new functional layer requirements.
Application:
Cost tier stratification separates premium passenger vehicle specifications from price-optimized commercial vehicle requirements, with electric vehicles occupying a distinct premium-functional tier.
- Passenger Vehicles:Sedans, SUVs, and light trucks manufactured for consumer markets requiring premium finish quality and extensive color palettes. Volume is climbing fastest at assembly plants in 10th of Ramadan City serving re-export markets to Middle East and African destinations.
- Electric Vehicles:Battery electric and hybrid platforms requiring specialized dielectric coatings, thermal management layers, and lightweight substrate compatibility. This segment is gaining share fastest as BYD and local partners establish battery-assembly capacity requiring functional coatings with specific electrical insulation properties.
- Commercial Vehicles:Trucks, buses, and heavy equipment assembled for fleet operators prioritizing durability over aesthetic refinement.
- Two-Wheelers:Motorcycles and scooters manufactured for domestic and regional export markets.
Passenger vehicles anchor current procurement volume. Electric vehicles represent the steepest expansion trajectory as battery-assembly localization accelerates.
Technology:
Application method and cure requirements determine capital intensity, with waterborne systems demanding spray booth retrofits that solventborne users have deferred.
- Waterborne:Water-based resin systems meeting Ministry of Environment volatile organic compound limits through reduced solvent content. Adoption is concentrating among multinational OEMs in Greater Cairo where environmental compliance permits condition operational licensing.
- Solventborne:Traditional solvent-based formulations offering lower capital cost and established application protocols. This technology retains dominance at local commercial vehicle assemblers where retrofit economics remain prohibitive.
- Powder Coatings:Solvent-free dry film applications cured through thermal fusion, primarily used for wheels and underbody components.
- UV-Cured:Rapid-cure systems polymerized through ultraviolet exposure, suited for heat-sensitive substrates.
Solventborne systems dominate legacy installed base. Waterborne technology is where qualification and contract expansion concentrate.
End User:
Customer type determines service intensity, with OEM manufacturers demanding on-site technical support that aftermarket channels cannot economically replicate.
- OEM Manufacturers:Original equipment producers operating licensed assembly plants for global automotive brands. Procurement concentrates at facilities in the Suez Canal Economic Zone where just-in-time delivery and color-matching technical service density determine supplier selection.
- Vehicle Assemblers:Local operations conducting complete knock-down assembly for regional markets. Volume is expanding at 10th of Ramadan City plants serving African export destinations with simplified specification requirements.
- Aftermarket Suppliers:Refinish and repair coating distributors serving collision repair networks.
- Component Providers:Tier suppliers coating individual parts prior to vehicle assembly, including battery pack manufacturers.
OEM manufacturers dominate premium contract value. Component providers are where battery coating specialization creates new supplier entry points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Passenger vehicle OEMs concentrate procurement in Egypt's industrial corridors, with environmental compliance reshaping supplier geography and contract allocation across sub-regional manufacturing clusters.
Greater Cairo
Assembly plants in 10th of Ramadan City and Obour City drive base coat and clear coat demand as European and Asian brand owners expand local production. Egypt's Ministry of Environment enforces volatile organic compound limits that condition operational licensing for paint shop facilities. Technical service density requirements favor multinational formulators with localized application engineering presence in this corridor.
Suez Canal Economic Zone
European-brand assembly operations generate premium coating procurement requiring advanced color-matching capabilities and just-in-time delivery reliability. The General Authority for Suez Canal Economic Zone offers investment incentives that attract OEM facilities with stringent environmental compliance obligations. Industrial clustering in Ain Sokhna and Port Said East concentrates demand for waterborne systems among export-oriented vehicle producers.
Alexandria and the North Coast
Port infrastructure and Mediterranean access support component import and finished vehicle export logistics for coating-dependent assembly operations. The Egyptian Organization for Standardization and Quality aligns automotive material specifications with UN ECE regulations to facilitate re-export markets. Paint shop operations in Borg El Arab industrial zone serve regional African destinations with dual-certified production requirements.
Upper Egypt Industrial Corridor
Commercial vehicle assemblers in Sohag and Qena retain solventborne system dominance due to deferred capital retrofit investments and lower regulatory enforcement intensity. Local fleet operators prioritize durability specifications over aesthetic finish quality in procurement decisions. This sub-region represents a technology transition lag zone where environmental compliance pressure remains attenuated relative to northern governorates.
Egypt Automotive OEM Coatings Market Competitive Landscape
Player mix skews toward multinational chemical conglomerates with integrated resin production and localized technical service infrastructure. Three to five global suppliers capture premium OEM contract value through qualification barriers that exclude regional formulators. Competitive dynamics center on backward integration into raw materials, application engineering headcount density at customer facilities, and carbon accounting compliance certification for emerging supplier qualification criteria.
Among Netherlands-based and Germany-based chemical majors, Akzo Nobel N.V. and BASF SE exemplify the integrated-resin archetype that reduces Egyptian customer exposure to import volatility. Axalta Coating Systems occupies a position representing the color-matching specialization vector serving European-brand assembly plants. These three anchors illustrate how technical service intensity and environmental compliance capability determine contract access in this procurement environment.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| BASF SE |
| PPG Industries Inc |
| Nippon Paint Holdings Co. Ltd. |
| RPM International |
| El Gammal |
| Southeast Auto Paint |
| Kansai Paint Co., Ltd. |
| Others |
Supply & Pricing Matrix
Waterborne resin substitution for solventborne systems is compressing procurement geography toward European and Asian chemical majors while elevating technical service premiums in Egyptian coating contracts. This input transition simultaneously concentrates supplier qualification around environmental compliance capability and extends contract durations as OEMs lock in application engineering support.
Pricing Analysis
Cost-plus contracts with resin indexation dominate procurement between multinational formulators and Egyptian OEM assembly plants. Price differentiation hinges on color-matching precision grades and Ministry of Environment compliance certification tiers, with premium waterborne systems commanding technical service premiums over commodity solventborne alternatives. Cost compression in commercial vehicle segments is intensifying as local assemblers defer capital retrofits and extend legacy system procurement cycles. Passenger vehicle OEMs in the Suez Canal Economic Zone exhibit lowest price sensitivity, prioritizing just-in-time reliability and specification adherence over unit cost.
Supply Chain Analysis
Germany and the Netherlands anchor specialty resin and pigment production serving Egyptian automotive coating formulators. Local production draws from imported epoxy intermediates, polyurethane dispersions, and colorant concentrates, with backward integration limited to multinational anchors. Single-source vulnerability concentrates in dielectric additive supply for emerging battery coating applications. Distribution runs through direct OEM contracts for base and clear coats, while specialty functional layers route via tier component providers serving localized battery assembly partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's automotive OEM coatings market represents a high-growth disruption as electric vehicle battery assembly localization creates entirely new functional coating categories. The Ministry of Environment's volatile organic compound enforcement acts as the regulatory inflection compressing technology transition timelines and reshaping supplier qualification criteria.
For Market Incumbents: Secure carbon accounting certification ahead of emerging OEM supplier qualification requirements to defend contract access against regional formulators building compliance capability. Anchor backward integration into resin production to reduce Egyptian customer exposure to import volatility, particularly for waterborne polyurethane dispersions facing supply chain congestion. For New Entrants and Emerging Players: Lead with dielectric coating specialization targeting BYD's localized battery assembly partnerships and tier component providers serving electrified powertrain applications. The Upper Egypt commercial vehicle corridor presents the most penetrable geography where solventborne retrofit economics remain prohibitive for incumbents, enabling price-competitive entry with technical service-light offerings. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional distributors holding established relationships with local vehicle assemblers but lacking waterborne technical service infrastructure. Five-to-ten year viability hinges on conversion execution capability rather than legacy solventborne market share. The signal to watch is Ministry of Environment permit conditioning intensity for existing paint shop facilities, which would accelerate mandated technology transition and compress valuation windows for non-compliant targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | BASF SE's captive polyurethane supply reduces Egyptian customer import dependency and currency exposure. |
| Waterborne Paint Shop Retrofit Partnership | Axalta Coating Systems stations application engineers at 10th of Ramadan City facilities to accelerate OEM conversion timelines. |
| Dielectric Coating R&D Collaboration | Specialized formulations for BYD battery packs merge automotive and electronics coating technology requirements. |
| Carbon Accounting Certification Program | First-mover compliance with Egypt's developing carbon rules reshapes supplier qualification criteria for premium OEM contracts. |
| Suez Canal Economic Zone Technical Service Hub | Concentrated European-brand demand in Ain Sokhna requires localized color-matching and just-in-time delivery infrastructure. |
Research Methodology
Desk research of customs trade databases, Egyptian Organization for Standardization and Quality filings, and automotive production registries preceded structured interviews with OEM procurement managers, paint shop engineers, and coating formulator technical directors. Primary fieldwork combined telephone and in-person exchanges across the Greater Cairo industrial corridor and Suez Canal Economic Zone with secondary validation against Ministry of Environment permit records and UN ECE regulatory alignment documentation. Bottom-up volume estimates triangulated against top-down market sizing from import value flows and installed paint shop capacity.
Variance decomposition across product type, application layer, technology chemistry, and end-user category shaped the analytical framework throughout the forecast period. Modeled segmentation captured vehicle class distinctions between passenger, electric, and commercial platforms alongside propulsion architecture evolution and regional production cluster concentration. CAGRs derived from segment-level volume trajectories weighted by technology conversion timelines and OEM capacity expansion announcements, with dielectric coating demand for battery applications treated as a distinct growth vector.
The analysis sits within stated boundaries; outcomes outside sustained Ministry of Environment enforcement intensity or accelerated electric vehicle assembly localization would require recalibration. Forecasts reflect assumptions regarding resin import cost stability and paint shop retrofit capital availability that exposure to currency volatility or credit tightening could revise. Recalibration cycles align with material shifts in environmental permit conditioning and battery assembly partnership announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Gelcoat Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
Global Floor Coatings Market
Coatings
Sustained Release Coatings Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Antimicrobial Coil Coating Market
Coatings
Hydrophilic Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Protective Coatings Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
Fillers and Coating Market
Coatings
Global Solar Panel Coatings Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
E-Coat Market
Coatings
Architectural Metal Coatings Market
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market