
 Polysulfide Market | 2026-2036
Polysulfide Market Size, Share, and Industry Trends Forecast 2026-2036
Polysulfide Market Outlook
Buyer concentration among aerospace OEMs is rebalancing procurement volumes toward long-term supply agreements with fewer qualified vendors. BASF leverages its Ludwigshafen integrated site to control feedstock costs for liquid polysulfide precursors. Arkema sustains technology leadership in high-performance sealant grades through dedicated R&D at its Serquigny facility. Flamemaster Corporation specializes in FAA-certified aerospace sealant formulations, occupying a defensible niche in fire-resistant polysulfide systems.
Polysulfides comprise sulfur-linked oligomeric chains, typically with molecular weights between 1,000 and 8,000 daltons, manufactured through condensation of sodium polysulfide with organic dihalides to yield thiol-terminated liquid polymers or solid elastomeric grades. These materials function primarily as chemically resistant sealants, adhesives, and coatings where flexibility across extreme temperatures and fuel exposure is required. Liquid polysulfide dominates sealant applications due to its self-leveling viscosity and room-temperature cure chemistry, while solid grades anchor the elastomer segment for molded gaskets and vibration-damping components. Water-based polysulfide formulations represent the fastest-growing product category as VOC regulations tighten across construction and automotive end uses.
EPA standards on volatile organic compound emissions restrict solvent-based polysulfide formulations in US construction and industrial coatings, while REACH registration requirements in Europe impose compliance burdens on imported raw material streams. The FAA's material flammability specifications under FAR 25.853 shape qualification pathways for aerospace sealant suppliers, creating barrier-to-entry effects for uncertified producers. Stakeholders must monitor evolving green chemistry mandates and OEM sustainability scorecards to align product portfolios with tightening environmental compliance thresholds.
Market Dynamics
Aerospace OEM consolidation toward long-term supply agreements with fewer qualified vendors is compressing procurement cycles and elevating qualification barriers for polysulfide sealant suppliers across the value chain.
Growth Catalysts
- FAR 25.853 Certification Requirements:FAA material flammability specifications mandate fire-resistant polysulfide systems in commercial aircraft interiors, locking in demand for qualified formulations.
- Germany's Industrial Corridor Concentration:Integrated production sites along the Rhine-Main chemical belt capture feedstock cost advantages for liquid polysulfide precursors serving European aerospace and construction.
- Water-Based Formulation Chemistry:Low-VOC polysulfide sealants are displacing solvent systems in construction applications as EPA and REACH thresholds tighten.
Market Restraints
- Feedstock Sulfur Price Volatility:Sodium polysulfide input costs fluctuate with petroleum refining byproduct availability, squeezing margin stability for liquid polymer producers.
- European Supply Concentration:Ludwigshafen and Serquigny anchor integrated polysulfide manufacturing, creating geographic vulnerability to regional energy cost spikes or logistics disruptions.
- Silicone Elastomer Substitution:High-performance silicone sealants compete in fuel-resistant aerospace gasket applications where extended temperature range outweighs polysulfide cost advantages.
Strategic Opportunities
- India Infrastructure Build-Out:National highway and airport expansion programs generate demand for construction-grade polysulfide joint sealants in concrete infrastructure.
- EU Green Deal Compliance Services:REACH registration support and lifecycle assessment documentation create service-layer revenue for suppliers helping customers navigate green chemistry mandates.
- Hybrid Curing Systems:Moisture-cure polysulfide-urethane copolymers are converging with automated dispensing equipment in automotive assembly lines.
Industry Challenges
- FAA Certification Timeline Compression:Aerospace sealant qualification cycles extend 18-36 months, delaying revenue recognition for new formulation launches.
- Specialized Polymer Synthesis Talent Scarcity:Thiol-terminated oligomer chemistry expertise concentrates among retiring workforce cohorts at legacy production facilities.
- Legacy Equipment Integration:Water-based polysulfide formulations require modified spray and extrusion systems incompatible with existing solvent-based application infrastructure at contractor sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysulfide Market |
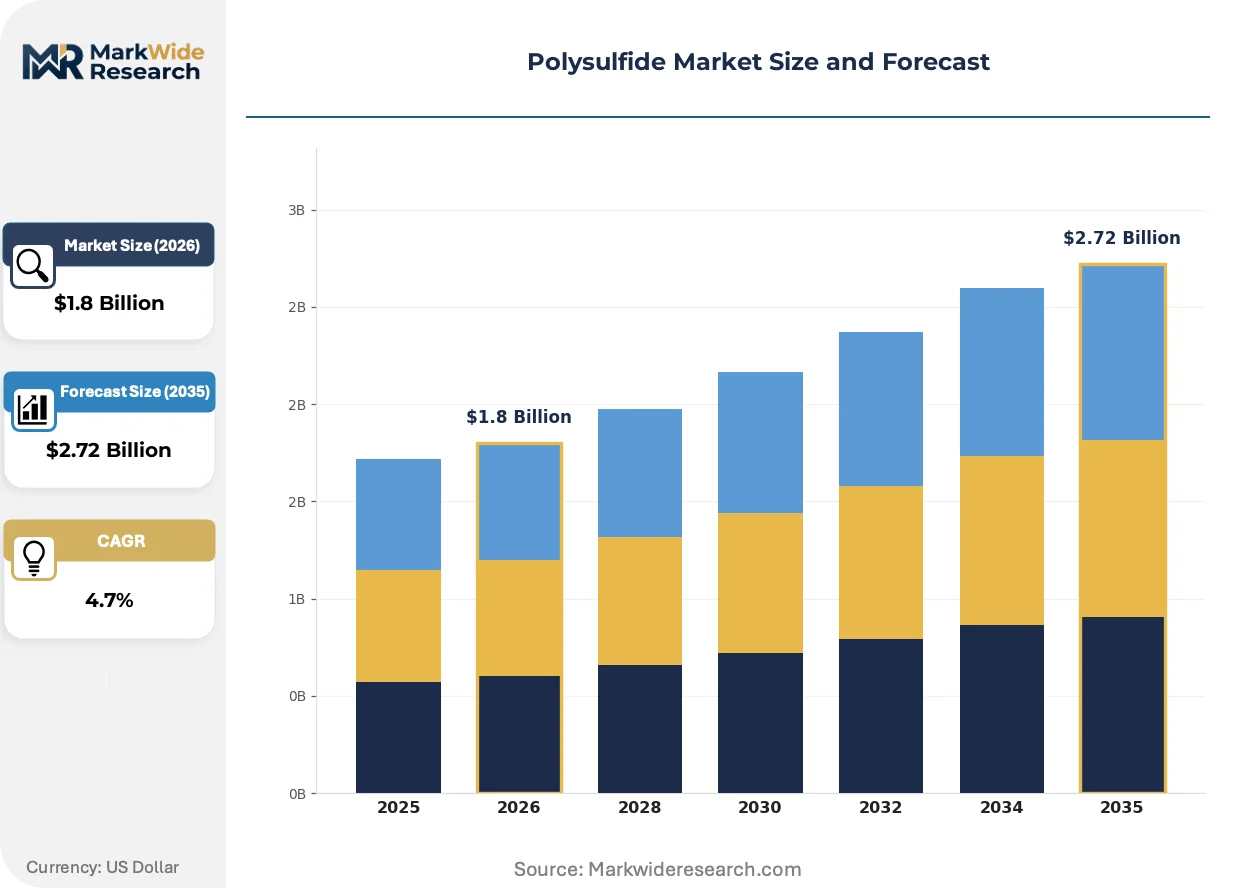
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Polysulfide, Solid Polysulfide, Water-Based Polysulfide, Oil-Based Polysulfide End User: Aerospace, Automotive, Construction, Electronics Application: Sealants, Adhesives, Coatings, Elastomers Distribution Channel: Direct Sales, Online Retailing, Distributors, Wholesalers |
| Companies Covered | BASF, Arkema, Nouryon, Ineos Group, Akzo Nobel, Toray Fine Chemicals, Flamemaster Corporation, 3M, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysulfide Market Strategic Shifts
Formulation chemistry, regulatory compliance architecture, and procurement contracting models are simultaneously evolving across the polysulfide value chain. These shifts reshape competitive positioning and technology investment priorities.
Two-part polysulfide-epoxy hybrid sealants are converging with automated metering-mixing-dispensing systems in wind turbine blade manufacturing. Vestas and Siemens Gamesa production lines in Denmark and Spain adopt these systems for root joint sealing. This convergence is compressing labor content and defect rates in blade assembly while locking in specification requirements for qualified material suppliers.
REACH registration requirements under EU chemicals regulation impose data-generation burdens on imported sodium polysulfide streams entering European compounding facilities. ECHA substance evaluation dossiers now demand extended toxicity endpoints for thiol-terminated oligomers. German and French formulators respond by backward-integrating into captive polysulfide precursor production to control registration asset ownership.
Aerospace buyers now unbundle sealant supply from application services, compressing vendor margins while elevating material certification documentation requirements. Tier-1 suppliers like Spirit AeroSystems and GKN Aerospace issue multi-year sole-source agreements to qualified polysulfide vendors. This pattern concentrates procurement volumes with BASF and Arkema in Germany and Flamemaster in California.
Polysulfide Market Segmentation
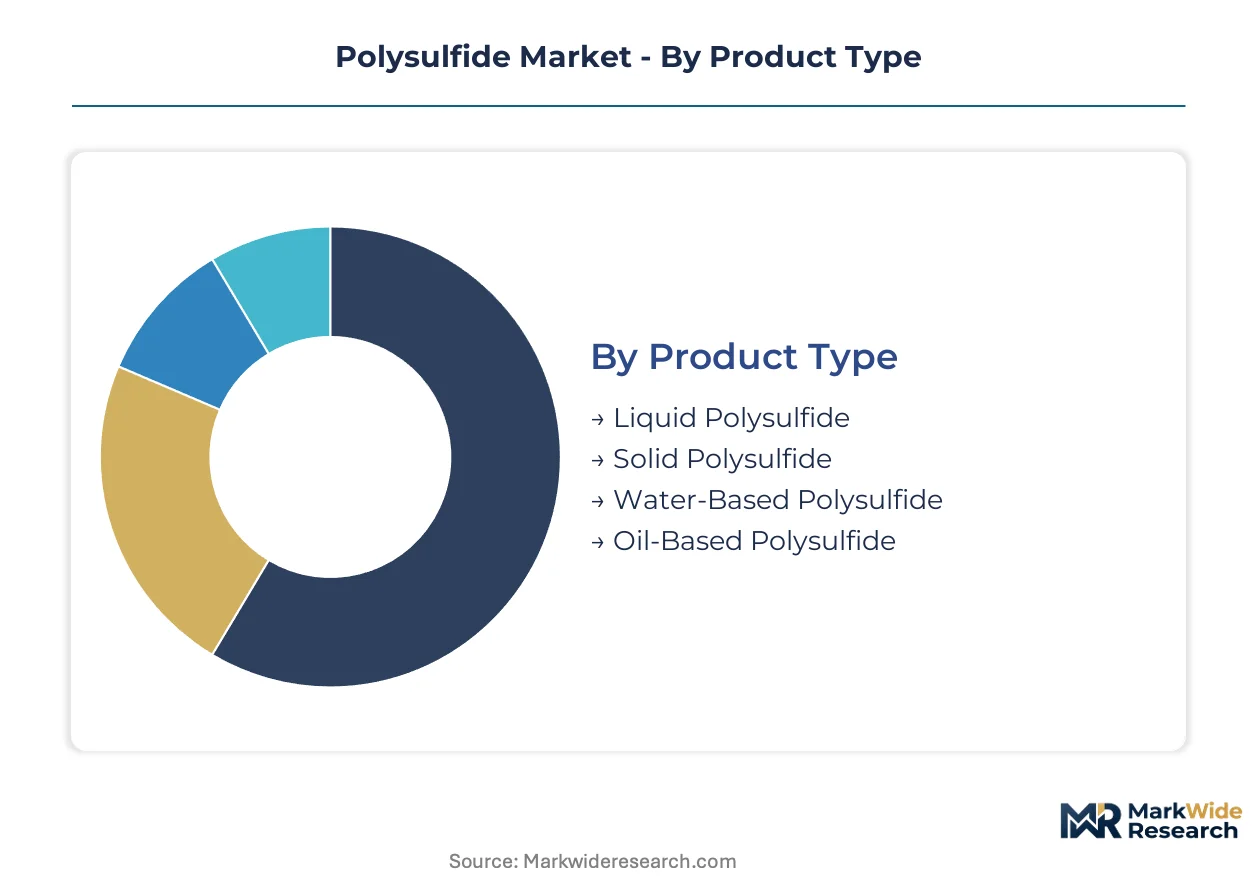
Polysulfide chemistry fragments across physical states, cure mechanisms, and performance tiers that map unevenly to end-use requirements. Aerospace sealant specifications demand thiol-terminated liquid polymers with FAA certification, while construction joint sealing tolerates broader viscosity ranges. Understanding where formulation flexibility ends and qualification lock-in begins separates addressable market pockets from protected vendor positions.
Product Type:
Customization intensity varies sharply across this category, with aerospace-qualified liquid grades requiring dedicated synthesis lines while water-based construction sealants permit toll manufacturing.
- Liquid Polysulfide:Thiol-terminated oligomers with molecular weights between 1,000 and 8,000 daltons cure at room temperature through oxidative crosslinking. Demand concentrates in Germany's aerospace corridor, where BASF and Arkema supply qualified sealant precursors under long-term OEM contracts. FAR 25.853 flammability certification locks in specification continuity for qualified formulations.
- Water-Based Polysulfide:Dispersed polymer particles in aqueous carriers achieve sub-100 g/L VOC content for EPA-compliant construction applications. Demand is climbing fastest in European building renovation programs driven by EU Green Deal embodied carbon thresholds and REACH solvent restrictions.
- Solid Polysulfide:Vulcanized elastomeric sheets and molded profiles serve vibration-damping and gasket applications.
- Oil-Based Polysulfide:Hydrocarbon-extended formulations target cost-sensitive industrial coating markets with reduced chemical resistance.
Leading the category by volume: Liquid Polysulfide. Expanding most quickly: Water-Based Polysulfide.
End User:
Application complexity and qualification burden create a steep cost-to-performance gradient across customer types, with aerospace commanding 3-5x raw material premiums over construction.
- Aerospace:Fuel tank sealants, firewall penetration seals, and cabin pressure boundary applications require thiol-terminated polymers with jet fuel immersion resistance across -55°C to 135°C operating windows. Boeing and Airbus procurement consolidation toward sole-source agreements compresses vendor counts while extending contract tenors. FAA material qualification cycles of 18-36 months protect incumbent positions.
- Construction:Expansion joint sealants in concrete highways, airport runways, and building envelopes tolerate broader performance bands. India's national infrastructure build-out generates demand for polysulfide joint sealants in concrete pavement systems, with procurement favoring domestic toll compounders over imported finished goods.
- Automotive:Direct glazing adhesives and seam sealers compete with polyurethane and silicone chemistries on automated assembly line compatibility.
- Electronics:Potting compounds and conformal coatings exploit polysulfide moisture resistance in harsh environment applications.
Dominating revenue contribution: Aerospace. Gaining share fastest: Construction.
Application:
Functional requirements split this category between structural load-bearing roles and protective barrier functions, with qualification intensity running inverse to material thickness.
- Sealants:Self-leveling and non-sag viscosities accommodate joint movement in building envelopes, fuel tanks, and transportation infrastructure. Two-part polysulfide-epoxy hybrids are converging with automated metering-mixing-dispensing systems in Vestas and Siemens Gamesa wind turbine blade root joint sealing, compressing labor content while locking in specification requirements.
- Adhesives:Structural bonding applications in aerospace panel assembly and automotive direct glazing demand controlled modulus development and primer compatibility.
- Coatings:Chemical-resistant tank linings and marine anti-corrosion systems exploit polysulfide hydrocarbon resistance.
- Elastomers:Molded gaskets, O-rings, and vibration isolation mounts leverage sulfur-crosslinked network elasticity.
Commanding the largest volume share: Sealants. Steepest expansion trajectory: Adhesives.
Distribution Channel:
Customer scale and technical service requirements fragment this category between direct vendor relationships for qualified aerospace buyers and arm's-length transactions for construction commodities.
- Direct Sales:Aerospace OEMs and Tier-1 suppliers like Spirit AeroSystems and GKN Aerospace procure certified sealant systems through multi-year sole-source agreements with technical service bundling. This channel captures the highest margin tier through formulation customization and qualification documentation support.
- Distributors:Regional construction chemical distributors stock standard-grade liquid and water-based polysulfides for contractor spot purchasing, with inventory carrying costs favoring established relationships over price shopping.
- Online Retailing:Small-lot specialty grades and repair quantities reach maintenance shops through B2B platforms with limited technical support.
- Wholesalers:Volume construction sealants flow through building material wholesalers serving regional contractor networks.
Generating the highest revenue per transaction: Direct Sales. Expanding fastest: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sulfur refining byproducts from petroleum processing concentrate polysulfide precursor supply in industrial corridors tied to major chemical clusters. Manufacturing gravity follows feedstock access and qualified end-user proximity.
Germany
Aerospace sealant demand from Airbus and Tier-1 suppliers drives consumption of thiol-terminated liquid polymers. REACH registration requirements under ECHA enforce data-generation burdens on imported sodium polysulfide streams. Ludwigshafen and Serquigny anchor integrated production, with BASF and Arkema maintaining captive precursor synthesis for qualified aerospace formulations.
United States
Commercial aircraft manufacturing and defense procurement sustain demand for FAR 25.853-certified sealant systems. EPA volatile organic compound standards restrict solvent-based formulations in construction and industrial coatings. California-based Flamemaster Corporation occupies a defensible niche in fire-resistant aerospace polysulfide systems serving Boeing and Northrop Grumman supply chains.
China
Wind turbine blade manufacturing expansion generates demand for two-part polysulfide-epoxy hybrid sealants in root joint applications. NMPA and GB standards govern chemical product registration, though aerospace-grade qualification remains limited to imported systems. Yangtze River Delta chemical clusters develop domestic liquid polymer capacity for construction sealant markets.
India
National highway and airport infrastructure programs create demand for construction-grade joint sealants in concrete pavement systems. BIS certification requirements and DGFT import regulations shape procurement preferences for domestic toll compounders. Gujarat and Maharashtra industrial corridors attract regional blending facilities serving western and southern infrastructure corridors.
France
Aerospace supply chain integration with Airbus final assembly sustains demand for qualified sealant precursors. EU Green Deal embodied carbon thresholds and REACH solvent restrictions accelerate water-based formulation adoption in building renovation. Auvergne-Rhône-Alpes chemical processing clusters support Arkema's Serquigny R&D and production operations.
Polysulfide Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue water-based formulation chemistry and regional toll manufacturing partnerships. Market structure concentrates among integrated chemical majors with captive sulfur processing and aerospace qualification assets. Three archetypes dominate: feedstock-integrated multinationals, aerospace-certified specialists, and regional toll compounders serving construction markets. Competitive moves center on backward integration into sodium polysulfide production and multi-year sole-source contracting with Tier-1 aerospace suppliers.
Among feedstock-integrated multinationals, BASF and Arkema exemplify the archetype of producers controlling precursor synthesis through Ludwigshafen and Serquigny chemical complexes. Flamemaster Corporation occupies a position within the aerospace-certified specialist tier, representing the model of California-based vendors securing FAA material approvals for fire-resistant sealant systems. These three anchors illustrate how qualification assets and geographic proximity to qualified end-users stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| BASF |
| Arkema |
| Nouryon |
| Ineos Group |
| Akzo Nobel |
| Toray Fine Chemicals |
| Flamemaster Corporation |
| 3M |
| PPG Industries |
| Others |
Value Chain & Pricing Dynamics
Sodium polysulfide feedstock costs cascade through three distinct pricing tiers, with sulfur refining byproduct availability in Germany's Ludwigshafen corridor anchoring premium aerospace-grade liquid polymers while toll compounders in India and China compete on construction-grade water-based formulations.
Pricing Analysis
Application service bundling separates aerospace direct sales from unbundled construction distributor transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by FAA certification status and REACH registration asset ownership. Pricing pressure stems from silicone elastomer substitution in fuel-resistant gasket applications. Construction contractors exhibit highest price sensitivity; aerospace OEMs prioritize qualification continuity over unit cost.
Supply Chain Analysis
Specialized polymer synthesis talent scarcity concentrates among retiring workforce cohorts at legacy production facilities in Germany and France. Manufacturing gravity centers on Ludwigshafen and Serquigny for captive precursor synthesis, with Yangtze River Delta and Gujarat corridors emerging for regional toll compounding. Feedstock draws from petroleum refining sulfur recovery units. Single-source vulnerability persists in thiol-terminated oligomer expertise. Distribution runs through direct vendor relationships for aerospace and regional construction chemical distributors for commodity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into sodium polysulfide production and captive REACH registration asset ownership has become the decisive competitive lever as ECHA toxicity endpoint requirements escalate compliance burdens.
For Market Incumbents: To counter silicone elastomer encroachment in aerospace fuel tank applications, BASF and Arkema should deepen captive precursor synthesis at Ludwigshafen and Serquigny while extending sole-source contract tenors with Spirit AeroSystems and GKN Aerospace. FAA certification timeline compression protects incumbent positions against formulation challengers.
For New Entrants and Emerging Players: Capture India's national highway and airport infrastructure build-out through toll manufacturing partnerships with Gujarat and Maharashtra regional compounders. Water-based construction sealants offer the most penetrable entry point given lower qualification barriers and BIS certification pathways versus aerospace FAR 25.853 requirements.
For Investors and Strategic Acquirers: ECHA substance evaluation dossier demands for extended thiol-terminated oligomer toxicity endpoints is the leading indicator that REACH registration asset ownership will separate viable acquisition targets from stranded capacity. Target formulators with backward-integrated precursor production in Germany's industrial corridor. Watch for aerospace OEM unbundling of sealant supply from application services as margin compression signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive sodium polysulfide synthesis at Ludwigshafen and Serquigny locks in REACH registration asset control against imported raw material stream vulnerabilities. |
| Long-term Supply Agreement | Multi-year sole-source contracts with Boeing and Airbus procurement consolidate volumes with qualified vendors and extend revenue visibility. |
| Green Manufacturing Transition | Water-based formulation conversion captures EU Green Deal embodied carbon thresholds and EPA VOC compliance in construction applications. |
| Joint Venture | Regional toll manufacturing partnerships in Gujarat and Maharashtra serve India's infrastructure corridors while navigating DGFT import regulations. |
| Capacity Expansion | Automated metering-mixing-dispensing system integration with Vestas and Siemens Gamesa wind turbine lines locks in specification requirements. |
Study Parameters
Independent corroboration across procurement executives at aerospace Tier-1 suppliers, plant managers at German chemical complexes, and construction chemical distributors underwrites the qualitative findings. Primary fieldwork encompassed technical R&D directors, downstream OEM procurement leads, and channel partners across the value chain. Secondary validation drew from ECHA substance evaluation dossiers, FAA material qualification databases, SEC 10-K filings of listed chemical producers, and customs trade data for sodium polysulfide precursor flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Rate-of-change decomposition across the analysis window disaggregated volume and value trajectories by product type tier, end-use industry qualification intensity, cure chemistry platform, and regional production hub concentration. CAGRs were derived from segment-level growth rate reconciliation with aggregate market scaling. Forecast inputs incorporated aerospace OEM procurement consolidation patterns, REACH registration cost escalation curves, and water-based formulation displacement rates in construction applications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sulfur refining byproduct availability, ECHA toxicity endpoint expansion, and aerospace OEM sole-source contract renegotiation cycles. Forecasts reflect documented assumptions regarding feedstock cost stability and qualification timeline continuity. Material deviation in FAA certification backlog duration or EU Green Deal solvent restriction acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Optically Clear Resin Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Rosin Resin Market
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Natural Polymers Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Foamed Plastics Market
Polymers & Resins
Global Water-Based Resins Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
India Polyacrylamide Copolymer Market