
 Global Thermoplastic Elastomers (TPE) Market | 2026-2036
Global Thermoplastic Elastomers (TPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermoplastic Elastomers (TPE) Market Foresight
Asset-light toll manufacturing and third-party compounding arrangements is narrowing the capital barrier for mid-sized compounders to supply automotive OEMs directly. Kraton Corporation leverages its hydrogenated styrenic block copolymer technology to sustain premium positioning in medical tubing applications. BASF SE anchors European supply through integrated polyether polyol operations for TPU grades. DuPont de Nemours, Inc. competes on specialty copolyester elastomers for wire and cable insulation demanding elevated thermal resistance.
Thermoplastic elastomers combine rubber-like elasticity at service temperatures with thermoplastic processability, typically featuring hard and soft segment block architectures that phase-separate into physical crosslink domains without chemical vulcanization. Shore hardness ranges from 20A to 75D depending on hard-segment content, enabling injection molding and extrusion without post-curing cycles. Styrenic block copolymers dominate volume due to established footwear and adhesive applications with mature margin structures. Thermoplastic vulcanizates are gaining structural share in under-the-hood automotive seals as OEMs pursue weight reduction against metal-rubber assemblies. Thermoplastic polyurethane concentrates value pools in medical device catheters and film laminates where biocompatibility certification commands price premiums.
The US EPA regulates volatile organic compound emissions from TPE processing facilities under Clean Air Act Title V permitting, while the EU REACH framework restricts phthalate plasticizers and certain heavy metal catalyst residues in consumer-contact grades. China's SAMR enforces GB standards for automotive interior air quality that favor low-VOC TPO formulations. Japan's METI promotes recycled-content targets through resource circulation legislation affecting post-industrial TPE scrap recovery. Stakeholders must monitor evolving extended producer responsibility schemes and bio-based feedstock certification standards that will determine which compounders retain formulation approval across major economies.
Market Dynamics
Automotive OEMs in Germany and China are redirecting formulation strategies toward halogen-free TPE grades as EU REACH restrictions on restricted substances and China's GB standards for vehicle materials tighten simultaneously. This dual-regulatory compression is forcing compounders to rebuild product portfolios around certified low-VOC formulations.
Growth Catalysts
- EU REACH substance restrictions:The regulation's phased limitations on phthalate plasticizers and heavy metal catalyst residues are pulling demand toward compliant TPO and TPU grades for consumer-contact applications.
- Automotive lightweighting mandates:OEMs in Stuttgart and Shanghai are substituting metal-rubber assemblies with thermoplastic vulcanizates in under-the-hood seals to meet fleet efficiency targets.
- East China petrochemical corridor concentration:Integrated polyether polyol operations in the Yangtze River Delta are compressing raw material logistics costs for regional TPU compounders.
Market Restraints
- Crude oil derivative volatility:Styrene and butadiene feedstock costs swing with naphtha cracking economics, squeezing margin predictability for SBC producers.
- US Gulf Coast polymer cluster concentration:Hurricane-disruption risk and pipeline bottlenecks around Houston create supply vulnerability for North American TPV and TPO grades.
- Metal-to-plastic substitution limits:Thermal resistance ceilings above 150°C prevent TPE penetration in high-temperature engine bay applications retained by fluoroelastomers.
Strategic Opportunities
- India automotive interior growth:BIS certification requirements for vehicle air quality are opening formulation approval slots for low-VOC TPO suppliers as domestic OEMs expand capacity.
- Bio-based feedstock certification:EU Green Deal procurement guidelines and Japan's METI resource circulation targets are creating premium price tiers for mass-balance certified TPE grades.
- Medical device catheter convergence:Biocompatibility certification under ISO 10993 and US FDA 21 CFR requirements is concentrating value pools for specialty TPU film and tubing producers.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel EU MDR, US FDA, and China NMPA biocompatibility testing extends product launch cycles for medical-grade TPU by 18-24 months.
- Post-industrial scrap recovery integration:Japan's extended producer responsibility schemes and EU CSRD reporting requirements are forcing compounders to rebuild compounding lines for recycled-content grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermoplastic Elastomers (TPE) Market |
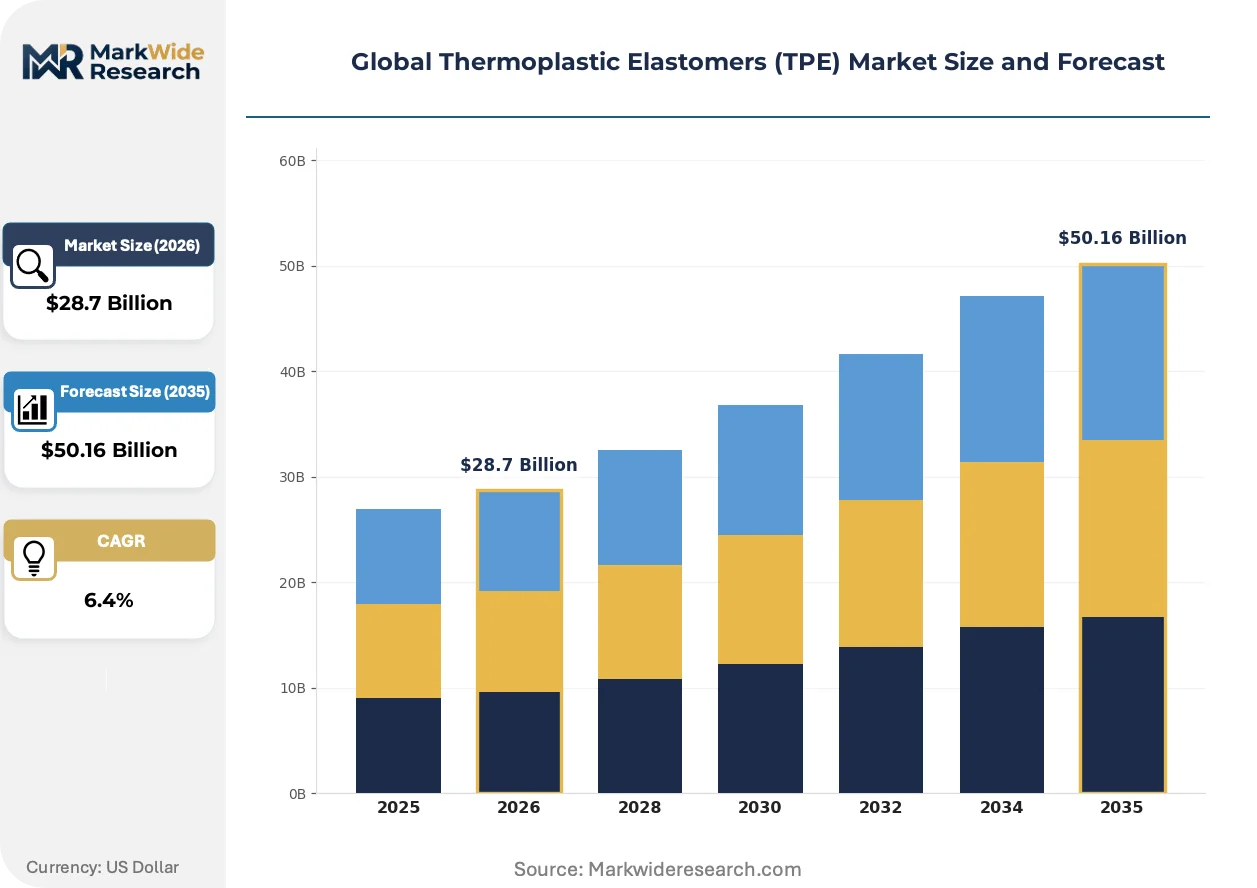
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SBC, TPO, TPU, TPV, Others Application: Footwear Components, Wire & Cable Insulation, Consumer Goods, Industrial Products, Sports Equipment End User: Electronics Manufacturers, Medical Device Makers, Construction Sector, Packaging Companies, Automotive OEMs Technology: Injection Molding, Extrusion, Blow Molding, Compression Molding, Calendering |
| Companies Covered | BASF SE, Kraton Corporation, Arkema SA, DuPont de Nemours, Inc., LG Chem Ltd., ExxonMobil Corporation, Covestro AG, Evonik Industries AG, LyondellBasell Industries Holdings B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermoplastic Elastomers (TPE) Market Shifts & Advancements
Formulation science is converging with process engineering as compounders engineer phase-separated block architectures that process on standard thermoplastic equipment while delivering vulcanizate-like performance. This technical trajectory is compressing the traditional divide between commodity and specialty grades.
Dynamic vulcanization technology is hybridizing rubber and thermoplastic phases at the molecular level to produce thermoplastic vulcanizates with compression set resistance below 35%. Automotive seal manufacturers in Wolfsburg and Detroit are adopting these grades for coolant system gaskets. The technology is hybridizing cost structures across the mid-performance elastomer segment, eroding the volume advantage of conventional EPDM in non-dynamic seals.
REACH Annex XVII expansions on intentionally added microplastics are forcing reformulation of TPE compounds containing synthetic polymer beads used for surface texture. Compounders serving European consumer goods brands are accelerating migration to mineral-based alternatives. Medical tubing and cosmetic packaging applications face the steepest compliance timelines, with ECHA guidance requiring substance notifications by 2027.
Automotive OEMs are consolidating approved supplier lists from twelve compounders per region to four with full formulation transparency and certified carbon footprint data. Tier-1 molders in Bavaria and Michigan are absorbing compounding capabilities in-house to secure supply continuity. This concentration is most visible in wire and cable insulation, where DuPont and BASF are capturing multi-year sole-source contracts through integrated material-plus-design service bundles.
Global Thermoplastic Elastomers (TPE) Market Segmentation
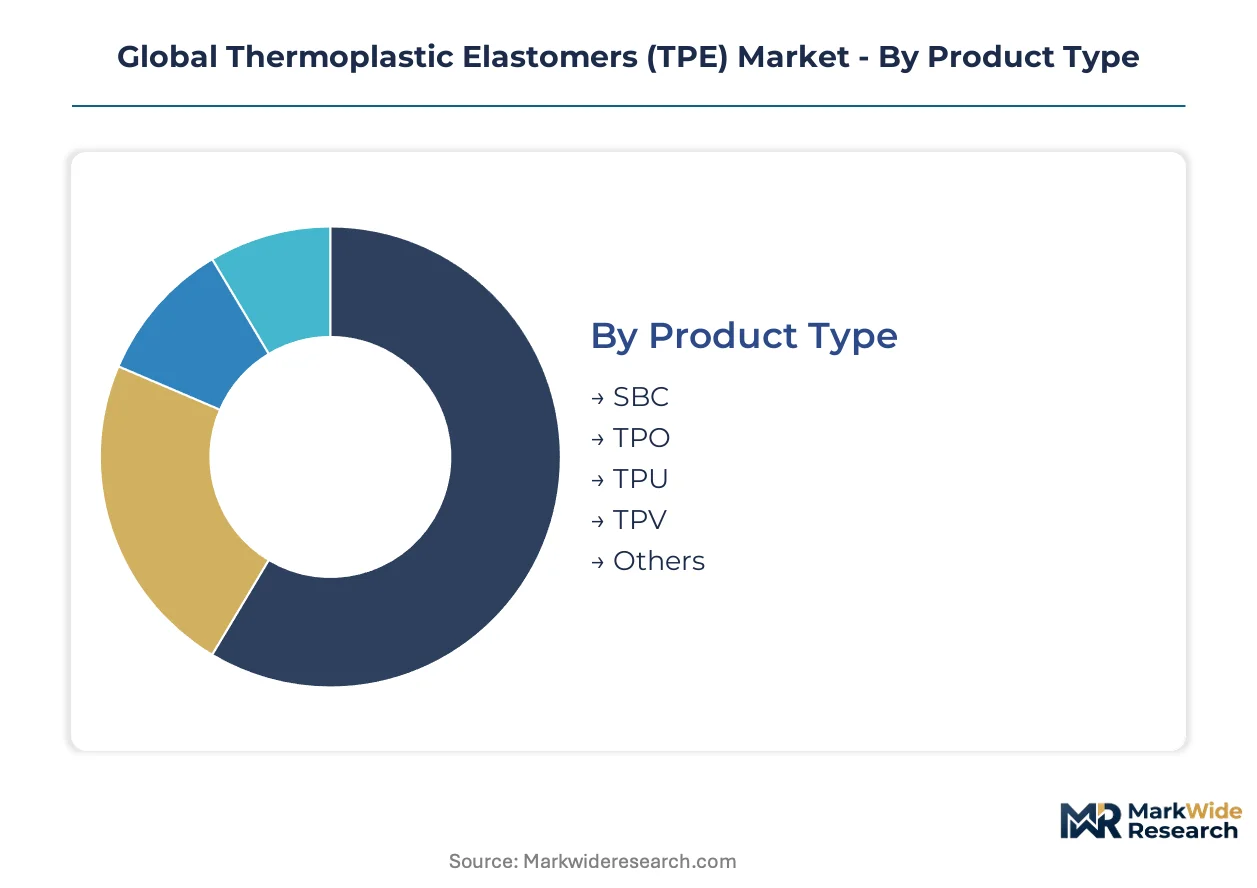
Segmentation reveals how TPE compounders allocate technical service resources across divergent processing requirements. Medical-grade TPU demands intensive regulatory support, while commodity SBC grades run on minimal intervention.
Product Type:
After-sales intensity escalates with formulation complexity and certification burden.
- SBC:Styrenic block copolymers feature hard polystyrene end-blocks and soft rubber mid-blocks that phase-separate without chemical crosslinking. Footwear sole manufacturers in Vietnam and Indonesia consume volume grades with Shore 40A-60A hardness ranges. Service needs concentrate on color-matching and melt-flow optimization for multi-component injection molding.
- TPO:Thermoplastic polyolefins blend EPDM rubber with polypropylene matrix polymers, offering density advantages over conventional vulcanizates. Automotive interior trim producers in Stuttgart and Shanghai drive specification evolution toward GB-standard-compliant low-VOC formulations. OEM approval cycles demand dedicated compounder technical teams for 18-month qualification protocols.
- TPU:Thermoplastic polyurethanes segment into polyester-based and polyether-based grades with Shore 70A-75D hardness spans. Medical catheter extruders require ISO 10993 biocompatibility dossiers and batch-level extractables testing.
- TPV:Thermoplastic vulcanizates achieve rubber-like compression set through dynamic vulcanization of EPDM in polypropylene matrices. Under-the-hood seal applications in Detroit and Wolfsburg specify coolant resistance and 150°C service ceilings.
- Others:Copolyester elastomers and polyamide-based TPEs occupy niche high-temperature wire insulation segments.
SBC holds the largest share; momentum sits with TPV as metal substitution accelerates in powertrain sealing.
Application:
Cost-tier stratification separates specification-grade medical and automotive applications from commodity consumer goods.
- Footwear Components:Midsole and outsole applications exploit SBC elasticity and abrasion resistance across injection-molded athletic and casual shoe platforms. Asian contract manufacturers in Dongguan and Ho Chi Minh City specify UV-stable grades for outdoor performance lines.
- Wire & Cable Insulation:Halogen-free TPU and copolyester grades achieve 105°C-125°C temperature ratings for data center power distribution. Compounders serving Bavarian automotive harness suppliers integrate flame-retardant packages meeting EN 50363 standards.
- Consumer Goods:Toothbrush grips, cosmetic packaging, and kitchen utensils leverage overmolding compatibility with polypropylene substrates. REACH Annex XVII microplastic restrictions are forcing texture-modifier substitutions in European-sourced compounds.
- Industrial Products:Conveyor belts, rollers, and vibration dampeners specify TPV grades for oil resistance and load-bearing capacity.
- Sports Equipment:Ski boot shells, bicycle grips, and fitness equipment padding demand cold-flex resistance down to minus 40°C.
Wire & cable insulation commands premium pricing; footwear components deliver volume scale.
End User:
Customer-type concentration determines whether compounders sell through distributors or direct technical account teams.
- Electronics Manufacturers:Smartphone and laptop producers specify ultra-soft TPE overmolds for ergonomic grips and drop protection. Dongguan and Shenzhen assembly plants prioritize just-in-time delivery and color consistency across million-unit production runs.
- Medical Device Makers:Catheter, tubing, and seal producers require US FDA 21 CFR master files and EU MDR technical documentation. Compounders maintain dedicated clean-compounding suites and extractables testing protocols for this segment.
- Construction Sector:Window gaskets, roofing membranes, and expansion joints specify UV-stable TPO grades with 20-year weathering warranties.
- Packaging Companies:Food-contact lid liners and dispensing valves demand FDA-compliant formulations with migration testing.
- Automotive OEMs:Interior, exterior, and under-the-hood applications consolidate approved supplier lists to four compounders per region with full formulation transparency.
Automotive OEMs concentrate procurement volumes; medical device makers generate the steepest expansion trajectory.
Technology:
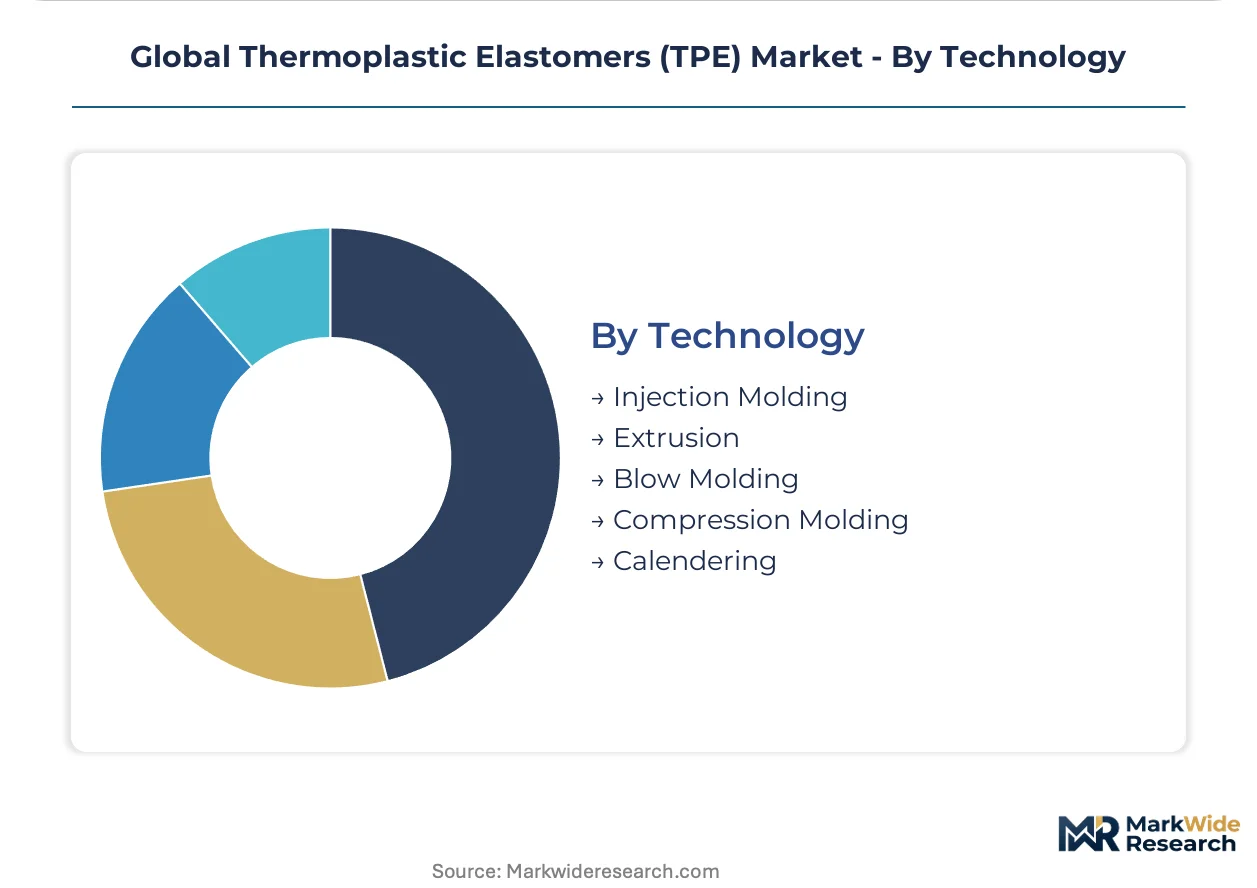
Processing-method selection correlates with part complexity and production scale economics.
- Injection Molding:Multi-cavity tooling for consumer goods and automotive interior components exploits TPE thermoplastic cycle times without post-curing. Machine suppliers in Nuremberg and Tokyo promote all-electric presses with 0.01mm repeatability for thin-wall medical applications.
- Extrusion:Continuous profile production dominates wire insulation, tubing, and weatherstrip manufacturing. TPV and TPU grades require screw designs with 24:1 L/D ratios and vacuum venting for moisture-sensitive polyether polyurethanes.
- Blow Molding:Hollow automotive ducts and consumer bottles leverage TPO parison stability and weld-line strength.
- Compression Molding:Large-format industrial pads and anti-vibration mounts process TPV preforms in heated platen presses.
- Calendering:Sheet production for roofing membranes and fabric lamination requires TPO grades with controlled melt strength across 2-meter widths.
Injection molding holds the largest share; extrusion gains share fastest through wire and cable infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH substance restrictions and China's GB standards for vehicle materials are redirecting formulation strategies toward halogen-free TPE grades. Automotive OEMs in Stuttgart and Shanghai are consolidating approved supplier lists to compounders with certified low-VOC portfolios. This dual-regulatory compression is reshaping regional competitive positioning.
United States
Automotive lightweighting mandates from the EPA and NHTSA are pulling demand toward thermoplastic vulcanizates in under-the-hood seals. The Clean Air Act Title V permitting framework regulates volatile organic compound emissions from TPE processing facilities around Houston. The US Gulf Coast polymer cluster concentrates TPV and TPO supply, though hurricane-disruption risk creates periodic supply vulnerability.
Germany
REACH Annex XVII expansions on intentionally added microplastics are forcing reformulation of TPE compounds containing synthetic polymer beads. The KBA enforces strict material compliance for automotive interior components. Bavarian Tier-1 molders are absorbing compounding capabilities in-house to secure supply continuity and meet OEM transparency requirements.
China
SAMR enforcement of GB standards for automotive interior air quality favors low-VOC TPO formulations for domestic OEM expansion. The MIIT promotes dual carbon goals that redirect investment toward energy-efficient compounding operations. East China's petrochemical corridor in the Yangtze River Delta compresses raw material logistics costs for regional TPU compounders.
Japan
METI resource circulation legislation establishes recycled-content targets affecting post-industrial TPE scrap recovery systems. The PMDA maintains stringent biocompatibility oversight for medical device applications. Kanto-based compounders are rebuilding production lines to handle certified mass-balance feedstocks for premium price tiers.
India
BIS certification requirements for vehicle air quality are opening formulation approval slots for low-VOC TPO suppliers as domestic OEMs expand capacity. The PLI scheme for automotive manufacturing incentivizes local sourcing of compliant materials. Maharashtra and Gujarat-based compounders are qualifying for direct supply relationships with expanding passenger vehicle producers.
Global Thermoplastic Elastomers (TPE) Market Competitive Landscape
On the supply side, the industry is consolidating around integrated petrochemical majors and specialty compounders with certified formulation portfolios. Tier-1 molders are absorbing compounding capabilities in-house, compressing the addressable market for independent suppliers. Three archetypes dominate: hydrogenated styrenic block copolymer specialists, integrated polyether polyol operators for TPU grades, and dynamic vulcanization technology leaders. Competitive moves center on multi-year sole-source contracts through material-plus-design service bundles and backward integration into captive polyol supply.
Within the integrated petrochemical tier, BASF SE anchors European supply through its Ludwigshafen operations. Kraton Corporation and DuPont de Nemours, Inc. occupy positions on the specialty vector, with the former representing hydrogenated styrenic block copolymer capabilities and the latter exemplifying specialty copolyester elastomer positioning for demanding thermal resistance applications. These three entities sit within distinct competitive spaces that resist direct overlap.
| Leading Market Players |
|---|
| BASF SE |
| Kraton Corporation |
| Arkema SA |
| DuPont de Nemours, Inc. |
| LG Chem Ltd. |
| ExxonMobil Corporation |
| Covestro AG |
| Evonik Industries AG |
| LyondellBasell Industries Holdings B.V. |
| Others |
Supply & Pricing Matrix
Yangtze River Delta freight corridors compress logistics costs for East China TPU compounders while amplifying price differentiation between certified medical grades and commodity automotive formulations. This logistics-cost asymmetry rewards integrated polyether polyol operators with margin capture unavailable to toll-dependent compounders serving price-sensitive footwear markets.
Pricing Analysis
Certification level creates the primary spread between ISO 10993-compliant medical TPU and standard automotive TPO grades. Three-tier pricing structure across premium, standard, and economy levels reflects biocompatibility dossier costs, with medical catheter extruders absorbing 40-60% premiums over wire insulation grades. Price erosion runs through commodity SBC footwear compounds as Vietnamese contract manufacturers consolidate procurement volumes. Electronics overmold buyers in Dongguan exhibit highest price sensitivity; medical device makers in Stuttgart and Boston demonstrate lowest.
Supply Chain Analysis
Styrene and butadiene feedstock costs swing with naphtha cracking economics across China, South Korea, and Germany. Raw material sourcing draws from integrated petrochemical complexes in Ludwigshafen and the US Gulf Coast, with polyether polyol supply anchored in BASF's captive operations. Single-source vulnerability concentrates around Houston pipeline bottlenecks and hurricane-disruption risk. Distribution runs through direct technical account teams for automotive OEMs and distributor networks for commodity footwear compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Thermoplastic Elastomers (TPE) Market operates as a regulatory-entrenchment story where REACH and GB-standard compliance timelines create switching costs that lock OEMs into approved supplier relationships. Multi-jurisdiction certification burdens extend product launch cycles, deepening moats for compounders with existing dossier libraries.
For Market Incumbents: Pre-empt emerging bio-based feedstock certification requirements by securing mass-balance chain-of-custody documentation ahead of EU Green Deal procurement guidelines. Absorb in-house compounding capabilities at Bavarian Tier-1 molders threatening direct supply relationships. Capacity addition in Maharashtra and Gujarat captures India PLI-scheme incentives before domestic compounders qualify for BIS-certified formulations.
For New Entrants and Emerging Players: Mid-market TPV suppliers in India's automotive interior segment represent the most penetrable entry point before BIS certification requirements harden. Toll-manufacturing arrangements with East China petrochemical corridor operators bypass capital-intensive compounding infrastructure. Target sole-source contract opportunities in wire and cable insulation where EN 50363 flame-retardant specification gaps persist among established players.
For Investors and Strategic Acquirers: Hydrogenated styrenic block copolymer specialists with medical tubing dossiers offer the strongest long-term viability through the projection horizon. Watch ECHA guidance on intentionally added microplastics as the inflection indicator for mineral-based texture-modifier substitution demand. Cross-checking against automotive OEM approved-supplier-list consolidation rates validates acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyether Polyol Supply | BASF's Ludwigshafen operations demonstrate margin capture unavailable to toll-dependent competitors. |
| Mass-Balance Certification Program | EU Green Deal procurement guidelines create premium price tiers for bio-based feedstock grades. |
| Long-term Supply Agreement with Automotive OEMs | Stuttgart and Shanghai OEMs consolidate to four compounders per region with full formulation transparency. |
| Joint Venture in East China Petrochemical Corridor | Yangtze River Delta concentration compresses logistics costs for regional TPU compounders. |
| Green Manufacturing Transition | MIIT dual carbon goals redirect investment toward energy-efficient compounding operations in China. |
Research Methodology
Desk research of customs/trade data, SEC 10-K filings, and ACC/Cefic industry reports preceded structured interviews with TPE plant managers, automotive OEM procurement leads, medical device regulatory affairs directors, and distribution channel partners. Bottom-up volume modeling across product type, application, and end-user segments triangulated against top-down macroeconomic indicators. Primary fieldwork validated formulation approval timelines and OEM supplier-list consolidation patterns.
Assumptions held fixed include REACH Annex XVII enforcement timelines and GB-standard compliance deadlines, while feedstock cost volatility and hurricane-disruption frequency were modeled as stochastic variables. Segmentation dimensions spanned grade tier, end-use industry, regional production hub, and certification level. CAGRs derived from regression analysis of historical volume trajectories adjusted for automotive lightweighting mandate intensity and medical device catheter demand convergence.
Practitioners should monitor ECHA microplastic restriction guidance and India BIS certification rollout pace for early signals of formulation strategy revision. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM supplier consolidation rates. Cross-checking against IHS Markit vehicle production databases and hospital procurement spend patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
North America Performance Elastomer Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Middle-East and Africa Fluoroelastomers Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Polysulfide Elastomers Market