
 North America Thermoplastic Elastomer (TPE) Market | 2026-2036
North America Thermoplastic Elastomer (TPE) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Thermoplastic Elastomer (TPE) Market Analytics
Modular material bundling is realigning how automotive and medical buyers configure TPE supply contracts. KRATON CORPORATION leverages its styrenic block copolymer technology leadership to anchor long-term agreements with tier-one automotive suppliers. BASF SE competes through backward integration into polyol feedstocks, sustaining margin stability across polyurethane elastomer grades. DuPont differentiates via fluoropolymer-modified TPE lines that occupy premium medical device segments requiring sterilization resistance.
Thermoplastic elastomers combine rubber-like elasticity with thermoplastic processability, enabling injection molding and extrusion without vulcanization curing cycles; Shore hardness ranges from 20A to 75D depending on block architecture and filler loading. The primary industrial purpose centers on replacing cross-linked rubber and flexible PVC in applications demanding recyclability, colorability, and reduced manufacturing cycle times. Styrenic block copolymers dominate volume due to mature supply infrastructure and cost positioning in footwear and consumer goods, while thermoplastic vulcanizates represent the fastest-expanding category as automakers pursue under-hood components requiring heat and fluid resistance. Thermoplastic polyurethanes command the deepest margin pools in medical catheter and wearable device applications where biocompatibility certification creates supply scarcity.
The U.S. EPA regulates volatile organic compound emissions from TPE processing facilities under Clean Air Act standards, pushing compounders toward aqueous-based dispersion technologies and enclosed venting systems. California's Department of Toxic Substances Control enforces Safer Consumer Products regulations that restrict phthalate plasticizers in flexible materials, directly redirecting formulation R&D toward non-phthalate TPE alternatives. Health Canada and PMRA coordinate with U.S. FDA on medical-grade TPE biocompatibility testing protocols, creating synchronized but distinct approval pathways for cross-border device manufacturers. Stakeholders must monitor evolving state-level extended producer responsibility frameworks that could impose recycled content thresholds on elastomer components sold into consumer and automotive channels.
Market Dynamics
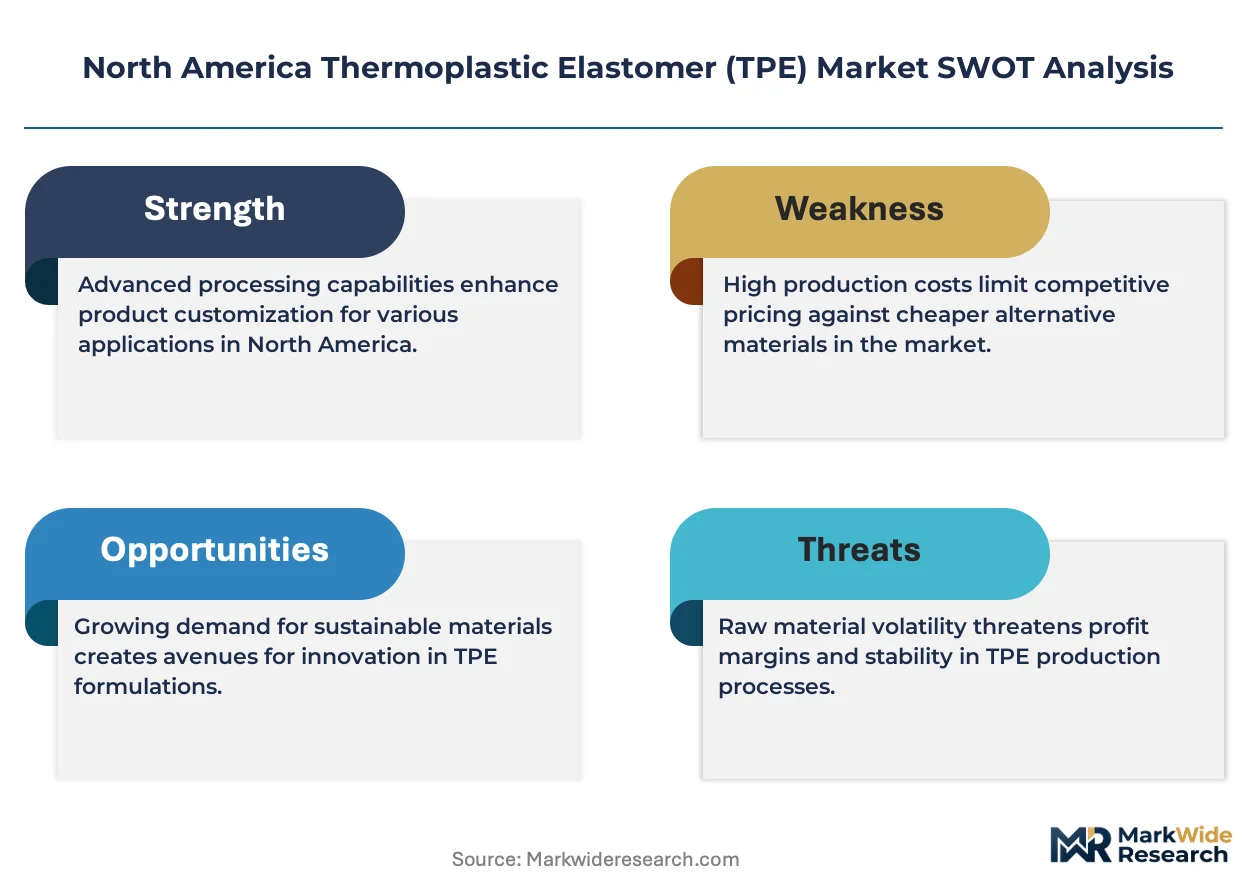
Automotive OEMs are systematically replacing vulcanized rubber with thermoplastic elastomers to meet U.S. EPA tailpipe emission standards and California's recycled content mandates, compressing material qualification cycles and rewiring supply relationships across the U.S. Gulf Coast petrochemical corridor.
Growth Catalysts
- State recycled content mandates:California's Department of Toxic Substances Control enforces Safer Consumer Products regulations that redirect formulation R&D toward non-phthalate TPE alternatives, opening substitution pathways in consumer goods.
- Automotive lightweighting protocols:OEMs expand TPE deployment in under-hood seals and interior components to satisfy Corporate Average Fuel Economy targets without sacrificing fluid resistance.
- Medical device sterilization requirements:Fluoropolymer-modified TPE lines capture premium catheter and wearable device segments where gamma and autoclave resistance creates supply scarcity.
Market Restraints
- Propylene feedstock volatility:Styrenic block copolymer producers face margin compression when Gulf Coast cracker operations experience unplanned outages or hurricane-related disruptions.
- Technical performance ceilings:Standard TPE grades fail to match thermoset rubber's compression set resistance above 150°C, limiting adoption in heavy-duty engine mounts and transmission seals.
- Cross-border certification friction:Health Canada and U.S. FDA maintain synchronized but distinct biocompatibility testing protocols for medical-grade TPE, extending approval timelines for cross-border device manufacturers.
Strategic Opportunities
- Texas-Louisiana compounding cluster expansion:Integrated polymer producers can anchor regional compounding operations to serve Midwest automotive assembly plants with shortened lead times.
- Extended producer responsibility frameworks:Emerging state-level recycled content thresholds for elastomer components sold into consumer channels create first-mover advantage for closed-loop material suppliers.
- 3D printing filament convergence:TPE-optimized fused deposition modeling materials enable medical device prototyping and low-volume production runs without tooling investment.
Industry Challenges
- Polymer science talent scarcity:Compounders struggle to recruit formulation chemists with expertise in block copolymer architecture and dynamic vulcanization process control.
- Multi-agency compliance timelines:Medical device manufacturers face 18-24 month certification cycles coordinating U.S. FDA biocompatibility submissions with state-level chemical disclosure requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Thermoplastic Elastomer (TPE) Market |
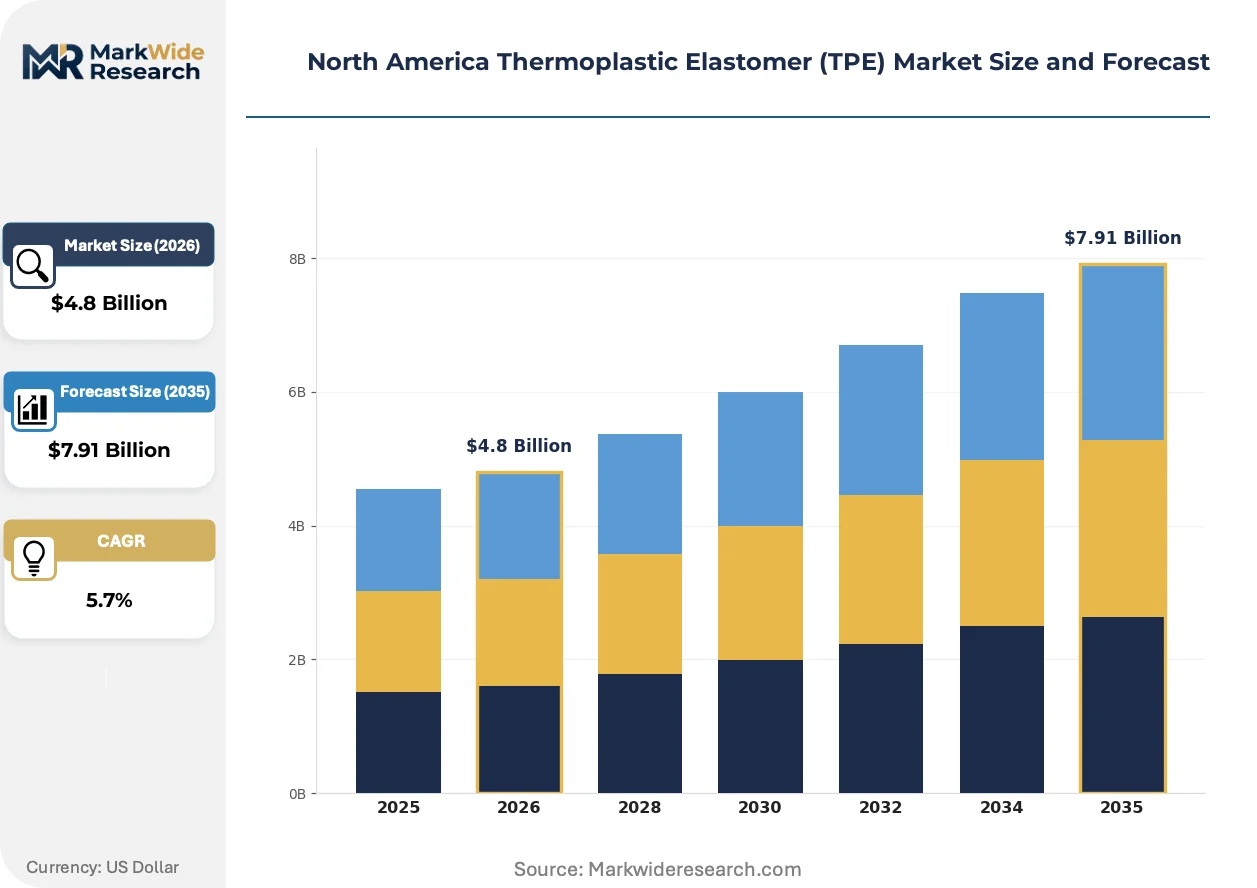
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrenic Block Copolymers, Thermoplastic Polyurethanes, Thermoplastic Vulcanizates, Others Application: Automotive Components, Medical Devices, Consumer Products, Industrial Applications End User: Manufacturers, Distributors, OEMs, Retailers Form: Sheets, Pellets, Granules, Films |
| Companies Covered | DuPont, BASF SE, Covestro AG, KRATON CORPORATION, Arkema, The Dow Chemical Company, Lubrizol Corporation, Avient Corporation, Teknor APEX Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Thermoplastic Elastomer (TPE) Market Evolving Landscape
Material science advances and regulatory pressure are converging to reshape how thermoplastic elastomers are formulated, processed, and specified across automotive and medical value chains.
Dynamic vulcanization technology is absorbing engineering-grade performance requirements previously reserved for thermoset rubber. Automotive under-hood applications adopt thermoplastic vulcanizates at accelerating rates as heat and fluid resistance specifications tighten. The technology is absorbing market share from ethylene propylene diene monomer rubber in coolant hose and air intake duct applications.
California's Safer Consumer Products regulations are forcing phthalate plasticizer elimination from flexible material formulations. Compounders redirect R&D investment toward bio-based plasticizers and hydrogenated styrenic block copolymers. Medical device and toy manufacturers in the Western U.S. are responding fastest, locking in multi-year supply contracts for certified non-phthalate TPE grades.
Buyers are consolidating supplier relationships around material bundling agreements that span multiple elastomer grades and technical service support. Tier-one automotive suppliers negotiate modular contracts covering styrenic block copolymers for interior soft-touch surfaces alongside thermoplastic polyurethanes for sealing applications. This pattern concentrates procurement decisions in Michigan and Ohio-based engineering centers where OEM material specification authority resides.
North America Thermoplastic Elastomer (TPE) Market Segmentation
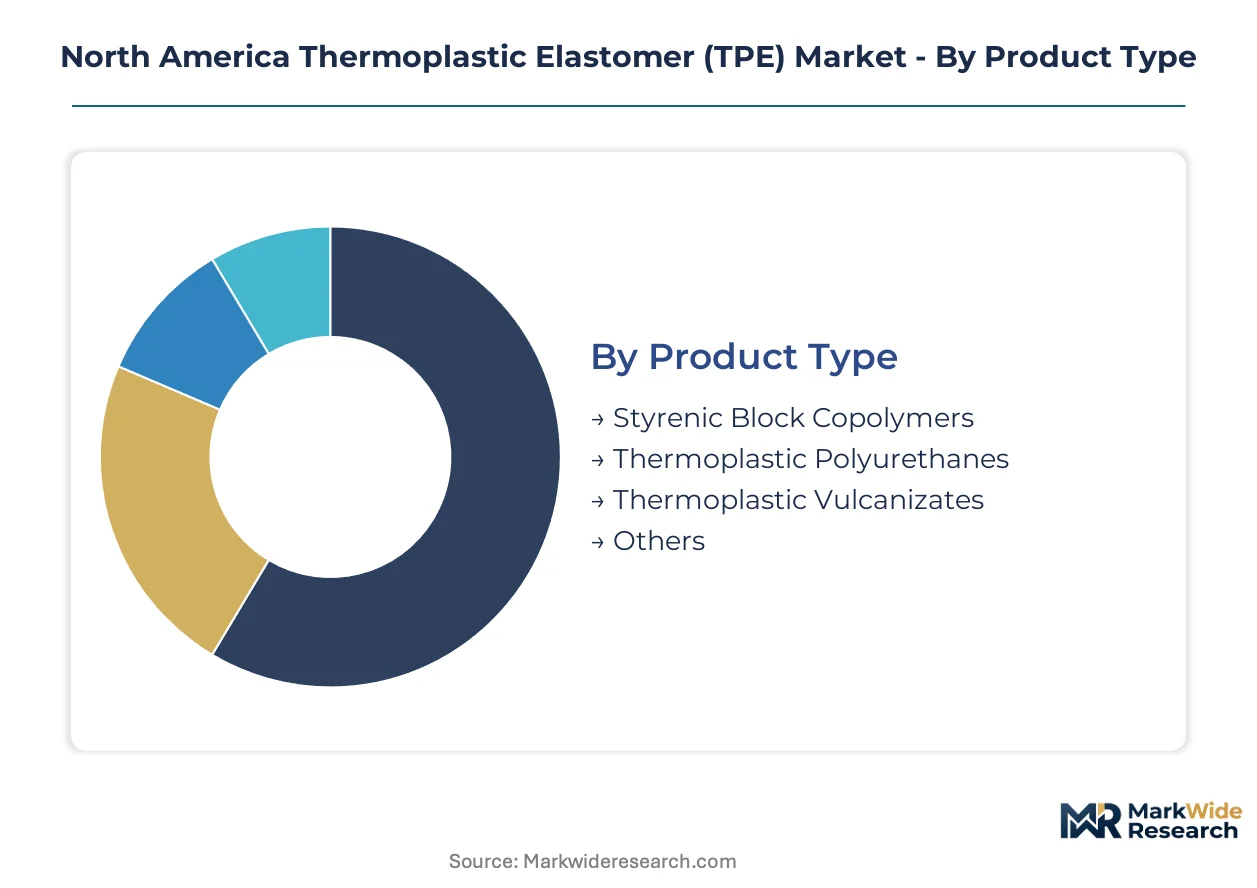
Segmentation in the North America TPE market reveals distinct capital requirements and margin profiles across product chemistry, application intensity, and supply chain position. Understanding these divisions enables suppliers to allocate technical resources and manufacturing assets against the highest-return opportunities.
Product Type:
Capital intensity varies sharply across polymerization chemistry, with hydrogenation reactors and dynamic vulcanization lines demanding the steepest upfront investment.
- Styrenic Block Copolymers:Hydrogenated and non-hydrogenated SBC grades rely on anionic polymerization in continuous stirred-tank reactor trains. U.S. Gulf Coast producers anchor supply for footwear and consumer goods compounders facing California's phthalate restrictions.
- Thermoplastic Vulcanizates:Dynamic vulcanization technology cross-links EPDM rubber within a polypropylene matrix during twin-screw extrusion. Automotive under-hood seals in Michigan and Ohio assembly corridors absorb expanding volume as heat resistance specifications tighten.
- Thermoplastic Polyurethanes:Reaction injection systems polymerize polyols with diisocyanates to yield Shore 70A-75D grades.
- Others:Copolyester and polyamide elastomer grades serve niche medical and industrial segments requiring chemical resistance.
Styrenic block copolymers absorb the bulk of installed capacity; thermoplastic vulcanizates are expanding most quickly.
Application:
Application segments diverge by qualification timeline and certification burden, with medical and automotive demanding the longest development cycles.
- Automotive Components:Under-hood seals, interior soft-touch surfaces, and air intake ducts specify TPV and TPU grades. OEMs in Detroit and Tennessee accelerate substitution away from vulcanized rubber to satisfy Corporate Average Fuel Economy targets.
- Medical Devices:Catheters, wearable patches, and drug delivery components require USP Class VI and ISO 10993 biocompatibility certification. Gamma and autoclave sterilization resistance favors fluoropolymer-modified TPE lines from specialized compounders.
- Consumer Products:Toy grips, sporting goods, and personal care items drive SBC consumption.
- Industrial Applications:Conveyor belts, hoses, and vibration dampeners specify TPU and TPV grades for abrasion resistance.
Automotive components command the deepest volume pools; medical devices generate the steepest margin premiums.
End User:
End-user categories reflect position in the value chain and corresponding technical service requirements.
- Manufacturers:Compounders and converters purchase base resins for in-house formulation and extrusion operations. Texas-Louisiana petrochemical corridor concentration enables just-in-time delivery to Midwest fabrication plants.
- Distributors:Regional warehouses stock standard grades for small-batch processors lacking direct supplier relationships.
- OEMs:Tier-one automotive and medical device assemblers negotiate direct supply agreements with formulation technical support.
- Retailers:Private-label consumer goods brands source certified non-phthalate TPE through distributor networks.
OEMs concentrate procurement authority; distributors serve fragmented processor demand.
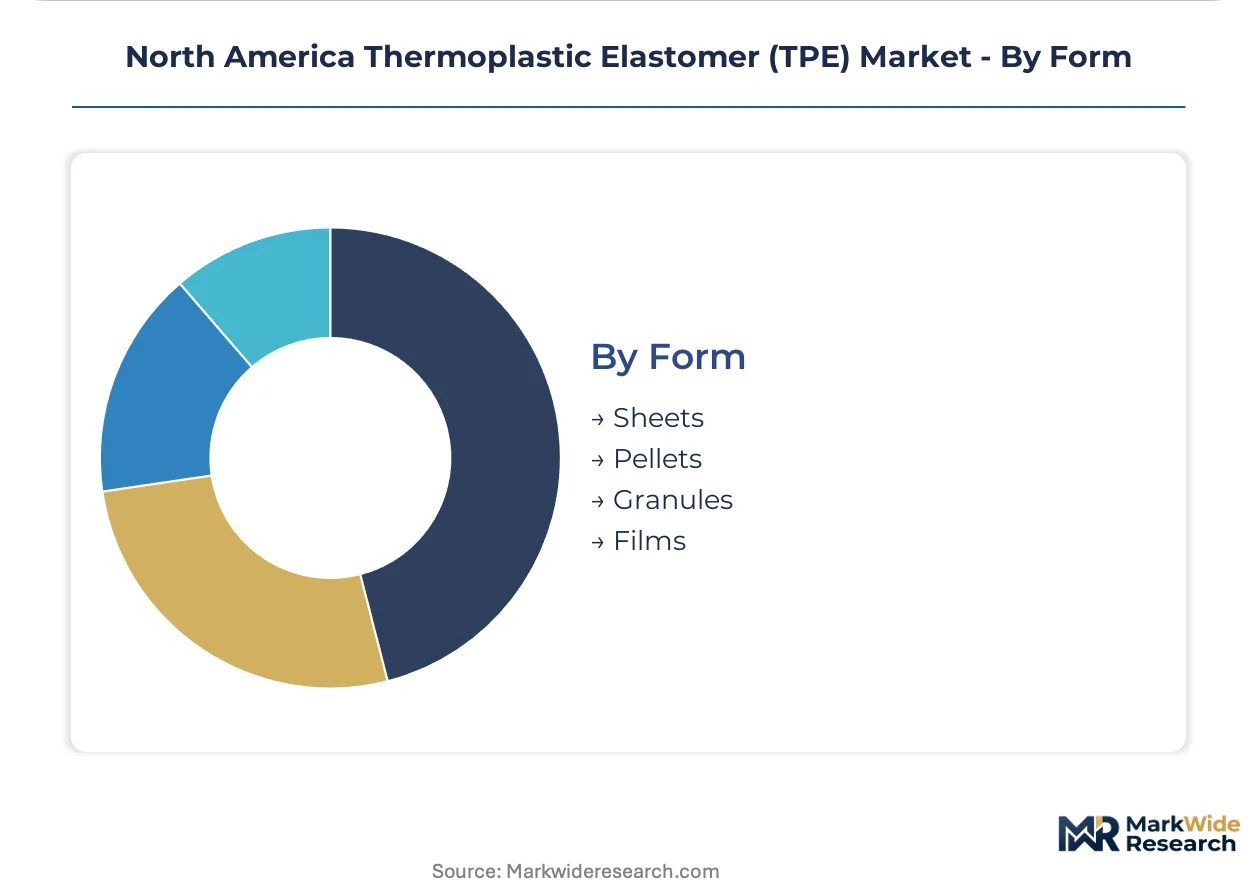
Form:
Physical form determines handling infrastructure and downstream processing compatibility.
- Pellets:Standard injection molding feedstock dominates volume through automated conveying systems.
- Granules:Larger particle size suits extrusion lines with gravimetric feeding equipment.
- Sheets:Calendered rolls serve thermoforming and die-cutting operations in medical device fabrication.
- Films:Thin-gauge extrusion enables flexible packaging and membrane applications.
Pellets move the highest tonnage; films claim the fastest expansion trajectory in wearable medical devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates along the U.S. Gulf Coast petrochemical corridor while consumption spreads across Midwest automotive assembly plants and Western medical device clusters. This geographic split creates logistics complexity and regional pricing differentials.
United States
Automotive OEMs in Michigan and Ohio specify TPV grades for under-hood seals to satisfy Corporate Average Fuel Economy targets. EPA tailpipe emission standards accelerate substitution away from vulcanized rubber. The Texas-Louisiana corridor hosts integrated polymer producers serving regional compounding operations with shortened lead times.
Canada
Medical device manufacturers in Ontario and Quebec demand USP Class VI certified TPE grades for catheter and wearable patch applications. Health Canada coordinates biocompatibility testing protocols with U.S. FDA, creating synchronized but distinct approval pathways. Toronto-area fabrication plants source base resins through cross-border distributor networks.
Mexico
Tier-one automotive suppliers in Nuevo León and Mexico City Metro expand TPE consumption for interior soft-touch components and sealing applications. The country's national automotive regulator enforces emission standards aligned with U.S. EPA frameworks. Querétaro's aerospace cluster generates niche demand for high-performance elastomer grades.
North America Thermoplastic Elastomer (TPE) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology vectors. The vendor base organizes around three strategic archetypes: integrated petrochemical giants with captive feedstock positions, specialty chemical houses with formulation expertise, and regional compounders with technical service proximity. Dominant competitive moves include backward integration into polyol feedstocks and long-term supply agreements anchoring tier-one automotive relationships.
Among the integrated chemical majors, BASF SE and Covestro AG exemplify scale-driven positions with upstream control over critical raw material streams. KRATON CORPORATION occupies a specialist position anchored in styrenic block copolymer technology leadership. DuPont represents the premium-tier vector through fluoropolymer-modified product lines serving sterilization-resistant medical applications.
| Leading Market Players |
|---|
| DuPont |
| BASF SE |
| Covestro AG |
| KRATON CORPORATION |
| Arkema |
| The Dow Chemical Company |
| Lubrizol Corporation |
| Avient Corporation |
| Teknor APEX Company |
| Others |
Value Network & Pricing Analysis
Tier-one automotive suppliers in Michigan and Ohio concentrate procurement authority for TPE grades, anchoring contract-based long-term offtake agreements that lock in volume commitments against feedstock volatility. This buyer concentration compresses margin buffers for compounders serving smaller medical device and consumer goods accounts.
Pricing Analysis
Cost-down pressure on standard SBC grades accelerates because Gulf Coast propylene outages force spot market exposure. Three-tier pricing structure across medical-certified, automotive-specified, and general industrial levels separates USP Class VI biocompatibility premiums from commodity footwear grades. Price differentiation hinges on hydrogenation reactor access and California phthalate-free certification. Medical device manufacturers show lowest price sensitivity; consumer goods compounders face relentless substitution threats from flexible PVC.
Supply Chain Analysis
Post-industrial regrind flows from Midwest automotive stamping operations feed closed-loop compounding lines in the Texas-Louisiana corridor. Raw material sourcing draws from U.S. Gulf Coast ethylene crackers, Canadian oil sands diluent streams, and imported Asian polyol specialties. Single-source vulnerability concentrates in hydrogenation catalyst supply from German specialty chemical houses. Distribution runs through regional distributor networks stocking standard grades for fragmented processors lacking direct supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America TPE market is consolidating around backward integration into polyol feedstocks and captive hydrogenation capacity, with players racing to secure margin stability against Gulf Coast petrochemical volatility.
For Market Incumbents: Deploy long-term supply agreements with tier-one automotive OEMs to lock in volume commitments before qualification cycles compress further. Anchor regional compounding assets in the Texas-Louisiana corridor to shorten lead times to Midwest assembly plants. Counter emerging bio-based TPE entrants by accelerating non-phthalate certification pipelines ahead of California mandate expansion. For New Entrants and Emerging Players: Direct-to-compounder digital platforms enable bypass of established distributor markups in fragmented medical device and consumer goods segments. Target Ontario and Quebec catheter manufacturers seeking secondary USP Class VI qualified suppliers to reduce sole-source risk. Lead with rapid prototyping services using TPE-optimized 3D printing filaments to capture low-volume medical device development contracts. For Investors and Strategic Acquirers: The window for entry favors hydrogenation technology specialists with dynamic vulcanization process control expertise. Mid-cap compounders holding California Safer Consumer Products pre-certifications command scarcity premiums as phthalate deadlines tighten. Monitor EPA enforcement actions on Gulf Coast VOC emissions as early signal for aqueous dispersion technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Feedstocks | BASF SE's captive supply of polyurethane precursors insulates margin stability against Asian import volatility. |
| Dynamic Vulcanization Capacity Expansion | Twin-screw extrusion lines in Ohio serve Detroit OEMs accelerating EPDM replacement in under-hood seals. |
| Non-Phthalate Certification Pipeline | California DTSC compliance pre-qualification locks in multi-year toy and personal care supply contracts. |
| Regional Compounding Cluster Anchoring | Texas-Louisiana just-in-time delivery networks compress inventory carrying costs for Midwest automotive fabricators. |
| Medical-Grade Biocompatibility Investment | USP Class VI and ISO 10993 certification creates supply scarcity capturing premium catheter and wearable device segments. |
Research Methodology
Trade databases, SEC 10-K filings, and American Chemistry Council industry reports formed the secondary backbone, cross-referenced with primary interviews conducted among polymer plant managers, Tier 1 automotive procurement leads, medical device regulatory affairs directors, and regional distribution channel partners. Bottom-up volume estimates derived from production capacity utilization rates and end-use consumption patterns were triangulated against top-down macroeconomic elasticity models.
Bottom-up modeling segmented the market by polymer chemistry type, application intensity, and end-user procurement authority, while top-down approaches validated aggregate value against petrochemical derivative demand correlations. CAGRs across the projection horizon were derived from regression analysis of historical substitution rates between TPE grades and incumbent materials. Forecast inputs incorporated EPA tailpipe emission stringency indices and California recycled content mandate phase-in schedules.
The model holds under stable propylene feedstock pricing and continued automotive lightweighting protocol enforcement; deviation in hurricane-related Gulf Coast cracker outages or federal emission standard rollbacks would shift volume trajectories. Practitioners should monitor Health Canada biocompatibility protocol harmonization progress and state-level extended producer responsibility framework adoption for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
High Temperature Elastomers Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Water Soluble Elastomers Market