
 Shape Memory Polymer Market | 2026-2036
Shape Memory Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Shape Memory Polymer Market Analysis
A shift from single-source to multi-source polymer procurement is restructuring supply relationships across the shape memory polymer value chain. BASF SE leverages its integrated polyurethane platform to secure precursor access for thermoplastic SMP grades. Evonik Industries AG anchors its position through high-purity specialty monomer production for medical-grade formulations. Covestro AG competes by extending its polycarbonate expertise into shape-memory copolymer architectures.
Shape memory polymers are stimuli-responsive materials capable of recovering a programmed permanent shape from a temporary deformed state upon exposure to heat, light, or magnetic fields, with transition temperatures typically engineered between 20°C and 100°C depending on crosslink density and monomer selection. These materials serve primarily as lightweight alternatives to mechanical actuators and metallic shape memory alloys in applications demanding programmable deformation cycles. Thermoplastic variants dominate current volume owing to reprocessability and weldability advantages in automotive and robotics assembly workflows, while biodegradable grades represent the fastest-expanding margin pool as healthcare providers seek implantable devices that eliminate secondary removal surgeries. Self-healing functionality commands premium positioning among aerospace end users seeking autonomous damage repair in composite laminates.
FDA clearance pathways for implantable SMP devices and REACH substance restrictions on isocyanate precursors jointly elevate compliance costs for market entrants lacking established regulatory dossiers. The EU Medical Device Regulation (MDR) reclassification of active implantable polymers intensifies clinical evidence requirements for European healthcare applications. Stakeholders must monitor evolving biodegradability certification standards and dual-use export controls on smart material technologies.
Market Dynamics
Multi-source procurement strategies are restructuring supply relationships across the shape memory polymer value chain as aerospace OEMs and medical device manufacturers seek to de-risk critical material dependencies. This shift is compressing traditional single-source contracts and forcing suppliers to demonstrate traceability compliance under tightening regulatory frameworks.
Growth Catalysts
- EU Green Deal material mandates:The EU Green Deal and REACH compliance frameworks are tightening material traceability requirements, creating pull for certified biodegradable SMP grades in medical and automotive applications.
- Smart actuation in aerospace:Aerospace manufacturers are expanding procurement of lightweight smart actuation components that replace mechanical systems in satellite deployment mechanisms and morphing wing structures.
- German industrial clustering:Automotive OEMs and medical device clusters in Germany are driving specialized thermoplastic consumption through proximity-based supplier relationships and shared R&D infrastructure.
Market Restraints
- Isocyanate precursor restrictions:REACH substance restrictions on isocyanate precursors elevate compliance costs for polyurethane-based SMP formulations, particularly affecting small-scale entrants lacking established regulatory dossiers.
- Specialty monomer supply concentration:High-purity specialty monomer production for medical-grade formulations remains concentrated among integrated chemical producers, creating bottleneck risks for qualified supply.
- Metallic shape memory alloy substitution:Nickel-titanium alloys continue to dominate high-force actuation applications where SMP load-bearing limitations prevent displacement, constraining addressable market expansion.
Strategic Opportunities
- Biodegradable implantable devices:Healthcare providers are seeking implantable devices that eliminate secondary removal surgeries, opening premium positioning for resorbable SMP formulations in cardiovascular and orthopedic applications.
- Self-healing aerospace composites:Autonomous damage repair functionality in composite laminates commands premium positioning among satellite and unmanned aerial vehicle manufacturers seeking extended mission durability.
- EU MDR reclassification tailwinds:The EU Medical Device Regulation reclassification of active implantable polymers intensifies clinical evidence requirements, favoring established suppliers with dossier capabilities over new entrants.
Industry Challenges
- FDA clearance pathway complexity:FDA clearance pathways for implantable SMP devices demand extensive biocompatibility testing and clinical validation timelines that strain development budgets and delay revenue recognition.
- Dual-use export control navigation:Smart material technologies face evolving dual-use export controls that complicate cross-border collaboration and limit access to defense-adjacent aerospace applications.
- Biodegradability certification standardization:Fragmented biodegradability certification standards across jurisdictions create compliance duplication costs and delay product launches in multi-regional healthcare markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shape Memory Polymer Market |
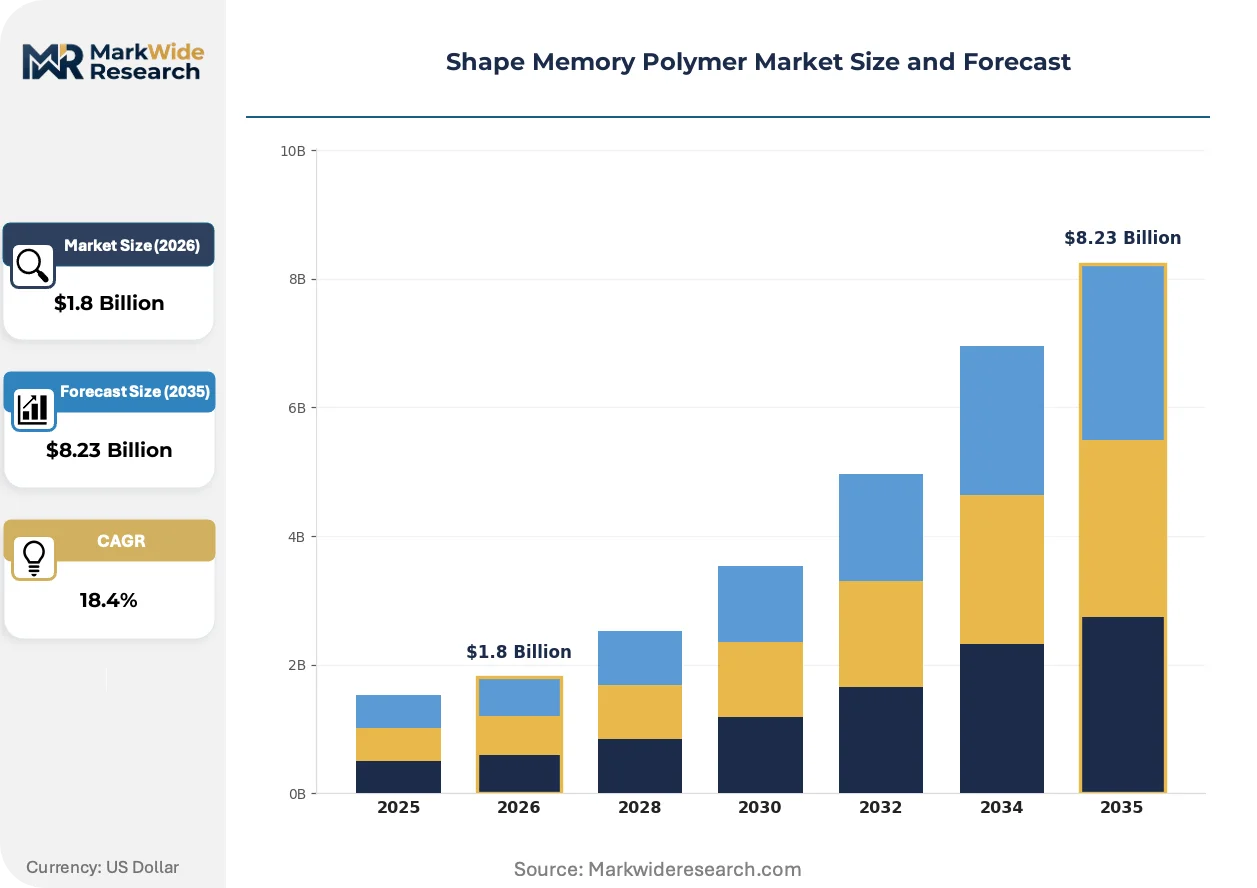
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Thermosetting, Biodegradable, Conductive Application: Aerospace, Healthcare, Automotive, Robotics End User: Manufacturers, Research Institutions, Healthcare Providers, Automotive OEMs Functionality: Self-Healing, Actuation, Shape Recovery, Smart Coating |
| Companies Covered | DuPont de Nemours Inc., Lubrizol Corporation, SMP Technologies Inc., Huntsman International LLC, Evonik Industries AG, BASF SE, Shape Memory Medical Inc., 3M Company, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shape Memory Polymer Market Emerging Trajectories
Programmable material architectures are absorbing capital and engineering talent as manufacturers seek to differentiate beyond commodity polymer offerings. Three convergent developments are restructuring competitive positioning and value capture mechanisms.
4D printing of shape memory polymers is absorbing development resources from traditional injection molding workflows. Aerospace prototyping labs and medical device foundries are adopting direct-ink-write and stereolithography methods to produce patient-specific implants and mission-adaptive satellite components. This technology is absorbing market share from conventional subtractive manufacturing by enabling geometric complexity impossible through molding, though throughput limitations constrain volume applications.
REACH authorization requirements for diisocyanates are forcing reformulation investments across polyurethane SMP suppliers. The industrial consequence is accelerated migration toward non-isocyanate polyurethane chemistries and thermoplastic alternatives that bypass restricted substance lists. Medical-grade formulation producers in Germany and the Netherlands are most affected, responding by locking in multi-year precursor supply agreements and accelerating bio-based feedstock qualification programs.
Outcome-based material service contracts are displacing traditional resin-by-kilogram transactions in automotive tier-one supply chains. German OEMs are piloting fixed-price deformation-cycle guarantees that transfer performance risk to material suppliers and align incentives around durability metrics. This shift is most visible in Stuttgart and Munich manufacturing corridors, where robotics assembly workflow integration demands predictable shape-recovery performance over million-cycle lifetimes.
Shape Memory Polymer Market Segmentation
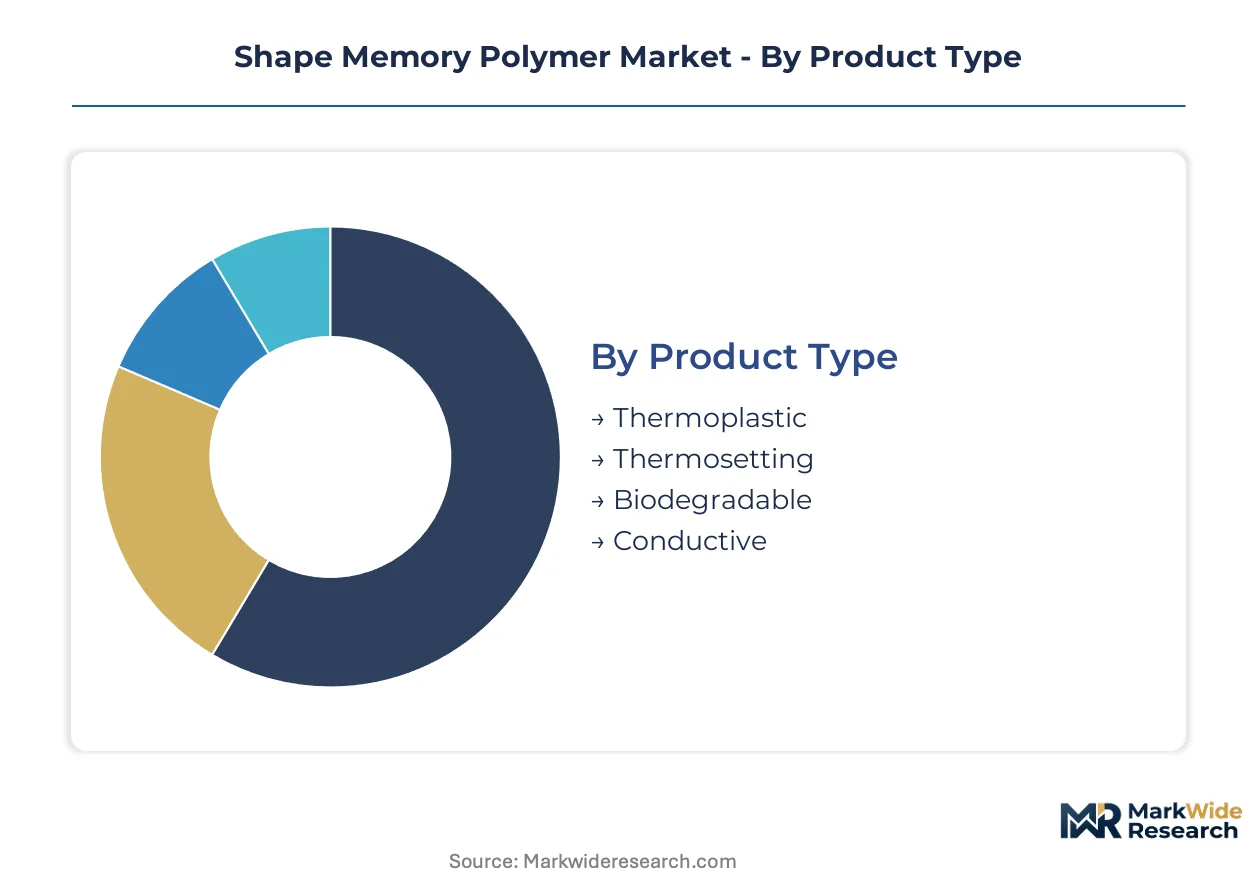
Segmentation in the shape memory polymer market reveals how regulatory burdens concentrate in medical and aerospace verticals while automotive and robotics applications face different qualification hurdles. Understanding these divides enables suppliers to prioritize R&D spending and certification investments against addressable margin pools.
Product Type:
FDA and EMA pathways impose divergent testing protocols across product categories, with implantable grades demanding biocompatibility dossiers that thermoplastic variants for automotive rarely require.
- Thermoplastic:Reprocessable polymers with weldability advantages dominate automotive assembly workflows and robotics integration. German OEMs in Stuttgart and Munich corridors drive procurement through million-cycle durability guarantees and proximity-based supplier relationships.
- Biodegradable:Resorbable formulations eliminate secondary removal surgeries in cardiovascular and orthopedic implants. Healthcare providers in Germany and the Netherlands seek these grades as REACH authorization pressures mount on permanent implant chemistries.
- Thermosetting:Crosslinked architectures deliver dimensional stability for high-temperature aerospace actuation components.
- Conductive:Electrically responsive grades enable magnetic-field-triggered shape recovery in satellite deployment mechanisms.
Leading the category by volume: Thermoplastic. Growing fastest: Biodegradable.
Application:
End-use concentration determines whether suppliers compete on price-per-kilogram or outcome-based performance contracts.
- Aerospace:Smart actuation components replace mechanical systems in satellite deployment and morphing wing structures. Manufacturers face dual-use export controls that complicate cross-border collaboration on defense-adjacent programs.
- Healthcare:Implantable devices and surgical tools demand FDA 510(k) or PMA pathways plus EU MDR clinical evidence. German medical device clusters absorb premium grades through shared R&D infrastructure and proximity to specialty monomer suppliers.
- Automotive:Lightweight actuators and assembly fixtures compete against metallic shape memory alloys on cost-per-cycle metrics.
- Robotics:Programmable deformation cycles enable adaptive grippers and compliant mechanisms in automated production lines.
Highest certification barrier: Healthcare. Steepest expansion trajectory: Aerospace.
End User:
Procurement sophistication varies sharply between volume buyers and specification developers.
- Automotive OEMs:German manufacturers pilot fixed-price deformation-cycle guarantees that transfer performance risk to material suppliers. These contracts demand predictable shape-recovery over million-cycle lifetimes and integrate directly into robotics assembly workflows.
- Healthcare Providers:Hospital systems and surgical networks seek implantable devices with elimination of secondary removal surgeries. EU MDR reclassification intensifies clinical evidence requirements, favoring established suppliers with dossier capabilities.
- Manufacturers:Tier-one and tier-two suppliers convert raw SMP grades into finished components across multiple end-markets.
- Research Institutions:Universities and national labs drive 4D printing method development and next-generation formulation discovery.
Most demanding contracting terms: Automotive OEMs. Fastest adoption of outcome-based pricing: Healthcare Providers.
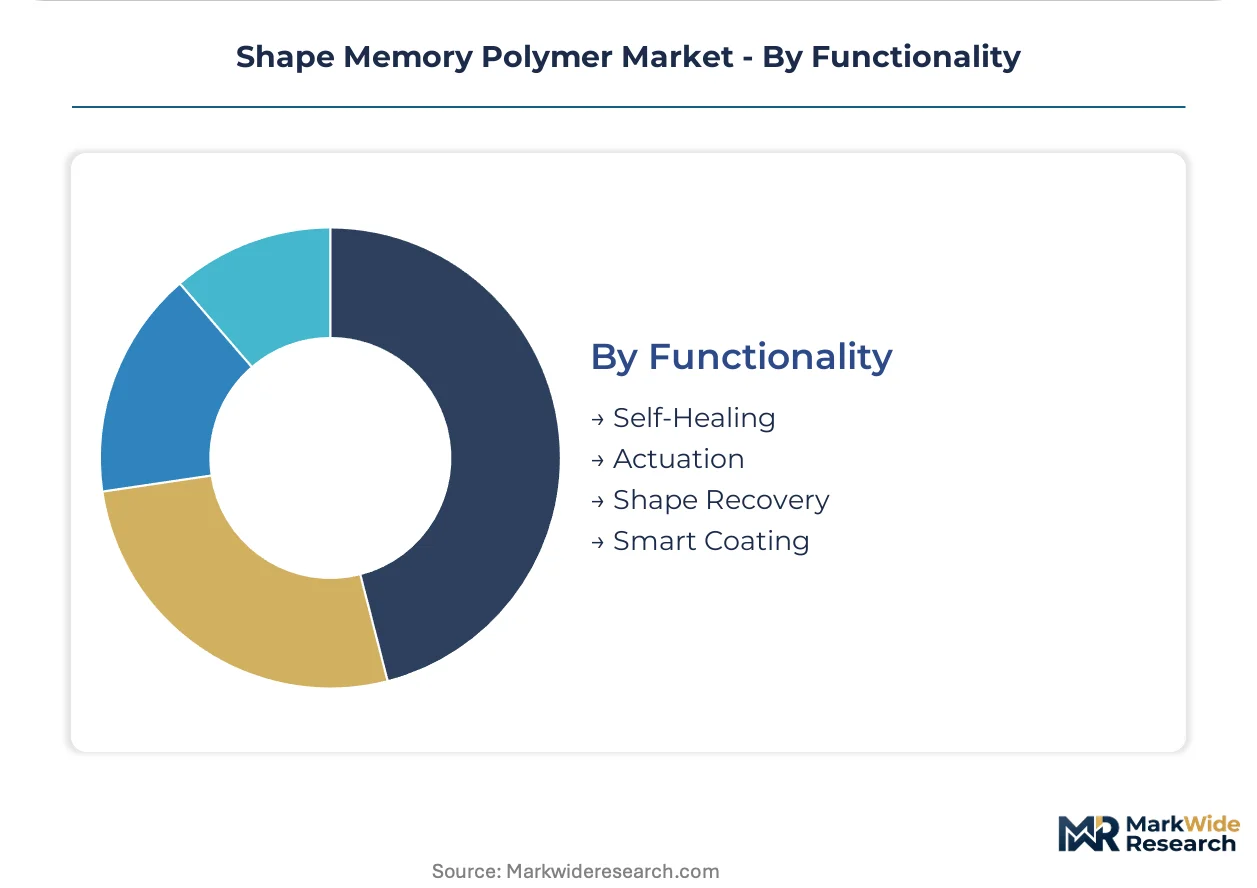
Functionality:
Performance-tier differentiation separates commodity offerings from premium positioning.
- Actuation:Programmable force and displacement outputs replace traditional mechanical actuators in weight-critical applications. Aerospace manufacturers expand procurement for satellite deployment mechanisms where gram-scale savings translate to launch cost reductions.
- Self-Healing:Autonomous damage repair in composite laminates commands premium positioning among unmanned aerial vehicle and satellite manufacturers seeking extended mission durability without maintenance access.
- Shape Recovery:Temperature-triggered return to permanent geometry serves as the baseline functionality across consumer and industrial applications.
- Smart Coating:Surface-integrated SMP layers enable adaptive aerodynamics and thermal management in specialized aerospace structures.
Widest addressable base: Shape Recovery. Highest margin capture: Self-Healing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty monomer production concentrates in Germany's industrial corridor, anchoring European supply for medical-grade formulations. German automotive OEMs and medical device clusters drive thermoplastic consumption through proximity-based procurement. REACH authorization pressures on isocyanate precursors are accelerating bio-based feedstock qualification programs across the continent.
United States
FDA clearance pathways for implantable devices attract venture-backed SMP developers to Boston and San Francisco biotechnology corridors. The EPA maintains oversight of industrial chemical precursors while NASA and DARPA fund smart actuation research for satellite deployment. Aerospace prototyping labs in Southern California adopt 4D printing methods for mission-adaptive components.
Germany
Automotive OEMs in Stuttgart and Munich pilot fixed-price deformation-cycle guarantees that transfer performance risk to material suppliers. ECHA REACH restrictions on diisocyanates force reformulation investments among polyurethane SMP producers. The Baden-Württemberg medical device cluster absorbs premium grades through shared R&D infrastructure with specialty monomer suppliers.
China
MIIT industrial policy directs capital toward advanced polymer capabilities including stimuli-responsive materials for robotics integration. SAMR oversees quality certification for medical-grade imports while domestic producers scale thermoplastic output for automotive assembly. Yangtze River Delta manufacturing hubs concentrate volume production for export-oriented robotics tier-one suppliers.
Japan
METI funding programs support next-generation actuator development for aging-population healthcare applications. PMDA regulatory frameworks govern implantable device approvals with stringent biocompatibility requirements. Osaka-based chemical producers leverage existing polyurethane expertise to enter medical-grade SMP formulation.
Netherlands
Eindhoven Region polymer research institutes collaborate with German automotive supply chains on million-cycle durability testing. ECHA headquarters proximity accelerates compliance adaptation for REACH-authorized precursor alternatives. Rotterdam logistics infrastructure enables just-in-time delivery of specialty monomers to medical device manufacturers.
Shape Memory Polymer Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated chemical producers scale specialty monomer output for medical-grade applications. The vendor base separates into three tiers: multinational diversified chemical conglomerates with captive precursor supply, mid-scale polymer specialists focused on thermoplastic formulations, and venture-backed device developers commercializing implantable applications. Strategic differentiation runs through regulatory dossier capabilities and multi-year supply agreements with automotive OEMs. M&A activity concentrates on acquiring FDA-cleared product pipelines and securing REACH-compliant precursor access.
Within the integrated chemical tier, BASF SE, Covestro AG, and Evonik Industries AG exemplify divergent strategic anchors. BASF leverages its Ludwigshafen polyurethane platform to secure backward control over thermoplastic SMP feedstocks. Covestro extends polycarbonate expertise into shape-memory copolymer architectures for automotive and electronics applications. Evonik occupies a position defined by high-purity specialty monomer production for medical-grade formulations requiring EMA and FDA compliance dossiers.
| Leading Market Players |
|---|
| DuPont de Nemours Inc. |
| Lubrizol Corporation |
| SMP Technologies Inc. |
| Huntsman International LLC |
| Evonik Industries AG |
| BASF SE |
| Shape Memory Medical Inc. |
| 3M Company |
| Covestro AG |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal material mandates gate both qualified supply and premium-tier pricing access, as REACH-compliant biodegradable grades command substantial markups over conventional thermoplastic formulations while excluding uncertified producers from German automotive and Dutch medical device procurement channels.
Pricing Analysis
Warranty and deformation-cycle guarantee bundling separates premium SMP suppliers from commodity resin vendors. Automotive OEMs in Stuttgart and Munich corridors negotiate fixed-price million-cycle performance contracts that transfer durability risk to material suppliers, while unbundled transactional kilogram pricing persists in standard thermoplastic grades. Price differentiation hinges on FDA/EMA certification tier and volume scale, with certified medical-grade formulations capturing substantial premiums. Cost compression in commodity thermoplastics is intensifying as Chinese producers scale output for robotics applications. Tier-one automotive buyers exhibit lowest price sensitivity due to integration complexity, whereas research institutions and prototyping labs face acute budget constraints.
Supply Chain Analysis
Reverse logistics for expired medical-grade SMP batches and aerospace component refurbishment flows remain underdeveloped, creating disposal cost burdens for healthcare providers and satellite manufacturers. Specialty monomer production concentrates in Germany, the Netherlands, and Japan, with Ludwigshafen and Eindhoven corridors anchoring European supply. Raw material dependencies center on high-purity diisocyanates, polycarbonate precursors, and bio-based feedstocks. Single-source vulnerability in medical-grade monomer supply elevates risk for qualified formulation producers. Distribution runs through just-in-time pipelines to Baden-Württemberg automotive clusters and Rotterdam-port-linked medical device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shape memory polymer market sits in a technology-transition phase as 4D printing methods displace conventional injection molding workflows for patient-specific implants and mission-adaptive aerospace components.
For Market Incumbents: Deepen backward integration into specialty monomer production to secure REACH-compliant precursor access against diisocyanate authorization pressures. Lock multi-year deformation-cycle guarantee contracts with German automotive OEMs before Chinese thermoplastic producers achieve qualification. Prioritize FDA 510(k) pathway investments to defend medical-grade positioning against venture-backed device developers. For New Entrants and Emerging Players: 4D printing capability for patient-specific cardiovascular implants offers the most penetrable wedge into healthcare applications, as established chemical conglomerates lack direct digital manufacturing expertise. Target Dutch medical device clusters through Eindhoven Region polymer research institute partnerships for shared R&D infrastructure access. Pursue outcome-based pricing pilots with hospital systems seeking elimination of secondary removal surgeries. For Investors and Strategic Acquirers: FDA clearance of a resorbable SMP cardiovascular stent is the leading indicator that clinical validation barriers are falling and premium pricing power is consolidating. Frame long-term viability around 5-10 year regulatory dossier moats rather than raw material cost advantages. Monitor ECHA REACH authorization timeline acceleration for diisocyanate precursors as the critical supply-side inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomers | Secures REACH-compliant precursor supply against ECHA diisocyanate authorization pressures. |
| 4D Printing Platform Development | Enables patient-specific implant geometries impossible through conventional injection molding workflows. |
| FDA 510(k) Clearance Pathway Investment | Builds regulatory dossier moats that exclude unqualified entrants from premium medical-grade segments. |
| Fixed-Price Deformation-Cycle Contracts | Aligns supplier incentives with German automotive OEM million-cycle durability requirements. |
| Bio-Based Feedstock Qualification Programs | Anticipates EU Green Deal mandates while reducing dependency on restricted petrochemical precursors. |
Methodological Framework
Multi-period observation of EMA approval timelines, REACH authorization registrations, and automotive OEM procurement contract structures anchored the trend analysis, supplemented by interviews with polymer plant managers, medical device regulatory affairs leads, automotive Tier 1 procurement directors, aerospace materials engineers, and Dutch logistics coordinators. Secondary validation drew from ECHA substance restriction databases, FDA 510(k) clearance filings, German customs trade records, SEC chemical company disclosures, and EU MDR implementation guidance documents. Bottom-up formulation demand estimates and top-down end-use consumption surveys underwent iterative triangulation.
Segment-weighting across thermoplastic, biodegradable, thermosetting, and conductive product types combined with application-level aerospace, healthcare, automotive, and robotics demand profiles structured the analytical framework. End-user procurement sophistication tiers and functionality-grade performance specifications provided additional modeling dimensions. CAGRs were derived from fitted growth curves against historical adoption patterns and regulatory milestone projections. Forecast inputs incorporated REACH authorization implementation schedules and FDA PMA pathway velocity assumptions.
Several conditions sit outside the modeled scope, including unforeseen ECHA substance restriction expansions, breakthrough metallic shape memory alloy cost reductions, and geopolitical disruptions to German-Dutch specialty monomer corridors. Forecasts reflect assumptions about regulatory timeline adherence and clinical trial enrollment rates. Practitioners should monitor ECHA diisocyanate authorization acceleration, FDA breakthrough device designation grants for SMP implants, and Chinese MIIT stimulus disbursement timing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
Sheath Materials Market
Specialty Materials
Colloidal Silica Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Barium Fluoride Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Engineered Foam Market
Specialty Materials
Electroactive Polymers (EAP) Market