
 Middle-East and Africa Fluoroelastomers Market | 2026-2036
Middle-East and Africa Fluoroelastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Fluoroelastomers Market Foresight
Modular kit configurations for sealing systems is recalibrating how downstream buyers evaluate total cost of ownership across plant maintenance cycles. DuPont leverages its polymer science heritage to sustain premium positioning in specialty grades for chemical processing environments. Solvay anchors regional supply through its fluorochemicals infrastructure, while Freudenberg Sealing Technologies competes on application engineering depth for oilfield service contracts.
Fluoroelastomers are synthetic fluorinated rubber polymers, typically based on vinylidene fluoride copolymers, engineered to withstand temperatures exceeding 200°C and resist aggressive hydrocarbon exposure in static and dynamic sealing applications. FKM formulations dominate volume flows given their cost-performance balance across automotive and chemical processing seals, while FFKM occupies the margin-intensive apex serving semiconductor and pharmaceutical cleanroom specifications where failure costs dwarf material premiums. Specialty and high-performance grades capture disproportionate value pools as end-users in the Gulf's sour gas operations and South Africa's fuel systems manufacturing prioritize extended mean-time-between-replacement metrics over upfront polymer expenditure.
Saudi Arabia's SFDA and the UAE's MOHAP enforce pharmaceutical-grade material certifications that constrain supplier qualification timelines for healthcare elastomer applications. South Africa's national standards body applies pressure equipment regulations aligned with ISO 10423 that mandate proven fluoroelastomer performance in wellhead and Christmas tree assemblies. Stakeholders must track how Gulf national oil companies revise their approved manufacturers lists as they integrate carbon-intensity criteria into procurement scorecards alongside traditional technical specifications.
Market Dynamics
Gulf national oil companies are integrating carbon-intensity criteria into procurement scorecards, forcing suppliers to requalify on environmental performance alongside ISO 10423 wellhead specifications. This procurement recalibration is compressing supplier margins while elevating specialty grade premiums.
Growth Catalysts
- Sour gas expansion:Saudi Aramco and ADNOC are developing high-hydrogen sulfide fields that demand FFKM seals for Christmas tree assemblies. Material specification upgrades are accelerating replacement cycles across existing infrastructure.
- EU F-Gas Regulation:Parallel MEE guidelines on fluorinated compounds are tightening environmental compliance requirements for regional suppliers, creating competitive separation for certified producers.
- Semiconductor fabrication:UAE and Saudi investments in chip manufacturing are importing cleanroom specifications that require pharmaceutical-grade fluoroelastomer components.
Market Restraints
- Feedstock volatility:Vinylidene fluoride monomer supply concentrates in Chinese and European chemical complexes, exposing regional compounders to currency and shipping cost swings.
- Technical ceiling:Perfluoroelastomer cure chemistry remains patent-encumbered, limiting indigenous formulation development in South Africa and the Gulf.
- Substitution pressure:Hydrogenated nitrile rubber advances are capturing static sealing applications below 150°C in automotive fuel systems.
Strategic Opportunities
- Healthcare certification:SFDA and MOHAP pharmaceutical-grade material mandates are constraining supplier qualification timelines, creating first-mover advantages for compliant compounders.
- Renewable hydrogen:Electrolyzer sealing applications are emerging as a greenfield demand vertical with unestablished material specifications.
- Digital distribution:B2B platforms for maintenance, repair, and operations procurement are disintermediating traditional distributor networks in South Africa's automotive belt.
Industry Challenges
- Compounding expertise scarcity:Formulation chemists with fluoroelastomer cure system experience are concentrated in European and North American technical centers.
- Dual certification burden:Suppliers must simultaneously satisfy ISO 10423 for oilfield service and automotive OEM material approvals, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Fluoroelastomers Market |
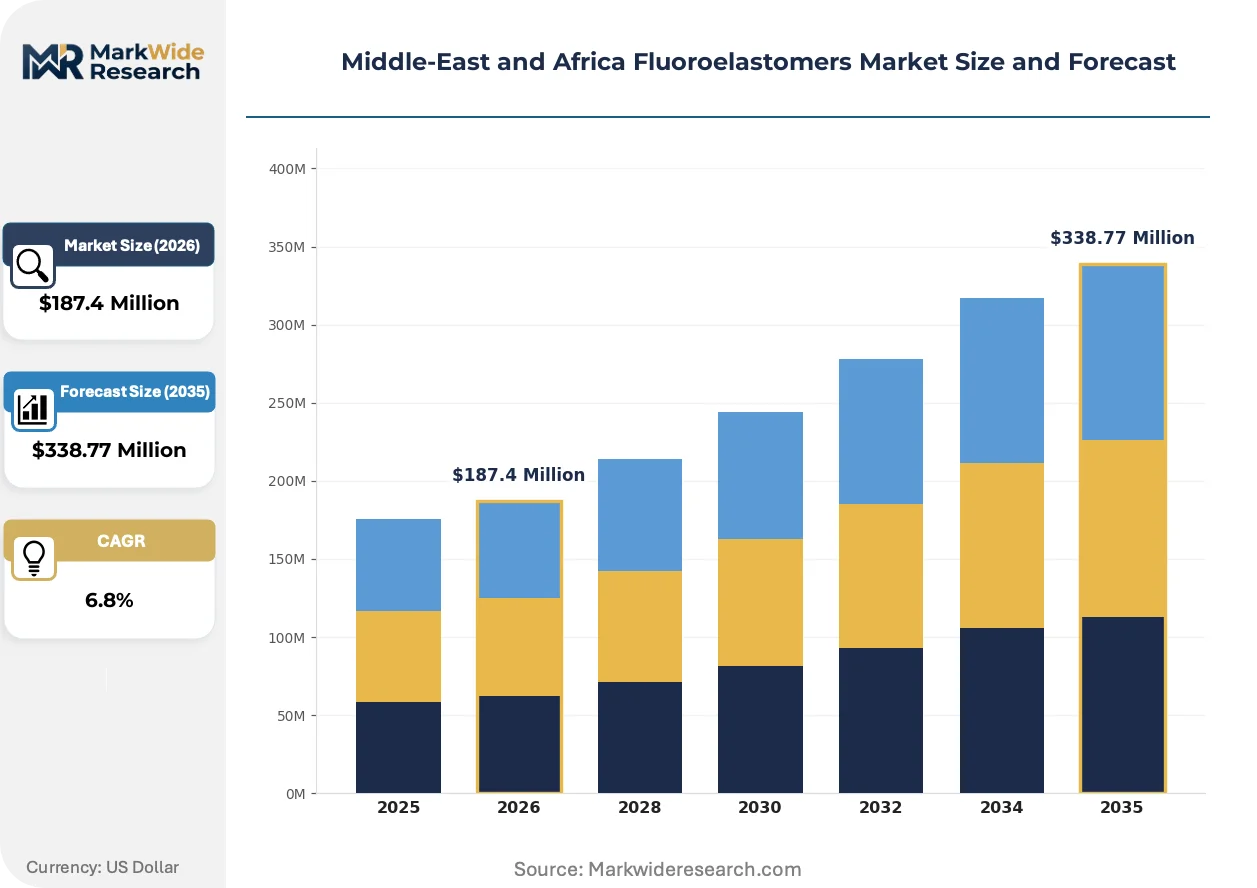
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FKM, FFKM, FVMQ, Copolymers Grade: Commercial, Specialty, High-Performance, Pharmaceutical Application: Automotive, Aerospace, Chemical Processing, Electrical End User: Manufacturing, Healthcare, Oil & Gas, Electronics |
| Companies Covered | 3M, DuPont, Solvay, Daikin Industries, AGC, Freudenberg Sealing Technologies, Dongyue Group, Kureha Corporation, The Chemours Company, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Fluoroelastomers Market Shifts & Advancements
Material science advances and procurement digitization are converging to reshape competitive positioning in Middle-East and Africa fluoroelastomer supply. Three developments merit particular attention.
Modular kit configurations for sealing systems are compressing total cost of ownership calculations across plant maintenance cycles. Saudi petrochemical operators and South African automotive assemblers are standardizing on pre-engineered seal families. This is modularizing supplier relationships around application engineering depth rather than commodity polymer supply.
MEE guidelines on fluorinated greenhouse gases are tightening in parallel with EU F-Gas Regulation enforcement. Regional compounders face accelerated reformulation timelines to maintain access to European-linked supply chains. Specialty grade producers with established low-global-warming-potential cure systems are capturing disproportionate qualification bandwidth.
After-sales service unbundling is disrupting traditional distributor economics. Gulf national oil companies are separating material procurement from installation supervision, forcing seal manufacturers to build direct technical service capabilities. South Africa's fuel systems manufacturers are piloting similar disaggregation, compressing intermediary margins while elevating specification control by end-users.
Middle-East and Africa Fluoroelastomers Market Segmentation
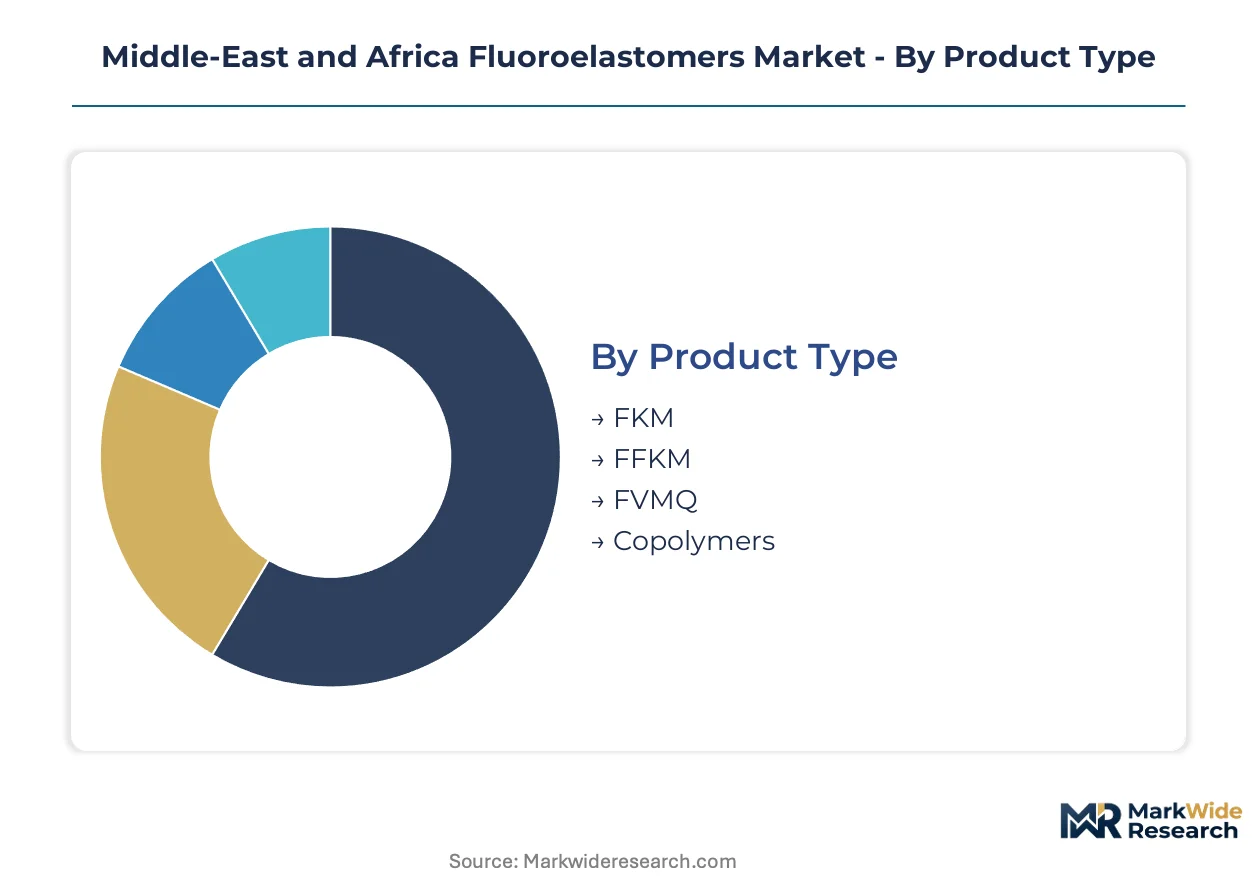
Segmentation in the Middle-East and Africa fluoroelastomers market reveals how technical specifications and regulatory requirements fragment procurement decisions across the region's industrial base. Buyers in Saudi Arabia's petrochemical corridor and South Africa's automotive belt prioritize different performance attributes, creating distinct demand pockets that suppliers must navigate.
Product Type:
Buyers differentiate primarily by temperature tolerance and chemical resistance thresholds, with cost-performance trade-offs determining specification choices across end-use applications.
- FKM:Vinylidene fluoride-based copolymers deliver operational stability between -20°C and 200°C, balancing chemical resistance with processability for high-volume seal production. Saudi Aramco and ADNOC specify FKM for standard wellhead assemblies where hydrogen sulfide concentrations remain moderate, though sour gas field expansion is pushing specification upgrades.
- FFKM:Perfluoroelastomers achieve near-universal chemical inertness and continuous service above 300°C, commanding substantial premiums for failure-critical applications. UAE and Saudi semiconductor fabrication investments are importing cleanroom specifications that demand FFKM for ultra-high-purity process equipment where seal failure costs dwarf material expenditure.
- FVMQ:Fluorosilicone variants combine fuel resistance with extreme low-temperature flexibility for aerospace fuel system seals.
- Copolymers:Modified terpolymer formulations target niche applications requiring customized cure kinetics or adhesion profiles.
FKM leads volumes today; FFKM is gaining share fastest as Gulf sour gas development accelerates material specification upgrades.
Grade:
Margin structures diverge sharply based on certification burden and batch traceability requirements, with pharmaceutical and high-performance grades capturing disproportionate value pools.
- Commercial:Standard formulations serve cost-sensitive automotive and general industrial sealing where ISO 10423 compliance suffices. South Africa's fuel systems manufacturers source commercial grades for high-volume O-ring production, though hydrogenated nitrile rubber advances are capturing static sealing applications below 150°C.
- Specialty:Application-optimized compounds incorporate proprietary cure systems and filler packages for defined operating envelopes. Regional compounders face accelerated reformulation timelines as MEE guidelines on fluorinated greenhouse gases tighten in parallel with EU F-Gas Regulation enforcement.
- High-Performance:Extreme-duty formulations target extended mean-time-between-replacement metrics in Gulf sour gas Christmas tree assemblies.
- Pharmaceutical:SFDA and MOHAP-mandated material certifications constrain supplier qualification timelines, creating first-mover advantages for compliant compounders serving UAE and Saudi healthcare manufacturing.
Commercial grade dominates current procurement volumes; pharmaceutical grade exhibits the steepest expansion trajectory as regional healthcare manufacturing investments mature.
Application:
End-use environments dictate specification stringency, with chemical exposure severity and regulatory oversight intensity determining grade selection.
- Automotive:Fuel system, transmission, and engine sealing applications demand temperature cycling resistance and hydrocarbon impermeability. South Africa's component belt manufacturers standardize on pre-engineered seal families, modularizing supplier relationships around application engineering depth rather than commodity polymer supply.
- Chemical Processing:Aggressive media exposure in Saudi petrochemical complexes drives specification toward specialty and high-performance grades. Modular kit configurations for sealing systems are compressing total cost of ownership calculations across plant maintenance cycles.
- Aerospace:Fuel system and hydraulic sealing applications in Gulf carrier maintenance operations require certified traceability and batch documentation.
- Electrical:Wire insulation and connector seals for high-temperature environments in industrial automation equipment.
Automotive applications anchor current demand; chemical processing is climbing the fastest as downstream capacity expansion accelerates across the Gulf.
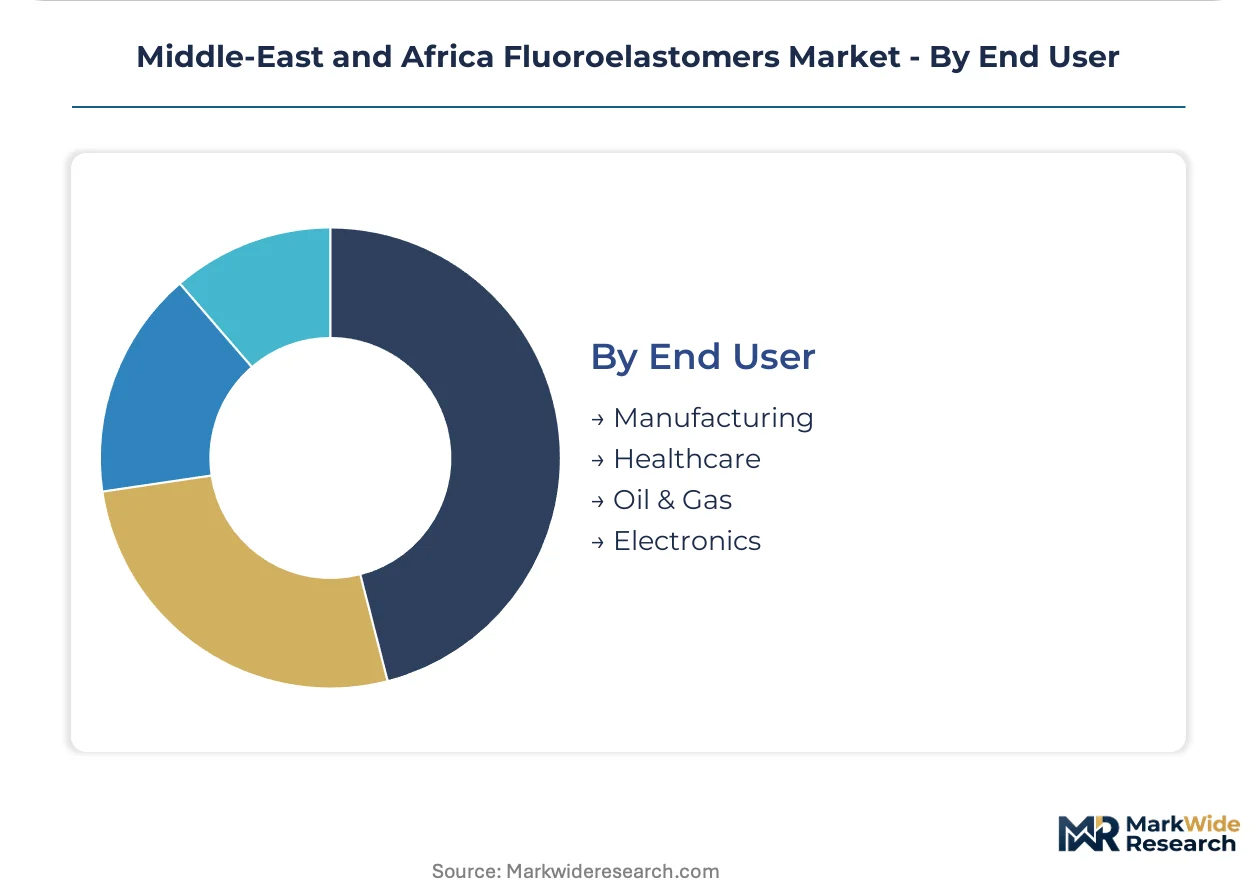
End User:
Procurement sophistication varies by sector maturity, with oil and gas buyers leveraging technical specification control while healthcare regulators impose qualification barriers.
- Oil & Gas:Gulf national oil companies are integrating carbon-intensity criteria into procurement scorecards, forcing suppliers to requalify on environmental performance alongside ISO 10423 wellhead specifications. After-sales service unbundling is disrupting traditional distributor economics as operators separate material procurement from installation supervision.
- Healthcare:SFDA and MOHAP pharmaceutical-grade material mandates are constraining supplier qualification timelines, creating competitive separation for certified producers.
- Manufacturing:Automotive and industrial component producers in South Africa's belt prioritize total cost of ownership over upfront polymer expenditure.
- Electronics:UAE and Saudi semiconductor fabrication investments are importing cleanroom specifications that require pharmaceutical-grade fluoroelastomer components.
Oil and gas commands the largest share of current procurement; healthcare is expanding most quickly as regional pharmaceutical manufacturing capacity builds out.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle-East and Africa fluoroelastomers industry traces its commercial scale to Gulf petrochemical development in the 1970s, when Saudi Aramco and ADNOC established sour gas processing infrastructure requiring high-performance sealing materials. Regional demand now concentrates in hydrocarbon extraction corridors and emerging manufacturing belts across five core markets.
Saudi Arabia
Saudi Aramco's high-hydrogen sulfide field development and NEOM industrial zone construction are accelerating FFKM specification upgrades for Christmas tree assemblies. The Saudi Food and Drug Authority enforces pharmaceutical-grade material certifications that constrain supplier qualification timelines for healthcare elastomer applications. The Eastern Province petrochemical corridor anchors regional demand, with Jubail Industrial City hosting downstream seal fabrication facilities serving Aramco procurement.
United Arab Emirates
ADNOC's sour gas expansion and semiconductor fabrication investments in Abu Dhabi and Dubai are importing cleanroom specifications requiring ultra-high-purity fluoroelastomer components. The Ministry of Health and Prevention applies parallel pharmaceutical-grade mandates that create competitive separation for certified compounders. Dubai's Jebel Ali industrial zone concentrates seal distribution and technical service operations for Gulf oilfield service contracts.
South Africa
Automotive fuel systems manufacturing and industrial component production in the Eastern Cape and Gauteng provinces are standardizing on pre-engineered seal families. The national standards body applies pressure equipment regulations aligned with ISO 10423 that mandate proven fluoroelastomer performance in wellhead assemblies. The Port Elizabeth-Uitenhage automotive belt is piloting disaggregated procurement models that separate material supply from installation supervision.
Qatar
North Field expansion and LNG train maintenance operations are driving specification upgrades for extreme-duty sealing in cryogenic and high-temperature environments. QatarEnergy's revised approved manufacturers lists are integrating carbon-intensity criteria alongside traditional technical specifications. Ras Laffan Industrial City hosts concentrated maintenance, repair, and operations procurement for offshore platform seal replacement cycles.
Egypt
Petroleum sector modernization and Mediterranean gas field development are expanding demand for specialty grade compounds in wellhead and processing equipment. The national petroleum regulator is aligning environmental compliance requirements with evolving EU F-Gas Regulation standards for fluorinated compound handling. The Suez Canal Economic Zone is emerging as a redistribution hub for seal materials serving North African and Levantine industrial markets.
Middle-East and Africa Fluoroelastomers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification burden and application engineering depth. The vendor base clusters around three tiers: integrated fluorochemical majors with captive monomer supply, regional compounders with formulation expertise, and application engineering specialists with oilfield service relationships. Structural consolidation is limited by patent-encumbered cure chemistry and scarce compounding expertise. Dominant competitive moves include backward integration into vinylidene fluoride monomer production and strategic partnerships with Gulf national oil companies for qualification bandwidth.
Within the integrated fluorochemical tier, DuPont and Solvay exemplify premium positioning through polymer science heritage and regional fluorochemicals infrastructure respectively. Freudenberg Sealing Technologies occupies a position among application engineering specialists competing on technical service depth for oilfield contracts. These three anchors illustrate how competitive separation derives from qualification timelines, environmental certification compliance, and direct relationships with procurement teams at Saudi Aramco, ADNOC, and South African automotive assemblers.
| Leading Market Players |
|---|
| 3M |
| DuPont |
| Solvay |
| Daikin Industries |
| AGC |
| Freudenberg Sealing Technologies |
| Dongyue Group |
| Kureha Corporation |
| The Chemours Company |
| Others |
Supply & Pricing Matrix
Gulf national oil company procurement teams concentrate purchasing power for extreme-duty sealing grades, anchoring a contract-based long-term offtake model that privileges qualification bandwidth over spot-market flexibility. This buyer concentration elevates specialty grade premiums while compressing margins for uncertified compounders locked out of approved manufacturers lists.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-certified FFKM compounds from commercial FKM grades and uncertified commodity formulations. Price differentiation centers on SFDA and MOHAP certification status plus ISO 10423 wellhead compliance, with carbon-intensity scoring now entering procurement scorecards as a third tier. Margins are tightening for commercial grade suppliers as hydrogenated nitrile rubber captures static sealing applications below 150°C. South African automotive assemblers exhibit highest price sensitivity, while UAE semiconductor fabricators accept substantial premiums for failure-critical cleanroom specifications.
Supply Chain Analysis
Vinylidene fluoride monomer supply rests on Chinese and European chemical complexes, with regional compounders drawing specialty cure system additives from German and Japanese technical centers. Fluoroelastomer compounding feeds from fluorochemical majors with captive polymerization capacity, while finished seal fabrication concentrates in Saudi Arabia's Eastern Province and South Africa's Eastern Cape. Single-source vulnerability runs through patent-encumbered perfluoroelastomer cure chemistry, limiting indigenous formulation development. Distribution runs through oilfield service contractors and B2B maintenance platforms disintermediating traditional automotive distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through pharmaceutical grade certification premiums and sour gas specification upgrades that extend replacement cycles. Cost compression in commercial grades is accelerating competitive separation around environmental compliance and application engineering depth.
For Market Incumbents: Deepen backward integration into vinylidene fluoride monomer production to secure feedstock margin control against Chinese and European supply volatility. Expand direct technical service capabilities as Gulf national oil companies unbundle after-sales supervision from material procurement, defending qualification bandwidth against emerging compounders with faster MEE environmental certification timelines. For New Entrants and Emerging Players: The price-point gap between pharmaceutical-certified FFKM and commercial FKM grades creates entry space for specialty compounders with targeted healthcare certification investment. Focus initial penetration on Egypt's petroleum sector modernization and Mediterranean gas field development, where ISO 10423 compliance requirements are newly stringent and incumbent relationships remain less entrenched than in Saudi Arabia or the UAE. For Investors and Strategic Acquirers: Gulf national oil companies are the most active acquirer in this space, seeking captive seal fabrication capacity to secure supply chain control for North Field and sour gas expansion programs. Long-term viability favors regional compounders with dual certification capability spanning oilfield service and pharmaceutical manufacturing. Watch QatarEnergy's approved manufacturers list revisions as the signal for carbon-intensity criteria adoption pace across Gulf procurement organizations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive vinylidene fluoride supply insulates margins from Chinese feedstock volatility and currency swings. |
| Pharmaceutical Grade Certification Investment | SFDA and MOHAP compliance creates first-mover barriers in UAE and Saudi healthcare manufacturing expansion. |
| Direct Technical Service Capability Buildout | Installation supervision unbundling by Aramco and ADNOC elevates specification control by seal manufacturers. |
| Low-Global-Warming-Potential Cure System Development | MEE guideline alignment with EU F-Gas Regulation secures qualification bandwidth for European-linked supply chains. |
| Digital B2B Platform Partnership | Maintenance procurement digitization in South Africa's automotive belt compresses distributor margins while expanding reach. |
Research Methodology
Coverage spans the Middle East and Africa, with primary inputs from each regional production hub and downstream demand cluster. The approach combines structured interviews with plant managers at Saudi and South African seal fabrication facilities, procurement leads at Gulf national oil companies, and technical R&D directors at European fluorochemical majors. Secondary validation draws from customs and trade data, SEC filings of listed fluorochemical producers, and MEE environmental compliance disclosures. Bottom-up demand modeling across end-use applications triangulates against top-down fluoropolymer consumption estimates from regional petrochemical associations.
Granularity extends to product type, grade tier, end-use industry, and national regulatory cluster across the analysis window. The analytical framework models FKM, FFKM, FVMQ, and copolymer demand separately, with grade-level splits across commercial, specialty, high-performance, and pharmaceutical certifications. CAGRs derive from replacement cycle analysis in sour gas infrastructure, semiconductor fabrication buildout timelines, and automotive content-per-vehicle trends in South Africa. Industry-specific inputs include Aramco and ADNOC approved manufacturers list revisions, and MEE guideline implementation schedules.
Caveats apply where feedstock supply disruptions, accelerated EU F-Gas Regulation enforcement, or breakthrough hydrogenated nitrile rubber formulations could materially shift the outlook. Forecasts reflect assumptions around qualification timeline stability and carbon-intensity procurement criteria adoption pace. A small set of triggers—QatarEnergy procurement scorecard revisions, Egyptian regulator alignment speed with European standards, and South African automotive procurement disaggregation depth—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Industrial PU Elastomer Market