
 South America Thermoplastic Elastomer (TPE) Market | 2026-2036
South America Thermoplastic Elastomer (TPE) Market Size, Share, and Industry Trends Forecast 2026-2036
South America Thermoplastic Elastomer (TPE) Market Analytics
Brazilian petrochemical compounders is restructuring TPE supply chains to serve rebounding automotive OEM programs across Mercosur. BASF SE leverages its regional polymerization assets to sustain compound consistency for high-specification automotive grades. KRATON CORPORATION anchors SBC supply through its controlled distribution network in São Paulo and Buenos Aires corridor. Dynasol Group competes on customized TPE-S and TPE-O blends for industrial hose and conveyor belt producers.
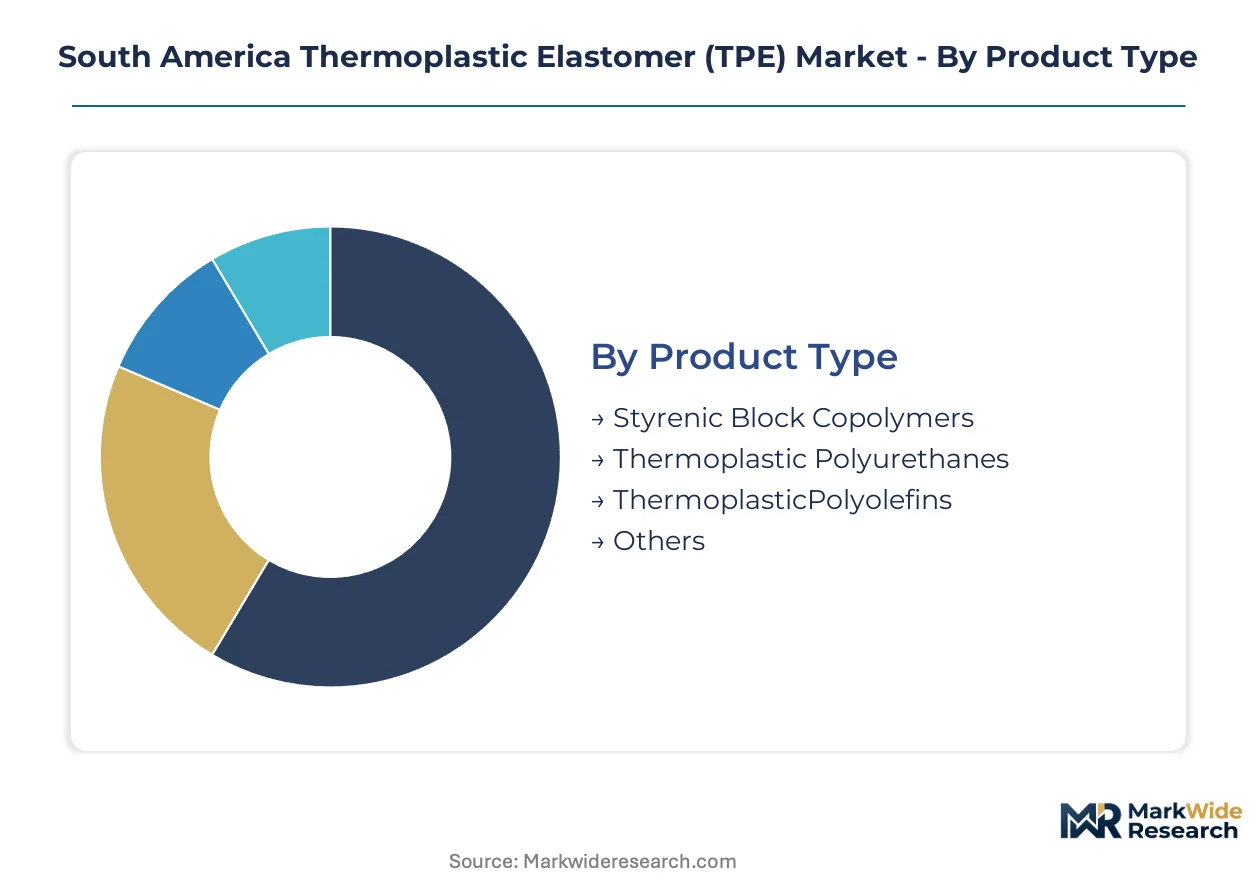
Thermoplastic elastomers combine rubber-like elasticity at service temperatures with thermoplastic processability, typically featuring hard and soft block segments in copolymer architectures that enable melt processing without vulcanization. Styrenic Block Copolymers dominate volume consumption across South America due to established pricing accessibility and broad compatibility with polyolefin substrates. Thermoplastic Polyurethanes command premium positioning in medical device tubing and film applications where abrasion resistance and biocompatibility specifications justify higher compound costs. Thermoplastic Polyolefins are gaining formulation share in automotive interior skins as OEMs pursue reduced volatile organic compound emissions and lower part density targets.
ANVISA in Brazil and Argentina's national pharmaceutical regulator enforce biocompatibility testing protocols that constrain TPE qualification timelines for medical device applications. INMETRO's automotive material certification framework and REACH-aligned chemical substance declarations through Mercosur's GMC resolutions shape importer compliance obligations for European and Asian resin suppliers. Stakeholders must monitor evolving Mercosur technical regulations on recycled content mandates, as these will determine which compounders can certify post-industrial TPE regrind for automotive interior specifications without OEM derogation.
Market Dynamics
Automotive OEMs across Mercosur are consolidating supplier bases to secure TPE compounds that satisfy INMETRO's tightening traceability mandates, compressing compounder margins while rewarding integrated petrochemical players with verified polymerization assets.
Growth Catalysts
- INMETRO Certification Pressure:Brazil's automotive material standards now require batch-level compound documentation, favoring suppliers with captive polymerization and laboratory verification capabilities.
- Interior Skin Reformulation:São Paulo-based Tier-1 suppliers are specifying thermoplastic polyolefins for dashboard and door panel applications to meet OEM volatile organic compound reduction targets.
- São Paulo Corridor Clustering:Compounders co-locating near Braskem's polyolefin feedstock infrastructure capture logistics savings and faster qualification cycles for Mercosur automotive programs.
Market Restraints
- Butadiene Supply Concentration:Styrenic block copolymer production depends on naphtha-cracking economics controlled by a narrow set of regional petrochemical complexes.
- ANVISA Qualification Timelines:Brazil's national pharmaceutical regulator enforces extended biocompatibility testing protocols that stretch TPE approval cycles for medical tubing applications to 18-24 months.
- Polypropylene Price Volatility:Thermoplastic polyolefin formulations expose compounders to monomer cost swings that compress blending margins during petrochemical downcycles.
Strategic Opportunities
- Argentine Industrial Hose Segment:Buenos Aires province manufacturers seek customized TPE-S and TPE-O compounds for agricultural equipment and mining conveyor applications with limited local supply options.
- Recycled Content Mandates:Evolving Mercosur GMC resolutions on post-industrial regrind certification will create first-mover advantage for compounders able to qualify automotive interior specifications without OEM derogation.
- Medical Device Convergence:Combination products integrating drug delivery with TPE tubing present white space for compounders with ANVISA-registered cleanroom compounding capabilities.
Industry Challenges
- Polymerization Chemistry Expertise Gap:Regional universities produce limited graduates with specialized training in block copolymer architecture design and melt rheology characterization.
- Multi-Site Certification Burden:Compounders serving both automotive and medical verticals must maintain parallel quality systems for INMETRO automotive standards and ANVISA pharmaceutical protocols.
- Legacy Equipment Retrofit Costs:Converting existing PVC extrusion lines for TPE processing requires screw and die modifications that strain mid-cap compounder capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Thermoplastic Elastomer (TPE) Market |
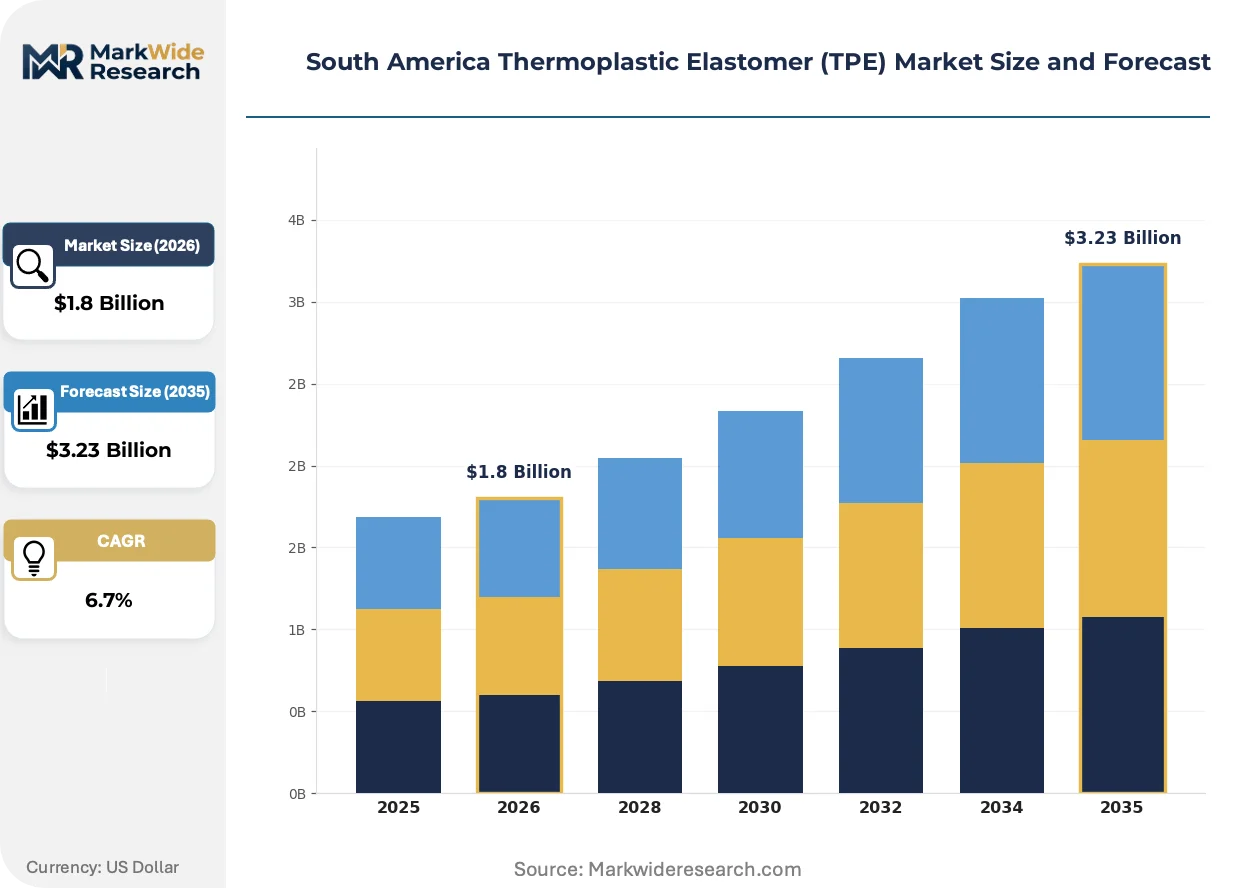
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrenic Block Copolymers, Thermoplastic Polyurethanes, ThermoplasticPolyolefins, Others End User: Automotive, Consumer Goods, Medical Devices, Industrial Applications Form: Granules, Pellets, Sheets, Liquid Application: Sealants, Adhesives, Coatings, Packaging |
| Companies Covered | DuPont, BASF SE, KRATON CORPORATION, Arkema, Evonik Industries AG, Huntsman International LLC, Mitsui Chemicals, Inc., SABIC, Dynasol Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Thermoplastic Elastomer (TPE) Market Evolving Landscape
Formulation science and regulatory compliance frameworks are converging to reshape how TPE compounders qualify materials for automotive and medical applications across the Mercosur trade zone.
Reactive extrusion compounding is consolidating control over molecular weight distribution in high-performance thermoplastic polyurethane grades. São Paulo-based automotive seal manufacturers are adopting these materials for under-the-hood gaskets requiring heat aging resistance above 150°C. The technology is consolidating mid-tier compounders into specialized niches while integrated producers capture specification-grade volume.
REACH-aligned chemical substance declarations through Mercosur's GMC resolutions are forcing European and Asian resin suppliers to restructure importer documentation. The framework mandates full supply chain disclosure for substances of very high concern, increasing compliance costs for non-integrated distributors. Automotive interior specifications in Brazil's São Paulo industrial corridor are most affected, with OEMs now requiring third-party verification of declaration accuracy.
Specification-driven procurement is compressing supplier qualification cycles as Brazilian automotive OEMs reduce approved compounder lists from twelve to four per material category. Tier-1 interior suppliers are consolidating purchase orders with integrated petrochemical players offering bundled feedstock-to-compound traceability. The pattern is most visible in dashboard skin applications, where OEMs now mandate single-source accountability for volatile organic compound emissions compliance.
South America Thermoplastic Elastomer (TPE) Market Segmentation
TPE procurement across South America divides sharply between specification-driven automotive buyers and price-sensitive industrial consumers. Understanding these segment boundaries reveals where compounders can defend margin versus where volume aggregation wins.
Product Type:
Compound selection hinges on the trade-off between performance specifications and feedstock cost exposure.
- Styrenic Block Copolymers:These materials combine polystyrene end-blocks with rubber mid-blocks to deliver elasticity without vulcanization. Brazilian automotive interior manufacturers in São Paulo specify SBC grades for dashboard skins and door seals where polyolefin compatibility and colorability matter. INMETRO's batch-traceability mandates favor suppliers with captive butadiene supply.
- Thermoplastic Polyurethanes:Segmented block copolymers with hard urethane and soft polyether or polyester domains command premium positioning. Argentine medical device tubing producers in Buenos Aires province specify TPU for catheter applications where ANVISA biocompatibility protocols and abrasion resistance converge.
- Thermoplastic Polyolefins:Physical blends of polypropylene and ethylene-propylene rubber offer density reduction and VOC compliance for automotive interiors.
- Others:Copolyester elastomers and polyamide block copolymers serve niche flexible hose and high-temperature seal applications.
Volume sits with Styrenic Block Copolymers; growth tilts toward Thermoplastic Polyolefins.
End User:
Customer concentration determines qualification burden and contract duration.
- Automotive:OEM consolidation across Mercosur has compressed approved supplier lists from twelve compounders to four per material category. Tier-1 interior suppliers in São Paulo's industrial corridor now mandate single-source accountability for VOC emissions compliance, bundling feedstock-to-compound traceability requirements.
- Consumer Goods:Soft-touch grips for power tools and appliance housings drive specification. Brazilian consumer durables manufacturers prioritize Shore A hardness consistency and UV stability for outdoor equipment.
- Medical Devices:ANVISA qualification timelines stretch TPE approval cycles to 18-24 months for tubing and film applications.
- Industrial Applications:Mining conveyor belts and agricultural hoses in Argentina's Buenos Aires province demand customized TPE-S and TPE-O blends with limited local supply options.
Automotive captures the largest contract values; medical devices show the steepest expansion trajectory.
Form:
Processing equipment compatibility shapes compounder formulation priorities.
- Granules:Irregular particle morphology suits dry-blending operations and color masterbatch incorporation. São Paulo compounders serving automotive Tier-1s favor granule form for injection molding of interior components where melt homogeneity affects surface finish.
- Pellets:Cylindrical extruded form enables precise dosing in continuous extrusion lines. Brazilian industrial hose manufacturers specify pelletized TPE-O for consistent output in high-speed conveyor belt production.
- Sheets:Calendered or extruded flat stock serves thermoforming and die-cutting operations.
- Liquid:Low-viscosity reactive systems enable cast molding of complex geometries.
Pellets dominate current volume; liquid formulations are gaining share fastest in medical molding.
Application:
Performance requirements and regulatory exposure vary sharply across use cases.
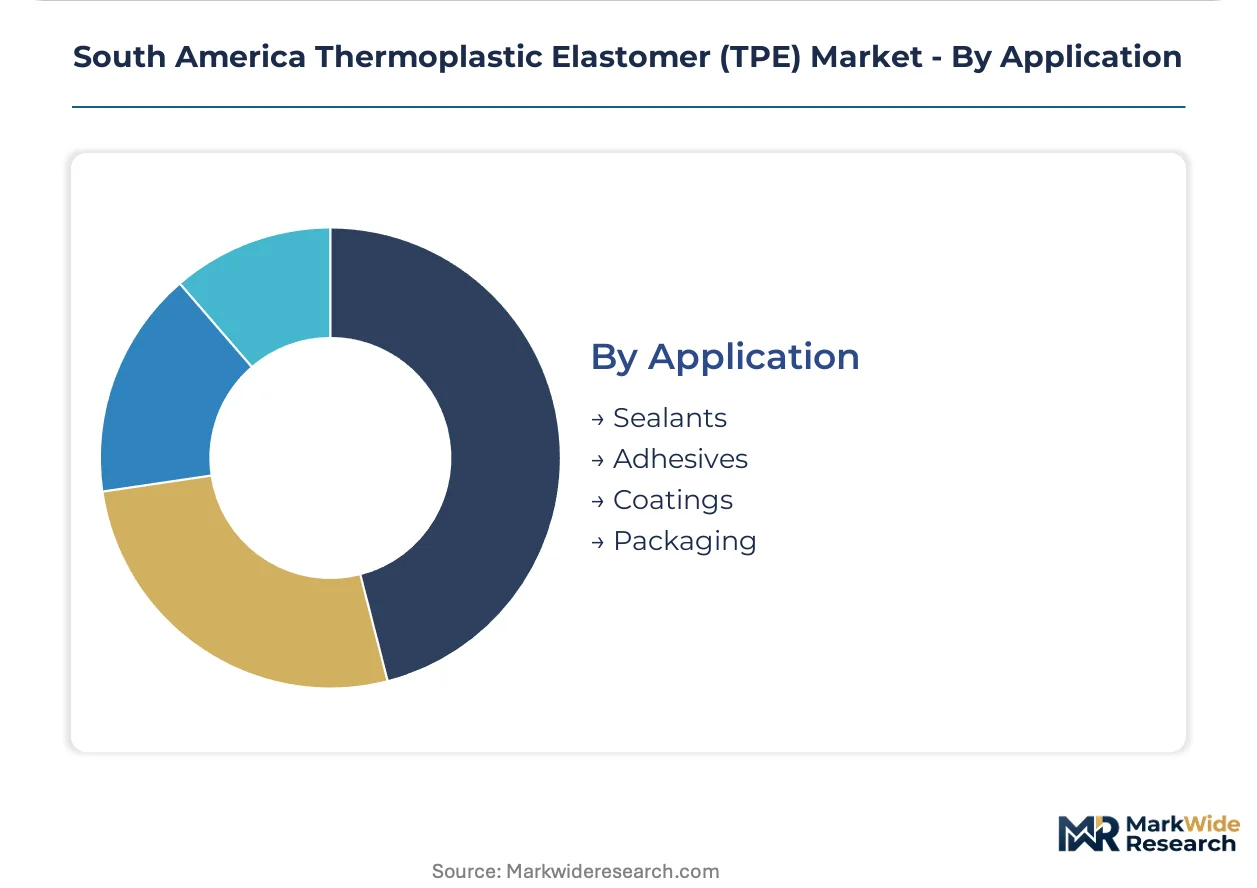
- Sealants:Compression set resistance and fluid compatibility define specification. Argentine agricultural equipment manufacturers specify TPE-S compounds for hydraulic seal applications where mineral oil resistance and low-temperature flexibility converge.
- Adhesives:Hot-melt formulations demand precise melt viscosity control. Brazilian packaging converters use TPE-based adhesives for flexible film lamination where food-contact compliance and bond strength matter.
- Coatings:Dip-molded or spray-applied TPU layers provide abrasion protection.
- Packaging:Flexible film and closure applications prioritize seal integrity and organoleptic neutrality.
Sealants anchor current demand; coatings represent the fastest-climbing application segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Braskem's polyolefin production complexes in Brazil anchor TPE feedstock supply across the continent. Petrochemical infrastructure clustering determines where compounders locate blending operations. Regulatory divergence between Mercosur members shapes cross-border material qualification requirements.
Brazil
São Paulo's industrial corridor concentrates automotive TPE demand from Tier-1 interior suppliers. INMETRO certification mandates batch-level compound documentation, favoring integrated producers with captive polymerization assets. Campinas and ABC Paulista host the densest compounder clustering near Braskem's feedstock terminals.
Argentina
Buenos Aires province manufacturers seek customized TPE-S and TPE-O compounds for agricultural equipment and mining conveyor belts. The national pharmaceutical regulator enforces biocompatibility testing protocols that stretch medical tubing approvals. Rosario's industrial belt represents the secondary demand node for industrial hose applications.
Chile
Mining sector procurement drives specialty sealant and gasket demand from copper extraction operations in the Atacama and Antofagasta regions. The country's national standards body aligns chemical substance declarations with REACH-equivalent frameworks. Santiago's logistics hub serves as the import gateway for Asian resin suppliers.
Colombia
Andean automotive assembly plants in Bogotá and Medellín source TPE compounds for interior components under regional content rules. The national technical standards institute enforces automotive material certification parallel to Mercosur GMC resolutions. Barranquilla's port infrastructure handles bulk resin imports for northern industrial consumers.
Peru
Lima-based consumer goods manufacturers specify soft-touch TPE grips for appliance and power tool applications. The national quality institute maintains food-contact compliance standards affecting packaging film specifications. Callao's maritime terminal serves as the distribution point for Pacific-rim resin imports.
South America Thermoplastic Elastomer (TPE) Market Competitive Landscape
Global majors compete with regional champions across feedstock access and qualification speed. The market structures around three tiers: integrated petrochemical players with captive polymerization, specialized compounders with formulation expertise, and distributors serving price-sensitive industrial accounts. Two strategic archetypes dominate: backward-integrated producers controlling butadiene-to-compound chains, and formulation specialists winning on customized blends. Competitive moves center on single-source accountability contracts and ANVISA-registered cleanroom capabilities.
Within the integrated producer tier, BASF SE and KRATON CORPORATION exemplify contrasting approaches to regional positioning. BASF SE leverages European polymerization technology transfer to serve high-specification automotive grades. KRATON CORPORATION anchors SBC supply through controlled distribution networks spanning São Paulo and Buenos Aires. Dynasol Group occupies a specialized position among mid-scale compounders, representing the customized blend archetype for industrial hose and conveyor belt producers.
| Leading Market Players |
|---|
| DuPont |
| BASF SE |
| KRATON CORPORATION |
| Arkema |
| Evonik Industries AG |
| Huntsman International LLC |
| Mitsui Chemicals, Inc. |
| SABIC |
| Dynasol Group |
| Others |
Value Network & Pricing Analysis
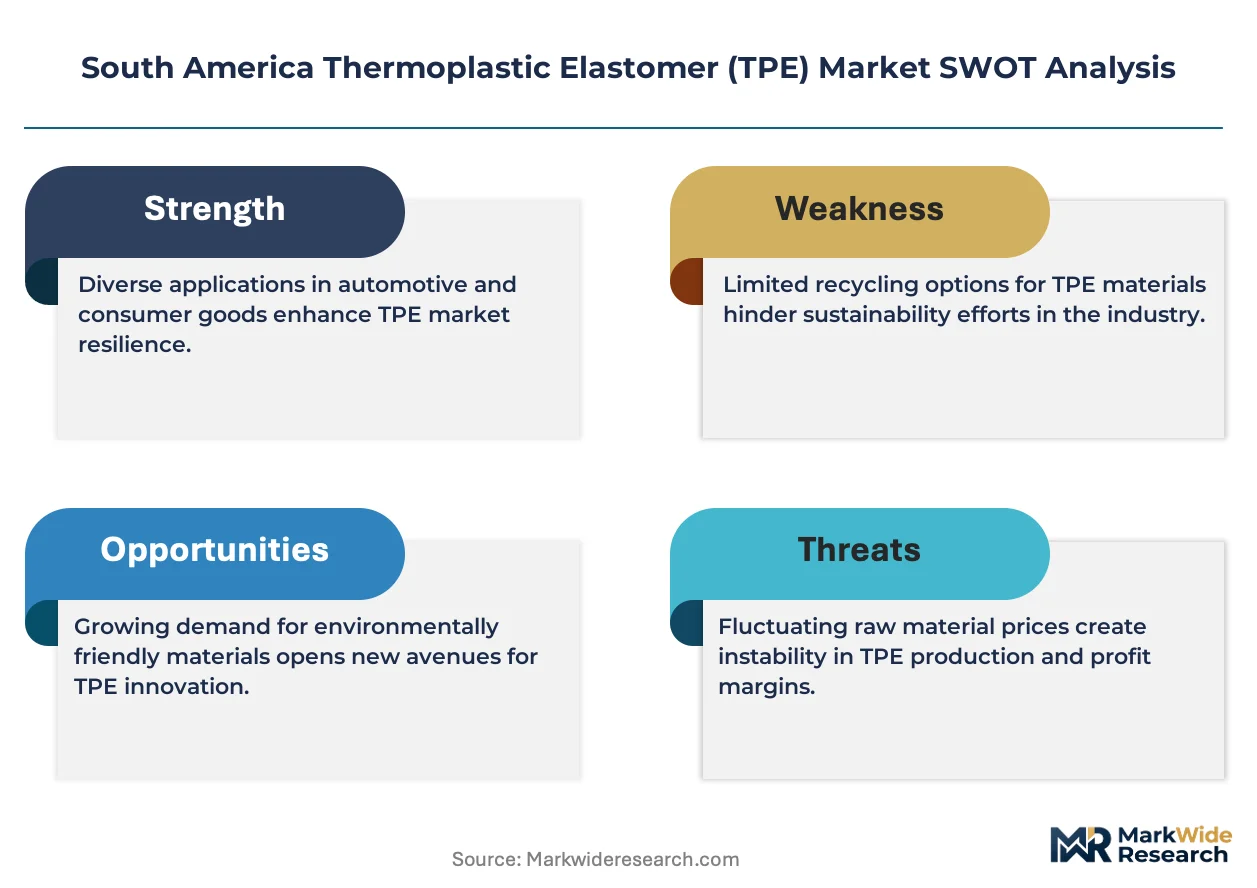
Butadiene feedstock costs flow from Braskem's naphtha crackers through three distinct pricing tiers for automotive compounders, with INMETRO-certified batches commanding premium positioning over undifferentiated industrial grades.
Pricing Analysis
Service bundling separates premium compounders from commodity suppliers, with integrated producers including laboratory verification and batch documentation while distributors strip out technical support. Price differentiation hinges on INMETRO certification grade and captive polymerization status, with backward-integrated players capturing margin from Tier-1 automotive accounts. Cost compression in standard-grade SBC compounds is intensifying as Argentine industrial buyers consolidate purchase volumes. Medical device manufacturers show least price sensitivity due to ANVISA qualification barriers, while mining conveyor belt producers in Buenos Aires province drive hardest volume negotiations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand from São Paulo Tier-1 suppliers, while distributor networks serve fragmented industrial accounts across Mercosur. Feedstock concentration centers on Brazil's Triângulo Mineiro petrochemical complex and Argentina's Bahía Blanca corridor. Raw material sourcing draws from butadiene monomer, polypropylene resin, and isocyanate precursors. Single-source vulnerability persists for medical-grade TPU polymerization, where ANVISA-registered cleanroom capacity remains constrained to two regional facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Butadiene cracking capacity expansion lags demand growth across Mercosur, propping compound pricing power for integrated producers with captive feedstock supply.
For Market Incumbents: Extend polymerization asset utilization into customized TPE-O blends for Argentine mining applications, while hardening INMETRO documentation systems against emerging Asian resin entrants seeking automotive qualification. Backward integration into butadiene supply secures margin defense during petrochemical upcycles. For New Entrants and Emerging Players: Mercosur's evolving GMC resolutions on post-industrial regrind certification open a window for compounders with mechanical recycling capabilities to capture automotive interior specifications before incumbent retrofit investments mature. Target Buenos Aires province industrial hose manufacturers with TPE-S formulations; lead with ANVISA pre-registration to compress future medical tubing approval timelines. For Investors and Strategic Acquirers: First-mover qualification of recycled-content automotive grades without OEM derogation is the leading indicator that compounder margin structures will bifurcate. Over the coming decade, acquisition targets center on mid-scale São Paulo compounders with validated polymerization assets and dormant cleanroom capacity suitable for ANVISA registration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Supply | Captive naphtha-cracking economics insulate Braskem-linked compounders from monomer cost volatility. |
| ANVISA Cleanroom Registration | Pharmaceutical-grade compounding capabilities unlock 18-24 month medical tubing approval cycles. |
| Post-Industrial Regrind Qualification | Mercosur GMC resolution compliance creates first-mover positioning for recycled-content automotive specifications. |
| Reactive Extrusion Technology Adoption | São Paulo seal manufacturers specify heat-aged TPU grades above 150°C for under-the-hood applications. |
| Single-Source Accountability Contracts | Tier-1 interior suppliers bundle feedstock-to-compound traceability for VOC emissions compliance. |
Research Methodology
Trade flow databases, petrochemical capacity registries, and automotive OEM procurement disclosures formed the secondary backbone, cross-referenced with primary interviews involving Braskem supply chain managers, Tier-1 automotive procurement leads, ANVISA regulatory consultants, and Argentine industrial hose compounders. Bottom-up volume estimates from compounder production data triangulated against top-down demand projections derived from vehicle production and medical device registration filings.
Bottom-up modeling segmented the market by product architecture, end-use vertical, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand functions incorporating feedstock cost pass-through assumptions and OEM specification migration patterns. Industry-specific inputs included INMETRO certification queue lengths and ANVISA biocompatibility testing throughput rates.
The model assumes a particular technology adoption path; alternative pathways for reactive extrusion compounding would alter the outlook if heat-aging performance thresholds shift. Forecasts incorporate assumptions regarding Mercosur regulatory harmonization and petrochemical capacity expansion timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
North America Performance Elastomer Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
High Temperature Elastomers Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
Hot Cast Elastomers Market