
 Global Flexible Elastomeric Foam Market | 2026-2036
Global Flexible Elastomeric Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexible Elastomeric Foam Market Foresight
Closed-cell microstructure engineering is fragmenting how thermal insulation systems are specified across commercial and industrial projects. Armacell International S.A. leverages its polymer compounding expertise to dominate specification-grade nitrile foam for HVAC infrastructure. Saint-Gobain anchors European supply through vertically integrated rubber processing and multi-regional compounding facilities. Huamei Energy-saving Technology Group Co., Ltd. competes on manufacturing scale, shipping roll and sheet formats from Shandong province to Middle Eastern contractors.
Flexible elastomeric foam denotes closed-cell synthetic rubber materials—nitrile butadiene rubber and ethylene-propylene-diene monomer copolymers—manufactured via continuous extrusion or expansion molding to densities between 40-80 kg/m³, delivering thermal conductivity values near 0.038 W/m·K for pipe and duct insulation. The material's primary commercial purpose centers on preventing condensation on cold surfaces while blocking vapor transmission in mechanical systems. Nitrile foam leads volume in HVAC insulation applications where oil resistance and thermal stability matter most, while silicone foam captures premium margin pools in electronics and automotive sealing where temperature extremes exceed 150°C. EPDM foam sustains growth in outdoor construction and vehicle manufacturing due to UV stability and ozone resistance in exposed environments.
REACH restrictions on halogenated flame retardants and the EU F-Gas Regulation phase-down reshape formulation chemistry across European supply chains, forcing compounders toward phosphorus-based and mineral filler alternatives. China's SAMR enforces GB 8624 combustion ratings that restrict benzene and formaldehyde emissions in building materials, tightening market access for uncertified imports. India's BIS certification mandate for polymer insulation products adds compliance layers for foreign manufacturers serving infrastructure tenders. Stakeholders must monitor how divergent flammability and emissions standards across these jurisdictions fragment product platforms and localize formulation investments.
Market Dynamics
REACH restrictions on halogenated flame retardants and China's GB 8624 combustion standards are fragmenting formulation chemistry across supply chains, forcing compounders toward phosphorus-based alternatives and mineral filler systems while raising compliance costs for cross-border trade.
Growth Catalysts
- EU F-Gas Regulation phase-down:HVAC contractors across Germany and France are specifying closed-cell elastomeric insulation for chilled water piping as fluorinated gas restrictions tighten equipment efficiency requirements.
- Commercial construction corridor expansion:India's infrastructure tenders from Mumbai to Bangalore concentrate demand for low-smoke, zero-halogen foam formulations in high-rise mechanical systems.
- Dual carbon goals:China's MIIT enforcement of building thermal performance standards pushes manufacturers toward energy-efficient insulation materials in district cooling networks.
Market Restraints
- Petrochemical input volatility:Nitrile butadiene rubber and EPDM feedstock prices fluctuate with crude oil derivatives, compressing margin predictability for continuous extrusion operations.
- Supply concentration in Shandong province:Roll and sheet format manufacturing clusters in eastern China create geographic single-point vulnerability for Middle Eastern contractor procurement.
- Technical ceiling in high-temperature applications:Standard nitrile foam thermal stability limits near 105°C prevent penetration into electronics sealing above 150°C where silicone dominates.
Strategic Opportunities
- Saudi Arabia's giga-project construction:NEOM and Red Sea development tenders specify imported elastomeric insulation for district cooling infrastructure at scale unmatched in Gulf Cooperation Council markets.
- Phosphorus-based flame retardant convergence:Mineral filler and intumescent coating technologies are merging with foam substrates to meet multi-jurisdiction fire safety codes without halogenated chemistry.
- BIS certification pathway:India's mandatory polymer insulation product certification creates first-mover advantage for foreign manufacturers completing compliance timelines ahead of infrastructure bid deadlines.
Industry Challenges
- Polymer compounding talent scarcity:Formulation chemists capable of balancing thermal conductivity, density, and emissions compliance across nitrile and EPDM platforms command premium compensation in competitive labor markets.
- Multi-jurisdiction certification timelines:Parallel GB 8624, BIS, and REACH compliance testing extends product launch cycles by 18-24 months for specification-grade formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexible Elastomeric Foam Market |
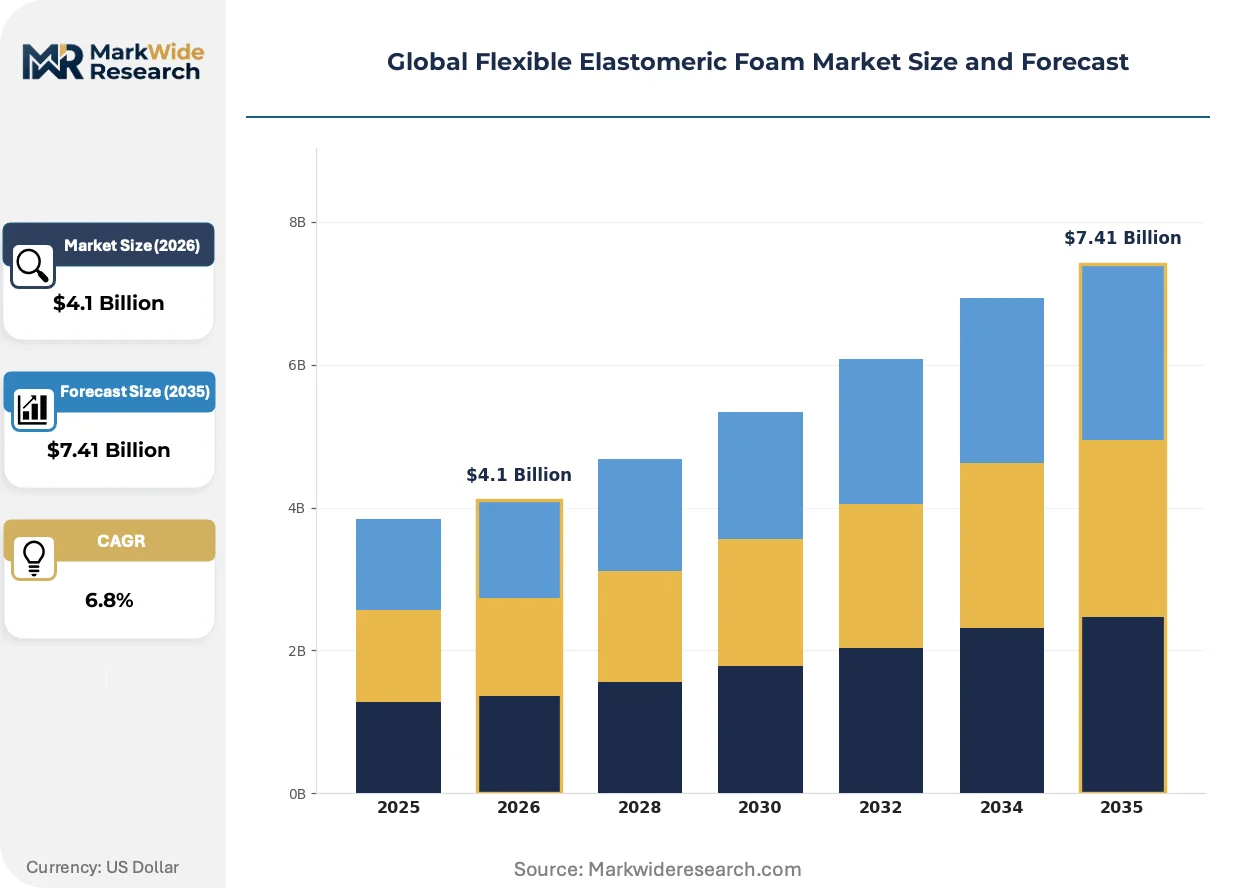
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Silicone Foam, EPDM Foam, Nitrile Foam, Neoprene Foam Application: HVAC Insulation, Automotive Sealing, Acoustics Management, Packaging Solutions, Consumer Goods Padding End User Industry: Construction, Vehicle Manufacturing, Electronics, Sports Equipment, Furniture Production Form: Sheet, Roll, Block, Molded, Spray |
| Companies Covered | Saint-Gobain, Huamei Energy-saving Technology Group Co., Ltd., Armacell International S.A., NMC SA, Zotefoams plc, L’Isolante K-FLEX S.p.A., Hira Industries LLC, Jinan Retek Industries Inc., Aeroflex USA, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexible Elastomeric Foam Market Shifts & Advancements
Closed-cell microstructure engineering is digitizing how thermal insulation systems are specified, with digital twin modeling and IoT-enabled performance monitoring reshaping contractor procurement and manufacturer R&D pipelines across commercial and industrial verticals.
Sensor-embedded elastomeric foam is digitizing condition monitoring in HVAC infrastructure. Facility managers in Singapore and Dubai are deploying smart insulation layers that transmit real-time thermal performance data to building management systems. This convergence is compressing maintenance cycles and enabling predictive replacement scheduling that shifts contractor revenue from product sales to performance contracts.
ECHA's REACH restrictions on halogenated flame retardants are forcing compounders toward phosphorus-based and mineral filler alternatives. European rubber processors face reformulation costs exceeding 15% of R&D budgets while awaiting ECHA guidance on acceptable substitution thresholds. HVAC specification teams in Germany and the Netherlands are prioritizing pre-certified low-smoke, zero-halogen formulations to de-risk project compliance.
Direct procurement from compounders is displacing traditional distribution tiers in Middle Eastern construction markets. EPC contractors in Saudi Arabia and the UAE are establishing captive supply relationships with Shandong and European manufacturers, bypassing regional stockists. This channel compression concentrates volume with vertically integrated producers capable of custom roll dimensions and just-in-time delivery to giga-project sites.
Global Flexible Elastomeric Foam Market Segmentation
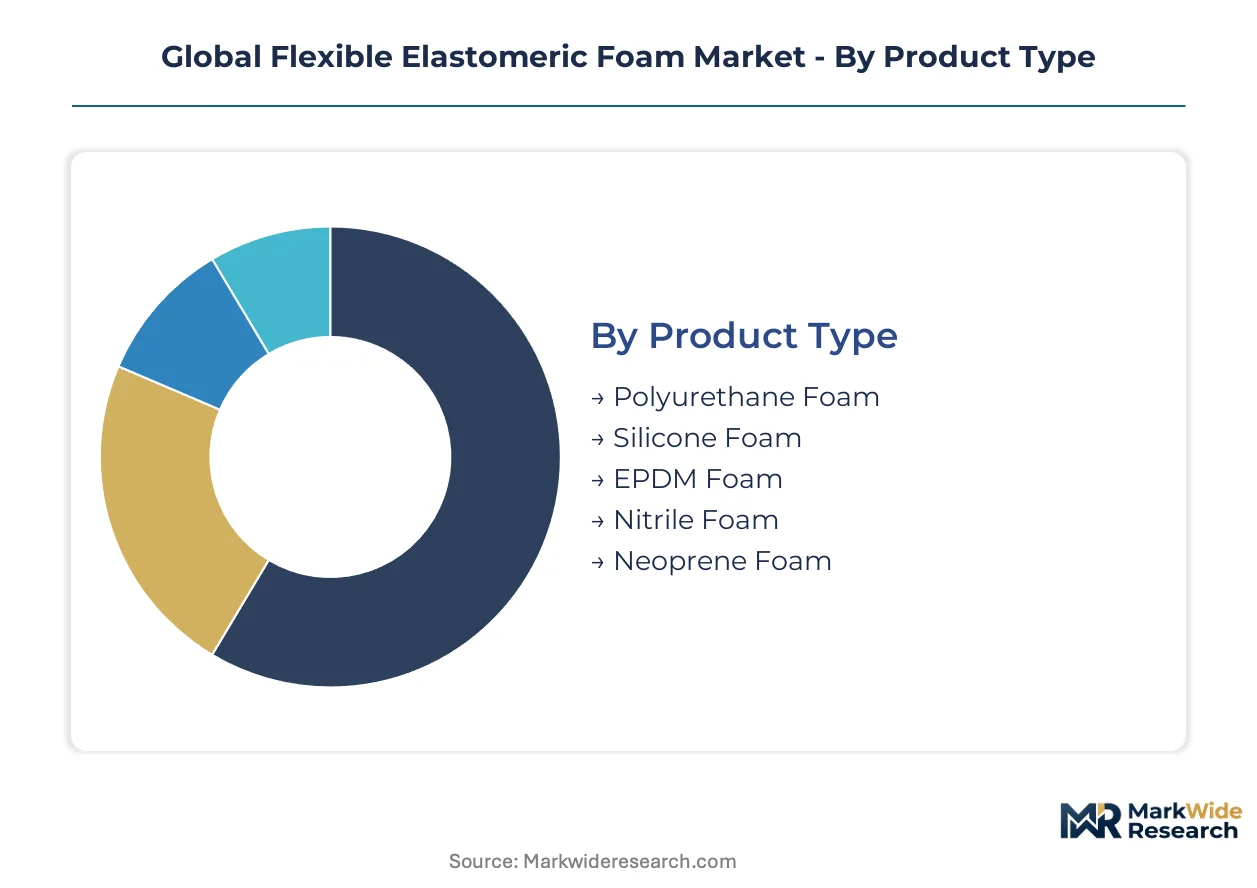
Segmentation in flexible elastomeric foam reveals how material chemistry, physical form, and end-use specifications fragment procurement patterns across industrial buyers. Specification engineers select foam substrates based on thermal stability thresholds, vapor transmission requirements, and regulatory compliance rather than commodity pricing alone.
Product Type:
Mature nitrile formulations dominate specification-grade procurement while emerging silicone variants capture premium thermal tolerance applications above 150°C.
- Nitrile Foam:Closed-cell nitrile butadiene rubber delivers thermal conductivity near 0.038 W/m·K with oil resistance critical for HVAC chilled water piping. Contractors across India's Mumbai-Bangalore corridor specify this grade for high-rise mechanical systems where GB 8624 and BIS emissions compliance is mandatory.
- Silicone Foam:Open and closed-cell silicone structures tolerate continuous exposure above 150°C with minimal compression set degradation. Electronics manufacturers in Germany and automotive sealing operations in Japan specify this grade where standard nitrile thermal ceilings fail.
- EPDM Foam:Ethylene-propylene-diene monomer copolymers provide UV stability and ozone resistance for outdoor construction exposure in Saudi Arabia's NEOM giga-projects.
- Polyurethane Foam:Lower density open-cell structures serve packaging and consumer padding applications where thermal performance is secondary to cost economics.
- Neoprene Foam:Chloroprene-based chemistry offers balanced oil, weather, and flame resistance for marine and industrial gasket applications in European REACH-compliant formulations.
Nitrile foam handles the majority of throughput; silicone foam is climbing the fastest on share as electronics and automotive thermal requirements intensify.
Application:
Cost tier stratification separates infrastructure-grade mechanical insulation from premium sealing and acoustic solutions across project specifications.
- HVAC Insulation:Closed-cell elastomeric pipe and duct insulation prevents condensation on chilled water surfaces while blocking vapor transmission. EU F-Gas Regulation phase-downs in Germany and France are accelerating specification of pre-certified low-smoke, zero-halogen formulations in district cooling retrofits.
- Automotive Sealing:Door, hood, and battery enclosure gaskets demand compression set resistance across temperature cycling from -40°C to 125°C. Vehicle manufacturers in China and Japan specify EPDM and silicone grades for electric vehicle thermal management systems.
- Acoustics Management:Open-cell polyurethane and melamine composites absorb airborne sound in commercial building interiors and transportation cabins.
- Packaging Solutions:Expanded polyethylene and polyurethane formats protect electronics and medical devices during distribution.
- Consumer Goods Padding:Molded polyurethane shapes provide ergonomic support in furniture, sporting equipment, and footwear applications.
HVAC insulation commands the largest procurement volumes; automotive sealing is expanding most quickly as electric vehicle production scales.
End User Industry:
Customer type differentiation separates project-based construction procurement from continuous manufacturing demand in vehicle and electronics sectors.
- Construction:Commercial and residential building projects specify roll and sheet formats for mechanical insulation, facade sealing, and acoustic treatment. EPC contractors in Saudi Arabia and the UAE are establishing direct procurement relationships with Shandong manufacturers for NEOM and Red Sea development tenders.
- Vehicle Manufacturing:Automotive OEMs and tier suppliers consume molded and extruded profiles for sealing, NVH management, and battery thermal isolation. China's MIIT enforcement of dual carbon goals is pushing manufacturers toward energy-efficient insulation materials in production facilities.
- Electronics:Device manufacturers specify silicone and specialty foam for gasketing, thermal interface materials, and shock protection in high-reliability applications.
- Sports Equipment:Footwear and protective gear producers mold polyurethane and EVA foams for impact absorption and comfort engineering.
- Furniture Production:Upholstery and bedding manufacturers source polyurethane block foam for cushioning applications with density specifications from 20-50 kg/m³.
Construction absorbs the greatest material tonnage; vehicle manufacturing is gaining share fastest as electric platform thermal management requirements proliferate.
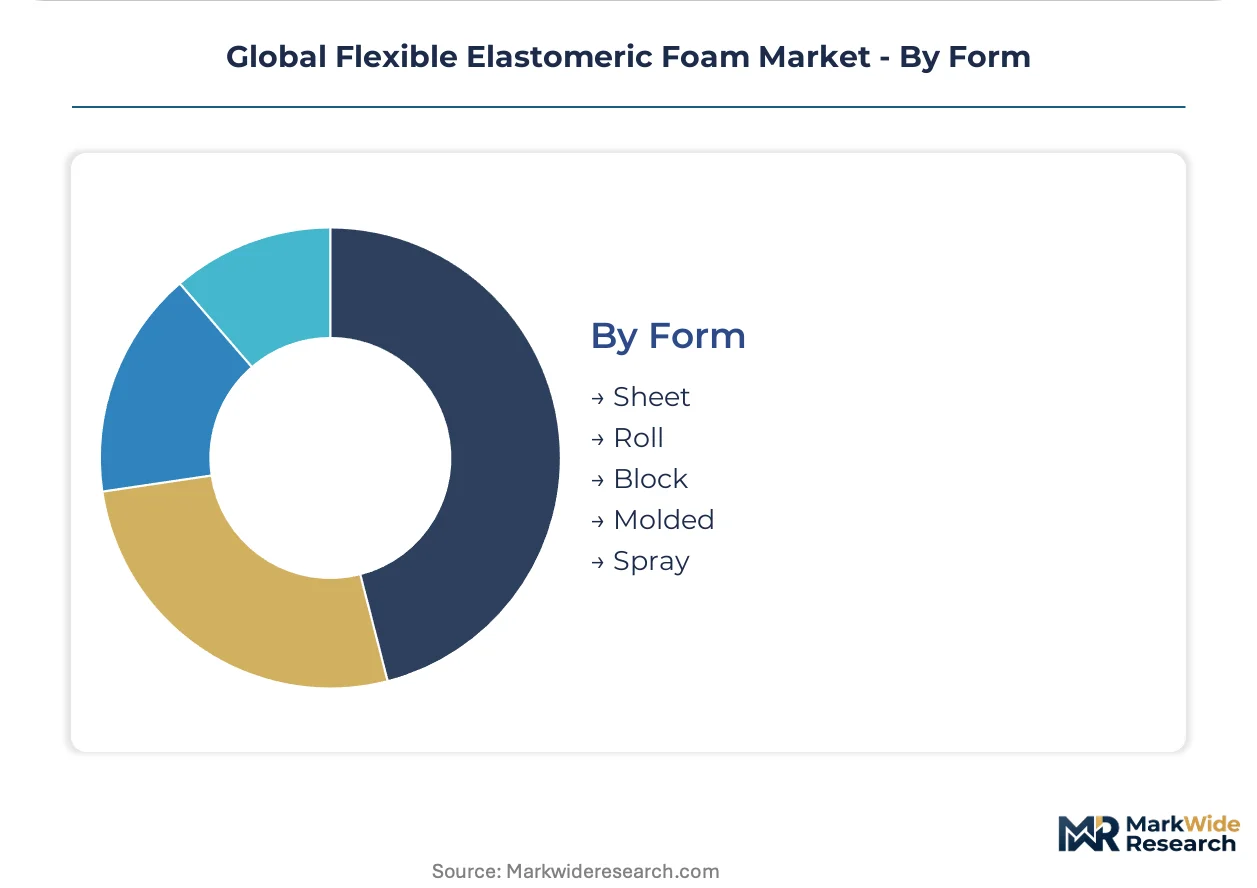
Form:
Supply concentration in continuous extrusion and batch molding operations determines geographic availability and lead time performance for format-specific procurement.
- Roll:Continuous extruded sheets wound to standard widths serve HVAC contractors and fabricators requiring custom-cut pipe insulation and duct lining. Manufacturing clusters in Shandong province ship roll formats to Middle Eastern contractors with just-in-time delivery coordination for giga-project sites.
- Sheet:Flat stock in standardized dimensions supports fabrication shops producing gaskets, pads, and laminated composites. European rubber processors maintain multi-regional compounding facilities to serve specification-grade sheet demand across Germany, France, and the Netherlands.
- Block:Bun stock for CNC machining and slabbing operations supplies furniture and packaging converters with raw material for shape cutting.
- Molded:Compression and injection molded components deliver complex geometries for automotive, electronics, and consumer goods sealing applications.
- Spray:Two-component polyurethane systems provide in-situ insulation and coating for irregular substrates in industrial maintenance and construction completion.
Roll and sheet formats together handle the majority of throughput; molded forms are advancing fastest on share as automotive and electronics specification complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in flexible elastomeric foam track divergent regulatory trajectories across manufacturing clusters. China maintains net export dominance in roll and sheet formats while European compounders import specialty grades for REACH-compliant formulations.
China
Shandong province manufacturers supply continuous extruded rolls to Middle Eastern contractors for NEOM-scale district cooling projects. MIIT enforcement of dual carbon goals accelerates domestic specification of low-smoke, zero-halogen formulations in Beijing-Tianjin-Hebei district networks. The Yangtze River Delta concentrates molding operations for automotive sealing exports to Japan and South Korea.
Germany
HVAC contractors specify pre-certified elastomeric insulation as F-Gas Regulation phase-downs tighten equipment efficiency mandates across Bavaria and North Rhine-Westphalia. ECHA REACH restrictions on halogenated flame retardants force compounders toward phosphorus-based alternatives. The Ruhr industrial corridor hosts multi-regional compounding facilities serving specification-grade sheet demand from Netherlands and France.
India
Infrastructure tenders along the Mumbai-Bangalore commercial construction corridor concentrate demand for BIS-certified polymer insulation in high-rise mechanical systems. The Bureau of Indian Standards mandate for polymer insulation products adds compliance layers for foreign manufacturers. Gujarat and Maharashtra fabrication clusters import raw roll stock from Shandong for local conversion and project delivery.
Saudi Arabia
NEOM and Red Sea giga-project tenders specify imported elastomeric insulation for district cooling infrastructure at unmatched Gulf Cooperation Council scale. SFDA building material safety standards intersect with international fire codes for low-smoke formulations. EPC contractors in Riyadh establish direct procurement relationships with Chinese and European manufacturers, bypassing regional distribution tiers.
United States
Commercial building retrofits in Texas and California drive specification of closed-cell foam for chilled water piping efficiency upgrades. EPA and OSHA workplace exposure standards influence formulation chemistry for domestic manufacturing. The Southeast industrial corridor hosts fabrication operations converting imported sheet stock for HVAC contractor networks.
Global Flexible Elastomeric Foam Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated compounders with multi-jurisdiction certification capabilities. Three strategic archetypes dominate: polymer specialists with captive compounding expertise, scale-driven roll manufacturers with just-in-time logistics networks, and regional fabricators with project-specific conversion capabilities. Competitive positioning depends on backward integration into rubber processing and upstream control over formulation chemistry.
Within the specification-grade tier, Armacell International S.A. and Saint-Gobain occupy positions anchored by polymer compounding expertise and vertically integrated rubber processing. Huamei Energy-saving Technology Group Co., Ltd. exemplifies the scale-driven archetype with manufacturing concentration in Shandong province. These three entities represent divergent competitive vectors: European regulatory compliance leadership, Chinese manufacturing scale, and multi-regional specification capture.
| Leading Market Players |
|---|
| Saint-Gobain |
| Huamei Energy-saving Technology Group Co., Ltd. |
| Armacell International S.A. |
| NMC SA |
| Zotefoams plc |
| L'Isolante K-FLEX S.p.A. |
| Hira Industries LLC |
| Jinan Retek Industries Inc. |
| Aeroflex USA, Inc. |
| Others |
Supply & Pricing Matrix
Shandong province's continuous extrusion capacity concentration grants Chinese roll manufacturers asymmetric pricing power over Middle Eastern EPC contractors bidding NEOM-scale district cooling packages. Nitrile butadiene rubber feedstock volatility transmits directly into margin compression for European compounders reformulating around REACH phosphorus-based flame retardant mandates.
Pricing Analysis
Standard nitrile formulations trade at substantial discounts to silicone grades engineered for 150°C-plus electronics sealing, while next-generation low-smoke zero-halogen compounds command certification premiums above baseline HVAC specifications. Three-tier pricing structure across specification-grade, performance-tier, and commodity bulk levels reflects divergence in GB 8624 and BIS compliance investment. Pricing pressure stems from crude oil derivative volatility in NBR and EPDM feedstocks. Project contractors in India's Mumbai-Bangalore corridor exhibit highest price sensitivity due to tender-based procurement, while German HVAC engineers prioritize pre-certified formulations with minimal cost elasticity.
Supply Chain Analysis
Tariff exposure between China and Saudi Arabia remains minimal under Gulf Cooperation Council trade frameworks, though BIS certification timelines for Indian market entry extend working capital cycles for Shandong exporters. Manufacturing concentrates in China, Germany, and India for distinct format tiers. Raw material dependencies center on acrylonitrile monomer, ethylene-propylene feedstock, and phosphorus-based flame retardant additives. Single-source vulnerability concentrates in Shandong roll extrusion clusters serving Middle Eastern giga-projects. Distribution runs through direct procurement relationships displacing traditional regional stockists in Saudi Arabia and UAE construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPC contractor consolidation around NEOM-scale developments is shifting procurement leverage toward volume-aggregated buyers capable of dictating custom roll dimensions and just-in-time delivery terms. Specification-grade compounders face compressed margins as direct procurement bypasses distribution markups.
For Market Incumbents: Insulate specification-grade positioning by accelerating multi-jurisdiction certification completion ahead of India's BIS enforcement deadlines and BIS-mandated compliance timelines. Captive compounding capacity in the Ruhr industrial corridor defends margin structure against Shandong volume competition. Prioritize phosphorus-based formulation R&D to preempt REACH regulatory displacement of halogenated chemistry. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with Singapore and Jakarta HVAC retrofit demand outpacing incumbent specification coverage. India's Gujarat and Maharashtra fabrication clusters offer white-space for BIS-certified roll conversion operations serving domestic infrastructure tenders. Target direct procurement relationships with tier-two EPC contractors excluded from NEOM-scale volume allocations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with captive phosphorus-based flame retardant formulation capabilities and multi-jurisdiction certification infrastructure. Long-term viability over the next decade rests on backward integration into rubber processing and upstream chemical synthesis. Watch for inflection signals in India's BIS certification completion rates among foreign manufacturers as early indicator of market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Investment | Parallel GB 8624, BIS, and REACH compliance accelerates product launch cycles for specification-grade nitrile formulations. |
| Phosphorus-Based Formulation Transition | ECHA REACH restrictions on halogenated chemistry force compounders toward mineral filler and intumescent alternatives. |
| Direct Procurement Channel Development | EPC contractors in Saudi Arabia bypass regional stockists to secure just-in-time roll delivery for NEOM infrastructure. |
| Sensor-Embedded Product Integration | IoT-enabled thermal monitoring layers shift contractor revenue from product sales to performance contracts. |
| Shandong Capacity Expansion | Continuous extrusion scale advantages consolidate export dominance to Middle Eastern district cooling projects. |
Research Methodology
Cross-validation between primary interviews with HVAC specification engineers, EPC procurement directors, and polymer formulation chemists and secondary validation through customs trade data, MIIT enforcement notices, and ECHA regulatory guidance anchors the qualitative findings. Technical R&D directors at rubber processing facilities and district cooling project managers in Singapore and Dubai provided operational perspective. SEC filings from vertically integrated compounders, BIS certification registries, and GB standards documentation supplied quantitative grounding. Bottom-up volume modeling triangulates against top-down construction spend allocation across the analysis window.
Calibration against historical nitrile foam penetration rates in European F-Gas Regulation compliance cycles and Chinese dual carbon goal enforcement phases refined projection parameters. Segmentation dimensions span product chemistry tier, application thermal threshold, end-use industry procurement pattern, and geographic regulatory cluster. CAGRs derive from elasticity-adjusted demand functions incorporating feedstock price volatility and certification timeline lag effects. Forecast inputs include district cooling infrastructure bid pipelines and electric vehicle platform thermal management specifications.
Stress conditions across acrylonitrile monomer price bands, REACH substitution threshold uncertainty, and Indian BIS enforcement timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation pacing and construction tender award velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Medical Styrenic Block Copolymer (SBC) Market
Elastomeric Membrane
Global Elastomeric Coating Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Cold Cast Elastomers Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Stretchable Conductive Material Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
Polyurethane Elastomers Market