
 Industrial PU Elastomer Market | 2026-2036
Industrial PU Elastomer Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial PU Elastomer Market Outlook
Maintenance and performance-monitoring service contracts is repositioning how industrial buyers procure polyurethane elastomer systems, shifting capital expenditure toward lifecycle-cost models. Covestro AG leverages its global technical service network to anchor long-term supply relationships with tier-one automotive seal manufacturers. BASF SE sustains R&D intensity in aliphatic polyurethane grades for outdoor and UV-exposed applications. Wanhua Chemical dominates MDI supply integration in Asia, controlling upstream isocyanate flows that determine regional elastomer pricing and availability.
Industrial polyurethane elastomers are thermoset or thermoplastic polymers formed by reacting diisocyanates with polyols and chain extenders, yielding Shore hardness values from 60A to 75D and tensile strengths exceeding 40 MPa in cast formulations. These materials absorb impact, resist abrasion, and maintain elasticity across temperature extremes from minus forty to one hundred twenty degrees Celsius, serving as structural alternatives to rubber and metal in load-bearing industrial components. Polyurethane Elastomers within the product type category generate the deepest margin pools due to formulation complexity and performance certification requirements. Seals and Gaskets among applications command premium pricing from aerospace and hydraulics OEMs demanding FMVSS or SAE compliance. Molded Parts is growing fastest as automated injection molding of thermoplastic polyurethane reduces cycle times and scrap rates versus cast processes.
EPA regulations on methylene diphenyl diisocyanate workplace exposure limits and REACH authorization requirements for certain aromatic amine curatives are elevating compliance costs while accelerating aliphatic and bio-based polyol development. ISO 9001 and IATF 16949 certification requirements from automotive OEMs restrict qualified supplier pools, concentrating volume among vertically integrated compounders. FDA food-contact approvals for polyurethane processing equipment further segment addressable markets by application hygiene class. Buyers must monitor regulatory divergence between California's Proposition 65 warning requirements and EU REACH restriction proposals to avoid stranded inventory in cross-border supply chains.
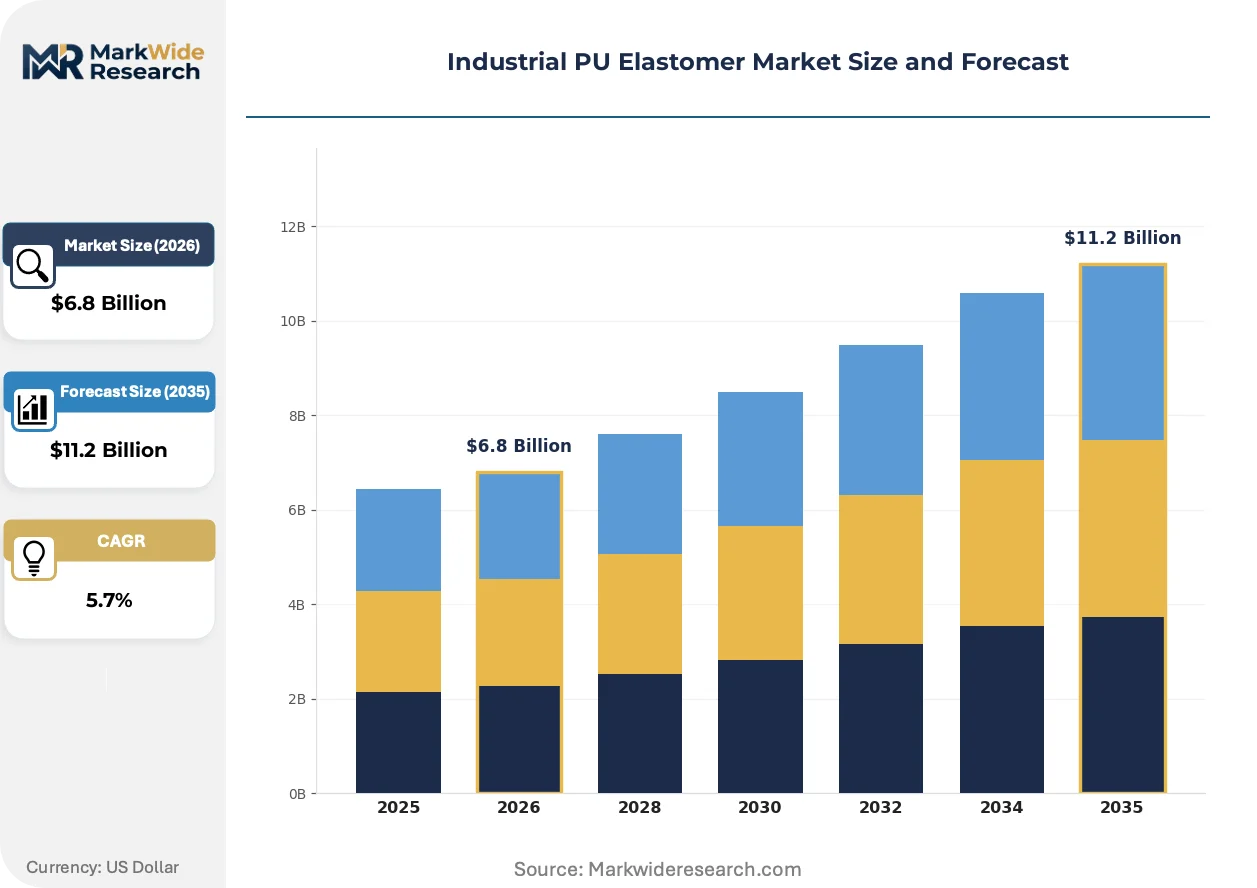
Market Dynamics
Automotive electrification is fundamentally recalibrating material specifications for polyurethane elastomers, as battery thermal management systems and electric motor mounts demand vibration-damping compounds that withstand higher thermal loads and electromagnetic interference than conventional internal combustion applications.
Growth Catalysts
- EPA workplace exposure limits on methylene diphenyl diisocyanate:These tightened standards are accelerating reformulation toward aliphatic polyurethane systems that eliminate aromatic amine curatives while maintaining Shore hardness performance.
- Automotive sealing applications:Electric vehicle battery pack gaskets and charging connector seals specify cast polyurethane for dielectric strength and compression set resistance under thermal cycling.
- China's dual carbon goals:Domestic processors are retrofitting production lines to reduce solvent-based processing emissions, expanding demand for waterborne polyurethane dispersion technologies.
Market Restraints
- MDI supply concentration:Asian isocyanate production dominates global feedstock availability, exposing compounders to freight cost volatility and geopolitical supply interruptions.
- REACH authorization timelines:ECHA's substance evaluation delays for certain chain extenders extend qualification periods by eighteen to twenty-four months, freezing new product introductions.
- Thermoplastic vulcanizate substitution:Automotive underhood applications increasingly specify TPVs for cost-sensitive components where polyurethane's performance premium cannot be recovered.
Strategic Opportunities
- India's PLI scheme for advanced materials:Domestic manufacturing incentives are attracting polyurethane system houses to establish compounding facilities serving automotive and footwear export markets.
- Wind turbine blade leading edge protection:Cast polyurethane erosion shields are displacing thermoset epoxy coatings in offshore installations requiring impact resistance and field repairability.
- FDA food-contact equipment certification:Processing machinery for dairy and beverage applications requires polyurethane components meeting migration limits, segmenting suppliers by hygiene class qualification.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required for isocyanate-polyol stoichiometry and cure kinetics is concentrating among aging technical workforces at legacy compounders.
- IATF 16949 certification burden:Automotive OEM qualification audits demand documented process control across eighteen months of production history, freezing new entrants from tier-one supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial PU Elastomer Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Polyurethane Coatings, Polyurethane Adhesives, Polyurethane Elastomers End User: Automotive, Aerospace, Construction, Footwear Application: Seals, Gaskets, Coatings, Molded Parts Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Covestro AG, BASF SE, Wanhua Chemical, Huntsman International LLC, Mitsui Chemicals, INOAC Corporation, Trelleborg, The Lubrizol Corporation, Lanxess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial PU Elastomer Market Strategic Shifts
Reactive extrusion and in-situ polymerization techniques are compressing the traditional separation between thermoplastic processing speed and thermoset performance characteristics, enabling hybrid material architectures that respond to real-time load conditions.
Waterborne polyurethane dispersions are overtaking solvent-based cast systems in industrial coating applications where volatile organic compound emissions face tightening MEE enforcement in China and EPA regional haze regulations in the United States. Furniture and flooring manufacturers in Zhejiang province and North Carolina's Piedmont corridor are retrofitting spray lines to accommodate aqueous systems with equivalent abrasion resistance. This transition is compressing margins for conventional solvent-based compounders while rewarding dispersion technology licensors with formulation licensing revenue.
ECHA's REACH restriction proposals for certain aromatic diisocyanates are forcing European compounders to validate aliphatic polyurethane grades for outdoor infrastructure applications previously served by cost-optimized aromatic systems. Wind energy OEMs in Denmark and Germany are specifying aliphatic elastomers for blade root bearings and pitch system bushings exposed to ultraviolet degradation and salt spray. Suppliers without validated aliphatic portfolios are exiting the European renewable energy supply chain.
Maintenance contracts bundled with material supply are displacing spot purchasing for high-volume automotive seal manufacturers seeking to outsource compound storage, mixing, and viscosity monitoring. Tier-one suppliers in Stuttgart and Detroit are signing five-year service agreements that transfer capital equipment responsibility to polyurethane system houses. This model concentrates procurement authority among buyers with lifecycle cost analytics capabilities.
Industrial PU Elastomer Market Segmentation
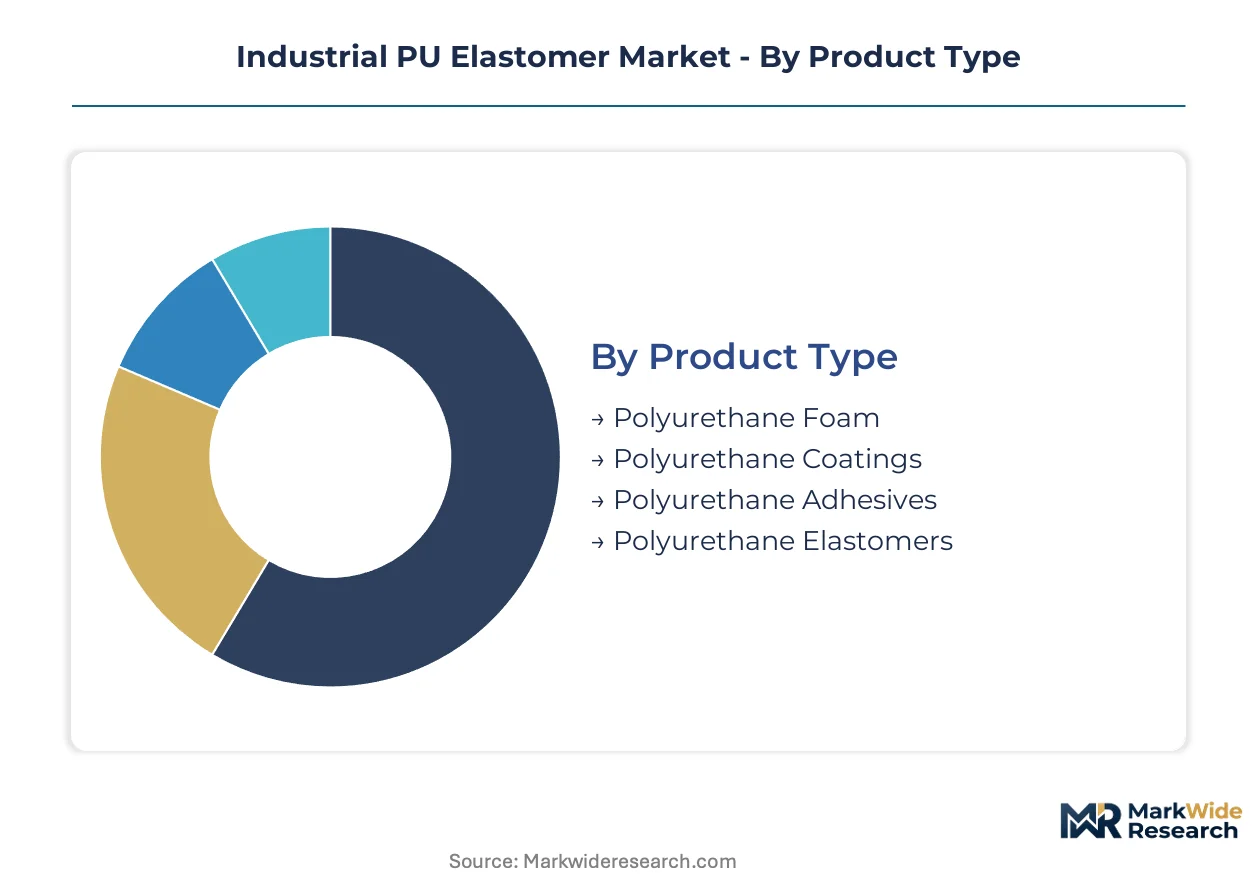
Segmentation in industrial polyurethane elastomers reveals how formulation complexity, certification requirements, and procurement models fragment addressable markets. Buyers sort across performance tiers, end-use specifications, and supply chain configurations that determine margin capture and supplier qualification barriers.
Product Type:
Customization intensity spans from commodity foams to engineered elastomers requiring stoichiometric precision and cure kinetics expertise.
- Polyurethane Elastomers:Thermoset or thermoplastic polymers formed by reacting diisocyanates with polyols and chain extenders, yielding Shore hardness values from 60A to 75D. Automotive sealing and industrial component manufacturers specify these grades for load-bearing applications where compression set resistance and abrasion tolerance justify formulation premiums. REACH authorization timelines for aromatic amine curatives extend qualification periods, freezing new product introductions among European compounders.
- Polyurethane Foam:Cellular structures created through controlled gas expansion during polymerization, delivering density gradients from flexible to rigid systems. Construction insulation and packaging sectors in China and the United States absorb volume, though margin compression from petrochemical feedstock volatility limits supplier differentiation.
- Polyurethane Coatings:Film-forming systems providing substrate protection through crosslinked polymer networks. Industrial maintenance and transportation OEMs specify these for corrosion resistance.
- Polyurethane Adhesives:Bonding systems leveraging isocyanate reactivity with substrate moisture or polyol components. Footwear assembly and composite manufacturing drive specification.
Leading the category by volume: Polyurethane Foam. Growing fastest: Polyurethane Elastomers.
End User:
Certification intensity separates aerospace and automotive buyers demanding IATF 16949 or AS9100 compliance from construction and footwear purchasers prioritizing cost efficiency.
- Automotive:Battery pack gaskets, charging connector seals, and electric motor mounts specify cast polyurethane for dielectric strength and thermal cycling resistance. Stuttgart and Detroit tier-one suppliers are signing five-year service agreements that transfer compound storage and viscosity monitoring to system houses. EPA workplace exposure limits on methylene diphenyl diisocyanate accelerate reformulation toward aliphatic systems.
- Aerospace:Hydraulic seals, cabin pressure gaskets, and vibration isolation components require FMVSS or SAE compliance with documented batch traceability. Salt Lake City and Toulouse clusters concentrate demand for fuel-resistant grades.
- Construction:Expansion joint fillers, waterproofing membranes, and structural bonding applications specify cost-optimized aromatic systems.
- Footwear:Midsole cushioning and outsole durability applications in Vietnam and Indonesia export markets favor thermoplastic polyurethane injection molding.
Volume concentrates in Automotive. Steepest expansion trajectory: Aerospace as electrification and urban air mobility create new material specifications.
Application:
Processing method divides the category—compression molding and casting serve low-volume precision components while injection molding captures high-volume standardized parts.
- Seals and Gaskets:Precision-molded components maintaining elastic recovery under compression set and fluid exposure. Aerospace and hydraulics OEMs command premium pricing through FMVSS or SAE compliance requirements. Offshore wind turbine installations in Denmark specify these for blade root bearings exposed to salt spray degradation.
- Molded Parts:Automated injection molding of thermoplastic polyurethane reduces cycle times and scrap rates versus cast processes. Automotive underhood and consumer electronics housings absorb volume in Zhejiang province and Guadalajara manufacturing corridors.
- Coatings:Surface protection systems applied through spray or dip processes. Waterborne polyurethane dispersions overtake solvent-based systems under China's MEE enforcement.
Revenue pools deepest in Seals and Gaskets. Climbing the fastest: Molded Parts as TPU processing automation penetrates Asian manufacturing.
Distribution Channel:
Relationship intensity varies from transactional wholesale to embedded technical service contracts that shift capital expenditure toward lifecycle-cost models.
- Direct Sales:System houses maintain field technical service networks for compound storage, mixing equipment, and viscosity monitoring. Covestro AG anchors long-term supply relationships through this channel with tier-one automotive seal manufacturers in Germany and Michigan.
- Distributors:Regional inventory positioning serves mid-volume compounders lacking bulk storage infrastructure. Indian and Brazilian processors rely on this channel for MDI and polyol blending kits.
- Online Retail:Small-lot specialty grades and tooling resins for prototyping and repair applications.
- Wholesale:Commodity TPU pellets and prepolymer systems for high-volume processors with captive compounding capability.
Direct Sales commands the highest value per ton. Expanding most quickly: Distributors as India's PLI scheme attracts system houses to establish regional compounding facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta around Shanghai anchors polyurethane elastomer demand through Wanhua Chemical's integrated MDI production and the dense concentration of automotive seal manufacturers in Zhejiang province.
China
Domestic processors in Jiangsu and Shandong provinces consume cast elastomer grades for construction machinery and wind turbine components. MEE enforcement of volatile organic compound limits is accelerating waterborne polyurethane dispersion adoption across furniture manufacturing clusters. Qingdao and Yantai in Shandong Peninsula host specialized compounders serving offshore wind installations with erosion-resistant cast systems.
United States
EPA workplace exposure limits on methylene diphenyl diisocyanate are forcing reformulation investments among compounders supplying Detroit-area automotive tier-ones. The Piedmont corridor in North Carolina concentrates furniture and flooring manufacturers retrofitting spray lines for aqueous polyurethane systems. Michigan-based seal manufacturers are signing five-year service agreements that transfer compound storage and viscosity monitoring to system houses.
Germany
ECHA REACH authorization timelines for aromatic amine curatives extend qualification periods for European compounders serving Stuttgart automotive clusters. The Cologne-Düsseldorf-Ruhr industrial belt maintains dense networks of technical service providers for polyurethane system supply. Bavarian wind energy OEMs are specifying aliphatic elastomers for blade root bearings exposed to ultraviolet degradation and salt spray.
India
The PLI scheme for advanced materials is attracting polyurethane system houses to establish compounding facilities serving automotive and footwear export markets. Tamil Nadu and Gujarat processors rely on distributor channels for MDI and polyol blending kits. Maharashtra's automotive corridors near Pune and Chennai's manufacturing belt are absorbing thermoplastic polyurethane injection molding capacity for underhood components.
Japan
METI guidelines on chemical substance management are elevating documentation requirements for isocyanate handling in Osaka-Kobe industrial zones. The Nagoya-Chubu corridor concentrates precision molded parts suppliers serving automotive and electronics OEMs. Kyushu-based processors are qualifying aliphatic grades for outdoor infrastructure applications previously served by cost-optimized aromatic systems.
Industrial PU Elastomer Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the polyurethane elastomer value chain. Integrated isocyanate manufacturers control upstream feedstock flows that determine regional pricing and availability, while specialized compounders compete on formulation expertise and certification portfolios. Three archetypes dominate: vertically integrated chemical conglomerates with captive MDI supply, independent system houses with technical service networks, and regional processors focused on specific end-use segments. Competitive moves concentrate on backward integration into polyol production and geographic expansion through distributor partnerships in emerging manufacturing corridors.
Among European chemical conglomerates, Covestro AG and BASF SE occupy positions anchored by global technical service networks and aliphatic polyurethane R&D intensity. Wanhua Chemical represents the Asia-Pacific integrated model with upstream MDI control determining regional elastomer pricing. These three exemplify how feedstock integration and certification depth separate premium-tier suppliers from commodity compounders competing on cycle time and scrap rate reduction.
| Leading Market Players |
|---|
| Covestro AG |
| BASF SE |
| Wanhua Chemical |
| Huntsman International LLC |
| Mitsui Chemicals |
| INOAC Corporation |
| Trelleborg |
| The Lubrizol Corporation |
| Lanxess |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals gate qualified supply and premium-tier pricing access for industrial polyurethane elastomers, as domestic processors retrofit solvent-based lines to meet MEE enforcement standards while European REACH authorization timelines freeze new aromatic system introductions. This sustainability-driven bifurcation concentrates margin capture among compounders with validated aliphatic portfolios and waterborne dispersion capabilities.
Pricing Analysis
Value-based pricing anchored to equipment uptime guarantees dominates service-contract relationships between system houses and automotive tier-one seal manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates IATF 16949-certified aliphatic grades from commodity aromatic formulations and unqualified import alternatives. Price differentiation rests on certification depth and technical service bundling rather than raw material cost pass-through alone. Cost compression in standard-grade cast elastomers is intensifying because thermoplastic vulcanizate substitution in automotive underhood applications erodes volume leverage.
Supply Chain Analysis
India's PLI scheme for advanced materials is reshaping sourcing patterns by incentivizing domestic compounding capacity for automotive and footwear export markets. Feedstock availability draws from Chinese MDI production concentration, German polyol specialty chemical networks, and South Korean TPU pellet manufacturing. Single-source vulnerability in Asian isocyanate supply exposes compounders to freight cost volatility and geopolitical interruption. Distribution runs through direct technical service contracts for high-volume automotive accounts and regional distributors for mid-tier processors lacking bulk storage infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial polyurethane elastomer market functions as a vertical-integration race where upstream MDI control and downstream formulation expertise determine margin capture. Players are pursuing captive isocyanate supply as the decisive lever to secure feedstock availability and pricing power.
For Market Incumbents: To counter thermoplastic vulcanizate substitution in cost-sensitive automotive applications, deepen backward integration into specialty polyol production and expand aliphatic certification portfolios for European renewable energy OEMs. Prioritize five-year service agreements that transfer compound storage and viscosity monitoring responsibility to anchor tier-one relationships. For New Entrants and Emerging Players: Distributor partnerships in India's Tamil Nadu and Gujarat corridors offer the most penetrable entry path for polyurethane system houses seeking to serve PLI-incentivized automotive and footwear export markets. Target waterborne dispersion technology licensing to furniture manufacturers in Zhejiang province facing MEE enforcement retrofit requirements. Lead with formulation expertise in aliphatic grades where REACH authorization timelines have frozen incumbent product pipelines. For Investors and Strategic Acquirers: ECHA's REACH restriction proposals for aromatic diisocyanates are the leading indicator that aliphatic-grade compounders will command scarcity premiums in European outdoor infrastructure and wind energy supply chains. The five-to-ten-year viability window favors acquisition targets with validated aliphatic portfolios and embedded technical service networks over commodity aromatic processors. Watch for IATF 16949 certification completion announcements as the inflection signal for tier-one automotive qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polyols | Captive polyol supply secures formulation flexibility for aliphatic grade development at BASF SE. |
| Waterborne Dispersion Technology Licensing | Formulation licensing revenue captures margin from Chinese furniture manufacturers under MEE enforcement. |
| Aliphatic Certification Portfolio Expansion | Validated aliphatic grades qualify compounders for Bavarian wind turbine OEM blade root bearing specifications. |
| Five-Year Service Agreement Structuring | Lifecycle cost contracts transfer capital equipment responsibility from Stuttgart tier-ones to system houses. |
| Regional Compounding Facility Establishment | Domestic Indian capacity serves PLI-incentivized automotive corridors near Pune and Chennai. |
Study Parameters
Independent corroboration across polyurethane system house technical directors, automotive tier-one procurement leads, and chemical distribution channel partners underwrites the qualitative findings in this study. Primary interviews with plant managers at Zhejiang province furniture manufacturers, R&D directors at German wind energy OEMs, and regulatory affairs specialists navigating REACH authorization timelines were cross-referenced against secondary validation from customs and trade data, SEC 10-K filings of listed chemical conglomerates, and ACC/Cefic industry reports. Bottom-up volume estimates from segmented end-use consumption patterns were reconciled with top-down market sizing derived from isocyanate production and trade flow analysis.
Rate-of-change decomposition across the analysis window separates volume growth into automotive electrification-driven specification shifts, construction sector cyclicality, and regional regulatory compliance retrofit cycles. Segmentation dimensions modeled include product type tier, end-use industry certification intensity, application processing method, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs incorporate MDI feedstock pricing trajectories and IATF 16949 certification pipeline visibility.
Caveats apply where ECHA substance evaluation delays, EPA methylene diphenyl diisocyanate exposure limit revisions, or sudden MDI supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory timeline adherence and automotive platform electrification penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Middle-East and Africa Fluoroelastomers Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market