
 Medical Grade Silicone Rubber Market | 2026-2036
Medical Grade Silicone Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Grade Silicone Rubber Market Intelligence
The EU Medical Device Regulation is pivoting the cost-of-entry calculus for silicone suppliers seeking European market access. Dow leverages backward integration into siloxane feedstocks to sustain margin resilience under stricter traceability mandates. Wacker Chemie AG anchors its position through specialized liquid silicone rubber grades that dominate high-consistency medical tubing applications. Shin-Etsu Chemical Co., Ltd. differentiates via proprietary platinum-catalyzed curing systems that command premium positioning in implantable device segments.
Medical grade silicone rubber denotes a platinum-cured or peroxide-cured polydimethylsiloxane elastomer meeting USP Class VI or ISO 10993 biocompatibility standards, with volatile content below 0.5% and Shore A hardness ranging from 10 to 80 depending on implant duration requirements. Its primary purpose centers on delivering inert, thermally stable sealing and flexing functions within devices contacting human tissue or physiological fluids for periods exceeding 30 days. Liquid silicone rubber formulations lead volume contribution due to their suitability for intricate micro-molding of surgical components and respiratory masks, while extruded silicone tubing captures expanding share in minimally invasive instrument sheathing where lumen precision dictates performance. Coated variants concentrate margin pools in drug-eluting stent substrates and antimicrobial wound dressing layers where functional surface chemistry commands pricing premiums.
FDA 21 CFR Part 177.2600 repeat-use rubber articles provisions and ISO 10993-1 biological evaluation frameworks shape material selection protocols across implant and device categories, with FDA Master File submissions now requiring extractables profiling under updated guidance. EMA's MDR Annex I general safety and performance requirements further tighten post-market surveillance obligations for silicone-containing permanent implants. REACH candidate list scrutiny of siloxane environmental persistence is forcing reformulation investments in D4/D5-free polymerization routes. Stakeholders must monitor evolving biocompatibility testing paradigms and polymer chemistry roadmaps to align R&D allocation with regulatory trajectory rather than current compliance baselines.
Market Dynamics
Platinum-catalyzed curing systems are compressing batch-to-batch variability tolerances while FDA extractables profiling requirements extend qualification timelines, forcing manufacturers to choose between captive polymerization investments and qualified supplier dependence.
Growth Catalysts
- ISO 10993-1 Biological Evaluation:Updated testing frameworks for permanent implant categories are expanding addressable device segments for certified silicone suppliers.
- Germany Precision Medical Device Clusters:Concentrated catheter and prosthetic manufacturing in Baden-Württemberg and Bavaria sustains specialized formulation demand.
- Liquid Silicone Rubber Micro-Molding:Intricate surgical component geometries are driving tooling investments in multi-cavity cold runner systems.
Market Restraints
- Siloxane Feedstock Concentration:D4/D5 cyclosiloxane supply chains concentrate among three integrated chemical majors, creating input cost volatility exposure.
- REACH Candidate List Scrutiny:ECHA evaluation of siloxane environmental persistence is forcing reformulation investments ahead of restriction timelines.
- Thermoplastic Elastomer Substitution:TPE advances in short-duration device applications are compressing silicone's addressable range in sub-30-day contact segments.
Strategic Opportunities
- Drug-Eluting Stent Substrates:Functionalized silicone coatings for controlled pharmaceutical release represent unpenetrated margin pools in cardiovascular devices.
- EMA MDR Annex I Compliance Services:Post-market surveillance documentation represents adjacent revenue streams for formulation houses with regulatory expertise.
- Antimicrobial Wound Dressing Layers:Silver-ion or chlorhexidine-impregnated silicone laminates are opening new therapeutic application categories.
Industry Challenges
- Extractables Profiling Expertise:FDA Master File submissions now require analytical chemistry capabilities scarce among mid-scale compounders.
- Cleanroom Manufacturing Scale-Up:ISO 14644 Class 7 expansion for medical tubing extrusion demands capital deployment with extended qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Grade Silicone Rubber Market |
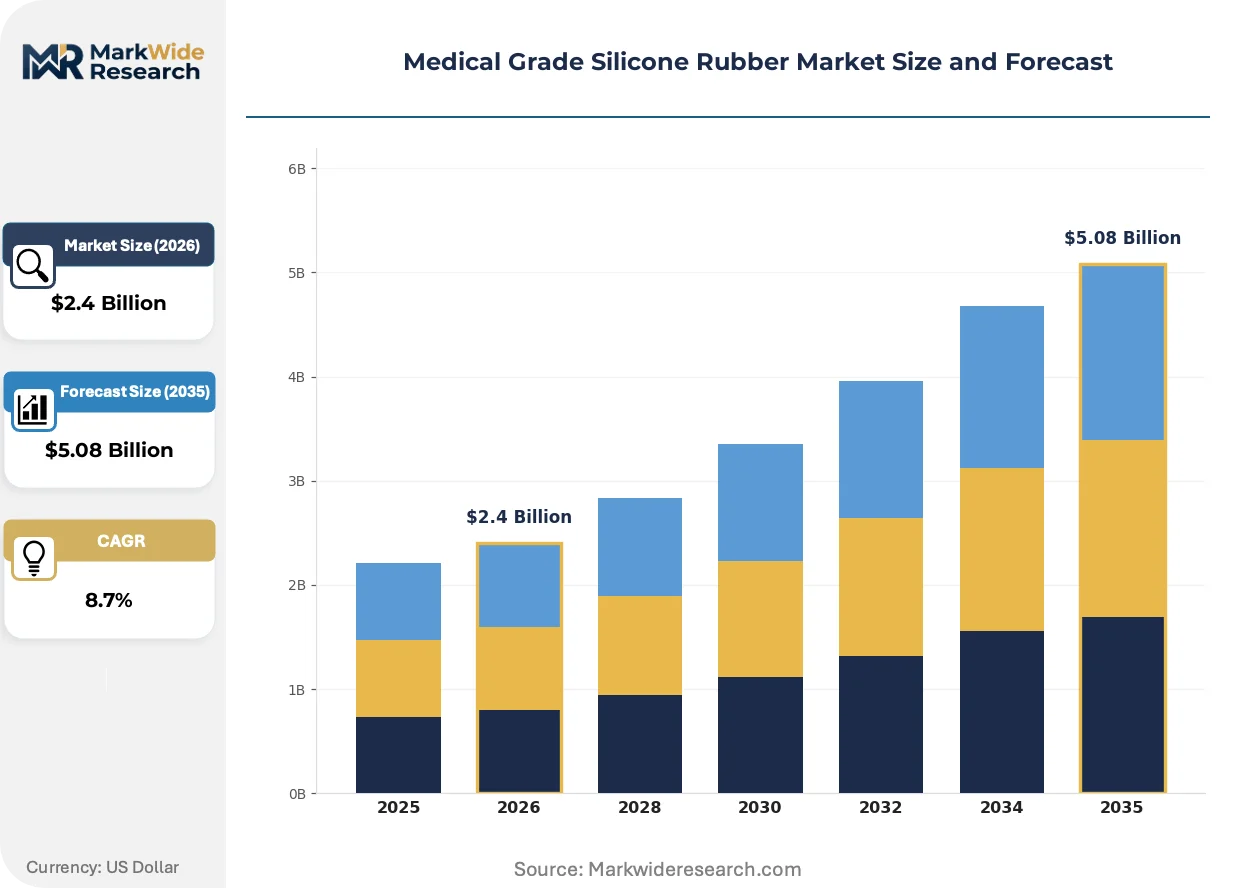
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded, Molded, Liquid Silicone, Coated Application: Medical Devices, Implants, Seals, Gaskets End User: Hospitals, Clinics, Manufacturers, Labs Form: Sheets, Tubes, Parts, Blocks |
| Companies Covered | Dow, Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials, Elkem ASA, Avantor, Inc., KCC Silicone Corporation, Zhejiang Xin’an Chemical Group Co., Ltd., Applied Silicone Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Grade Silicone Rubber Market Strategic Shifts & Innovations
Additive manufacturing of silicone lattice structures is dissolving traditional molding constraints, enabling patient-specific implant geometries that were economically unfeasible under conventional tooling economics.
Room-temperature vulcanizing platinum-catalyzed systems are decentralizing production geography by eliminating high-temperature post-cure requirements. Regional device manufacturers in secondary medical technology hubs are adopting these formulations to bypass centralized compounding dependencies. Distributed manufacturing networks are compressing supply lead times for time-critical implant components.
EMA's MDR implementation is restructuring supplier qualification protocols across European implant markets. Biological evaluation documentation requirements now cascade through three tiers of the supply chain, forcing raw material vendors to assume liability exposure previously held by finished device manufacturers. German notified bodies are experiencing qualification backlog extending submission-to-approval intervals.
Hospital procurement consortia are consolidating silicone component purchasing across multi-year framework agreements. Group purchasing organizations are displacing spot-market transactions for standard-grade tubing and seals, compressing supplier margins while guaranteeing volume commitments. This concentration is most visible in Benelux and Nordic healthcare systems with centralized tendering authorities.
Medical Grade Silicone Rubber Market Segmentation
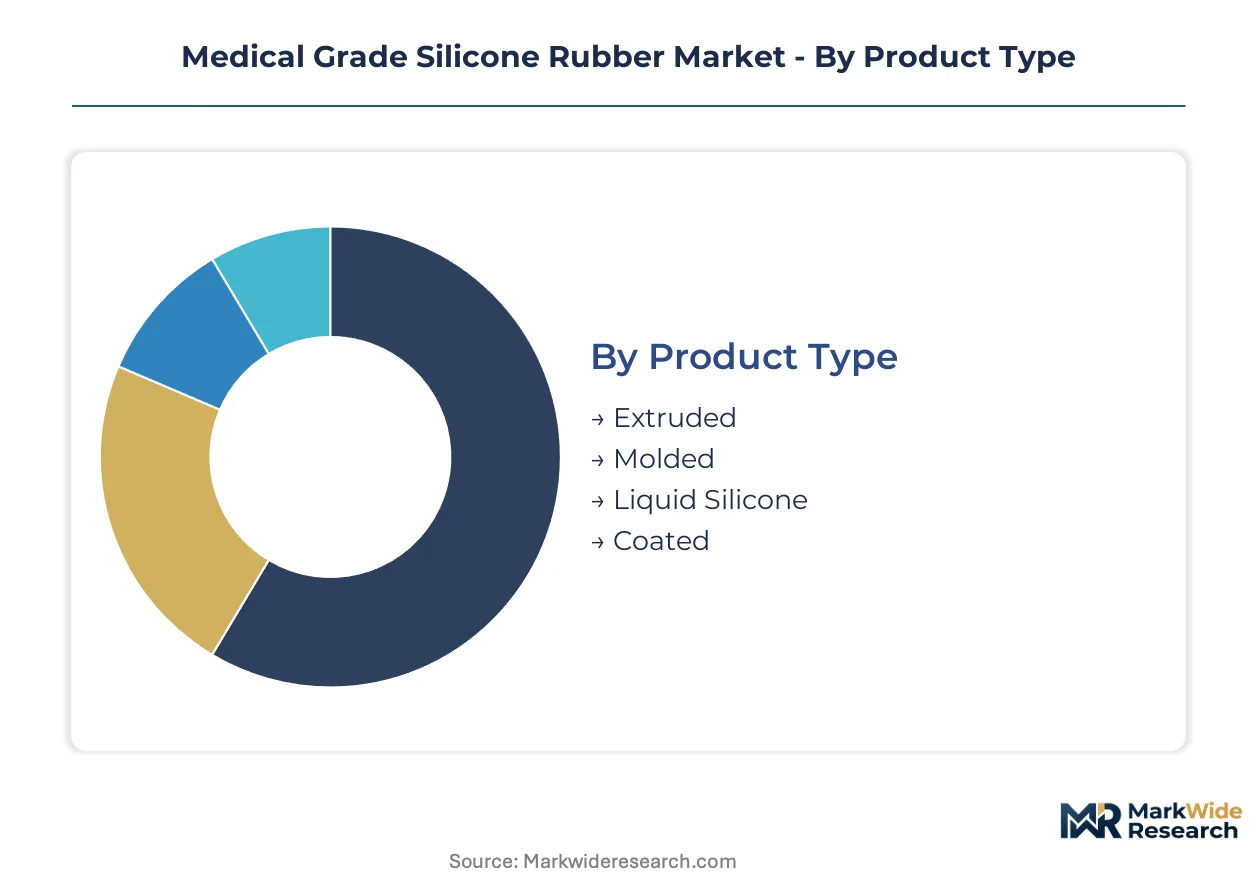
Medical grade silicone rubber procurement decisions hinge on processing method compatibility with device geometries and regulatory exposure duration. Formulation houses align product portfolios against specific manufacturing technologies and end-use risk classifications to capture margin pools across the value chain.
Product Type:
Upgrade cycles in medical device manufacturing are compressing legacy equipment amortization periods, forcing compounders to demonstrate compatibility with next-generation processing platforms.
- Liquid Silicone:Two-part platinum-catalyzed systems with viscosity below 500,000 cP enable intricate micro-molding of surgical components and respiratory masks. German catheter manufacturers in Baden-Württemberg dominate procurement for high-cavity cold runner tooling applications.
- Extruded:Continuous profile production through heated dies yields lumen-precision tubing for minimally invasive instrument sheathing. Demand concentrates in Bavarian precision device clusters where dimensional tolerance requirements exceed ±0.05mm.
- Molded:Compression and transfer molding of high-consistency rubber serves legacy prosthetic socket and seal geometries requiring Shore A 40-70 hardness ranges.
- Coated:Functionalized surface layers for drug-eluting stent substrates and antimicrobial wound dressings command formulation premiums based on controlled release kinetics.
Volume placements concentrate in Liquid Silicone; the faster expansion belongs to Coated variants.
Application:
Cost tier stratification separates commodity-grade seals from implantable devices requiring extractables documentation and Master File support.
- Medical Devices:Respiratory masks, tubing sets, and diagnostic instrument housings constitute the highest-volume application segment with standardized USP Class VI certification requirements.
- Implants:Permanent prosthetics and long-term indwelling devices demand ISO 10993-5 cytotoxicity and ISO 10993-6 implantation testing with full extractables profiling. German notified bodies are experiencing qualification backlog extending submission-to-approval intervals for these applications.
- Seals:Static and dynamic sealing elements for fluid management systems in dialysis and infusion equipment.
- Gaskets:Compression-set resistant barriers for sterilizable medical equipment enclosures and autoclave-resistant instrument trays.
Revenue concentration sits with Implants; Medical Devices deliver volume scale.
End User:
Customer type determines procurement modality, with consolidated hospital purchasing displacing spot-market transactions across Nordic and Benelux healthcare systems.
- Manufacturers:Original equipment producers of finished medical devices drive formulation customization and captive compounding relationships. Dow and Wacker Chemie AG anchor supply agreements with tier-one device producers requiring backward-integrated siloxane traceability.
- Hospitals:Group purchasing organizations consolidate silicone component procurement across multi-year framework agreements, compressing supplier margins while guaranteeing volume commitments.
- Clinics:Outpatient surgical centers source standard-grade tubing and seals through distributor networks with limited technical specification involvement.
- Labs:Research and diagnostic laboratories procure small-batch specialty formulations for prototype development and analytical instrument sealing.
Procurement gravity centers on Manufacturers; Hospital consolidation is reshaping contract structures.
Form:
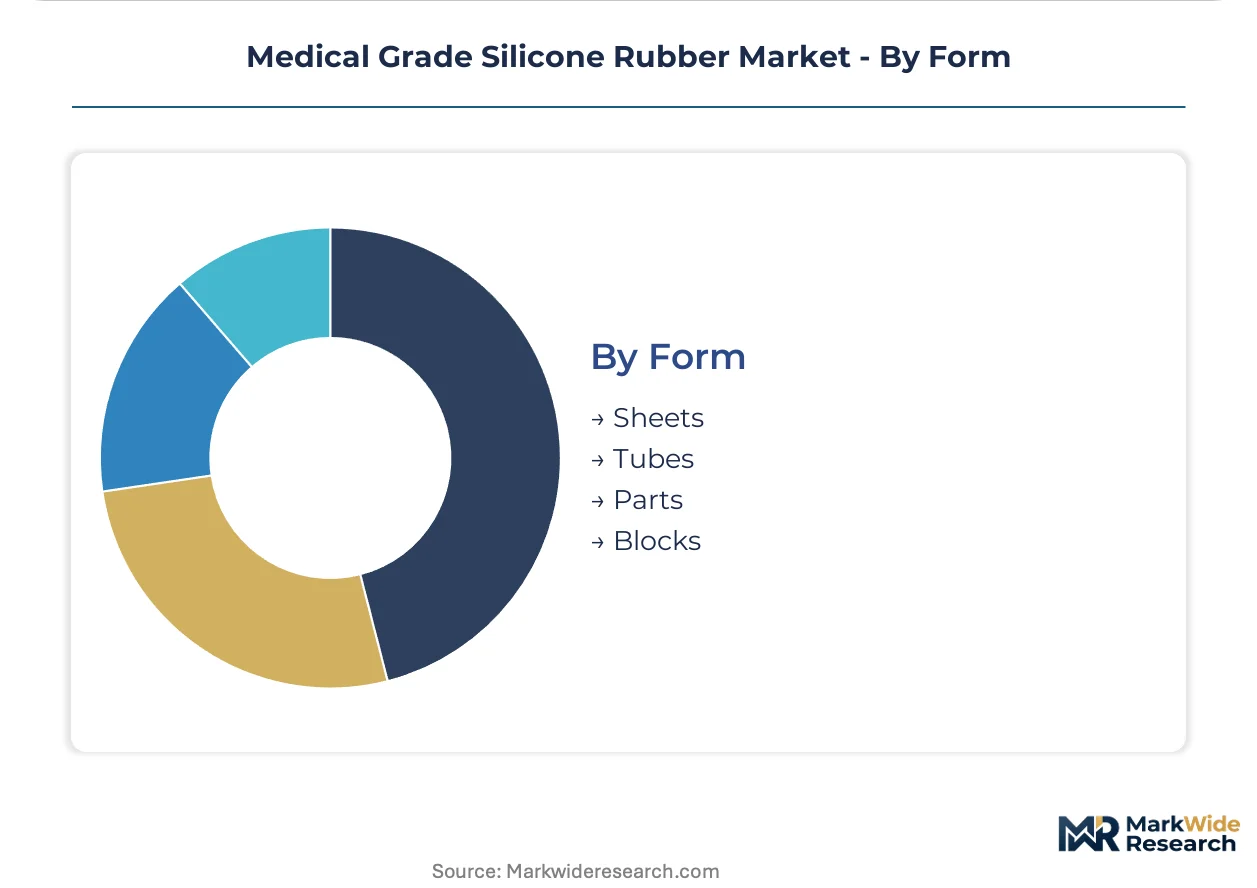
Supply concentration in sheeting and tubing reflects extrusion scale economies versus machined-part job shop fragmentation.
- Tubes:Lumen-critical profiles for catheter shafts, drainage systems, and endoscopic instrument channels require ISO 14644 Class 7 cleanroom extrusion with laser gauging verification.
- Sheets:Calendered or cast membranes for wound dressing substrates and medical equipment gasketing in thickness ranges from 0.1mm to 6.0mm.
- Parts:Finished molded components including valves, connectors, and diaphragms supplied direct to device assembly operations.
- Blocks:Uncured rubber billets for custom machining of prototype implants and specialized surgical tools.
Tubing captures the dominant share; Parts are climbing the fastest on device miniaturization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision medical device clusters in Baden-Württemberg and Bavaria concentrate demand for high-purity silicone formulations. FDA biocompatibility testing protocols and EMA MDR Annex I requirements reshape procurement across major manufacturing zones.
Germany
Catheter and prosthetic manufacturers in Baden-Württemberg drive specialized liquid silicone rubber procurement for multi-cavity cold runner tooling applications. EMA MDR Annex I general safety requirements extend post-market surveillance obligations through three supply chain tiers. Bavarian precision device clusters demand extruded tubing with dimensional tolerances exceeding ±0.05mm for minimally invasive instrument sheathing.
United States
Surgical implant manufacturers accelerate procurement of platinum-catalyzed curing systems as FDA 21 CFR Part 177.2600 repeat-use rubber provisions tighten extractables profiling requirements. FDA Master File submissions now mandate analytical chemistry capabilities for permanent implant categories. Minnesota and Massachusetts medical technology corridors concentrate device assembly operations sourcing USP Class VI certified elastomers.
China
Domestic catheter and respiratory mask producers expand liquid silicone rubber compounding capacity for regional device assembly. NMPA biocompatibility evaluation standards align with ISO 10993 frameworks for export-oriented manufacturers. Yangtze River Delta medical device clusters invest in ISO 14644 Class 7 cleanroom extrusion for lumen-critical tubing profiles.
Japan
Platinum-catalyzed silicone systems command premium positioning in implantable device segments requiring long-term physiological stability. PMDA pharmaceutical and medical device regulations enforce biological evaluation documentation parallel to FDA and EMA requirements. Osaka-based precision polymer compounders specialize in micro-molding formulations for cardiovascular and neurological applications.
Switzerland
Drug-eluting stent substrate manufacturers source functionalized silicone coatings with controlled release kinetics for cardiovascular devices. Swissmedic medical device regulations integrate EU MDR technical documentation requirements for European market access. Basel pharmaceutical technology clusters anchor demand for antimicrobial wound dressing laminates with silver-ion or chlorhexidine impregnation.
Medical Grade Silicone Rubber Market Key Industry Players
German chemical majors anchor one tier; Japanese and American specialists hold differentiated positions in curing system technologies. Three integrated siloxane producers control D4/D5 cyclosiloxane feedstock supply chains, creating input cost volatility exposure for non-integrated compounders. Strategic archetypes separate backward-integrated siloxane producers, specialized liquid silicone rubber formulators, and regional toll compounders serving device manufacturers. Competitive moves concentrate on captive polymerization investments and qualified supplier certification programs under tightening FDA extractables protocols.
Within the integrated chemical major tier, Dow and Wacker Chemie AG occupy positions defined by siloxane feedstock control and specialized formulation portfolios. Shin-Etsu Chemical Co., Ltd. exemplifies the premium-curing-system specialist archetype through proprietary platinum-catalyzed technologies. These three companies represent the concentration pattern in medical-grade silicone supply, with geographic origins in the United States, Germany, and Japan reflecting regional chemical industry structures.
| Leading Market Players |
|---|
| Dow |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive Performance Materials |
| Elkem ASA |
| Avantor, Inc. |
| KCC Silicone Corporation |
| Zhejiang Xin'an Chemical Group Co., Ltd. |
| Applied Silicone Corporation |
| Others |
Cost & Logistics Intelligence
Hospital procurement consortia in Nordic and Benelux healthcare systems anchor pricing power through multi-year framework agreements that displace spot-market transactions. This buyer concentration compresses supplier margins while rewarding compounders with FDA Master File documentation and ISO 10993 certification depth.
Pricing Analysis
Short-lead-time premiums apply to platinum-catalyzed liquid silicone rubber grades for catheter manufacturers facing urgent tooling cycles. Three-tier pricing structure across implant-grade, device-grade, and industrial-grade certification levels separates extractables-documented formulations from standard USP Class VI elastomers. Cost compression in respiratory mask tubing intensifies as group purchasing organizations consolidate volume commitments. Price sensitivity peaks among clinics sourcing through distributor networks, while implant manufacturers exhibit inelastic demand for Master File-supported grades.
Supply Chain Analysis
D4/D5 cyclosiloxane feedstock rests on integrated chemical majors in the United States, Germany, and Japan. Raw material dependencies center on siloxane monomers, platinum catalyst systems, and high-purity fillers. Single-source vulnerability concentrates in cyclosiloxane polymerization capacity controlled by three producers. Distribution runs through qualified supplier programs with tier-one device manufacturers, bypassing spot-market intermediaries for implant-grade formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Medical Grade Silicone Rubber Market functions as a cost-of-compliance arena where FDA 21 CFR Part 177.2600 extractables profiling and EMA MDR Annex I post-market surveillance obligations erect formidable barriers to uncertified entrants.
For Market Incumbents: Extend backward integration into siloxane feedstocks to insulate margin structures from D4/D5 cyclosiloxane price volatility. Deepen captive polymerization investments in Germany and the United States to secure traceability documentation for FDA Master File submissions. Thermoplastic elastomer substitution in sub-30-day contact devices threatens silicone's addressable range, demanding formulation innovation in long-implant segments. For New Entrants and Emerging Players: Begin with antimicrobial wound dressing laminates and drug-eluting stent substrates where functionalized coating expertise opens margin pools outside commodity tubing competition. Regional device manufacturers in China's Yangtze River Delta medical device clusters present penetrable entry points for room-temperature vulcanizing platinum-catalyzed systems. A technical service-led go-to-market approach leveraging decentralized manufacturing networks bypasses entrenched qualified supplier relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale compounders with ISO 14644 Class 7 cleanroom extrusion capacity in Germany and Switzerland. Long-term viability hinges on regulatory expertise arbitrage across FDA, EMA, and PMDA jurisdictions. Watch ECHA REACH candidate list progression on siloxane environmental persistence as a restriction-timeline inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Master File Submission | Extractables profiling documentation secures permanent implant category access against tightening protocols. |
| Backward Integration into Siloxane Feedstocks | Dow and Wacker Chemie AG demonstrate margin resilience through captive D4/D5 cyclosiloxane supply. |
| EMA MDR Annex I Compliance Services | Post-market surveillance documentation generates adjacent revenue from German notified body qualification backlogs. |
| Antimicrobial Functionalization R&D | Silver-ion and chlorhexidine-impregnated laminates open therapeutic categories beyond commodity seals. |
| Room-Temperature Vulcanizing Formulation Launch | Elimination of high-temperature post-cure requirements decentralizes production geography for regional manufacturers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with biomedical engineers, GPO contracts managers, silicone compounding plant managers, and regulatory affairs directors at notified bodies combined with FDA 510(k) databases, EMA MDR technical documentation, and ISO certification registries. Bottom-up demand modeling across catheter, prosthetic, and respiratory device categories triangulated against top-down chemical industry production data.
Granularity-level modeling distinguished liquid silicone rubber, extruded tubing, molded components, and coated variants by application risk classification and processing technology. End-use segmentation captured implantable devices, medical devices, seals, and gaskets with separate treatment of hospital procurement consortia and original equipment manufacturer direct purchasing. CAGRs derived from regression analysis of historical formulation demand against device approval timelines and regulatory implementation schedules. Siloxane feedstock price indices and cleanroom manufacturing capacity expansion pipelines informed supply-side constraints.
Underlying measurement precision varies by segment; implant-grade formulations with extractables documentation carry tighter precision than commodity respiratory mask elastomers. Forecasts reflect assumptions on regulatory implementation timelines, substitution elasticity of thermoplastic elastomers, and cyclosiloxane supply chain concentration. ECHA restriction progression, FDA guidance updates on extractables profiling, and German notified body qualification throughput warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
Global Elastomeric Coating Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
High Temperature Elastomers Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Global Thermoplastic Elastomers (TPE) Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market