
 Global Elastomeric Sealants Market | 2026-2036
Global Elastomeric Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Elastomeric Sealants Market Foresight
Buyer concentration across commercial construction is broadening as general contractors consolidate procurement authority while specialty subcontractors fragment across renewable energy and marine fabrication niches. Dow leverages its silicone raw material integration to anchor supply security for high-performance building envelope specifications. Henkel AG competes through hybrid polymer R&D intensity, particularly in moisture-cure systems for HVAC ductwork. Sika AG dominates European infrastructure refurbishment with specialized polysulfide formulations for bridge expansion joints.
Elastomeric sealants are polymeric compounds formulated with >200% elongation capacity, typically comprising silicone, polyurethane, or silyl-terminated polyether backbones cured through moisture or two-part catalytic reactions to accommodate dynamic substrate movement across temperature cycles from -40°C to 150°C. Silicone sealants sustain premium positioning in structural glazing and aerospace applications where UV stability and 50-year service life justify material cost. Polyurethane occupies high-volume construction joints and marine decking where paintability and abrasion resistance outweigh maximum elongation requirements. Hybrid polymers are capturing specification share in renewable installations and electronic enclosures by combining silicone weatherability with polyurethane substrate adhesion.
FDA regulates indirect food contact sealants in commercial food processing facilities, while EPA VOC limits under 40 CFR Part 59 constrain solvent-borne acrylic formulations in US states. REACH restricts isocyanate content in European polyurethane systems, and China's GB standards mandate low-odor emission certification for interior construction applications. India's BIS certification requirements for building sealants are tightening test protocols for tropical humidity cycling. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that fragment product portfolios across export markets.
Market Dynamics
EU Green Deal embodied carbon requirements are redirecting formulation priorities toward low-VOC hybrid chemistries, forcing raw material substitution across silicone and polyurethane supply chains while construction contractors consolidate procurement authority for high-movement building envelope systems.
Growth Catalysts
- Passive House Retrofit Mandates:Germany's building energy efficiency regulations are accelerating specification of high-elongation sealants for thermal bridge elimination in facade renovations.
- REACH Isocyanate Restrictions:European polyurethane reformulation toward low-monomer content is driving silyl-terminated polyether adoption in moisture-cure construction applications.
- Smart City Infrastructure:India's urban development programs are expanding joint sealing specifications for integrated utility corridors and flood-resilient transport networks.
Market Restraints
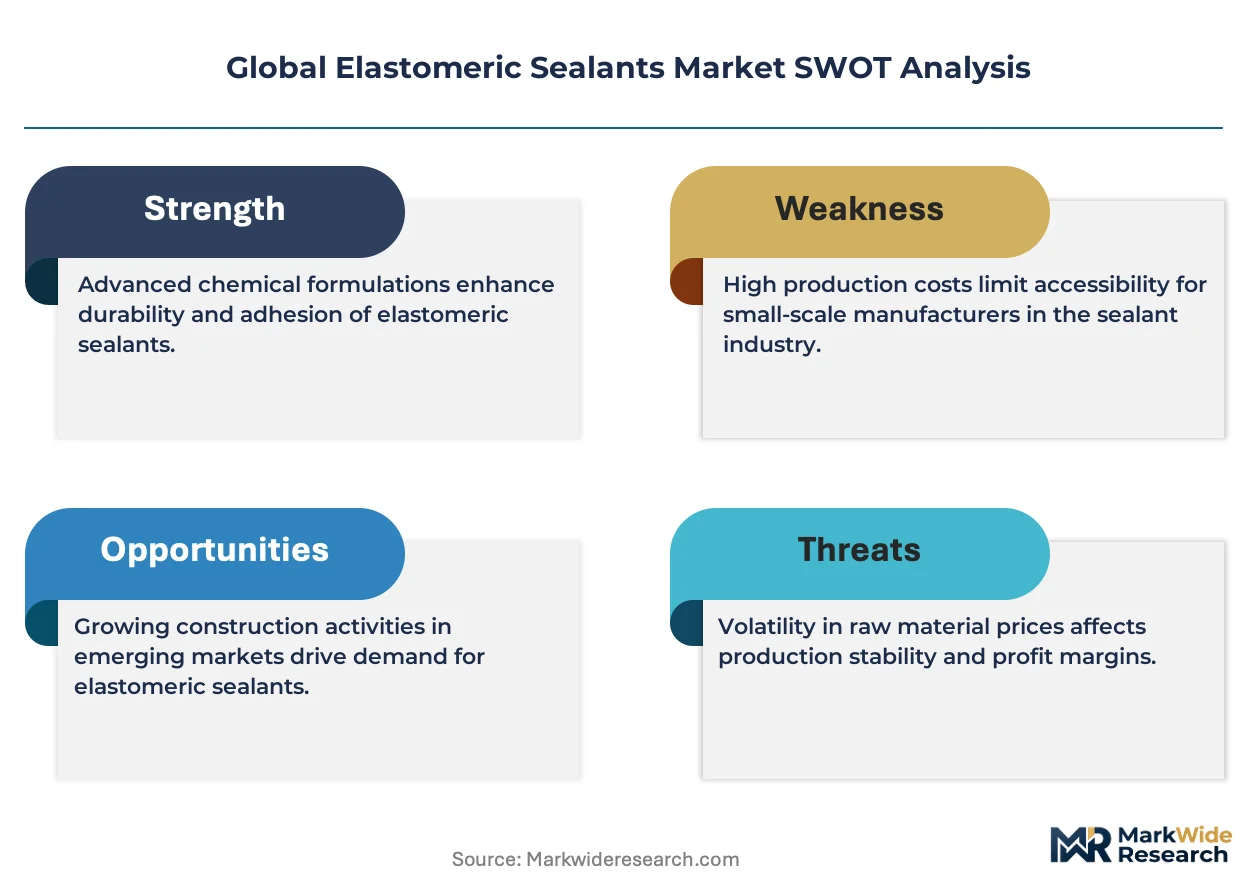
- Silicone Feedstock Concentration:Organosilicon precursor supply clusters in China's Yangtze River Delta create vulnerability to energy rationing and export licensing volatility.
- Two-Part System Complexity:Catalytic curing equipment requirements and pot-life constraints limit on-site application flexibility for large-scale infrastructure contractors.
- Acrylic Substitution Pressure:Water-borne acrylic sealants with lower material cost capture specification share in interior residential applications where movement accommodation requirements are minimal.
Strategic Opportunities
- Renewable Energy Installation Growth:Wind turbine blade root sealing and solar tracker joint protection represent unpenetrated demand for UV-stable hybrid polymer systems.
- Electronic Enclosure Convergence:Silyl-terminated polyether formulations combining silicone weatherability with polyurethane adhesion are displacing conventional gasketing in outdoor telecommunications housing.
- US IRA Clean Building Incentives:Tax credits for high-performance building envelopes are redirecting commercial construction specification toward certified low-VOC sealant systems.
Industry Challenges
- Formulation Chemist Scarcity:Moisture-cure kinetics expertise and hybrid polymer synthesis capability reside with retiring technical specialists, constraining R&D pipeline velocity.
- Multi-Jurisdiction Certification Burden:Divergent test protocols between India's BIS humidity cycling requirements and China's GB odor emission standards fragment product portfolios and extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Elastomeric Sealants Market |
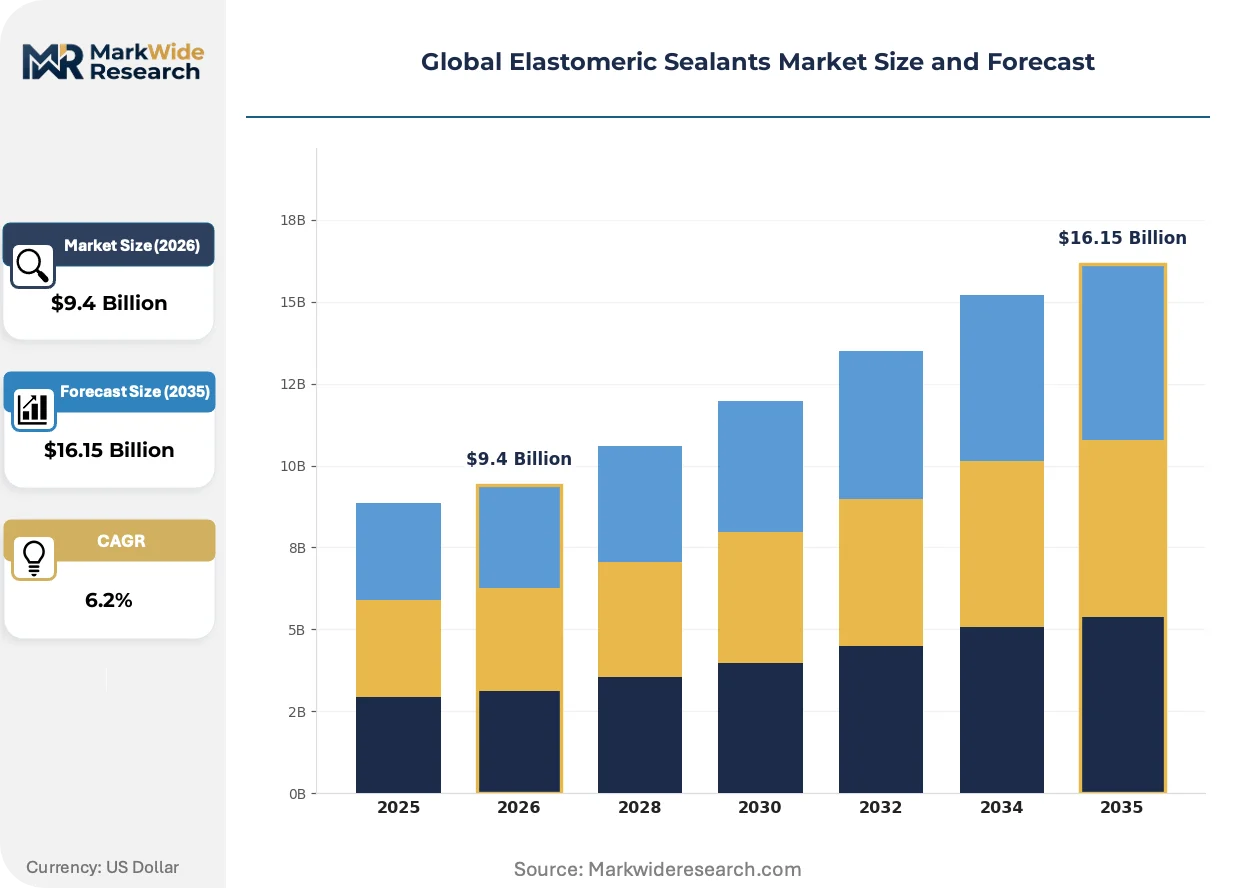
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.15 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Polysulfide, Acrylic, Butyl, Hybrid Application: Building & Construction, Marine Vessels, Aerospace Components, Electronic Devices, HVAC Systems, Renewable Installations End User: Contractors, OEMs, Facility Managers, Marine Fabricators, Aerospace Engineers, Electronics Assemblers Packaging Type: Cartridge Tubes, Sausage Packs, Bulk Containers, Brush-On Bottles, Tubes, Pails |
| Companies Covered | Dow, Henkel AG, 3M, Sika AG, Arkema, H.B. Fuller, RPM International, Wacker Chemie AG, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Elastomeric Sealants Market Shifts & Advancements
Formulation chemistry convergence is compressing the performance gap between silicone weatherability and polyurethane substrate adhesion, while regulatory pressure on embodied carbon accelerates raw material substitution timelines across construction supply chains.
Hybrid silyl-terminated polyether technology is consolidating specification authority in building envelope applications by delivering 400% elongation with paintable surface characteristics. Commercial contractors in Germany's passive house retrofit sector are specifying these systems for movement joints exceeding 25% cyclic amplitude. The technology is consolidating formerly separate silicone and polyurethane procurement categories into unified hybrid polymer specifications.
REACH restrictions on isocyanate content in European polyurethane systems are forcing reformulation toward low-monomer prepolymers and alternative curing mechanisms. Industrial consequence includes extended cure time profiles and modified application equipment requirements for construction sealant contractors. Bridge expansion joint specialists across France, Germany, and the Netherlands are responding with accelerated validation protocols for polysulfide alternatives.
General contractor procurement consolidation is disintermediating specialty sealant distributors in commercial building envelope specifications. Direct manufacturer relationships and volume-based framework agreements are replacing fragmented subcontractor purchasing across Germany's commercial construction sector. This concentration is most visible in facade renovation projects where single-source warranty requirements dominate specification authority.
Global Elastomeric Sealants Market Segmentation
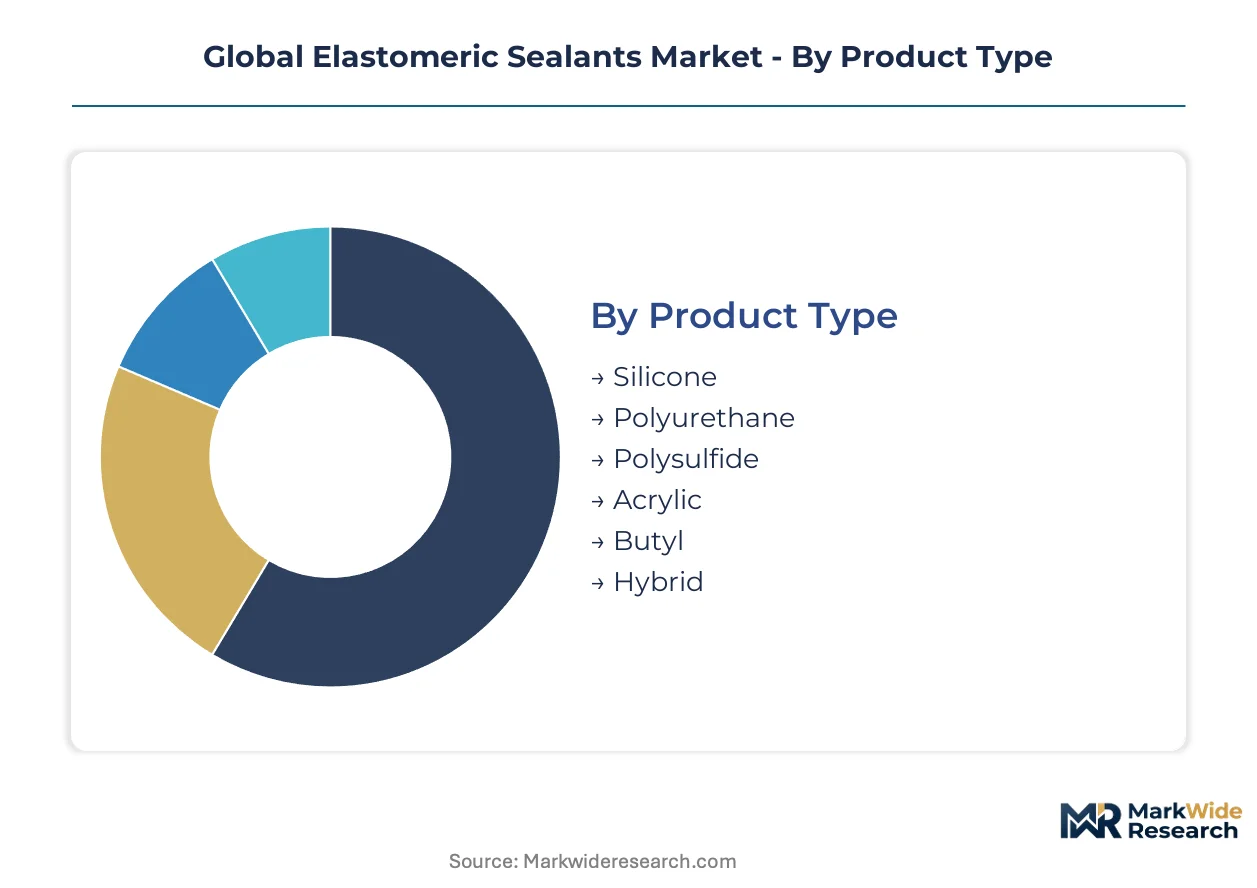
Elastomeric sealant procurement patterns diverge sharply across formulation chemistry and end-use specifications, with upgrade cycles in building envelope retrofits and renewable infrastructure driving portfolio reconfiguration among contractors and OEMs.
Product Type:
Replacement cycles in commercial building envelopes favor systems with extended service life and reduced maintenance intervals, redirecting specification authority toward advanced hybrid formulations.
- Silicone:UV-stable polydimethylsiloxane backbones deliver 50-year durability in structural glazing and aerospace applications. Demand clusters in Germany's passive house retrofit sector where thermal bridge elimination requires high-elongation facade sealing.
- Polyurethane:Paintable, abrasion-resistant formulations dominate high-volume construction joints and marine decking. REACH isocyanate restrictions are forcing European reformulation toward low-monomer prepolymers with extended cure profiles.
- Polysulfide:Liquid polymer systems maintain specification in bridge expansion joints and fuel-resistant industrial sealing.
- Acrylic:Water-borne formulations capture interior residential share where movement accommodation requirements remain minimal.
- Butyl:Isobutylene-isoprene copolymers serve preformed tape applications in window glazing and vapor barrier detailing.
- Hybrid:Silyl-terminated polyether systems consolidate silicone weatherability with polyurethane adhesion for 400% elongation in renewable energy installations and electronic enclosures.
Volume placements concentrate in polyurethane construction applications; the faster expansion belongs to hybrid systems displacing separate silicone and polyurethane procurement categories.
Application:
Cost tier differentiation separates specification-grade systems warranting single-source accountability from commodity products procured through distributor networks.
- Building & Construction:Joint sealing for commercial facades, thermal envelopes, and infrastructure refurbishment commands premium pricing with direct manufacturer relationships replacing fragmented subcontractor purchasing.
- Marine Vessels:Deck sealing and hull bonding applications prioritize paintability and saltwater resistance over maximum elongation in shipyard fabrication.
- Aerospace Components:FAA-certified fuel tank and pressure boundary sealing sustains qualification-intensive procurement with extended validation timelines.
- Electronic Devices:Miniaturized dispensing requirements for handheld equipment favor precision-applied hybrid polymers with rapid moisture cure.
- HVAC Systems:Ductwork sealing specifications are consolidating around moisture-cure hybrid systems with low-VOC certification for indoor air quality compliance.
- Renewable Installations:Wind turbine blade root sealing and solar tracker joint protection represent unpenetrated demand for UV-stable hybrid systems with 25-year service guarantees.
Specification authority clusters in building envelope applications; renewable installation demand is climbing the fastest as IRA clean building incentives redirect commercial construction procurement.
End User:
Customer type determines procurement channel structure, with consolidated general contractor frameworks diverging from specialty subcontractor fragmentation.
- Contractors:Commercial building envelope specialists consolidate procurement authority through volume-based manufacturer agreements, particularly in Germany's facade renovation sector.
- OEMs:Original equipment manufacturers in HVAC and electronics specify certified systems with validated cure kinetics for automated assembly lines.
- Facility Managers:Maintenance-driven purchasing favors cartridge-packaged products for in-house repair crews with limited application equipment.
- Marine Fabricators:Shipyard production schedules demand bulk delivery with pot-life flexibility for large-deck sealing operations.
- Aerospace Engineers:Qualification protocols restrict sourcing to pre-approved material lists with batch traceability and extended shelf-life documentation.
- Electronics Assemblers:Precision dispensing requirements favor small-format packaging with automated application compatibility.
Procurement volume concentrates with contractors; specification influence is expanding most quickly among OEMs integrating sealant selection into product design cycles.
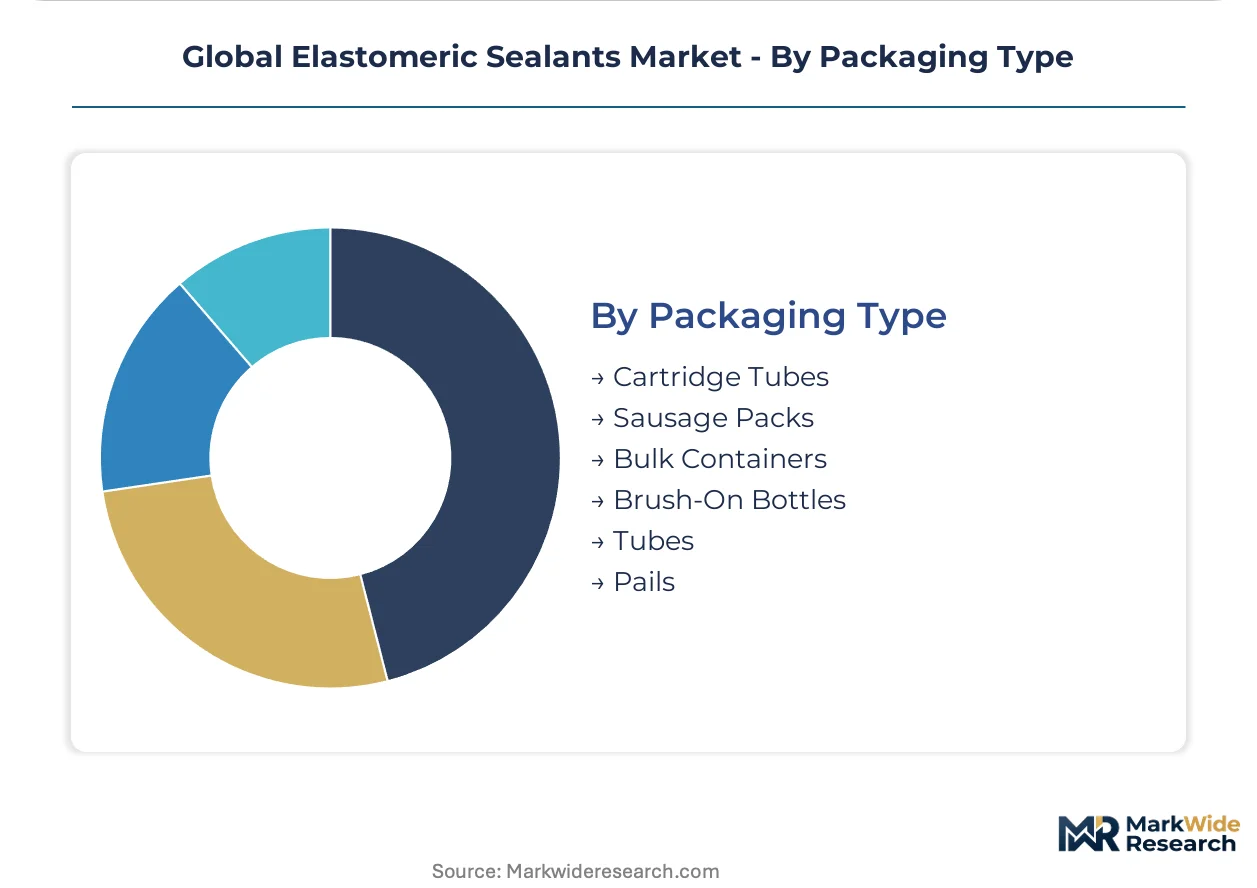
Packaging Type:
Application scale and equipment infrastructure dictate format selection, with field-installation flexibility competing against production-line efficiency.
- Cartridge Tubes:Standard 300ml aluminum cartridges dominate professional contractor applications with caulking gun compatibility.
- Sausage Packs:Foil-wrapped bulk formats reduce packaging waste for high-volume facade sealing with pneumatic dispensing equipment.
- Bulk Containers:Drum and tote deliveries serve OEM production lines with automated meter-mix dispensing systems.
- Brush-On Bottles:Consumer-oriented formats target DIY maintenance applications with simplified application methods.
- Tubes:Small-format squeeze tubes address electronics assemblers and facility maintenance crews with limited consumption volumes.
- Pails:Open-head containers facilitate two-part catalytic mixing for infrastructure contractors with on-site batch preparation capability.
Shipment volumes concentrate in cartridge and sausage formats; pail delivery is gaining share fastest among infrastructure contractors consolidating on-site mixing operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's passive house retrofit sector and India's smart city infrastructure programs, with regulatory divergence across jurisdictions fragmenting product portfolios and extending time-to-market for multinational suppliers.
Germany
Passive house retrofit mandates and thermal bridge elimination requirements are accelerating specification of high-elongation facade sealants in commercial building renovations. The EU Green Deal's embodied carbon requirements redirect formulation priorities toward low-VOC hybrid chemistries across German construction supply chains. Industrial concentration centers on the Rhine-Ruhr metropolitan region where general contractors consolidate procurement authority for facade renovation frameworks.
United States
Commercial building envelope upgrades and IRA clean building incentives are redirecting specification toward certified low-VOC sealant systems in high-performance construction. EPA VOC limits under 40 CFR Part 59 constrain solvent-borne acrylic formulations across multiple states. Demand clusters in the Northeast Corridor where consolidated general contractor procurement is disintermediating specialty distributors.
India
Smart city infrastructure programs and integrated utility corridor development are expanding joint sealing specifications for flood-resilient transport networks. BIS certification requirements mandate tightened test protocols for tropical humidity cycling in building sealant applications. Procurement authority concentrates in Maharashtra's Mumbai-Pune industrial corridor where urban development authorities specify certified systems for metro and airport expansions.
China
Organosilicon precursor supply clusters in the Yangtze River Delta create vulnerability to energy rationing and export licensing volatility for silicone sealant manufacturers. GB standards mandate low-odor emission certification for interior construction applications, constraining formulation flexibility. Manufacturing gravity centers on Jiangsu and Zhejiang provinces where feedstock concentration shapes regional supply security.
France
Bridge expansion joint refurbishment and infrastructure maintenance programs sustain demand for polysulfide and hybrid polymer systems in civil engineering applications. REACH isocyanate restrictions force European polyurethane reformulation toward low-monomer prepolymers with extended cure profiles. Technical validation activity concentrates in the Paris metropolitan area where infrastructure contractors accelerate alternative material protocols.
Global Elastomeric Sealants Market Competitive Landscape
European producers anchor the premium formulation tier; Asian chemical conglomerates hold volume positions in silicone feedstock and polyurethane intermediates. The vendor base stratifies across three tiers: integrated chemical majors with captive raw material supply, specialized sealant formulators with application expertise, and regional distributors with local certification relationships. Dominant competitive moves include backward integration into organosilicon precursors and strategic partnerships with general contractors for framework supply agreements.
Among the integrated chemical majors, Dow, Henkel AG, and Sika AG exemplify contrasting strategic archetypes. Dow represents upstream-integrated silicone specialists leveraging raw material control for supply security. Henkel AG occupies the hybrid polymer innovation position with moisture-cure system development. Sika AG anchors the infrastructure refurbishment segment with specialized civil engineering formulations. These three companies collectively illustrate how formulation chemistry expertise, geographic footprint, and end-use specialization define competitive positioning in building envelope and infrastructure applications.
| Leading Market Players |
|---|
| Dow |
| Henkel AG |
| 3M |
| Sika AG |
| Arkema |
| H.B. Fuller |
| RPM International |
| Wacker Chemie AG |
| PPG Industries |
| Others |
Supply & Pricing Matrix
Silyl-terminated polyether technology migration is compressing formulation cost differentials between silicone and polyurethane systems while simultaneously concentrating procurement leverage among general contractors with direct manufacturer frameworks. This chemistry convergence eliminates historical premium tiers and forces raw material suppliers to compete on volume scale rather than proprietary performance positioning.
Pricing Analysis
Volume placements in polyurethane construction joints sustain margin pressure from water-borne acrylic substitution, while hybrid polymer premiums hold in certified building envelope specifications. Three-tier pricing structure across certified low-VOC, standard construction-grade, and commodity interior tiers separates warranty-backed facade systems from distributor-procured maintenance products. Cost compression in standard polyurethane runs through REACH-driven reformulation expenses and extended cure time penalties. Facility managers represent the most price-sensitive segment, while aerospace engineers demonstrate minimal sensitivity due to qualification lock-in.
Supply Chain Analysis
Dual-sourcing mandates from German general contractors and US commercial developers require qualification of hybrid polymer suppliers across at least two production geographies. Organosilicon precursor production clusters in China, Germany, and the United States, with polyurethane intermediate concentration in Belgium, Japan, and South Korea. Feedstock supply draws from petrochemical complexes vulnerable to energy rationing and export licensing volatility. Distribution runs through direct manufacturer relationships replacing specialty sealant distributors in commercial building envelope procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive organosilicon precursor supply determines pricing power and specification authority. Players are pursuing upstream control over hybrid polymer raw material streams to escape feedstock cost volatility.
For Market Incumbents: Acquire moisture-cure formulation expertise through specialist R&D team recruitment or technology licensing. Consolidate procurement authority by establishing volume-based framework agreements with Germany's passive house retrofit contractors. Defend against hybrid polymer commoditization by investing in BIS and GB certification capabilities for India and China market access.
For New Entrants and Emerging Players: Launch via direct-to-contractor distribution models bypassing fragmented specialty distributor networks. Target renewable energy installation specifications where UV-stable hybrid polymer demand outpaces qualified supplier availability. Penetrate wind turbine blade root sealing applications through 25-year service guarantee partnerships with OEMs.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical majors seeking hybrid polymer technology capabilities. Five-to-ten year viability favors formulators with REACH-compliant low-monomer polyurethane platforms and silyl-terminated polyether synthesis expertise. Monitor BIS certification timeline acceleration as the signal for India market entry inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organosilicon Precursors | Captive silicone feedstock supply secures margin protection against Yangtze River Delta energy rationing disruptions. |
| Hybrid Polymer R&D Capacity Expansion | Moisture-cure kinetics expertise addresses formulation chemist scarcity constraining new product development velocity. |
| Multi-Jurisdiction Certification Investment | Simultaneous BIS, GB, and EPA compliance reduces time-to-market fragmentation across export destinations. |
| General Contractor Framework Agreements | Direct procurement relationships disintermediate distributors and anchor specification authority in facade renovation. |
| Renewable Energy Application Validation | Wind turbine and solar tracker sealing protocols open unpenetrated demand with 25-year performance guarantees. |
Research Methodology
Document review covered customs trade data, SEC 10-K filings, and ECHA REACH registration databases, complemented by interviews with sealant formulation chemists, commercial construction procurement directors, and HVAC OEM technical specification leads. Primary fieldwork included discussions with bridge expansion joint contractors, renewable energy EPC firms, and building envelope facade renovation specialists. Secondary validation drew from Cefic chemical industry reports, BIS certification protocol documents, and GB standards emission testing guidelines. Bottom-up volume modeling triangulated against top-down construction spending allocation estimates.
Segment-level demand outputs reflect formulation chemistry, application end-use, and regional regulatory cluster interactions across the analysis window. The analytical framework modeled silicone, polyurethane, polysulfide, acrylic, butyl, and hybrid product types against building construction, marine, aerospace, electronics, HVAC, and renewable installation applications. CAGRs derived from construction spending elasticity coefficients and substitution rate assumptions between conventional and hybrid polymer systems. Key inputs included passive house retrofit mandate enforcement timelines and IRA clean building incentive qualification criteria.
REACH isocyanate restriction enforcement, BIS humidity cycling protocol revisions, and Yangtze River Delta energy policy shifts are the dominant revision risks to modeled forecasts. Deviation in EU Green Deal embodied carbon requirement implementation speed would shift hybrid polymer adoption timelines materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Global Elastomeric Coating Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
High Temperature Elastomers Market
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market