
 Polysulfide Sealants Market | 2026-2036
Polysulfide Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Polysulfide Sealants Market Analytics
High-performance aerospace-grade specifications is rotating demand toward polysulfide sealants with enhanced fuel resistance and extended service intervals. Sika AG leverages its European manufacturing footprint to supply aviation-qualified formulations. Henkel AG & Co. KGaA anchors its position through R&D intensity in reactive polymer chemistry. Dow Chemical Company dominates industrial-scale production of liquid polysulfide base polymers for tier-one sealant manufacturers.
Polysulfide sealants are synthetic elastomeric compounds formed through the condensation of organic dichlorides with sodium polysulfide, typically exhibiting elongation at break exceeding 200% and superior resistance to jet fuel, hydraulic fluids, and thermal cycling from -55°C to 130°C. These properties make them indispensable for dynamic sealing in aircraft fuel tanks, marine hull joints, and curtain wall glazing systems where movement accommodation and chemical resistance coincide. The construction application segment leads volume consumption through institutional glazing and infrastructure waterproofing projects. Marine applications represent the fastest-growing structural pocket, driven by shipyard activity in East Asia and offshore platform maintenance cycles. Liquid formulations command the dominant product-type share due to ease of application in field conditions and compatibility with automated dispensing equipment.
The EPA regulates VOC emissions from architectural sealants under 40 CFR Part 59, directly constraining formulation chemistry and curing agent selection for US-manufactured products. REACH registration requirements and the EU F-Gas Regulation shape product development priorities for European suppliers, while China's MEE enforces GB standards on hazardous substance limits in building materials. Stakeholders must monitor evolving chemical restriction schedules and certification migration timelines to preserve market access across jurisdictions.
Market Dynamics
REACH compliance pressure in the European Union is forcing reformulation of legacy polysulfide chemistries, compressing margins for suppliers while creating first-mover advantages for compliant producers. Aerospace OEMs in Germany and France are accelerating qualification timelines for low-VOC alternatives, shifting procurement criteria toward environmental certification parity with performance metrics.
Growth Catalysts
- Aerospace fuel tank sealing:Commercial aircraft production rates in Toulouse and Hamburg are driving demand for jet-fuel-resistant formulations with extended service intervals. OEM specification updates favor polysulfide over silicone in integral fuel tank applications.
- REACH Annex XVII restrictions:Tightening VOC thresholds for construction sealants are eliminating solvent-based competitors, expanding addressable market for high-solids polysulfide systems in institutional glazing.
- Offshore platform maintenance cycles:North Sea decommissioning schedules and new floating production installations in Norwegian waters are concentrating marine demand for immersion-grade polysulfide joint sealants.
Market Restraints
- Liquid polysulfide polymer supply concentration:Base polymer production clusters in Texas and Louisiana create geographic single-source risk for European formulators lacking backward integration into polymer synthesis.
- Curing agent cost volatility:Manganese dioxide and lead dioxide activator prices fluctuate with mining output from specific regional deposits, compressing formulation economics unpredictably.
- Hybrid polyurethane-polysulfide substitution:Modified polyurethane sealants with comparable fuel resistance are displacing polysulfide in non-critical airframe applications where specification flexibility exists.
Strategic Opportunities
- India infrastructure buildout:Metro rail expansion in Mumbai and Bangalore creates demand for movement-accommodating joint sealants in elevated guideway construction, a segment currently served by inferior bituminous products.
- Two-part automated dispensing convergence:Integration of precision metering equipment with robotics in automotive glazing lines enables polysulfide penetration into high-volume passenger vehicle manufacturing previously blocked by cycle time constraints.
- EU Green Deal public procurement mandates:Environmental product declaration requirements for publicly funded construction projects are creating preferential purchasing channels for bio-based polysulfide formulations under development.
Industry Challenges
- Aerospace qualification timeline compression:FAA and EASA certification cycles for new sealant formulations extend 18-36 months, freezing R&D returns and requiring sustained capital commitment without revenue.
- Formulation chemist scarcity:Expertise in thiol-terminated polymer chemistry and polysulfide-epoxy hybrid systems concentrates among retiring specialists in Germany and the United States, constraining product development capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysulfide Sealants Market |
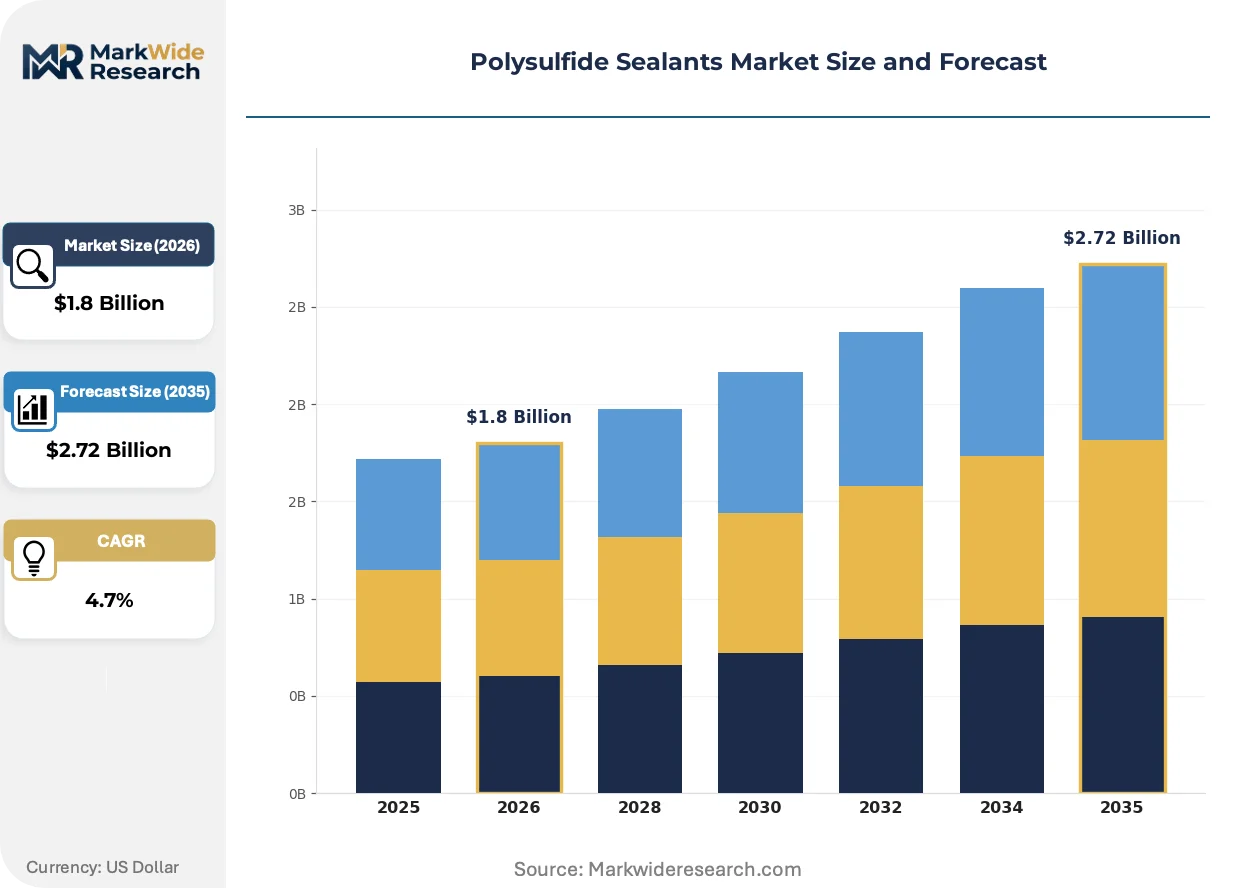
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Paste, Spray, Gel Application: Construction, Automotive, Aerospace, Marine End User: Contractors, Manufacturers, DIY Enthusiasts, Distributors Packaging Type: Tubes, Cans, Pails, Cartons |
| Companies Covered | Sika AG, Henkel AG & Co. KGaA, PPG Industries, RPM International, Tremco CPG, BASF SE, Dow Chemical Company, Fosroc, Pecora Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysulfide Sealants Market Evolving Landscape
Reactive chemistry advances and automated application systems are compressing the traditional trade-off between field-workability and factory-throughput efficiency. Formulators are converging on hybrid systems that preserve polysulfide's chemical resistance while accelerating cure kinetics.
Low-viscosity polysulfide oligomers with thiol end-group functionality enable spray application in marine ballast tank environments previously requiring hand-tooling. Shipyards in South Korea and Japan are adopting these systems for double-hull construction programs. The technology is miniaturizing equipment footprints, allowing robotic application in confined spaces that excluded automated sealing.
ECHA's 2023 update to REACH candidate list restrictions on certain curing accelerators is forcing substitution of lead-based activators in European-manufactured products. Formulators are qualifying calcium peroxide and organic peroxide alternatives with comparable pot life characteristics. German automotive sealant suppliers are most affected, accelerating reformulation timelines to preserve OEM supply contracts.
Buyers in commercial construction are consolidating sealant procurement through national distributor agreements rather than project-specific sourcing. This channel compression favors formulators with inventory positioning and technical service networks across multiple metropolitan areas. The shift is most visible in France, where institutional clients are centralizing maintenance material purchasing through cooperative procurement organizations.
Polysulfide Sealants Market Segmentation
Segmentation in the polysulfide sealants market reveals divergent margin structures across formulation physics and procurement channels. Manufacturers optimize production lines around viscosity grades and curing kinetics that match specific end-use certification requirements.
Product Type:
Margin pools concentrate in formulations enabling automated dispensing and field-applied systems with extended working times.
- Liquid:Low-viscosity thiol-terminated polymers with controlled molecular weight distribution enable precision metering in robotic glazing systems. Demand concentrates in German automotive OEM lines where cycle time compression favors pumpable systems with 30-60 minute pot life.
- Paste:Thixotropic formulations with fumed silica reinforcement maintain profile in vertical joints and overhead applications. Construction contractors in France specify gun-grade consistency for institutional curtain wall installations where sag resistance determines specification compliance.
- Spray:Atomizable low-viscosity oligomers penetrate marine ballast tank geometries inaccessible to trowel application.
- Gel:High-internal-phase systems with pseudoplastic flow characteristics target precision gap-filling in aerospace fastener sealing.
Liquid formulations hold installed capacity. Spray systems are rotating up the share rankings.
Application:
Volume distribution follows capital project cycles and maintenance scheduling in transport infrastructure.
- Construction:Movement-accommodating joint sealants for curtain wall glazing and podium waterproofing dominate tonnage. Institutional clients in Germany centralize procurement through cooperative purchasing organizations, compressing distributor margins while securing volume commitments.
- Marine:Immersion-grade formulations for double-hull sealing and offshore platform maintenance exhibit steepest expansion trajectory. South Korean shipyards specify polysulfide for ballast tank compliance with classification society rules.
- Aerospace:Jet-fuel-resistant integral tank sealing demands thiol-epoxy hybrid systems with FAA and EASA qualification.
- Automotive:Direct glazing applications in passenger vehicle windshields face substitution pressure from modified polyurethane systems.
Construction commands current volume leadership. Marine applications are climbing the fastest.
End User:
Procurement authority and technical specification control determine channel economics and service intensity requirements.
- Contractors:Project-based purchasing with spot-buying behavior and price sensitivity dominates residential and light commercial segments. French maintenance contractors are consolidating procurement through national distributor agreements.
- Manufacturers:Automotive and aerospace OEMs impose qualification-heavy supply relationships with 18-36 month certification timelines. German aviation suppliers anchor demand for batch-traceable aerospace-grade formulations.
- Distributors:Inventory-positioning intermediaries with technical service capabilities capture value in fragmented regional construction markets.
- DIY Enthusiasts:Small-format retail sales of general-purpose sealants generate minimal margin contribution.
Manufacturers hold specification authority. Distributors are rotating up the share rankings.
Packaging Type:
Packaging economics reflect application scale, shelf-life requirements, and dispensing equipment compatibility.
- Pails:Bulk containers for high-volume commercial construction and marine applications enable cost-efficient field mixing of two-part systems.
- Tubes:Cartridge formats for manual caulking guns dominate maintenance and repair segments with intermittent usage patterns.
- Cans:Intermediate volumes for specialty contractors with recurring demand but limited storage capacity.
- Cartons:Multi-unit packaging for distributor inventory and retail channel logistics.
Pail packaging holds installed capacity. Tube formats are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France exhibit low price elasticity for aerospace-qualified formulations, while construction contractors in India and Brazil remain highly sensitive to unit costs. This demand-elasticity contrast shapes regional procurement patterns and margin structures across the polysulfide sealants value chain.
United States
Commercial aircraft production in Seattle and Charleston drives consumption of jet-fuel-resistant tank sealants. The EPA regulates VOC emissions from architectural sealants under 40 CFR Part 59, constraining formulation chemistry for domestic manufacturers. Texas and Louisiana host concentrated liquid polysulfide polymer production, creating geographic supply advantages for regional formulators.
Germany
Automotive OEM lines in Stuttgart and Munich specify pumpable polysulfide systems for robotic windshield glazing. REACH Annex XVII restrictions on VOC thresholds are eliminating solvent-based competitors and expanding addressable market for high-solids formulations. Aviation suppliers in Hamburg anchor demand for batch-traceable aerospace-grade sealants with EASA qualification.
China
Shipyards in Dalian and Shanghai are adopting spray-applicable polysulfide oligomers for double-hull ballast tank construction. The MEE enforces GB standards on hazardous substance limits in building materials, shaping product development priorities for domestic suppliers. Yangtze River Delta infrastructure projects concentrate demand for movement-accommodating joint sealants in elevated guideway construction.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries specify polysulfide for marine classification society compliance in newbuild programs. The MFDS maintains chemical safety oversight for industrial materials, though sealant-specific regulations remain less prescriptive than EU equivalents. Ulsan and Geoje shipbuilding clusters drive immersion-grade formulation demand for offshore platform maintenance cycles.
India
Metro rail expansion in Mumbai and Bangalore creates demand for polysulfide joint sealants in elevated guideway construction, displacing inferior bituminous alternatives. BIS certification requirements for construction chemicals are tightening, though enforcement lags European standards. Maharashtra and Karnataka infrastructure buildouts concentrate procurement through state-level public works departments with consolidated tender processes.
Polysulfide Sealants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the polysulfide sealants market. The vendor base organizes around three tiers: diversified chemical conglomerates with captive polymer synthesis, specialized sealant formulators with aviation qualification expertise, and regional construction chemical suppliers competing on logistics proximity. Consolidation pressure is intensifying as REACH compliance costs favor scaled players with reformulation resources. Dominant competitive moves include backward integration into liquid polysulfide polymer production and strategic partnerships with aerospace OEMs for qualification-heavy supply relationships.
Within the diversified chemical conglomerate tier, Sika AG, Henkel AG & Co. KGaA, and Dow Chemical Company exemplify contrasting strategic positions. Sika AG leverages its European manufacturing footprint to supply aviation-qualified formulations. Henkel AG & Co. KGaA anchors its position through R&D intensity in reactive polymer chemistry. Dow Chemical Company occupies the upstream end, dominating industrial-scale production of liquid polysulfide base polymers for tier-one sealant manufacturers. These three players represent the archetype spectrum from formulation specialization through materials science integration to commodity polymer supply.
| Leading Market Players |
|---|
| Sika AG |
| Henkel AG & Co. KGaA |
| PPG Industries |
| RPM International |
| Tremco CPG |
| BASF SE |
| Dow Chemical Company |
| Fosroc |
| Pecora Corporation |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII VOC thresholds gate both supplier qualification and price differentiation simultaneously, compressing margins for non-compliant legacy formulators while granting compliant producers pricing power in institutional glazing and aerospace procurement channels.
Pricing Analysis
After-sales service contracts and technical field support drive lifetime value in aerospace and marine segments. Pricing stratifies across aviation-qualified, industrial-grade, and construction-standard tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in construction-grade formulations is intensifying because of hybrid polyurethane substitution. Contractors in India and Brazil exhibit highest price sensitivity, while German aviation OEMs show lowest elasticity for batch-traceable aerospace grades.
Supply Chain Analysis
Inventory positioning for liquid polysulfide base polymers runs through extended lead-time supply chains anchored in Texas and Louisiana production clusters. European formulators draw from these US polymer synthesis hubs, with manganese dioxide and lead dioxide curing agents sourced from concentrated mining deposits. Single-source vulnerability in base polymer supply creates geographic risk for non-integrated formulators. Distribution feeds through national distributor agreements with technical service networks in France and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in thiol-terminated polymer chemistry and EASA qualification protocols represents a contracting asset pool, constraining product development capacity across the vendor base and amplifying returns for holders of scarce technical capabilities.
For Market Incumbents: Compound aerospace qualification advantages by accelerating EASA certification timelines for low-VOC reformulations before REACH restrictions fully phase out legacy chemistries. Deepen backward integration into liquid polysulfide polymer production to offset supply concentration risk in Texas and Louisiana. Channel control through cooperative procurement organization partnerships in Germany secures volume commitments against price-sensitive spot-buying competitors. For New Entrants and Emerging Players: Lead with automated dispensing system integration for automotive glazing lines, targeting the two-part metering equipment convergence in German and South Korean passenger vehicle manufacturing. White-space exists in spray-applicable marine formulations for South Korean and Japanese shipyard double-hull programs. A technical service partnership model with regional distributors bypasses direct aerospace qualification barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across REACH-compliant reformulation capabilities as ECHA restriction schedules accelerate R&D spend requirements. Long-term viability favors scaled players with captive polymer synthesis and established aviation qualification portfolios. Acquisition targets should display backward integration into thiol-terminated polymer production or EASA-certified aerospace-grade formulation capacity. The signal to watch is lead time expansion for liquid polysulfide base polymers from US production clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Liquid Polysulfide Polymer Production | Captive supply from Texas and Louisiana hubs eliminates geographic single-source vulnerability for European formulators. |
| REACH-Compliant Low-VOC Reformulation Program | ECHA restriction timelines force substitution of lead-based activators with calcium peroxide alternatives to preserve EU market access. |
| Automated Dispensing Equipment Partnership | Precision metering integration with robotic glazing lines in Stuttgart and Munich enables polysulfide penetration into high-volume automotive manufacturing. |
| Aerospace Qualification Acceleration | FAA and EASA certification for thiol-epoxy hybrid systems locks in integral fuel tank specification preference over silicone alternatives. |
| Marine Spray Application Technology Deployment | Atomizable low-viscosity oligomer qualification with Hyundai Heavy Industries and Samsung Heavy Industries captures double-hull construction demand in Ulsan and Geoje. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with sealant formulator R&D directors, aerospace OEM procurement leads, marine shipyard technical managers, construction contractor purchasing heads, and national distributor inventory planners. Secondary validation drew from ECHA REACH restriction updates, EPA 40 CFR Part 59 regulatory filings, SEC 10-K disclosures from diversified chemical conglomerates, customs trade data on liquid polysulfide polymer imports, and classification society ballast tank coating rules. Bottom-up segment sizing triangulated against top-down market aggregation.
Across the projection horizon, the analytical framework modeled formulation physics, application end-use, procurement channel authority, and regional regulatory cluster segmentation. CAGRs were derived from elasticity-adjusted demand curves calibrated to aerospace production rates, shipyard newbuild schedules, and infrastructure tender pipelines. Industry-specific forecast inputs included REACH compliance cost trajectories and curing agent commodity price volatility indices.
Forecasts assume regulatory continuity in EU REACH and EPA 40 CFR regimes; material policy shifts would require re-modeling. Aerospace qualification timeline delays, liquid polysulfide polymer supply disruptions, or accelerated hybrid polyurethane substitution in non-critical airframe applications represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
Japan Adhesives Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
Canada Sealants Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market