
 Dry Cleaning Solvents Market | 2026-2036
Dry Cleaning Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Cleaning Solvents Market Analysis
Market Context
Product bundling from concentrate-plus-stabilizer kits to single-dose pre-formulated cartridges is shifting how mid-sized dry cleaners manage inventory and dosing precision. BASF leverages its specialty chemicals portfolio to anchor European supply relationships for hydrocarbon solvent blends. Shell Plc competes through integrated feedstock control, converting refinery streams into tailored cleaning-grade solvents. Evonik Industries specializes in silicone-based formulations that target premium garment-care operators seeking fabric-safe alternatives.
Technical Definition and Segments
Dry cleaning solvents are non-aqueous liquid formulations, typically with boiling points between 150°C and 210°C and Kauri-butanol values above 27, designed to dissolve oils, greases, and particulate soils from textiles without fiber swelling or dimensional distortion. Hydrocarbon solvents still occupy the largest volume position due to compatibility with existing equipment infrastructure, while green solvents—spanning bio-based glycol ethers and liquid carbon dioxide systems—are attracting capital as regulatory pressure intensifies. The hospitality end-use segment sustains above-average throughput per account, whereas automotive interior cleaning represents a margin-rich niche with specialized solvent specifications.
Regulatory Outlook
The US EPA oversees perc emissions through National Emission Standards for Hazardous Air Pollutants, while REACH in Europe mandates substitution plans for chlorinated solvents under authorization procedures; Health Canada evaluates perc under its Chemicals Management Plan, creating a multi-jurisdictional compliance burden. California's Air Resources Board enforces the nation's most aggressive perc phase-down timeline, directly constraining solvent selection for operators in Los Angeles, San Francisco, and San Diego clusters. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and equipment obsolescence.
Market Dynamics
The US EPA's phased perc restrictions under the Toxic Substances Control Act are forcing solvent substitution programs across commercial dry-cleaning networks, while REACH authorization procedures in Europe simultaneously tighten chlorinated solvent supply chains.
Growth Catalysts
- REACH authorization pressure:European substitution mandates for chlorinated solvents under ECHA procedures are pulling hydrocarbon and silicone-based alternatives into service territories previously dominated by perc.
- Hospitality linen standards:Hotel chains upgrading fabric-care protocols are expanding solvent procurement volumes through centralized commercial laundry contracts.
- Liquid CO₂ technology maturation:Supercritical carbon dioxide systems are achieving throughput parity with conventional equipment, enabling adoption in premium garment-care segments.
Market Restraints
- Petrochemical feedstock volatility:Hydrocarbon solvent producers face margin compression when naphtha and kerosene stream prices spike at integrated refineries.
- Equipment lock-in:Existing perc-machine installed base in North American urban clusters creates capital friction for operators considering solvent switches.
- Green solvent cost premiums:Bio-based glycol ethers and silicone formulations carry 40-60% unit-cost disadvantages versus conventional hydrocarbons at wholesale.
Strategic Opportunities
- Automotive interior detailing:Specialized solvent specifications for leather and synthetic upholstery cleaning represent a margin-rich niche with limited incumbent supply.
- California Air Resources Board phase-down:The nation's most aggressive perc timeline creates first-mover advantage for alternative solvent distributors in Los Angeles, San Francisco, and San Diego clusters.
- Single-dose cartridge formats:Pre-formulated solvent cartridges reduce dosing error and inventory complexity for mid-sized independent operators.
Industry Challenges
- Technician retraining requirements:Solvent transitions demand certified competency in fire-safety protocols for hydrocarbon systems and pressure-vessel handling for liquid CO₂ equipment.
- Cross-jurisdictional compliance burden:Operators serving multiple states must reconcile divergent EPA, CARB, and state-level air-quality regulations without stranded inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Cleaning Solvents Market |
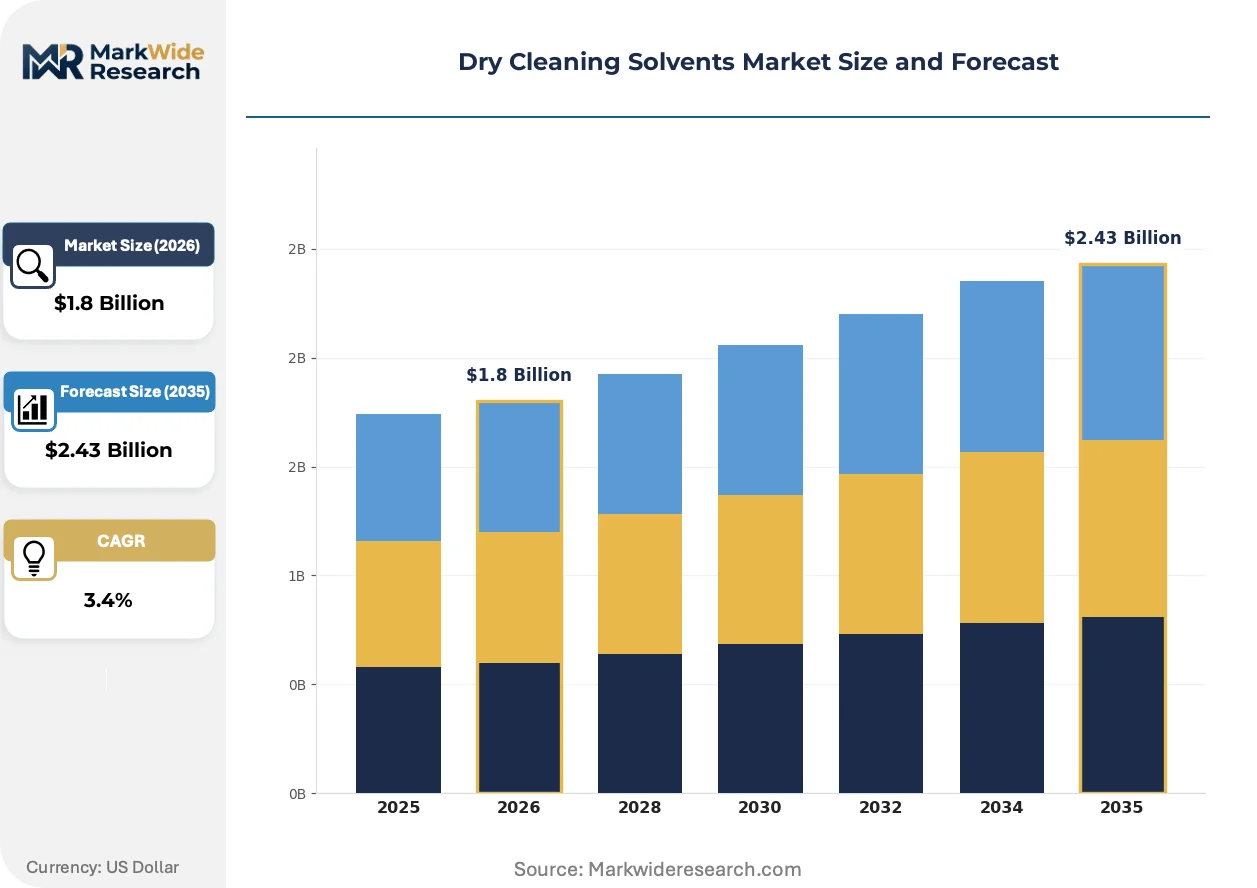
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Perc, Hydrocarbon Solvents, Green Solvents, Silicone-Based Solvents End Use Industry: Textile, Hospitality, Healthcare, Automotive Form: Liquid, Powder, Concentrate, Gel Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Ashland Global Holdings Inc, BASF, Shell Plc, Evonik Industries, ExxonMobil Corp., Eastman Chemical Company, Dow, Solvay SA, LyondellBasell Industries Holdings B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Cleaning Solvents Market Emerging Trajectories
Formulation chemistry and equipment engineering are converging to address regulatory compression on legacy chlorinated solvents, with three distinct vectors reshaping competitive positioning and procurement patterns.
Supercritical carbon dioxide cleaning systems are electrifying premium garment-care operations by eliminating solvent disposal costs and regulatory reporting burdens entirely. High-end bridal and couture specialists in Germany and Japan are adopting these systems despite 3-4x capital cost premiums, compressing addressable market share for conventional solvent suppliers in luxury segments.
REACH authorization procedures for chlorinated solvents are forcing substitution planning across European dry-cleaning networks. ECHA's sunset date mechanics are accelerating hydrocarbon and silicone solvent uptake in Germany, France, and Italy, with affected operators front-loading equipment replacement cycles to beat compliance deadlines.
Concentrate-to-cartridge format migration is altering inventory management for mid-sized operators. Pre-dosed solvent cartridges reduce chemical handling labor and dosing inconsistency, displacing bulk concentrate-plus-stabilizer procurement in the United States and Canadian markets where labor costs pressure operational margins.
Dry Cleaning Solvents Market Segmentation
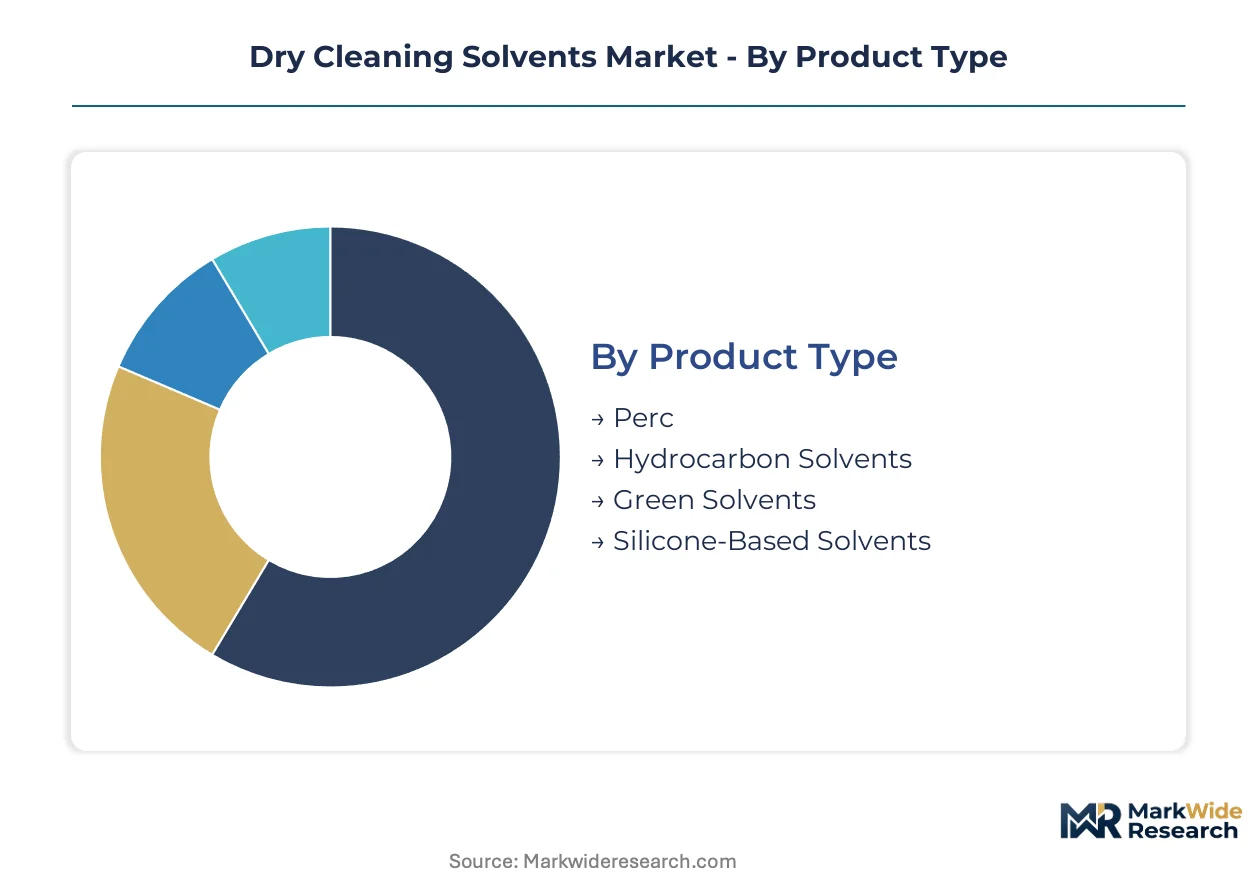
Dry cleaning solvent procurement patterns diverge sharply across product chemistries and end-use specifications. Understanding these fault lines reveals where substitution pressures concentrate and where incumbent technologies retain defensive moats.
Product Type:
Supply concentration for hydrocarbon blends at integrated refineries in Germany and the United States shapes competitive access and pricing power across this category.
- Perc:Chlorinated solvent with Kauri-butanol values above 85 and flash points below non-flammable thresholds, historically dominant in North American urban clusters. US EPA phase-down timelines under the Toxic Substances Control Act are forcing accelerated decommissioning of perc machines in Los Angeles, San Francisco, and San Diego, compressing addressable volume in California's premium garment-care corridor.
- Hydrocarbon Solvents:Petroleum-derived formulations with boiling points between 150°C and 210°C, designed for compatibility with existing perc-machine retrofits. Demand concentrates in Germany where REACH authorization procedures for chlorinated alternatives pull operators toward hydrocarbon systems ahead of compliance deadlines.
- Green Solvents:Bio-based glycol ethers and liquid carbon dioxide systems eliminating regulatory reporting burdens entirely.
- Silicone-Based Solvents:Fabric-safe formulations targeting premium bridal and couture specialists in Japan and Germany.
Today's leader: Hydrocarbon Solvents. Tomorrow's challenger: Green Solvents.
End Use Industry:
Application-specific solvent specifications create margin tiering that separates commodity textile cleaning from specialized healthcare and automotive segments.
- Textile:Conventional garment cleaning representing baseline volume throughput with standardized solvent specifications and price-sensitive procurement.
- Hospitality:Centralized commercial laundry contracts with above-average solvent consumption per account. Hotel chains in the United States upgrading linen care standards are expanding hydrocarbon and silicone solvent procurement through multi-year supply agreements with national distributors.
- Healthcare:Sterility-adjacent cleaning requirements with specialized solvent purity grades and documentation protocols.
- Automotive:Leather and synthetic upholstery cleaning specifications commanding 40-60% unit-cost premiums over conventional textile solvents. German automotive interior detailing specialists are driving specialized silicone formulation demand.
Volume concentrates in Hospitality. Margin concentrates in Automotive.
Form:
Inventory management complexity and dosing precision requirements differentiate procurement patterns between bulk concentrate buyers and pre-formulated cartridge adopters.
- Liquid:Standard bulk delivery format for high-throughput operators with on-site storage and manual dosing infrastructure.
- Powder:Concentrated solid formulations reducing transport costs and storage footprint for remote or space-constrained facilities.
- Concentrate:Dilution-required formulations demanding stabilizer kits and technical competency for proper reconstitution.
- Gel:Pre-thickened formulations for targeted spot-cleaning applications and reduced airborne exposure.
Mid-sized operators are migrating from Concentrate to single-dose alternatives.
Distribution Channel:
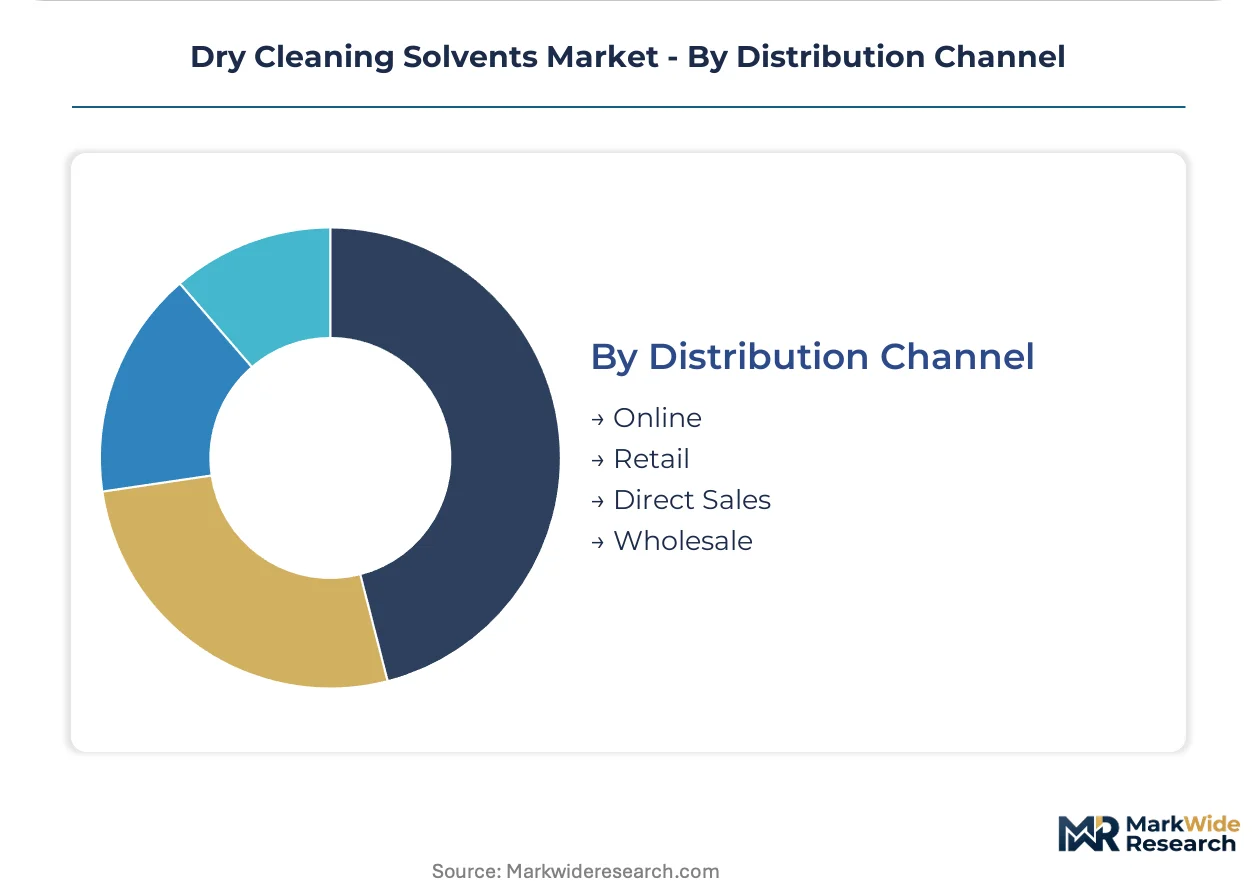
Customer scale and technical support requirements determine whether procurement flows through direct manufacturer relationships or intermediated wholesale and retail channels.
- Online:E-commerce platforms capturing small independent operators seeking transparent pricing and rapid replenishment without sales force engagement.
- Retail:Counter sales through industrial chemical distributors serving walk-in customers with immediate fulfillment needs.
- Direct Sales:Manufacturer-account relationships for large multi-location operators requiring technical training, equipment compatibility verification, and regulatory compliance documentation.
- Wholesale:Distributor intermediation providing credit terms, consolidated procurement, and last-mile logistics for mid-sized dry cleaning networks.
Direct Sales locks in the largest accounts. Online is gaining share fastest among independents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dry cleaning solvent manufacturing originated in Germany during the early twentieth century, with BASF pioneering chlorinated hydrocarbon formulations that spread across European textile centers. The industry later consolidated in the United States as petroleum refining integrated solvent production into downstream chemical operations.
United States
Commercial laundry networks in the hospitality sector drive hydrocarbon solvent procurement through centralized contracts with national distributors. The EPA's phased perc restrictions under the Toxic Substances Control Act force solvent substitution programs across California, New York, and Illinois. Los Angeles, San Francisco, and San Diego clusters face the nation's most aggressive perc phase-down timeline under California Air Resources Board enforcement.
Germany
REACH authorization procedures for chlorinated solvents pull operators toward hydrocarbon and silicone-based alternatives ahead of ECHA sunset deadlines. The country's stringent compliance framework creates premium solvent requirements unmatched elsewhere in Europe. The Rhine-Ruhr industrial corridor concentrates specialty chemical production, with BASF anchoring European supply relationships for tailored cleaning-grade formulations.
Japan
Premium bridal and couture specialists adopt liquid carbon dioxide systems despite capital cost premiums, compressing conventional solvent demand in luxury garment-care segments. METI industrial standards govern solvent purity grades for specialized textile applications. Tokyo and Osaka metropolitan areas host the densest concentration of high-end dry-cleaning operations transitioning to fabric-safe silicone formulations.
China
Rapid urbanization expands commercial laundry infrastructure in tier-one cities, though solvent selection remains price-sensitive compared to developed markets. MEE environmental regulations tighten emissions controls for chlorinated solvents in manufacturing zones. The Yangtze River Delta and Pearl River Delta clusters concentrate textile processing facilities with evolving solvent procurement specifications.
Canada
Health Canada's Chemicals Management Plan evaluates perc under extended regulatory review, creating uncertainty for operators considering equipment investments. Cross-border supply chains integrate Canadian dry cleaners with US hydrocarbon solvent distributors. Toronto and Vancouver metropolitan areas face pressure to align with California-level environmental standards despite slower federal timelines.
Dry Cleaning Solvents Market Vendor Landscape
The competitive structure tilts toward integrated petrochemical majors with captive feedstock control. Market concentration remains moderate, with specialty chemical divisions of oil majors competing against standalone solvent formulators. Three archetypes dominate: refinery-integrated producers converting naphtha streams, specialty chemical houses with formulation expertise, and equipment-integrated solvent suppliers. Capacity expansion in hydrocarbon blends and strategic partnerships for bio-based alternatives represent the dominant competitive vectors.
Within the integrated petrochemical tier, Shell Plc and ExxonMobil Corp. exemplify refinery-integrated positioning through upstream control over kerosene and naphtha feedstocks. BASF anchors the specialty chemical archetype with European supply relationships for hydrocarbon blends and silicone formulations. Evonik Industries occupies a position within the high-performance segment, representing fabric-safe alternatives targeting premium garment-care operators. These three companies collectively illustrate how feedstock access, formulation chemistry, and end-use specialization divide competitive territory.
| Leading Market Players |
|---|
| Ashland Global Holdings Inc |
| BASF |
| Shell Plc |
| Evonik Industries |
| ExxonMobil Corp. |
| Eastman Chemical Company |
| Dow |
| Solvay SA |
| LyondellBasell Industries Holdings B.V. |
| Others |
Supply Flow & Price Mechanics
California Air Resources Board perc phase-down mandates are forcing hotel chains and commercial laundries to accelerate hydrocarbon and silicone solvent procurement, compelling integrated refiners to reconfigure naphtha stream allocations and specialty chemical houses to absorb feedstock cost volatility into contract pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silicone-based bridal formulations from hydrocarbon workhorse blends and unbranded perc alternatives. Certification grade under REACH authorization and volume scale through multi-year hospitality contracts drive price differentiation. Cost compression in standard hydrocarbon tiers is intensifying because petrochemical feedstock volatility at integrated refineries compresses formulator margins. Small independent operators in the United States exhibit highest price sensitivity, while German premium garment-care specialists accept silicone premiums for fabric-safe performance.
Supply Chain Analysis
Single-source vulnerability sits with German specialty chemical production of REACH-compliant hydrocarbon blends and silicone formulations. Manufacturing concentrates in Germany, the United States, and Japan, with the Rhine-Ruhr corridor anchoring European supply and Gulf Coast refineries feeding North American demand. Raw material dependencies include naphtha streams, kerosene fractions, and siloxane precursors. Tariff exposure on cross-border solvent shipments between North American and European jurisdictions elevates landed cost uncertainty. Distribution runs through wholesale chemical distributors providing credit terms and last-mile logistics to mid-sized dry cleaning networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry cleaning solvent margins expand through green solvent adoption premiums and operational cost-down from single-dose cartridge formats displacing concentrate-plus-stabilizer procurement complexity.
For Market Incumbents: Anchor hydrocarbon supply relationships through long-term offtake agreements with Gulf Coast and Rhine-Ruhr refiners before REACH sunset dates tighten feedstock access. Defend against liquid CO₂ equipment suppliers by embedding formulation expertise into technical service contracts that lock in hospitality procurement managers. Capacity addition in silicone-based solvents targeting Japanese and German bridal specialists preserves premium tier positioning. For New Entrants and Emerging Players: CARB enforcement in California opens a window for hydrocarbon solvent distribution partnerships with Los Angeles and San Francisco operators facing perc machine decommissioning deadlines. Target automotive interior detailing specifications in Germany where specialized silicone formulations command supply gaps. Pursue direct-to-operator e-commerce platforms capturing small independents seeking transparent pricing without distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with equipment-integrated solvent suppliers bridging liquid CO₂ system sales with consumables lock-in. Five-to-ten year viability favors formulators with backward integration into bio-based glycol ether feedstocks rather than petrochemical-tethered hydrocarbon producers. Watch EPA state adoption timelines beyond California as the inflection signal for accelerated perc substitution capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Green solvent formulators secure non-petrochemical supply chains ahead of REACH authorization deadlines. |
| Capacity Expansion in Silicone-Based Solvents | Specialty chemical houses capture premium garment-care demand from Tokyo and Osaka bridal specialists. |
| Long-Term Supply Agreement with Hospitality Chains | Hydrocarbon solvent distributors lock in volume through centralized commercial laundry contracts. |
| Joint Venture for Liquid CO₂ Equipment Distribution | Technology providers access German and Japanese premium operators seeking zero-regulatory-reporting solutions. |
| Green Manufacturing Transition Certification | Formulators achieve Ecolabel and EPA Safer Choice recognition to differentiate in procurement tenders. |
Methodological Framework
Bottom-up hospitality and automotive modeling reconciled against top-down refinery stream tracking forms the analytical core of this study. Primary interviews with commercial laundry procurement directors, dry cleaning equipment distributors, specialty chemical plant managers, and ECHA regulatory affairs specialists combined with secondary validation from EPA enforcement databases, REACH authorization registers, SEC 10-K chemical segment disclosures, and German chemical industry association reports. Triangulation between operator-level solvent consumption patterns and integrated refinery output data ensures volume coherence.
Input-output matrices map solvent demand by product chemistry, end-use specification, and distribution channel across the projection horizon. Segmentation dimensions include hydrocarbon versus silicone versus green solvent grade, hospitality versus automotive versus textile end-use, and bulk liquid versus cartridge format. CAGRs derive from equipment replacement cycle analysis and regulatory deadline mechanics rather than extrapolation. Forecast inputs incorporate CARB phase-down enforcement intensity and REACH sunset date adherence rates by member state.
Revisions become necessary when EPA expands perc restrictions beyond California timelines or when liquid CO₂ equipment achieves capital cost parity with conventional systems. Forecasts reflect assumptions about regulatory adherence rates and feedstock price stability at integrated refineries. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Korea Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Low-Foaming Detergent Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market
Cleaning Chemicals
Global Metal Cleaning Chemicals Market
Cleaning Chemicals
Industrial and Institutional Hand Hygiene Chemicals Market
Cleaning Chemicals
Europe Mastic Remover Market
Cleaning Chemicals
Global Bleach Wipes Market