
 RO Membrane Chemicals Market | 2026-2036
RO Membrane Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
RO Membrane Chemicals Market Intelligence
Municipal water utilities is reorganizing procurement priorities as desalination and wastewater reuse projects expand across arid and water-stressed regions. SUEZ leverages its integrated water technology portfolio to anchor long-term chemical supply contracts with municipal operators. Kemira competes through specialized antiscalant formulations tailored to high-salinity feedwater conditions. Genesys International differentiates by focusing on membrane preservation chemistry for industrial reverse osmosis systems.
RO membrane chemicals encompass antiscalants, biocides, cleaning agents, and coating formulations designed to prevent mineral fouling, biological growth, and oxidative degradation on polyamide thin-film composite membranes operating at pressures typically ranging from 150 to 1,200 psi. These chemicals extend membrane lifespan, sustain permeate flux rates, and reduce energy consumption in water purification systems. Antiscalants command the largest product type position due to universal deployment in brackish and seawater reverse osmosis plants where calcium carbonate and sulfate precipitation threaten membrane integrity. The desalination application segment records the fastest structural expansion as coastal municipalities in the Middle East, North Africa, and Australia commission large-scale facilities requiring continuous chemical dosing.
The EPA Safe Drinking Water Act and EU Drinking Water Directive shape product registration requirements and maximum contaminant limits for chemicals contacting potable water membranes. NSF/ANSI Standard 61 certification in the United States and CE marking under EU construction product regulations gate market access for biocide and antiscalant suppliers. Stakeholders must monitor evolving regulatory timelines for per- and polyfluoroalkyl substance restrictions that could displace certain membrane coating chemistries and force reformulation investments.
Market Dynamics
Tightening discharge standards under EPA and EU frameworks are forcing municipal utilities toward higher-grade antiscalants and biocides, compressing procurement cycles and elevating technical specifications across membrane preservation programs.
Growth Catalysts
- Antiscalant chemistry advancement:Polymer-based threshold inhibitors now prevent calcium sulfate precipitation at saturation indices exceeding 200 percent, extending membrane cleaning intervals in Saudi Arabian desalination facilities.
- EPA Safe Drinking Water Act enforcement:Maximum contaminant limit revisions for disinfection byproducts are compelling utilities to replace chlorine-based biocides with non-oxidizing alternatives compatible with polyamide membranes.
- Industrial water reuse expansion:Semiconductor fabrication plants in Taiwan and South Korea are deploying closed-loop RO systems requiring continuous chemical dosing to maintain permeate quality for chip manufacturing.
Market Restraints
- Phosphonate raw material concentration:Antiscalant production depends on phosphonic acid derivatives sourced primarily from Chinese chemical manufacturers, creating supply vulnerability during export quota periods.
- Per-fluorinated compound regulatory friction:ECHA restrictions on PFAS-containing membrane coatings are forcing reformulation investments before viable alternatives achieve equivalent fouling resistance.
- Energy cost pass-through limitations:Desalination operators in Egypt and Morocco face regulated water tariffs that prevent full recovery of pumping energy costs, constraining chemical procurement budgets.
Strategic Opportunities
- Brackish water treatment in India:The Jal Jeevan Mission rural water supply program is creating demand for low-dose antiscalant formulations suited to decentralized RO units in fluoride-affected districts.
- EU Green Deal chemical substitution incentives:Biodegradable biocide development receives accelerated registration pathways under REACH simplification measures for sustainable water treatment chemistry.
- Digital dosing system convergence:Integration of real-time conductivity sensors with automated chemical feed pumps enables predictive antiscalant injection at Australian mining camp water treatment installations.
Industry Challenges
- NSF/ANSI Standard 61 certification timelines:New antiscalant formulations require 18-24 month evaluation periods for potable water contact approval, delaying commercial deployment.
- Membrane preservation chemistry skill gaps:Field service technicians lack training in Fourier-transform infrared spectroscopy for foulant identification, reducing cleaning protocol effectiveness at industrial sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RO Membrane Chemicals Market |
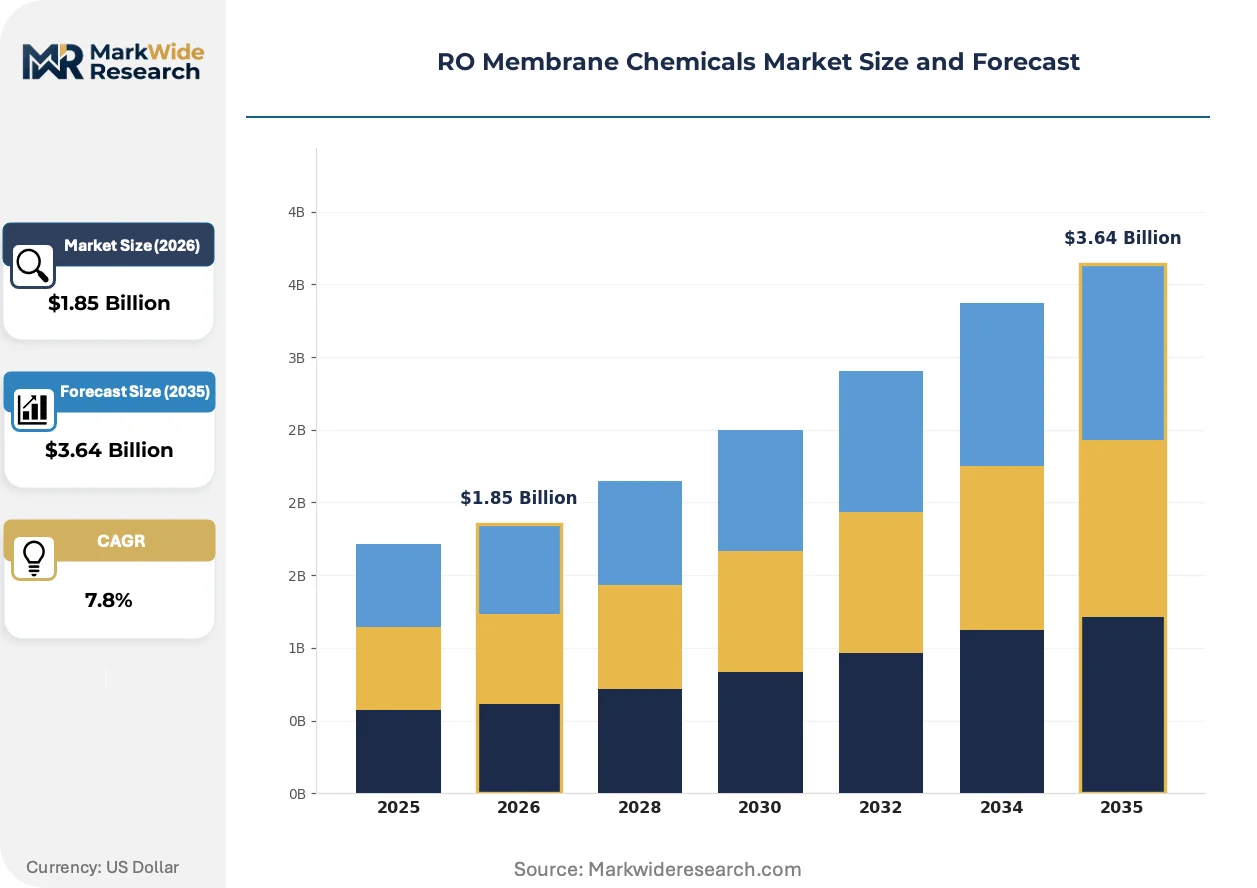
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleaning Chemicals, Antiscalants, Biocides, Coating Agents Application: Wastewater Treatment, Desalination, Industrial Process Water, Membrane Filtration End User: Municipal, Industrial, Commercial, Agricultural Packaging Type: Drums, Bulk Bags, Canisters, Totes |
| Companies Covered | Lenntech B.V, Genesys International, SUEZ, LANXESS, Kemira, Ecolab, Applied Membranes, Inc., Nalco, American Water Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RO Membrane Chemicals Market Strategic Shifts & Innovations
Membrane chemical dosing systems are converging with IoT-enabled monitoring platforms, shifting competitive advantage from formulation chemistry alone toward integrated preservation-as-a-service business models.
Phosphonate-free antiscalant chemistry is miniaturizing deployment footprints through concentrated liquid formulations that reduce shipping volumes by 60 percent. Municipal utilities in Australia are adopting these concentrates for remote desalination facilities where logistics costs dominate operational budgets. The technology is compressing supply chain requirements for island and coastal communities previously dependent on bulk chemical deliveries.
REACH authorization requirements for biocidal active substances are eliminating legacy isothiazolinone chemistries from European membrane treatment applications. Industrial RO operators in Germany and the Netherlands are transitioning to glutaraldehyde-quaternary ammonium blends that maintain efficacy against biofilm formation while meeting stricter environmental release criteria. The shift is accelerating registration investments among specialty chemical suppliers seeking CE-marked product portfolios.
Performance-based chemical supply contracts are displacing traditional volume-purchase agreements across Middle Eastern desalination consortia. Operators in the UAE and Qatar now compensate suppliers based on achieved membrane flux maintenance rather than delivered tonnage, transferring technical risk to chemical providers. This restructuring is most visible at large-scale reverse osmosis facilities where membrane replacement costs exceed chemical expenditures by an order of magnitude.
RO Membrane Chemicals Market Segmentation
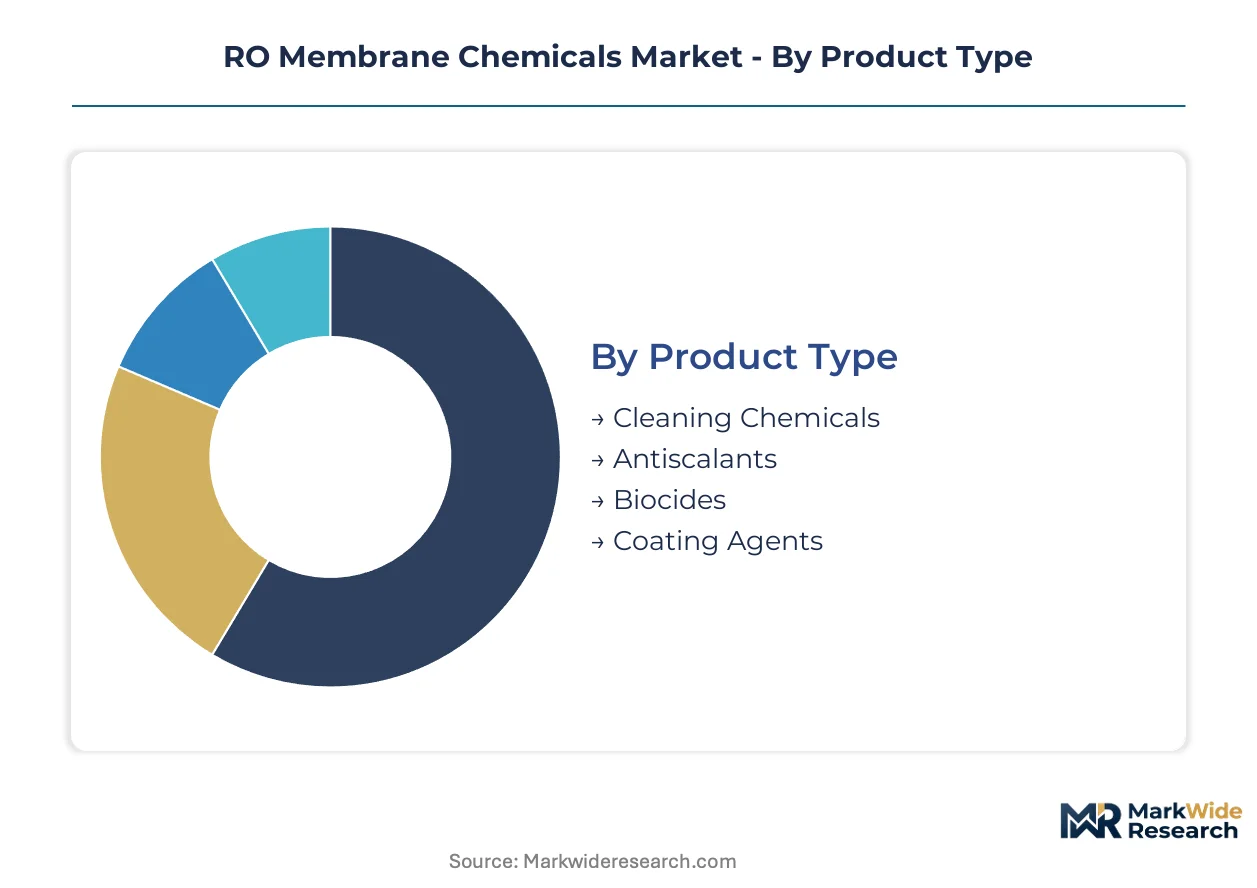
RO membrane chemicals segment along four dimensions that determine procurement economics, regulatory compliance, and logistics complexity. Product chemistry dictates EPA and EU registration pathways. Application context shapes dosing protocols and technical service intensity. End-user category determines contract structure and price sensitivity. Packaging configuration drives supply chain costs, especially for remote desalination facilities.
Product Type:
EPA Safe Drinking Water Act and EU Drinking Water Directive create divergent registration timelines and contaminant limits across chemical categories, fragmenting supplier portfolios by geography.
- Antiscalants:Polymer-based threshold inhibitors, including phosphonate and phosphonate-free formulations, prevent calcium carbonate and sulfate precipitation at saturation indices exceeding 200 percent. Municipal desalination plants in Saudi Arabia and Australia deploy these for continuous dosing to extend membrane cleaning intervals. Antiscalants handle the majority of throughput; coating agents are the fastest mover on share.
- Biocides:Non-oxidizing chemistries—glutaraldehyde-quaternary ammonium blends and isothiazolinone alternatives—control biofilm formation without degrading polyamide thin-film composite membranes. REACH authorization requirements are eliminating legacy biocides from European applications, forcing reformulation investments.
- Cleaning Chemicals:Alkaline and acidic formulations remove organic foulants and mineral scale during membrane maintenance cycles. Industrial RO operators in Taiwan semiconductor fabs require high-purity grades.
- Coating Agents:Surface-modifying chemistries enhance fouling resistance and oxidative stability. ECHA restrictions on PFAS-containing formulations are accelerating phosphonate-free alternatives.
Antiscalants dominate procurement volumes across brackish and seawater reverse osmosis installations; coating agents are climbing the fastest as membrane preservation protocols advance.
Application:
Application context determines chemical specification grade, dosing automation requirements, and technical service intensity, with water quality standards varying sharply between potable and industrial process streams.
- Desalination:Coastal reverse osmosis facilities in the UAE, Qatar, and Australia require continuous antiscalant and biocide dosing at pressures from 800 to 1,200 psi. Performance-based supply contracts now compensate suppliers on membrane flux maintenance rather than delivered tonnage.
- Industrial Process Water:Semiconductor fabrication plants in South Korea and Taiwan deploy closed-loop RO systems with real-time conductivity monitoring for chip manufacturing permeate quality.
- Wastewater Treatment:Municipal reuse projects in California and Spain recover effluent for irrigation and industrial cooling, requiring NSF/ANSI Standard 61 certified chemistries.
- Membrane Filtration:Pre-treatment and post-treatment chemical protocols protect ultrafiltration and nanofiltration membranes in hybrid water treatment trains.
Desalination commands the largest chemical volumes; industrial process water is gaining share fastest as semiconductor capacity expands.
End User:
End-user category structures contract duration, technical support expectations, and price elasticity, with municipal procurement increasingly shifting to outcome-based frameworks.
- Municipal:Water utilities in the United States, China, and Saudi Arabia operate under regulated tariffs that constrain chemical budgets but prioritize membrane longevity. The Jal Jeevan Mission in India is creating demand for low-dose formulations suited to decentralized rural units.
- Industrial:Manufacturing facilities negotiate direct supply agreements with technical service packages. Mining camp operators in Australia adopt concentrated liquid formulations to reduce logistics costs.
- Commercial:Hotels, hospitals, and data centers deploy smaller-scale RO systems with standardized chemical dosing protocols.
- Agricultural:Greenhouse and hydroponic operations in water-stressed regions utilize brackish water treatment for irrigation supply.
Municipal utilities account for the largest procurement base; industrial end users are expanding most quickly on share as manufacturing reuse intensifies.
Packaging Type:
Packaging configuration determines freight economics, storage requirements, and handling safety protocols, with concentrated formulations disrupting traditional bulk delivery models.
- Drums:Standard 55-gallon steel and polyethylene containers serve mid-scale municipal and industrial installations with established chemical handling infrastructure.
- Bulk Bags:Powdered antiscalant intermediates arrive in flexible intermediate bulk containers for on-site dilution at large desalination facilities.
- Canisters:Smaller-volume packaging addresses commercial and agricultural end users with limited storage capacity and intermittent dosing requirements.
- Totes:Intermediate bulk containers reduce drum handling labor at industrial process water installations with continuous chemical consumption.
Drums remain the default for municipal procurement; totes are climbing fastest as industrial automation reduces manual handling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese phosphonate manufacturers supply antiscalant intermediates to desalination operators across the Middle East and Australia, creating a trade corridor that shapes procurement economics for membrane preservation chemistry worldwide.
United States
Municipal utilities in California and Texas are expanding brackish water desalination capacity under state drought resilience mandates. EPA Safe Drinking Water Act enforcement compels replacement of chlorine-based biocides with membrane-compatible alternatives. The Colorado River Basin and Central Valley host concentrated reuse projects requiring continuous chemical dosing.
Saudi Arabia
Coastal desalination facilities at Jubail and Yanbu Industrial City operate the world's largest membrane-based water production capacity. SFDA and national water authority specifications mandate high-grade antiscalant formulations for seawater reverse osmosis at 1,200 psi operating pressure. NEOM Northwest development is commissioning next-generation facilities with performance-based chemical supply contracts.
Australia
Mining camp operators in Western Australia and Queensland are adopting concentrated liquid antiscalants to reduce logistics costs across remote desert installations. National water quality guidelines under the Australian Drinking Water Framework shape biocide selection for potable membrane systems. Perth's coastal desalination plants and Pilbara mining regions drive concentrated formulation demand.
Germany
Industrial RO operators in the Ruhr Valley and Bavarian chemical corridor are transitioning from isothiazolinone biocides under REACH authorization timelines. ECHA restrictions on PFAS-containing membrane coatings force reformulation investments among specialty chemical suppliers. The Rhine-Ruhr and Upper Bavaria clusters concentrate technical service-intensive preservation programs.
India
The Jal Jeevan Mission is deploying decentralized RO units across fluoride-affected districts in Rajasthan and Gujarat, creating demand for low-dose antiscalant formulations. BIS water quality standards and state pollution control board discharge limits shape chemical procurement for rural installations. Tamil Nadu and Karnataka industrial corridors are expanding closed-loop reuse systems for textile and electronics manufacturing.
RO Membrane Chemicals Market Key Industry Players
Listed leaders compete with private specialists across formulation chemistry and technical service capabilities, producing a tiered market structure where scale advantages in phosphonate production coexist with regional customization expertise. Three archetypes dominate: integrated water technology conglomerates with captive chemical portfolios, pure-play membrane preservation specialists, and diversified industrial chemical suppliers leveraging raw material positions. Competitive dynamics center on performance-based contract restructuring and phosphonate-free formulation development.
Within the integrated technology tier, SUEZ and Ecolab occupy positions that bundle chemical supply with membrane system engineering, exemplifying the shift toward outcome-based compensation models. Among specialty chemical suppliers, Kemira and LANXESS represent European formulation expertise navigating REACH regulatory complexity, while Genesys International anchors the dedicated membrane preservation specialist archetype with focused technical service intensity. These three company groupings illustrate how competitive positioning stratifies across scale, specialization, and geographic regulatory adaptation.
| Leading Market Players |
|---|
| Lenntech B.V |
| Genesys International |
| SUEZ |
| LANXESS |
| Kemira |
| Ecolab |
| Applied Membranes, Inc. |
| Nalco |
| American Water Chemicals, Inc. |
| Others |
Cost & Logistics Intelligence
Chinese phosphonate manufacturers command scale economies in antiscalant intermediate production that compress price floors for downstream formulators while simultaneously concentrating supply vulnerability during export quota periods. This scale-concentration dynamic forces membrane chemical suppliers to balance cost pass-through capabilities against buyer procurement power across municipal and industrial segments.
Pricing Analysis
Prior-generation phosphonate-based antiscalants trade at commodity margins while next-generation phosphonate-free concentrates capture premium positioning through 60 percent logistics reduction. The dominant structure runs through contract-based long-term offtake agreements with performance-linked clauses, where price differentiation hinges on NSF/ANSI Standard 61 certification grade and bundled technical service intensity. Cost compression in phosphonate formulations is intensifying because Chinese export quotas disrupt raw material availability, though desalination operators in the Middle East show lowest price sensitivity due to membrane replacement cost exposure. Municipal utilities in India and Egypt face highest price sensitivity as regulated tariffs constrain chemical procurement budgets.
Supply Chain Analysis
Chinese chemical manufacturers anchor global phosphonic acid derivative supply for antiscalant production, while German and Belgian specialty chemical houses concentrate high-grade biocide formulation. Raw material flows draw from phosphonate intermediates, glutaraldehyde feedstocks, and polymer-based threshold inhibitors. Single-source vulnerability concentrates in Chinese phosphonate export quotas, which constrain global antiscalant availability during regulatory enforcement periods. Distribution runs through regional chemical distributors serving municipal utilities, direct supply agreements with desalination consortia, and technical service-intensive channels for industrial RO operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane preservation chemistry fragments across regulatory jurisdictions and application-specific formulation requirements, creating niche opportunities as REACH authorization and EPA discharge standards eliminate legacy chemistries and force substitution cycles.
For Market Incumbents: Shield formulation portfolios by accelerating phosphonate-free antiscalant registration ahead of ECHA restrictions on persistent chemistries. Backward integration into phosphonate intermediate production reduces Chinese supply quota exposure. Priority certification investment targets NSF/ANSI Standard 61 potable water contact approval to lock municipal utility procurement channels against specialty chemical challengers.
For New Entrants and Emerging Players: Differentiate on biodegradable biocide chemistry aligned with EU Green Deal registration pathway acceleration. The most penetrable white-space sits in low-dose antiscalant formulations for India's Jal Jeevan Mission decentralized rural units, where technical service intensity requirements remain modest. Direct technical partnership with state water authorities offers go-to-market traction against established distributor networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty chemical suppliers with REACH-compliant biocide portfolios and concentrated liquid formulation capabilities. Long-term viability centers on chemical-as-a-service business models where outcome-based compensation transfers membrane performance risk from operators to suppliers. The signal to watch is performance-based contract penetration at Middle Eastern desalination facilities, indicating structural shift from volume-purchase to flux-maintenance compensation.
| Strategic Initiative | Industry Significance |
|---|---|
| Phosphonate-Free Formulation Development | ECHA PFAS restrictions force reformulation investments before viable alternatives achieve equivalent fouling resistance thresholds. |
| Performance-Based Supply Contract Restructuring | UAE and Qatar desalination operators now compensate suppliers based on achieved membrane flux maintenance rather than delivered tonnage. |
| Backward Integration into Phosphonate Intermediates | Captive production of phosphonic acid derivatives reduces exposure to Chinese export quota volatility and supply interruption. |
| Biodegradable Biocide Registration Acceleration | EU REACH simplification measures for sustainable water treatment chemistry create expedited pathways for glutaraldehyde-quaternary ammonium alternatives. |
| Digital Dosing System Convergence | Integration of real-time conductivity sensors with automated chemical feed pumps enables predictive antiscalant injection at remote installations. |
Research Approach
The analysis maps antiscalant, biocide, cleaning agent, and coating agent sub-sectors, each validated through technical service directors at membrane system OEMs, procurement leads at municipal water utilities, plant managers at desalination facilities, and specialty chemical R&D heads. Primary interview findings triangulated against secondary sources including customs and trade data, EPA Safe Drinking Water Act regulatory filings, ECHA REACH authorization databases, and SEC 10-K disclosures from listed water technology conglomerates. Bottom-up volume modeling across product chemistry and application segments converged with top-down market sizing through regional desalination capacity databases.
Outputs underwent consistency validation against external benchmarks including national water authority procurement disclosures and industrial water reuse project announcements. The analytical framework models chemistry type, application context, end-user category, and packaging configuration across the projection horizon. CAGRs derived from segment-level volume trajectories indexed to announced desalination capacity additions and semiconductor fabrication plant water reuse intensification. Forecast inputs incorporated membrane replacement cost ratios, energy price pass-through elasticity, and regulatory timeline probability weightings.
The analysis sits within stated boundaries; outcomes outside sustained municipal desalination investment, stable phosphonate intermediate trade flows, or unchanged membrane material compositions would require recalibration. Forecasts reflect documented assumptions regarding EPA and EU regulatory enforcement intensity, Middle Eastern desalination tariff structures, and Indian rural water supply program execution. Recalibration cycles align with material shifts in REACH authorization timelines, PFAS restriction scope, and performance-based contract adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
North America Oxo-Alcohol Market
Chemicals
Integrated Chemistry Systems Market
Chemicals
Cold Phosphating Chemicals Market
Chemicals
Concrete Surface Treatment Chemicals Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Waterborne Curing Agents Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
Global Diphenylmethane Diisocyanate Market
Chemicals
Europe Hydrazine Market
Chemicals
South America Construction Chemicals Market
Chemicals
Mercury (I) Sulphate Market
Chemicals
Aerosol Insecticides Market
Chemicals
Sodium Ethylate Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
Allyl Chloride Market