
 Polymer Modified Cementitious Coatings Market | 2026-2036
Polymer Modified Cementitious Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Modified Cementitious Coatings Market Intelligence
The performance gap between high-specification, polymer-rich formulations and basic, low-polymer commodity grades is recalibrating customer choice. Premium products offer superior durability and flexibility for critical applications. Sika AG leverages its extensive portfolio to serve large-scale infrastructure projects. BASF SE differentiates through its advanced polymer chemistry and material science expertise, while Pidilite Industries Limited sustains a strong position in residential and commercial segments in specific regional markets.
Polymer modified cementitious coatings are composite materials combining a cementitious binder with polymers and aggregates. These formulations, often incorporating acrylic or styrene-butadiene polymers, improve adhesion, flexural strength, and impermeability compared to standard cement mortars. Their primary purpose is to protect and repair concrete and masonry structures. Acrylic-based products lead the market due to their UV stability and cost-effectiveness, while waterproofing applications in commercial buildings represent a core demand driver.
Regulations such as Europe's REACH framework govern the chemical substances used in coating formulations. In the United States, EPA standards on volatile organic compounds (VOCs) push manufacturers toward water-based systems. These regulatory pressures directly influence product development and market access. Consequently, material selection for polymer modification will dictate a supplier's ability to compete in environmentally stringent markets.
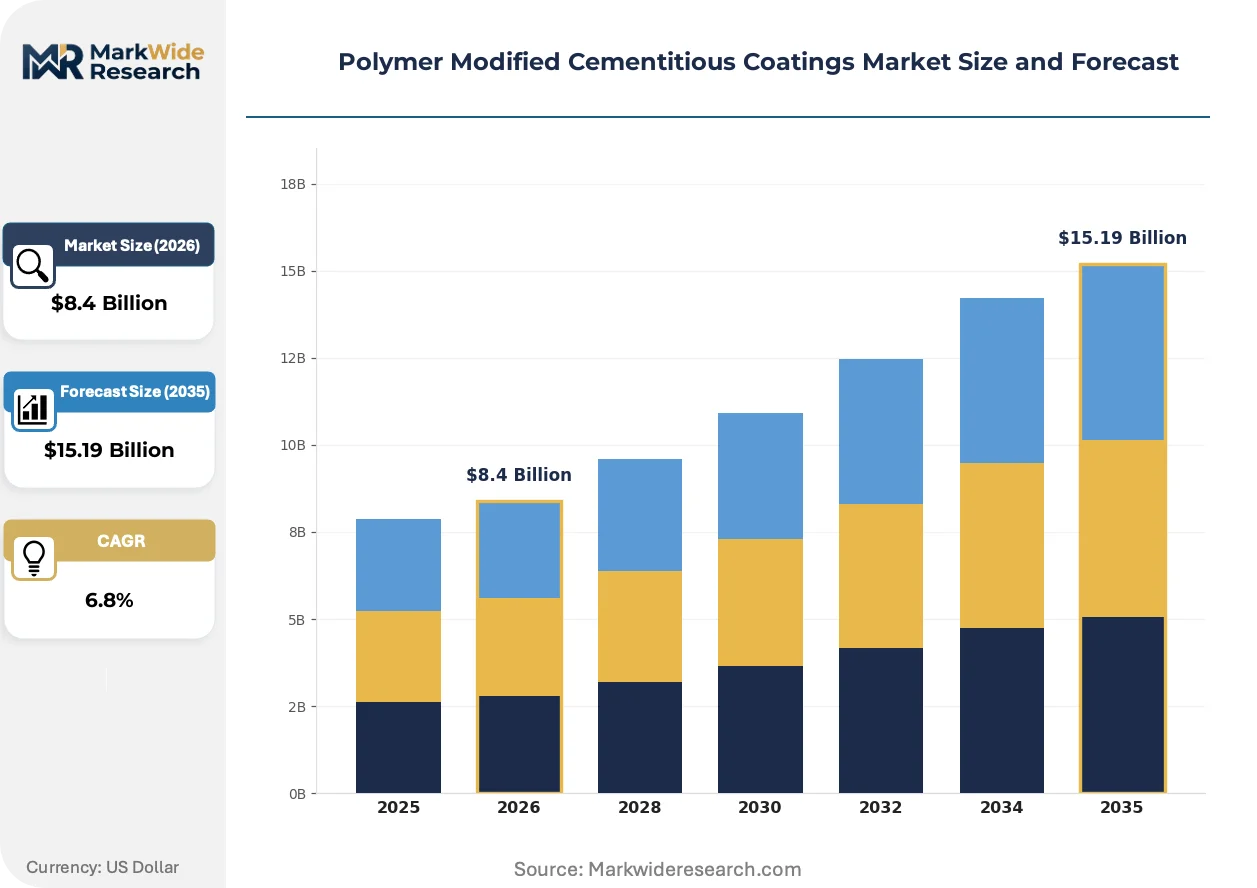
Market Dynamics
The primary dynamic shaping the polymer modified cementitious coatings market is the intersection of stringent environmental regulations and the performance demands of large-scale infrastructure. Policies like the EU Green Deal are compelling a shift toward more durable, lower-VOC polymer formulations for construction.
Growth Catalysts
- Infrastructure Modernization:Government-funded programs for renewing aging bridges, tunnels, and water systems in countries like the United States and Germany create sustained demand for high-performance protective coatings.
- Waterproofing Standards:Increasingly stringent building codes for water management, particularly for below-grade structures and reservoirs in regions like the Middle East and India, mandate the use of impermeable cementitious systems.
- Urban Development in China:Continued massive investment in new residential, commercial, and public works construction across China provides a concentrated and high-volume demand base for all grades of cementitious coatings.
Market Restraints
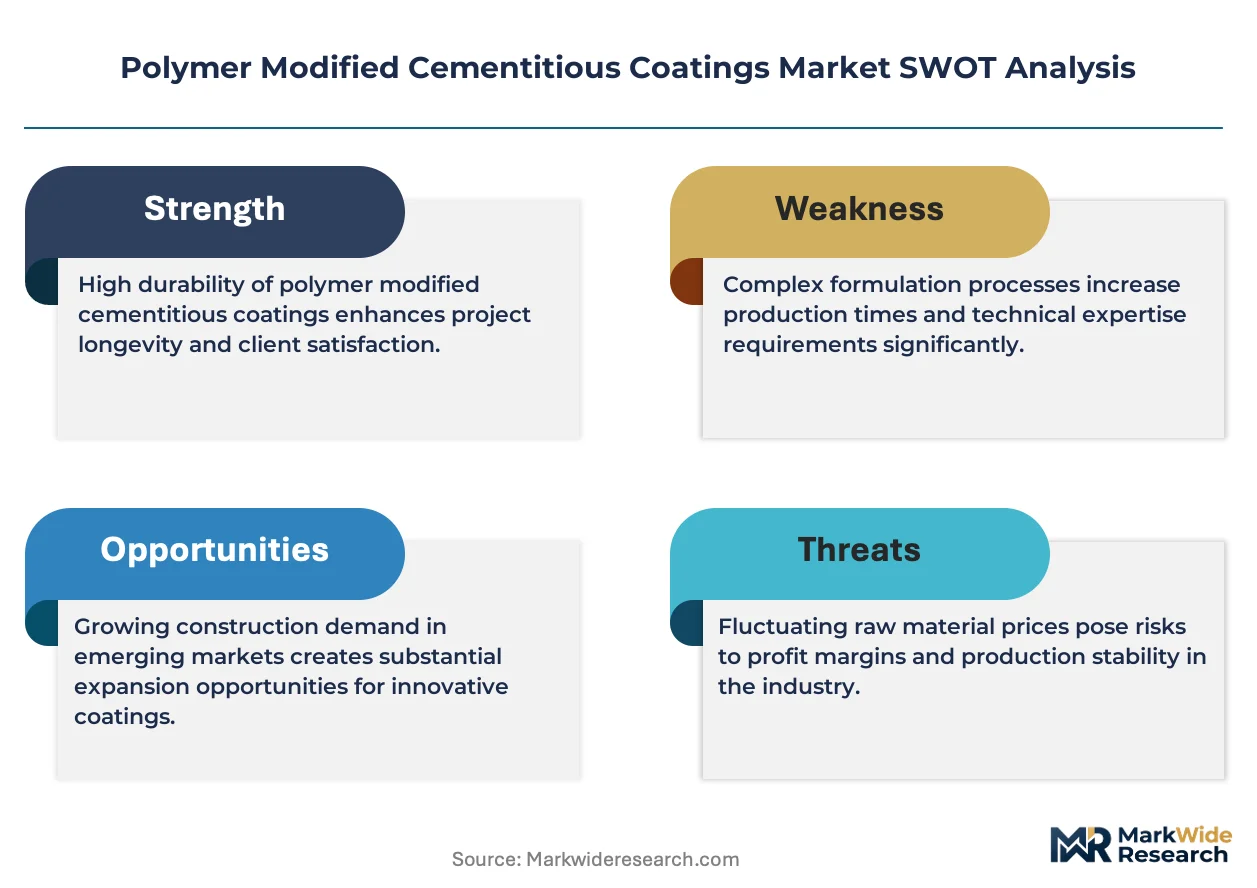
- Petrochemical Dependency:The cost and supply of key polymers, such as acrylics and styrene-butadiene, are directly linked to volatile oil and natural gas feedstock markets, creating price instability for manufacturers.
- Performance Trade-offs:Formulators face a persistent technical challenge in balancing flexibility and crack-bridging capabilities with the necessary compressive strength and adhesion required for structural applications.
- Threat from Pure Polymer Systems:For certain applications like industrial flooring and chemical containment, pure epoxy or polyurethane systems offer superior chemical resistance and abrasion performance, representing a significant substitution threat.
Strategic Opportunities
- Bio-Based Formulations:Developing polymers from renewable sources offers a path to differentiate products and meet the sustainability targets of architects and asset owners under frameworks like LEED and BREEAM.
- Prefabricated Construction Coatings:The growth of modular and offsite construction creates an opportunity for factory-applied coatings designed to withstand the stresses of transportation and on-site assembly.
- Smart Coatings with Sensing:Integrating piezoresistive fillers or fiber optics allows coatings to act as sensors for structural health monitoring, enabling a shift toward predictive maintenance service models for critical assets.
Industry Challenges
- Applicator Skill Gap:The performance of advanced coating systems depends on correct surface preparation and application techniques, but a persistent shortage of trained and certified applicators limits successful outcomes.
- On-Site Quality Assurance:Maintaining consistent quality, including proper mixing ratios and curing conditions, across diverse and often challenging construction site environments remains a significant operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Modified Cementitious Coatings Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Styrene-Butadiene, Epoxy, Polyurethane, Vinyl Acetate Application: Waterproofing, Anti-Corrosion, Concrete Repair, Protective Coatings, Decorative Finishes End User: Commercial Buildings, Residential Complexes, Infrastructure Projects, Industrial Facilities, Institutional Structures Packaging Type: Powder Bags, Pre-Mixed Buckets, Liquid Drums, Cartridge Tubes, Sachets |
| Companies Covered | Fosroc International, Saint-Gobain Weber, BASF SE, Pidilite Industries Limited, Akzo Nobel N.V., Sika AG, Arkema Group, H.B. Fuller, Mapei S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Modified Cementitious Coatings Market Strategic Shifts & Innovations
Material science advancements are directly responding to regulatory pressures and evolving asset management philosophies. The focus is shifting from simple protection to extending the service life of structures through more intelligent and sustainable coating formulations, influencing both product development and market positioning.
Self-healing technologies, incorporating microcapsules filled with healing agents, are a key innovation. These systems are being adopted by owners of critical infrastructure, such as bridges and dams, who seek to minimize downtime and repair costs. This technology is modularizing maintenance by automating crack repair at a microscopic level, thereby extending the operational life of concrete structures.
Europe's Corporate Sustainability Reporting Directive (CSRD) is compelling manufacturers to provide transparent, verifiable data on the environmental impact of their products. This regulation forces a greater emphasis on lifecycle assessment, including embodied carbon and durability metrics. Premium product segments, which often base their value proposition on longevity, are most affected as they must now substantiate these claims with robust data.
Specification by performance is displacing traditional brand-based purchasing, especially in the waterproofing segment. Instead of selecting a named product, engineering consultants and architects now define required outcomes like hydrostatic pressure resistance and crack-bridging ability. This trend is most prominent in large-scale commercial and public infrastructure projects across North America and Western Europe, favoring suppliers with strong technical data and testing credentials.
Polymer Modified Cementitious Coatings Market Segmentation
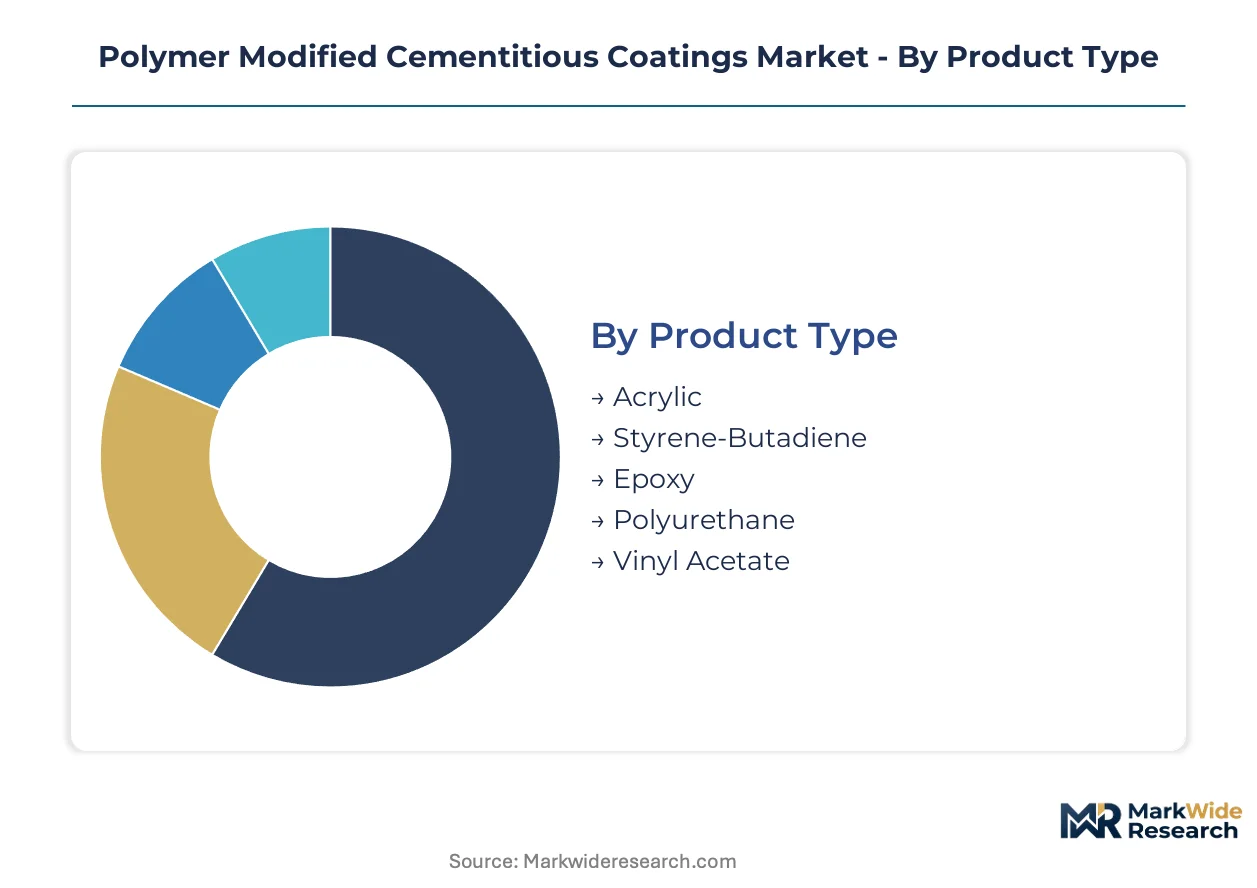
Segmentation of the polymer modified cementitious coatings market reveals distinct performance and application tiers. Understanding these segments helps manufacturers tailor formulations for specific structural demands. This granular view informs strategic positioning across diverse construction projects.
Product Type:
The product type segmentation reflects the material science evolution driving product longevity and replacement cycles in construction.
- Acrylic:Acrylic polymers, often used in water-based systems, impart excellent UV stability and weather resistance for exterior applications. Demand is concentrating in residential and commercial facades across Germany and the United States, driven by a need for durable, low-VOC finishes.
- Styrene-Butadiene:Styrene-butadiene (SBR) polymers enhance flexibility, adhesion, and crack-bridging capabilities in cementitious mortars. Infrastructure projects in China and India increasingly specify SBR-modified coatings for bridge decks and reservoir linings, requiring superior resistance to dynamic loads.
- Epoxy:Epoxy-modified coatings offer high chemical resistance and compressive strength, often specified for industrial flooring and chemical containment areas.
- Polyurethane:Polyurethane formulations provide superior elasticity and abrasion resistance, finding use in highly trafficked areas and waterproofing membranes.
- Vinyl Acetate:Vinyl acetate polymers improve adhesion and workability, commonly used in tile adhesives and repair mortars for general construction.
Acrylic sits at the top of the volume ranking, with Styrene-Butadiene climbing the fastest.
Application:
Application segments often align with varying performance requirements and associated cost tiers for project owners.
- Waterproofing:Waterproofing applications require impermeable barriers to protect structures from moisture ingress, frequently employing flexible polymer-modified systems. Commercial buildings and underground infrastructure in regions like the Middle East and Southeast Asia drive significant demand due to high humidity and water table challenges.
- Concrete Repair:Concrete repair coatings restore structural integrity and appearance to deteriorated concrete elements, often incorporating fiber reinforcement for enhanced crack resistance. Aging infrastructure in the United States and Japan relies heavily on these solutions for bridges and dams, extending asset lifecycles.
- Anti-Corrosion:Anti-corrosion coatings protect steel reinforcement within concrete from chemical attack and environmental degradation, particularly in marine or industrial environments.
- Protective Coatings:General protective coatings shield surfaces from wear, abrasion, and minor chemical exposure, extending the service life of masonry and concrete.
- Decorative Finishes:Decorative finishes combine aesthetic appeal with protective qualities, used in architectural applications for floors and walls.
Waterproofing applications command the largest market share, with concrete repair exhibiting significant expansion due to infrastructure aging.
End User:
End-user categories define distinct customer profiles, each with specific procurement processes and performance expectations.
- Infrastructure Projects:Infrastructure projects encompass large-scale public works such as bridges, tunnels, and transportation networks, demanding high-durability and long-lifecycle coatings. Government-funded programs in Germany and Canada prioritize these applications for national asset preservation.
- Commercial Buildings:Commercial buildings include offices, retail spaces, and hospitality venues, where coatings must balance aesthetic appeal with performance for high-traffic areas. Urban development in major cities like Dubai and Singapore drives demand for both protective and decorative solutions.
- Residential Complexes:Residential complexes require cost-effective and easy-to-apply coatings for waterproofing, flooring, and façade protection in multi-unit dwellings.
- Industrial Facilities:Industrial facilities, including manufacturing plants and warehouses, specify coatings for chemical resistance, abrasion protection, and heavy-duty flooring.
- Institutional Structures:Institutional structures like hospitals and schools require coatings that meet stringent hygiene, safety, and durability standards.
Infrastructure projects represent a high-value segment, while commercial buildings demonstrate consistent volume growth.
Packaging Type:
Packaging type often correlates with the volume and scale of application, influencing logistics and on-site efficiency.
- Powder Bags:Powder bags are the most common packaging for dry-mix polymer-modified cementitious coatings, offering extended shelf life and cost-effective transport. Large construction sites in India and Brazil favor this format for bulk mixing and extensive area coverage.
- Pre-Mixed Buckets:Pre-mixed buckets contain ready-to-use formulations, simplifying application and ensuring consistent quality on smaller projects or for specialized repairs. Professional applicators in the UK and Australia prefer these for convenience and reduced on-site labor.
- Liquid Drums:Liquid drums package polymer emulsions or liquid components for two-part systems, typically used for large-volume industrial applications.
- Cartridge Tubes:Cartridge tubes deliver small quantities of specialized repair or sealing compounds, ideal for precise application in niche repairs.
- Sachets:Sachets provide single-use portions for minor repairs or DIY applications, offering convenience and minimizing waste.
Powder bags dominate the market by volume, with pre-mixed buckets gaining traction in efficiency-driven projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering and construction expertise globally drives demand for advanced polymer modified cementitious coatings. These specialized materials are critical for ensuring the longevity and performance of modern infrastructure. Demand concentrations reflect significant investment cycles in public works and urban development projects worldwide.
United States
Infrastructure modernization programs, particularly for aging bridges and dams, create sustained demand for high-performance protective coatings. EPA standards on volatile organic compounds (VOCs) push manufacturers towards water-based systems. Cities along the Northeast Corridor, with extensive historical infrastructure, represent a significant market for concrete repair and protective applications.
Germany
Government-funded programs for renewing critical infrastructure and the EU Green Deal's emphasis on durable construction materials drive innovation. REACH framework regulations govern the chemical substances used in coating formulations. The Rhine-Ruhr region, a dense industrial and urban cluster, shows strong demand for advanced polymer systems in both new builds and renovation projects.
China
Massive urban development and public works provide a concentrated and high-volume demand base for all grades of cementitious coatings. Dual carbon goals compel a shift towards more sustainable and durable construction materials. The Yangtze River Delta region, with its extensive new residential, commercial, and transportation infrastructure, represents a primary consumption hub.
India
Increasingly stringent building codes for water management and large-scale infrastructure projects mandate the use of impermeable cementitious systems. BIS standards for construction materials ensure quality and performance in public and private projects. Major metropolitan areas like Mumbai and Delhi-NCR exhibit strong demand from both commercial building and residential complex construction.
United Arab Emirates
Commercial buildings and underground infrastructure in the UAE drive significant demand for waterproofing due to high humidity and water table challenges. MOHAP building codes emphasize robust moisture protection for new developments. Dubai and Abu Dhabi, characterized by rapid high-rise construction, are key markets for flexible polymer-modified systems.
Polymer Modified Cementitious Coatings Market Key Industry Players
Capital-heavy producers of base chemicals compete with asset-light formulators specializing in end-use applications within the polymer modified cementitious coatings market. The market exhibits a tiered structure, with global chemical giants providing raw polymers and specialized coating manufacturers developing application-specific formulations. Strategic archetypes include global material science conglomerates, regional application specialists, and niche solution providers. Dominant competitive moves include strategic partnerships for technology transfer and portfolio diversification to serve varied customer segments.
Within the global material science archetype, Sika AG and BASF SE represent comprehensive solution providers. Sika AG, a Swiss-based company, exemplifies broad portfolio strength across construction chemicals, serving large-scale infrastructure projects. BASF SE, a German chemical company, anchors deep polymer chemistry expertise and material science differentiation. Pidilite Industries Limited, an Indian-origin entity, occupies a strong position in specific regional residential and commercial segments, influencing product development and market access across diverse geographies.
| Leading Market Players |
|---|
| Fosroc International |
| Saint-Gobain Weber |
| BASF SE |
| Pidilite Industries Limited |
| Akzo Nobel N.V. |
| Sika AG |
| Arkema Group |
| H.B. Fuller |
| Mapei S.p.A. |
| Others |
Cost & Logistics Intelligence
Vertical integration by chemical manufacturers anchors the supply position for key polymers, influencing pricing power across the polymer modified cementitious coatings market. This strategy also shapes the availability of specialized formulations for diverse construction projects.
Pricing Analysis
Bundled product-and-service offerings drive premium pricing for high-performance polymer modified cementitious coatings, especially for large infrastructure projects. Project-based pricing dominates, with differentiation stemming from application expertise and certification levels. Pricing softness affects commodity-grade products due to input cost volatility, particularly petrochemicals. Commercial building and residential segments exhibit higher price sensitivity compared to critical infrastructure projects.
Supply Chain Analysis
Certification and qualification standards gate market access for polymer modified cementitious coatings, particularly in regulated construction markets like the EU and US. Supply of key polymers like acrylics and styrene-butadiene draws from manufacturing hubs in China, Germany, and the United States. Petrochemical dependency creates structural risk from commodity price volatility. Downstream distribution runs through a network of specialized construction material distributors and direct sales to large project contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polymer modified cementitious coatings market acts as a regulatory compounder, with the EU Green Deal significantly driving demand for durable, sustainable construction materials. This regulatory push elevates performance requirements and material science innovation across the industry.
For Market Incumbents:Lock in long-term supply agreements for bio-based polymer feedstocks to mitigate petrochemical dependency and meet sustainability goals. Invest in advanced applicator training programs to address the skill gap and ensure consistent application quality for complex formulations. This defends against substitution threats from pure polymer systems and secures market share in high-specification infrastructure projects. Focus R&D on self-healing technologies to extend product lifecycles and differentiate offerings.
For New Entrants and Emerging Players:A price-point gap exists between premium, high-specification products and basic commodity grades, particularly in residential and light commercial segments. Target underpenetrated regional markets like Southeast Asia with cost-effective SBR-modified coatings for waterproofing applications. Leverage modular construction trends by developing factory-applied coatings for offsite assembly, offering a distinct go-to-market angle. Focus on transparent, verifiable environmental data to appeal to sustainability-conscious developers.
For Investors and Strategic Acquirers:Roll-up economics work for regional application specialists because the market fragments across diverse local building codes and specific project requirements. Long-term viability is strong over the next decade due to persistent infrastructure aging and new urban development. Target specialist formulators with strong technical data and established applicator networks in high-growth regions. Watch for increasing regulatory enforcement of sustainability metrics as an inflection indicator for premium segment consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | This initiative meets rising demand from massive urban development projects across China. |
| Bio-Based Polymer R&D | This aligns product portfolios with the EU Green Deal's stringent sustainability targets. |
| Applicator Training Programs | These ensure correct application techniques for advanced, high-performance coating formulations. |
| Smart Coating Integration | This enables predictive maintenance and structural health monitoring for critical infrastructure assets. |
| Strategic Partnerships | These expand market access and distribution channels within specific regional segments. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window for a comprehensive market understanding. Primary research involved R&D directors, procurement leads, application specialists, and regulatory affairs managers. Secondary validation drew from construction industry reports, national building codes, and chemical industry association data. This approach facilitated bottom-up and top-down triangulation of market insights.
The segment-weighting approach informed market projections, integrating detailed analysis across product type, application, end-user, and packaging type. Forecasts considered infrastructure spending and regulatory shifts as key inputs across the modeling period. Compound Annual Growth Rates were derived from historical trends, projected demand drivers, and expert consultations. This framework captured market dynamics.
Caveats apply where significant shifts in petrochemical feedstock prices or global infrastructure investment policies could materially shift the outlook, reflecting assumptions on technological advancements and regulatory stability. A model refresh is warranted upon material change in key polymer supply or environmental regulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Plastic Coatings Market
Coatings
Europe Powder Coatings Market
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
Asia-Pacific Marine Coatings Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Marine Nanocoating Market
Coatings
Coatings and Fillings Market
Coatings
Brazil Automotive OEM Coatings Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Electrocoat Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
Europe Thermal Spray Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Stain Resistant Coatings Market
Coatings
Extrusion Coating Market