
 Asia-Pacific Marine Coatings Market | 2026-2036
Asia-Pacific Marine Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Marine Coatings Market Insights
Performance-based maintenance contracts is consolidating as the dominant service layer, shifting revenue from gallon sales to hull-performance guarantees over multi-year terms. PPG Industries leverages its regional technical service network to anchor long-term fleet agreements across Southeast Asian ports. Hempel A/S differentiates through silicone-based fouling-release systems that reduce dry-dock frequency for container operators. Chugoku Marine Paints Ltd. dominates Japanese newbuild contracts through integrated supply arrangements with domestic shipyards.
Asia-Pacific marine coatings are protective film systems formulated from epoxy, polyurethane, or silicone resin matrices with biocide or foul-release additives, applied to submerged and atmospheric steel surfaces to prevent corrosion and biofouling while maintaining hydrodynamic efficiency. Epoxy primers and anti-fouling topcoats constitute the majority of volume, though polyurethane finishes command premium positioning in yacht and passenger vessel segments where gloss retention and UV resistance determine specification. Water-based technologies are gaining share in shipyard applications where VOC limits tighten, while nano-coatings remain a nascent but high-margin pool concentrated in specialized naval and superyacht builds across South Korean yards.
China's MEE enforces VOC caps and hazardous substance limits that compel reformulation of solvent-based systems, while Japan's METI promotes low-friction hull technologies through energy-efficiency benchmarking for domestic fleets. South Korea's environmental ministry aligns with IMO conventions to phase out tributyltin and high-copper biocides, redirecting R&D toward silicone and hydrogel foul-release chemistries. Shipowners and coating suppliers must calibrate product portfolios against divergent national compliance timelines and emerging lifecycle-carbon accounting for hull performance.
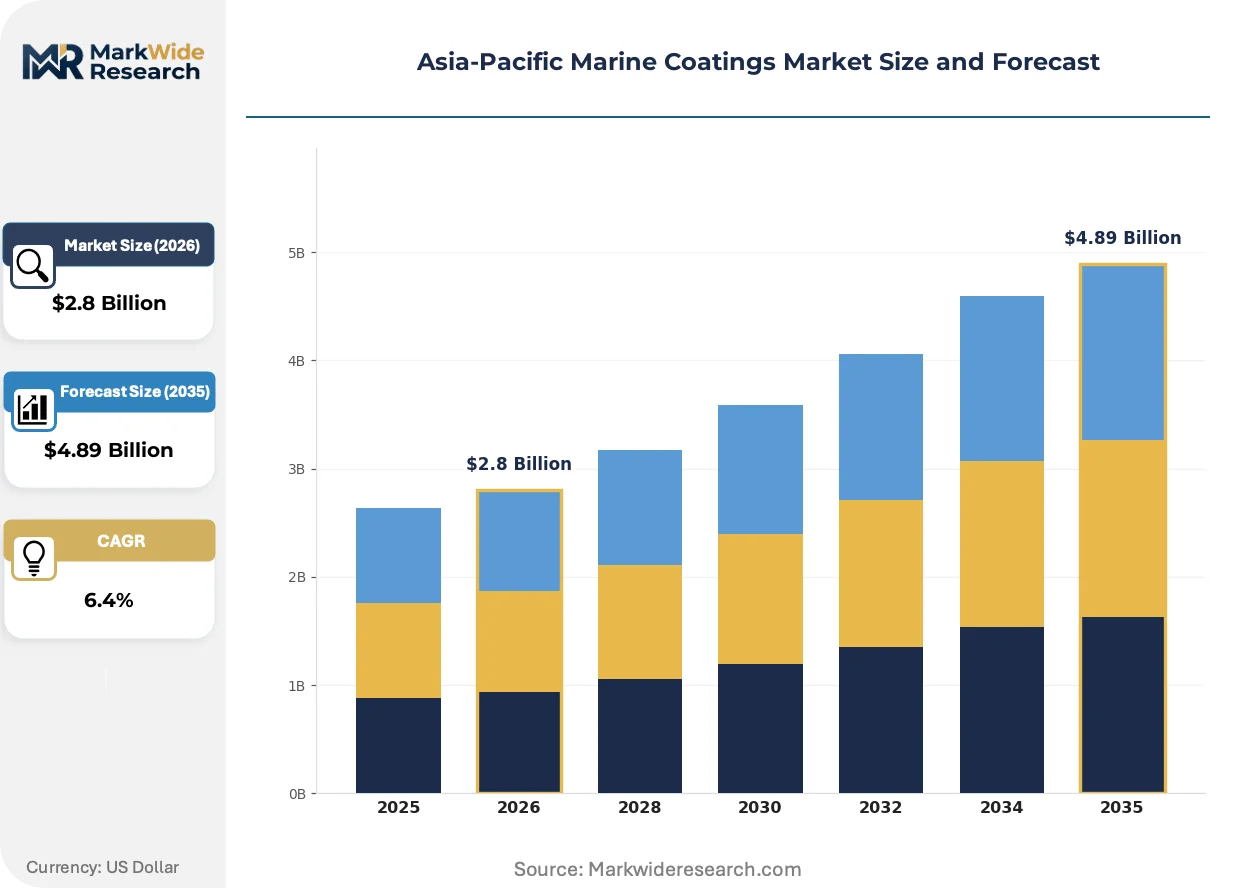
Market Dynamics
Fleet operators across Asia-Pacific are abandoning spot-purchase coating procurement in favor of performance-guaranteed hull management contracts that transfer biofouling risk from shipowner to supplier. This structural inversion compresses coating gallons into embedded service revenue and locks technical service networks into multi-year anchoring agreements.
Growth Catalysts
- China MEE Emissions Enforcement:Tightening VOC caps and hazardous substance limits under MEE directives are forcing solvent-based system reformulation, accelerating demand for compliant water-based and high-solids alternatives in domestic shipyards.
- Silicone Foul-Release Chemistry:Biocide-free silicone technologies are displacing copper-based anti-fouling in Japanese newbuild specifications, driven by dry-dock frequency reduction guarantees and lifecycle cost optimization.
- South Korean Naval Modernization:Specialized nano-coating specifications for stealth and corrosion resistance in naval vessel programs are creating premium demand pools concentrated in Geoje and Ulsan shipbuilding clusters.
Market Restraints
- Epoxy Resin Input Volatility:Bisphenol-A and amine hardener feedstock price swings compress formulation margins, particularly for high-build epoxy primer systems serving bulk carrier maintenance cycles.
- Biocide Supply Concentration:Active ingredient production for copper pyrithione and zinc pyrithione concentrates in Chinese chemical manufacturing hubs creates single-source vulnerability for conventional anti-fouling producers.
- Silicone Adhesion Limitations:Substrate preparation requirements and in-service damage repair complexity restrict silicone foul-release adoption to newbuild applications, excluding retrofit opportunities.
Strategic Opportunities
- Vietnamese Shipyard Expansion:Greenfield yard development in Haiphong and Vung Tau is creating first-mover positioning for coating suppliers willing to establish localized technical service infrastructure ahead of fleet growth.
- Lifecycle Carbon Accounting:Emerging IMO frameworks for hull performance carbon intensity are creating specification pull for low-friction coatings that demonstrably reduce fuel consumption across voyage profiles.
- Digital Hull Monitoring Convergence:Integration of ultrasonic fouling sensors with coating warranty systems is enabling predictive maintenance contracts that monetize performance data alongside film integrity guarantees.
Industry Challenges
- Applicator Certification Bottlenecks:Qualified spray technicians for high-performance polyurethane yacht finishes remain scarce in Southeast Asian shipyards, constraining premium segment expansion.
- Multi-Jurisdiction Compliance Complexity:Divergent national implementation timelines for biocide bans across China, Japan, and South Korea force portfolio fragmentation and redundant registration expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Marine Coatings Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Anti-fouling, Primer Application: Commercial Vessels, Cargo Ships, Yachts, Fishing Boats End User: Shipping Companies, Shipbuilders, Marine Service Providers, Government Technology: Water-Based, Solvent-Based, Powder Coatings, Nano Coatings |
| Companies Covered | PPG Industries, Nippon Paint Marine Coatings Co. Ltd., AkzoNobel N.V., Kansai Paint Marine Coatings Co. Ltd., Hempel A/S, Chugoku Marine Paints Ltd., The Sherwin-Williams Company, KCC, Jotun, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Marine Coatings Market Trends and Innovations
Active coating intelligence and predictive hull performance modeling are displacing static specification sheets, embedding suppliers into continuous vessel optimization rather than discrete dry-dock transactions. This reconfiguration rewards technical service density over manufacturing scale.
Silicone-hydrogel hybrid foul-release systems are decentralizing anti-fouling technology ownership from centralized chemical suppliers to vessel operators equipped with in-service monitoring capabilities. Japanese container lines operating transpacific routes are piloting these systems at pace, attracted by five-year dry-dock interval guarantees. The technology is decentralizing maintenance scheduling authority from classification society survey cycles to real-time hull condition data streams.
South Korea's environmental ministry alignment with IMO tributyltin and high-copper biocide phase-out conventions is redirecting R&D expenditure toward silicone and hydrogel chemistries. Domestic coating producers face reformulation deadlines that compress product development timelines while opening technical collaboration opportunities with European foul-release specialists. Container operators with Korean-flagged fleets are responding by pre-qualifying silicone-based systems in newbuild tenders ahead of regulatory effective dates.
Shipowner procurement functions are consolidating coating specification authority under fleet technical managers, displacing traditional shipyard purchasing autonomy. Performance-based contracts with hull-speed guarantees are replacing gallon-based procurement in Singapore-flagged and Hong Kong-flagged container fleets. This concentration is most visible in transpacific liner operations where fuel cost exposure drives specification consolidation across vessel classes.
Asia-Pacific Marine Coatings Market Segmentation
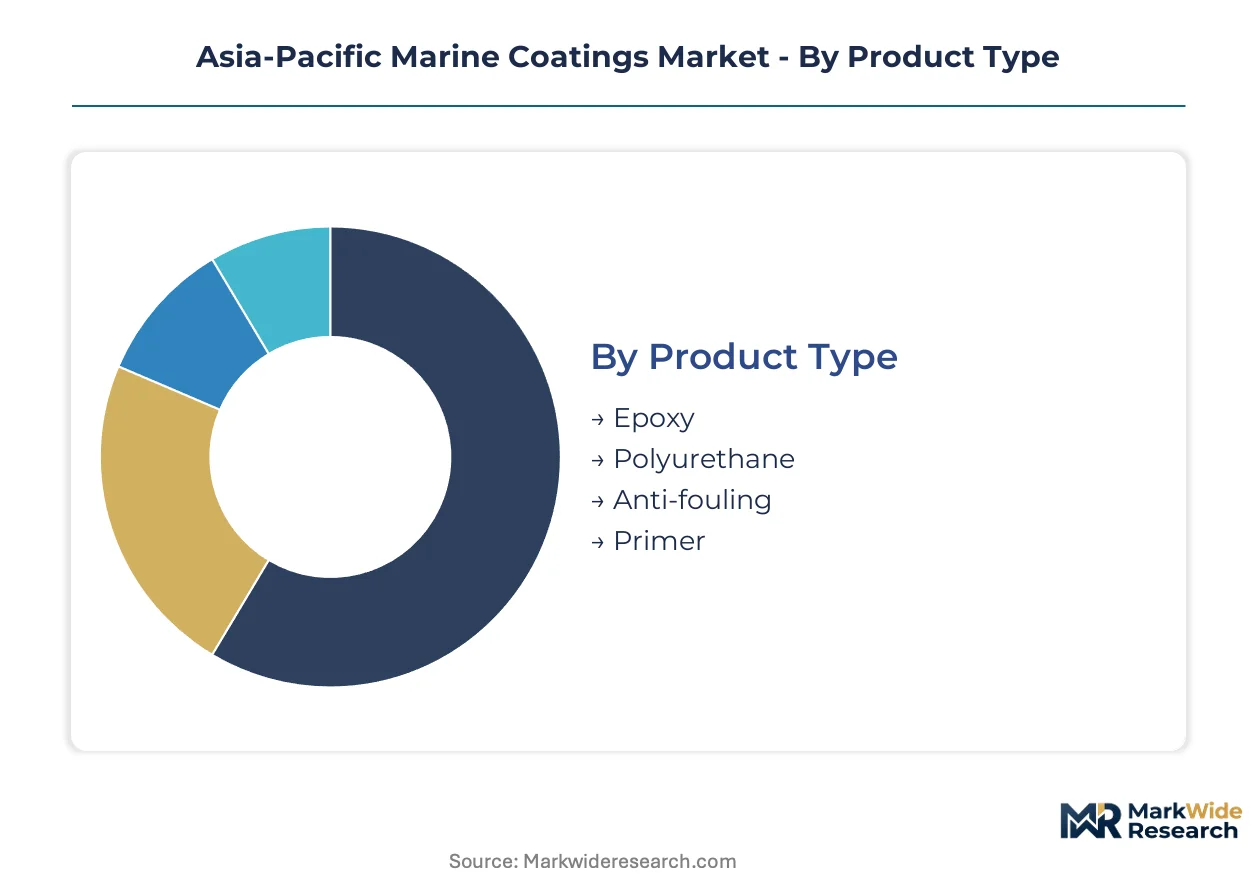
Marine coatings segmentation in Asia-Pacific reflects divergent certification burdens across hull zones and vessel classes. Product chemistry, application environment, and end-user procurement authority each impose distinct compliance pathways that reshape supplier positioning.
Product Type:
Epoxy primers carry IMO PSPC type-approval mandates for ballast tank applications, while anti-fouling topcoats face biocide registration under China's MEE and Japan's METI chemical substance laws. Polyurethane finishes require yacht-class gloss retention certifications that few Southeast Asian applicators maintain.
- Epoxy:High-build amine-cured systems dominate ballast tank and cargo hold specifications, with PSPC compliance mandatory for international trading vessels. Chinese bulk carrier operators at Dalian and Qingdao yards drive volume concentration amid fleet renewal programs.
- Anti-fouling:Biocide-laden or silicone foul-release films applied to submerged hull surfaces prevent biofouling accumulation. Japanese container lines at Nagasaki and Kure shipyards are pre-qualifying silicone-based systems to extend dry-dock intervals under METI energy-efficiency benchmarking.
- Polyurethane:Aliphatic topcoat systems deliver UV-stable gloss retention for superstructure and yacht applications. Premium specifications from South Korean superyacht builders at Geoje cluster constrain supply to certified applicator networks.
- Primer:Zinc-rich and surface-tolerant formulations provide cathodic protection and adhesion promotion. Maintenance demand from Vietnam's expanding Haiphong repair yards creates retrofit volume for conventional epoxy-amine systems.
Epoxy sits at the top of the volume ranking, with anti-fouling climbing the fastest.
Application:
Hull zone geometry and operational duty cycles fragment specification authority across vessel classes. Deep-draft commercial fleets prioritize fuel-efficiency guarantees, while yacht builders emphasize aesthetic performance metrics.
- Commercial Vessels:Container ships and tankers operating transpacific routes specify low-friction foul-release systems under lifecycle carbon accounting frameworks. Singapore-flagged fleet technical managers are consolidating procurement authority under performance-based hull management contracts.
- Cargo Ships:Bulk carriers and general cargo vessels subject to abrasive loading in holds require high-build epoxy tank lining systems. Chinese MEE VOC enforcement is accelerating water-based primer adoption at domestic newbuild yards.
- Yachts:Gloss retention and color stability specifications dominate superyacht and passenger vessel segments. South Korean nano-coating development for naval stealth applications is spilling into high-end civilian specifications at Ulsan clusters.
- Fishing Boats:Small-scale fleet operators in Indonesia and Philippines prioritize cost-minimized maintenance cycles over performance guarantees. Localized biocide registration gaps create informal supply channels outside major coating networks.
Cargo ships anchor volume concentration, with yachts gaining share fastest.
End User:
Procurement centralization varies sharply by ownership structure. State-linked fleets leverage integrated supply arrangements, while independent operators retain shipyard purchasing autonomy.
- Shipping Companies:Fleet technical managers at major container lines are displacing traditional shipyard purchasing authority. Performance-guaranteed contracts with hull-speed warranties now dominate Singapore and Hong Kong-flagged fleet specifications.
- Shipbuilders:Japanese yards at Nagasaki and Kure maintain integrated supply arrangements with domestic coating producers for newbuild contracts. Chugoku Marine Paints leverages these captive channels to lock out multinational competitors.
- Marine Service Providers:Independent dry-dock operators across Southeast Asian ports compete on turnaround speed and technical service density. PPG Industries anchors regional fleet agreements through localized service network investments.
- Government:Naval modernization programs in South Korea specify specialized corrosion-resistant and stealth-optimized nano-coatings. Geoje and Ulsan shipbuilding clusters concentrate premium R&D expenditure for military-grade film systems.
Shipping companies command the largest procurement scale, with government expanding most quickly.
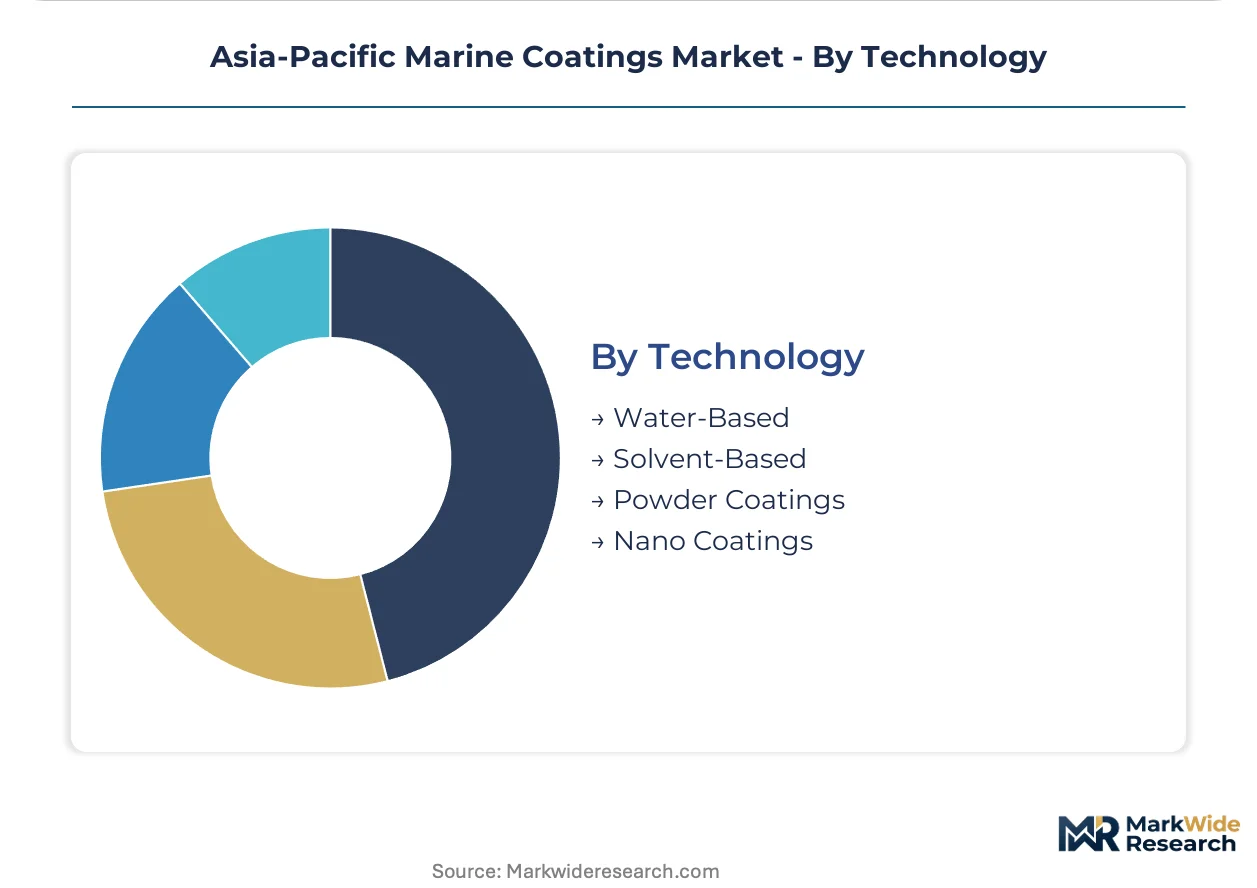
Technology:
Formulation chemistry determines VOC compliance trajectory and application method constraints. Water-based systems gain share where shipyard emissions limits tighten, while nano-coatings remain confined to premium military and superyacht niches.
- Water-Based:Reduced-VOC epoxy and polyurethane dispersions satisfy China's MEE shipyard emissions caps. Reformulation investments by domestic Chinese producers are accelerating substitution for conventional solvent-borne systems.
- Solvent-Based:High-solids and conventional solvent systems retain cost advantage in maintenance applications where regulatory enforcement varies. Biocide supply concentration in Chinese chemical hubs creates formulation vulnerability for conventional anti-fouling producers.
- Powder Coatings:Thermoset epoxy and polyester powders serve superstructure and tank internal applications requiring zero-VOC curing. Limited adoption reflects substrate size constraints and field repair complexity for marine assets.
- Nano Coatings:Silica and ceramic nanoparticle-enhanced films deliver extreme corrosion resistance for naval and specialized superyacht specifications. South Korean environmental ministry alignment with IMO conventions is redirecting R&D toward these premium chemistries.
Solvent-based technology retains volume leadership, with water-based formulations climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within Asia-Pacific follows divergent national compliance calendars, with coating formulators arbitraging cost-of-compliance gaps between China's MEE enforcement corridors and Vietnam's lagging VOC implementation timelines.
China
Commercial fleet renewal at Dalian and Qingdao yards drives epoxy primer volume, while MEE VOC caps force solvent-based reformulation toward water-borne alternatives. Domestic producers accelerate high-solids R&D to retain market position amid tightening emissions benchmarks.
Japan
Container operators at Nagasaki and Kure pre-qualify silicone foul-release systems under METI energy-efficiency benchmarking. Chugoku Marine Paints leverages integrated supply arrangements with domestic shipyards to lock newbuild specifications against multinational entrants.
South Korea
Naval modernization programs at Geoje and Ulsan clusters create premium demand for nano-coating stealth applications. The environmental ministry's alignment with IMO biocide phase-out conventions redirects R&D expenditure toward silicone and hydrogel chemistries ahead of regulatory deadlines.
Vietnam
Greenfield yard development in Haiphong and Vung Tau attracts first-mover coating suppliers establishing localized technical service infrastructure. Maintenance demand from expanding repair yards creates retrofit volume for conventional epoxy-amine primer systems.
Singapore
Flagged fleet technical managers consolidate procurement authority under performance-guaranteed hull management contracts. Transpacific liner operations drive specification consolidation across vessel classes as fuel cost exposure intensifies.
Asia-Pacific Marine Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated coating suppliers commanding newbuild specifications while independent service providers anchor maintenance volumes. The structure concentrates around technical service density rather than manufacturing scale. Three archetypes dominate: domestic Japanese producers with captive shipyard relationships, European foul-release specialists licensing silicone technology, and diversified chemical majors building regional fleet agreements through port-level service networks. Competitive moves center on multi-year performance contracting and backward integration into applicator certification programs.
Among Asia-Pacific-based specialists, Chugoku Marine Paints Ltd. and Kansai Paint Marine Coatings Co. Ltd. occupy positions tied to domestic Japanese shipyard supply chains. European-origin players exemplified by Hempel A/S represent the silicone foul-release technology tier, while PPG Industries anchors diversified chemical major participation through Southeast Asian technical service investments.
| Leading Market Players |
|---|
| PPG Industries |
| Nippon Paint Marine Coatings Co. Ltd. |
| AkzoNobel N.V. |
| Kansai Paint Marine Coatings Co. Ltd. |
| Hempel A/S |
| Chugoku Marine Paints Ltd. |
| The Sherwin-Williams Company |
| KCC |
| Jotun |
| Others |
Pricing and Supply Chain Analysis
Container fleet technical managers in Singapore and Hong Kong are consolidating procurement authority under performance-guaranteed hull management contracts, embedding coating gallons into multi-year service revenue streams rather than transactional spot purchases.
Pricing Analysis
Capacity additions in Vietnam are reshaping price floors for conventional epoxy-amine primer systems serving maintenance demand from Haiphong repair yards. Three-tier pricing structure across premium silicone foul-release, standard high-solids epoxy, and economy solvent-based tiers reflects certification grade and dry-dock guarantee duration. Cost compression in economy tiers is intensifying because Chinese MEE VOC enforcement accelerates water-borne reformulation investments. Independent dry-dock operators in Indonesia and the Philippines exhibit highest price sensitivity, while Japanese container lines at Nagasaki and Kure yards accept premium positioning for five-year dry-dock interval guarantees.
Supply Chain Analysis
Dual-sourcing qualification mandates from South Korean naval modernization programs are fragmenting nano-coating procurement across domestic and European specialty suppliers. Bisphenol-A and amine hardener feedstock production concentrates in China, South Korea, and Japan, while copper pyrithione active ingredient supply rests on Chinese chemical manufacturing hubs. Single-source vulnerability for conventional anti-fouling biocides creates formulation risk for producers dependent on centralized Chinese supply. Distribution runs through port-level technical service networks anchored by PPG Industries and Hempel A/S across Southeast Asian maritime corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific marine coatings market represents a late-cycle quality story as Japanese and South Korean fleet operators pre-qualify silicone foul-release systems ahead of regulatory phase-out deadlines for high-copper biocides.
For Market Incumbents: Lock in multi-year performance contracts with transpacific container lines before silicone-hydrogel hybrid technologies mature. Anchor technical service density in Vietnamese greenfield yards at Haiphong and Vung Tau to preempt entrant positioning. Backward integration into applicator certification programs defends margin position against qualified spray technician scarcity for high-gloss polyurethane yacht finishes. For New Entrants and Emerging Players: Vietnamese shipyard expansion represents the most penetrable white-space target, with localized technical service infrastructure creating first-mover advantage ahead of fleet growth. Fishing boat operators in Indonesia and the Philippines present underserved retrofit volume outside major coating networks. Partner with ultrasonic fouling sensor providers to monetize predictive maintenance data alongside film integrity guarantees. For Investors and Strategic Acquirers: Diversified chemical majors are the most active acquirer in this space, seeking Southeast Asian technical service networks to anchor regional fleet agreements. Five-to-ten year viability hinges on silicone foul-release chemistry maturation and lifecycle carbon accounting framework adoption. Watch for IMO hull performance carbon intensity rules as the inflection indicator redirecting specification authority toward low-friction coating suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Foul-Release Technology Licensing | European specialists transfer biocide-free chemistry to Japanese and South Korean producers ahead of regulatory deadlines. |
| Technical Service Network Expansion | Port-level infrastructure investments in Vietnam preempt fleet growth and lock out competitor anchoring agreements. |
| Applicator Certification Program Development | In-house training for high-gloss polyurethane finishes addresses scarcity constraining South Korean superyacht segment expansion. |
| Digital Hull Monitoring Integration | Ultrasonic sensor partnerships enable predictive maintenance contracts monetizing real-time fouling data streams. |
| Backward Integration into Biocide Supply | Captive production of copper pyrithione alternatives mitigates single-source vulnerability from Chinese chemical hub concentration. |
Research Methodology
Bottom-up vessel class modeling reconciled against top-down coating supplier shipment tracking forms the analytical core of this study. Primary interviews with fleet technical managers, shipyard procurement directors, dry-dock operators, and coating R&D heads across China, Japan, South Korea, Vietnam, and Singapore were validated against secondary sources including IMO PSPC type-approval registries, MEE emissions compliance filings, METI energy-efficiency benchmarking reports, and customs trade data for epoxy resin and biocide active ingredient flows.
Input-output matrices map coating gallon consumption to vessel dry-dock cycles, newbuild completions, and regulatory compliance deadlines across the projection horizon. Segmentation dimensions include product chemistry, hull zone application, vessel class, end-user procurement structure, and national regulatory framework. CAGRs derive from regression analysis of historical fleet renewal patterns against divergent MEE, METI, and South Korean environmental ministry implementation timelines.
Underlying measurement precision varies by segment; silicone foul-release and nano-coating specifications carry tighter precision than economy solvent-based maintenance volumes due to concentrated supplier disclosure. Forecasts reflect assumptions about regulatory enforcement consistency and fleet operator contract structure preferences. Deviation in IMO lifecycle carbon accounting adoption timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Coating Equipment Market
Coatings
Marine Anti Fouling Coatings Market
Coatings
Japan Marine Coatings Market
Coatings
BRIC Performance Coatings Market
Coatings
Mexico Floor Coatings Market
Coatings
Mexico Protective Coatings Market
Coatings
Sustained Release Coatings Market
Coatings
Transparent Conductive Coatings Market
Coatings
South Africa Automotive OEM Coatings Market
Coatings
North America Powder Coatings Market
Coatings
Bio-Fouling Prevention Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
Water Based Enamel Market
Coatings
Fire Retardant Coatings Market
Coatings
Concrete Floor Coatings Market
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market