
 Europe Thermal Spray Market | 2026-2036
Europe Thermal Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Thermal Spray Market Foresight
The divergence between premium aerospace-grade coatings and commodity industrial repair services is realigning competitive strategy across Europe. Bodycote leverages its network of specialized facilities to dominate high-specification turbine coating contracts for Rolls-Royce and Safran supply chains. Kennametal Stellite anchors its position through captive tungsten carbide powder production and proprietary HVOF parameter sets. Saint-Gobain competes on ceramic feedstock purity, sustaining margins in medical implant coating segments where CE marking under MDR demands batch-level traceability.
Thermal spray encompasses deposition processes wherein molten or semi-molten material—typically metals, ceramics, or cermets—accelerates onto a substrate to build functional coatings ranging from 50 microns to several millimeters thickness, primarily serving wear resistance, corrosion protection, and dimensional restoration in high-value engineering. Plasma spraying leads European revenue contribution due to its versatility with refractory ceramics for gas turbine thermal barrier coatings, while cold spray represents the fastest-expanding technology segment as solid-state deposition avoids phase transformation in temperature-sensitive aerospace alloys. HVOF occupies the mature center of the product spectrum, with margin pools concentrating in automated cell deployments for automotive powertrain component reconditioning.
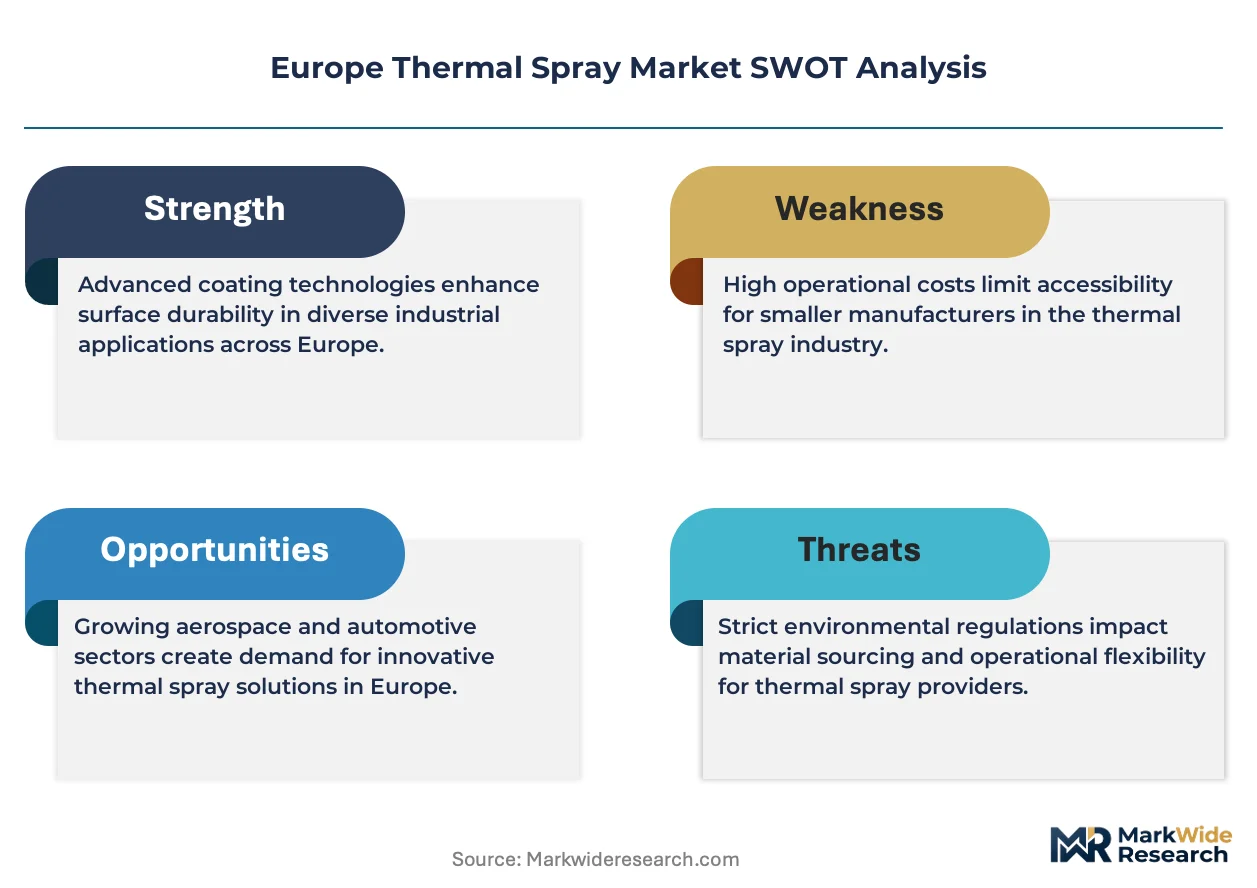
REACH restrictions on hexavalent chromium compounds and the EU F-Gas Regulation on process gases are reshaping process chemistry selection and equipment investment timelines across coating service providers. EMA oversight of medical device coatings and CE marking requirements under the revised MDR create differentiated compliance burdens between healthcare-facing and general industrial applicators. Stakeholders must monitor how the EU AI Act intersects with automated spray parameter control systems, as algorithmic process documentation may become a precondition for aerospace supplier qualification.
Market Dynamics
REACH restrictions on hexavalent chromium compounds and the EU F-Gas Regulation are forcing coating service providers to reconfigure process chemistry and equipment investments across the continent.
Growth Catalysts
- EU Green Deal decarbonization mandates:Industrial manufacturers in Germany and France accelerate substitution of chrome plating with environmentally compliant thermal spray alternatives for corrosion protection.
- Cold spray technology maturation:Aerospace OEMs adopt solid-state deposition for temperature-sensitive superalloy components, avoiding phase transformation damage during coating.
- Medical device regulation (MDR):CE marking requirements under the revised MDR create sustained demand for batch-traceable ceramic coatings on orthopedic and dental implants.
Market Restraints
- Tungsten carbide powder supply concentration:Feedstock sourcing depends on a limited supplier base concentrated in Central Europe, creating input cost volatility and security-of-supply risks.
- REACH compliance friction:ECHA substance authorization processes extend lead times for new coating material qualification, delaying commercialization of novel feedstock formulations.
- Plasma spray equipment capex intensity:Automated plasma cells require substantial capital deployment, compressing margins for mid-scale coating service providers serving commodity industrial repair segments.
Strategic Opportunities
- Poland and Czech industrial corridor expansion:Automotive powertrain manufacturers in Central Europe seek localized HVOF reconditioning capacity for transmission and engine components.
- EU AI Act algorithmic process control:Automated spray parameter documentation using machine learning creates qualification pathways for aerospace supplier tiers requiring predictive quality assurance.
- Wind turbine blade repair:Offshore wind installations in the North Sea and Baltic regions generate demand for erosion-resistant ceramic coatings on leading-edge protection systems.
Industry Challenges
- Skilled technician scarcity:HVOF and plasma spray operations require certified operators capable of parameter optimization and substrate preparation, with training pipelines failing to match replacement demand.
- CE marking timeline compression:Medical device coating applicators face extended conformity assessment periods under MDR notified body capacity constraints, delaying revenue recognition on healthcare contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Thermal Spray Market |
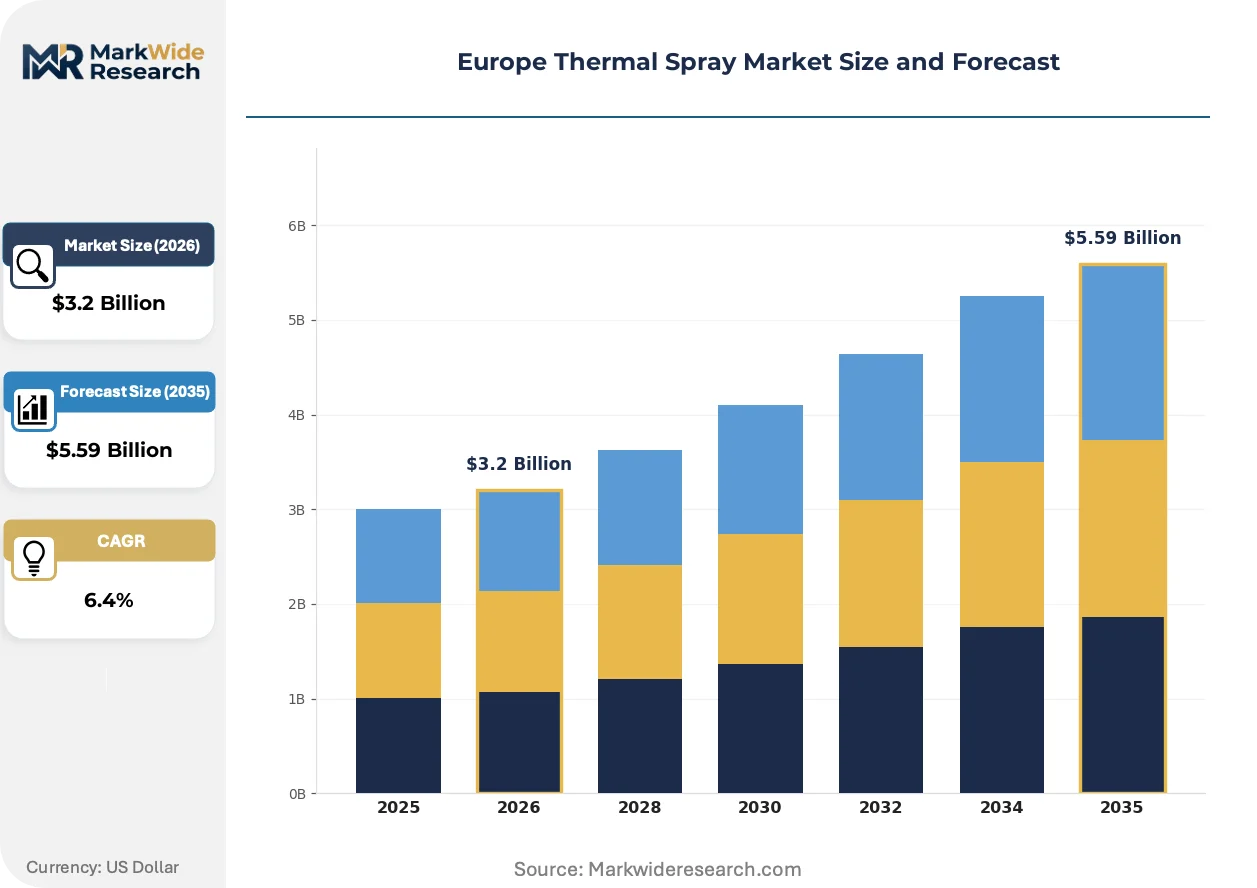
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flame Spraying, Plasma Spraying, HVOF, Cold Spray Application: Aerospace Components, Automotive Parts, Medical Devices, Industrial Equipment Technology: Thermal Spray Coating, Additive Manufacturing, Coating Removal, Surface Treatment End User: Aerospace Industry, Healthcare Sector, Manufacturing Industry, Energy Sector |
| Companies Covered | Bodycote, Kennametal Stellite, Saint-Gobain, Sandvik AB, The Lincoln Electric Company, OC Oerlikon Management AG, Hoganas AB, APS Materials, Linde Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Thermal Spray Market Shifts & Advancements
Cold spray deposition is absorbing investment flows previously directed toward conventional thermal processes, while regulatory chemistry restrictions and buyer consolidation reshape competitive requirements across coating service tiers.
Cold spray technology deposits solid metal powders at supersonic velocities without melting, preserving substrate microstructure in aerospace-grade nickel and titanium alloys. Rolls-Royce and Safran supply chain partners in Germany and France expand adoption for turbine blade leading-edge restoration. The technology is absorbing market share from laser cladding in thin-film dimensional restoration applications where heat-affected zones must be minimized.
REACH authorization requirements for chromium trioxide and strontium chromate corrosion inhibitors compel coating formulators to validate trivalent chromium and rare-earth alternatives. ECHA sunset date enforcement creates compliance cliffs for surface treatment shops dependent on legacy chemistry. Automotive and aerospace finishing operations in Baden-Württemberg and Bavaria accelerate qualification of compliant thermal spray substitutes ahead of authorization withdrawal deadlines.
Consolidated procurement by tier-one aerospace and power generation OEMs compresses supplier bases and extends contract durations. Buyers now mandate integrated coating-to-finishing capabilities and predictive maintenance data feeds alongside deposition services. This concentration is most visible in Germany's industrial corridor, where Siemens Energy and MTU Aero Engines reduce qualified coating vendor lists from dozens to single-digit preferred partnerships.
Europe Thermal Spray Market Segmentation
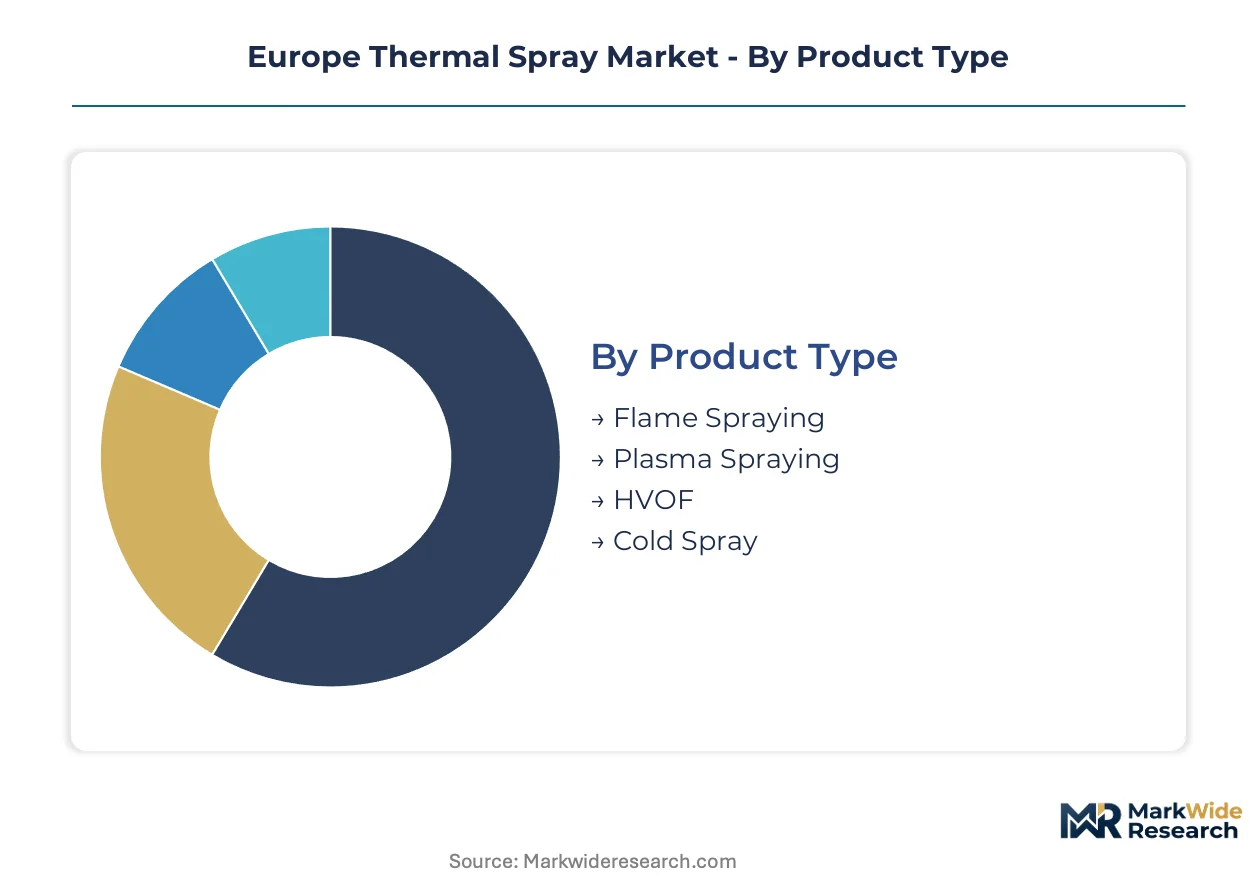
Segmentation in the Europe Thermal Spray Market reveals how coating specifications, regulatory compliance tiers, and end-use performance requirements stratify demand across distinct technology and application clusters. Understanding these divisions exposes where margin pools concentrate and where standardization pressures commoditize service offerings.
Product Type:
Temperature thresholds and particle velocity ranges differentiate deposition technologies, with each process occupying a distinct position on the coating density-porosity spectrum.
- Plasma Spraying:Electric arc ionizes inert gas streams to generate temperatures exceeding 15,000°C, enabling deposition of refractory ceramics like yttria-stabilized zirconia for gas turbine thermal barrier coatings. Demand concentrates in Germany's aerospace corridor where Rolls-Royce Deutschland and MTU Aero Engines mandate plasma-sprayed ceramic insulation for high-pressure turbine blades operating above 1,200°C metal temperatures.
- Cold Spray:Solid-state deposition accelerates metal powders through convergent-divergent nozzles at supersonic velocities without melting, preserving substrate microstructure in temperature-sensitive nickel superalloys. Adoption is accelerating across French and German repair stations for turbine blade leading-edge restoration where heat-affected zones from conventional thermal processes would compromise fatigue life.
- HVOF:Combustion of oxygen-fuel mixtures propels carbide and metal powders at velocities above 700 m/s, producing dense, low-porosity coatings for wear resistance. Automotive powertrain reconditioning in Baden-Württemberg drives volume demand for transmission component refurbishment.
- Flame Spraying:Lower-velocity combustion deposition suits cost-sensitive industrial repair applications where coating density requirements are less stringent. General machinery maintenance across Poland and Czech Republic industrial zones sustains deployment.
Mature deployment sits with HVOF for automotive and general industrial repair. Newer deployment is concentrated in Cold Spray for aerospace component restoration where substrate integrity preservation commands premium pricing.
Application:
End-use performance specifications and certification burdens fragment demand across sectors with divergent tolerance for coating variability and traceability requirements.
- Aerospace Components:Thermal barrier coatings, abradable seals, and wear-resistant surfaces on turbine blades, combustion chambers, and landing gear components demand aerospace-grade process control and full batch documentation. German and French OEM supply chains enforce Nadcap accreditation and AS9100 quality system compliance.
- Medical Devices:Hydroxyapatite and porous titanium coatings on orthopedic implants and dental prostheses require CE marking under MDR with batch-level traceability. Saint-Gobain and specialized coating houses in Switzerland and Germany dominate this high-margin segment where biocompatibility validation extends qualification timelines.
- Automotive Parts:Engine blocks, transmission gears, and piston rings receive HVOF carbide coatings for wear resistance and dimensional restoration. Central European automotive manufacturing clusters in Czech Republic and Slovakia drive localized service demand.
- Industrial Equipment:Pumps, valves, and paper mill rollers receive corrosion-resistant and wear coatings where specification tolerance is wider and price sensitivity higher. General engineering workshops across Northern Italy and Spain serve this volume segment.
Margin concentration aligns with Aerospace Components due to qualification barriers and long-term supply agreements. Volume concentration rests with Industrial Equipment where coating service standardization intensifies price competition.
Technology:
Process capability breadth spans deposition, material addition, and surface preparation functions, with technology selection determining addressable application scope.
- Thermal Spray Coating:Core deposition processes including flame, plasma, HVOF, and cold spray variants constitute the revenue foundation for European coating service providers. Equipment manufacturers in Germany and Switzerland supply integrated spray cells with automated parameter control.
- Additive Manufacturing:Cold spray deposition extends into near-net-shape component fabrication and repair, particularly for aerospace alloy structures where powder bed fusion thermal cycles would induce distortion. Research consortia in France and Germany advance qualification protocols for flight-critical repairs.
- Coating Removal:Controlled stripping of degraded thermal barrier coatings from turbine components enables substrate reuse and re-coating. Specialized facilities in the UK and Germany serve engine overhaul shops with chemical and mechanical removal processes.
- Surface Treatment:Pre-spray grit blasting, masking, and post-spray finishing operations integrate into full-service coating workflows. Automation of these ancillary processes distinguishes tier-one suppliers from commodity applicators.
Revenue concentration remains with Thermal Spray Coating as the primary value driver. Capability expansion is accelerating in Additive Manufacturing as cold spray technology matures beyond traditional coating boundaries.
End User:
Buyer consolidation and procurement centralization across end-use sectors reshape competitive requirements and contract structures for coating service providers.
- Aerospace Industry:Rolls-Royce, Safran, and MTU Aero Engines enforce stringent supplier qualification with reduced vendor lists and multi-year coating service agreements. Nadcap special process accreditation and EASA Part 145 repair station certification create entry barriers.
- Healthcare Sector:Orthopedic implant manufacturers and dental device producers demand CE-marked coatings with full material traceability under MDR. Notified body capacity constraints extend conformity assessment timelines.
- Manufacturing Industry:Automotive OEMs and general machinery producers seek localized HVOF capacity for production-line component reconditioning. Procurement emphasizes turnaround time and logistics integration over technical differentiation.
- Energy Sector:Siemens Energy and renewable turbine operators require erosion-resistant coatings for gas turbine hot gas path components and wind turbine blade leading-edge protection. Offshore wind installations in the North Sea generate emerging demand for ceramic erosion coatings.
Procurement sophistication peaks in the Aerospace Industry where technical qualification and predictive quality assurance dominate supplier selection. Growth momentum is strongest in the Energy Sector as renewable installations expand coating addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bavaria-Baden-Württemberg industrial corridor anchors European thermal spray activity, with Stuttgart and Munich hosting concentrated aerospace and automotive coating infrastructure that processes the majority of regional HVOF and plasma spray contracts.
Germany
Rolls-Royce Deutschland and MTU Aero Engines drive demand for thermal barrier coatings on high-pressure turbine blades. REACH authorization deadlines for hexavalent chromium compounds accelerate substitution toward tungsten carbide HVOF alternatives. The Stuttgart industrial zone concentrates automated spray cell deployments serving powertrain reconditioning for Mercedes-Benz and Porsche supply chains.
France
Safran Aircraft Engines mandates cold spray restoration for turbine blade leading-edge repair on LEAP and CFM56 powerplants. EMA oversight of medical device coatings under MDR extends qualification timelines for hydroxyapatite implant applications. The Toulouse-Blagnac aerospace cluster hosts specialized facilities serving Airbus and Safran repair stations with Nadcap-accredited processes.
United Kingdom
Rolls-Royce plc enforces reduced vendor lists for thermal spray services across Derby and Bristol manufacturing sites. The UK Environment Agency enforces REACH compliance timelines parallel to ECHA sunset dates for chromate corrosion inhibitors. The East Midlands aerospace corridor maintains coating removal and re-coating capacity for engine overhaul operations.
Poland
Volkswagen Group and Stellantis manufacturing plants generate localized demand for transmission component HVOF reconditioning. EU cohesion fund investments support industrial modernization including thermal spray capability expansion. The Silesian automotive cluster around Katowice and Bielsko-Biała attracts coating service providers seeking proximity to powertrain assembly lines.
Switzerland
Swissmedic regulation of orthopedic implant coatings creates premium market segmentation for batch-traceable ceramic deposition. Precision manufacturing traditions support medical device coating houses serving Zimmer Biomet and Straumann supply chains. The Solothurn-Aargau medtech corridor concentrates CE-marked coating operations for dental and spinal implant applications.
Europe Thermal Spray Market Competitive Landscape
Capital-heavy coating service providers compete with asset-light feedstock specialists across differentiated technology tiers. The market structure consolidates around multi-facility networks capable of Nadcap aerospace accreditation and single-site commodity applicators serving industrial repair segments. Three archetypes dominate: integrated coating-to-finishing houses, captive powder producers with proprietary parameter sets, and specialized medical coating boutiques. Competitive moves concentrate on geographic expansion into Central European automotive corridors and automated cell deployment for production-line integration.
Among UK-based coating service networks, Bodycote exemplifies the integrated multi-facility archetype spanning aerospace and industrial segments. Kennametal Stellite anchors the captive feedstock producer tier through in-house tungsten carbide powder production. Saint-Gobain occupies the high-purity ceramic specialist position serving medical and aerospace thermal barrier applications. These three represent distinct strategic postures rather than direct substitutes, with each embedding in different buyer supply chain tiers.
| Leading Market Players |
|---|
| Bodycote |
| Kennametal Stellite |
| Saint-Gobain |
| Sandvik AB |
| The Lincoln Electric Company |
| OC Oerlikon Management AG |
| Hoganas AB |
| APS Materials |
| Linde Plc |
| Others |
Supply & Pricing Matrix
Aerospace-grade certification tiers versus commodity industrial repair create divergent margin architectures across European thermal spray services. Nadcap-accredited coating houses serving Rolls-Royce and Safran command throughput-based contracts tied to turbine uptime guarantees, while Baden-Württemberg automotive reconditioning shops compete on per-component turnaround pricing with minimal certification overhead. This bifurcation concentrates pricing power upstream with powder producers and captive feedstock operations, while distribution economics favor regional hub consolidation around Stuttgart, Toulouse-Blagnac, and the East Midlands aerospace corridor.
Pricing Analysis
Throughput-linked contracts for aerospace thermal barrier coatings anchor value-based pricing to turbine availability metrics rather than deposition volume. Three-tier pricing structure across premium, standard, and economy levels separates Nadcap-specialist plasma spray cells from automated HVOF production lines and manual flame spray job shops. Pricing pressure stems from REACH authorization delays extending new material qualification timelines and compressing first-mover premiums. Medical device coating applicators exhibit lowest price sensitivity due to MDR-mandated batch traceability requirements that lock in qualified supplier relationships.
Supply Chain Analysis
Regional distribution centers in Germany, Austria, and the Czech Republic manage tungsten carbide and ceramic powder inventories on hub-and-spoke patterns serving coating service clusters. Feedstock sourcing draws from Central European powder metallurgy specialists and Swiss ceramic producers, with yttria-stabilized zirconia and cobalt-chrome alloys constituting critical input categories. Single-source vulnerability concentrates in ECHA-authorized chromium compound alternatives where qualification timelines exceed commercialization windows. Distribution runs through integrated coating-to-finishing houses that bundle powder supply, deposition, and post-processing under consolidated procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European thermal spray markets are consolidating around vertical-integration races where powder production capabilities determine margin capture. Players are pursuing backward integration into captive tungsten carbide and ceramic feedstock supply to defend pricing power against ECHA authorization volatility.
For Market Incumbents: Anchor market position through Nadcap accreditation expansion into cold spray parameter sets for turbine blade restoration, while securing long-term powder supply agreements with Central European metallurgy specialists. Cold spray technology maturation threatens HVOF market share in thin-film aerospace applications, demanding R&D investment in solid-state deposition automation. Capacity addition in Poland's Silesian automotive corridor captures localized powertrain reconditioning demand from Volkswagen Group and Stellantis assembly lines. For New Entrants and Emerging Players: Tier-two automotive suppliers in the Czech Republic and Slovakia represent the most penetrable entry point, with HVOF reconditioning capacity for transmission components offering lower certification barriers than aerospace segments. Wind turbine blade leading-edge protection systems in the North Sea and Baltic regions present white-space demand for erosion-resistant ceramic coatings where established aerospace players have limited presence. Equipment leasing partnerships with German spray cell manufacturers reduce upfront capital requirements for automated cell deployment. For Investors and Strategic Acquirers: Re-rating potential sits with medical coating boutiques possessing CE-marked hydroxyapatite deposition capabilities given MDR compliance timelines extending qualification moats. Long-term viability favors specialists with batch-traceable ceramic feedstock integration and notified body relationships that compress conformity assessment periods. Signal to watch is ECHA sunset date enforcement for chromate corrosion inhibitors, which will accelerate substitution demand and expand addressable market for compliant thermal spray alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Spray Parameter Qualification | Rolls-Royce and Safran supply chain accreditation opens turbine restoration contract pipelines. |
| Captive Tungsten Carbide Production | Kennametal Stellite's powder metallurgy integration demonstrates margin defense against feedstock volatility. |
| MDR Batch Traceability Investment | Saint-Gobain's ceramic purity protocols secure orthopedic implant coating premiums under Swissmedic oversight. |
| Central European Hub Expansion | Poland and Czech Republic automotive corridors localize HVOF capacity for powertrain reconditioning demand. |
| EU AI Act Process Documentation | Automated spray parameter logging creates aerospace supplier qualification pathways under algorithmic oversight frameworks. |
Research Methodology
Multi-period observation of ECHA authorization timelines, REACH compliance transitions, and cold spray adoption curves anchored the trend analysis, supplemented by interviews with coating service operations directors, powder metallurgy procurement leads, aerospace quality assurance managers, and medical device regulatory affairs specialists. Secondary validation incorporated ECHA substance restriction databases, EU F-Gas Regulation implementation reports, Nadcap special process audit records, and MDR notified body capacity disclosures. Bottom-up coating service revenue estimates triangulated against top-down aerospace and automotive production forecasts.
Input-output matrices modeled deposition technology penetration across application segments, with segmentation dimensions spanning process type, end-use performance tier, certification requirement level, and regional production cluster. CAGRs were derived from technology substitution curves and regulatory-driven chrome plating displacement rates. Industry-specific forecast inputs included turbine engine overhaul cycle frequencies and automotive powertrain component reconditioning volumes across Central European manufacturing hubs.
Caveats apply where ECHA authorization delays, REACH substance sunset date enforcement shifts, or cold spray qualification protocol changes could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology adoption elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Laser Cladding Service Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
E-Coat Market
Coatings
Corrosion Protection Coating Market
Coatings
Fire Retardant Coatings Market
Coatings
Global Coil Coatings Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Heavy Duty Glass Coating Market
Coatings
Acrylic Surface Coating Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Global Conformal Coatings Market
Coatings
Yacht Coatings Market
Coatings
Acrylic Coating Market
Coatings
Can Coatings Market
Coatings
Anti-Microbial Coatings Market
Coatings
Fillers and Coating Market