
 Bitumen Waterproofing Membrane Market | 2026-2036
Bitumen Waterproofing Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Bitumen Waterproofing Membrane Market Insights
The bitumen waterproofing membrane industry is pivoting on a widening split between specification-grade polymer-modified systems and commodity-grade APP-modified rolls used in cost-driven residential roofing. Sika AG leverages its European formulation expertise to sustain premium positioning in SBS-modified membranes for green roof assemblies. GAF Materials LLC anchors its North American presence through vertical integration into asphalt sourcing and contractor certification programs. BMI Group competes across Middle Eastern infrastructure tenders where hot-applied torch methods dominate tunnel and bridge specifications despite labor safety constraints.
Bitumen waterproofing membranes are multi-layer sheet materials manufactured from oxidized asphalt or polymer-modified bitumen compounds reinforced with polyester or fiberglass carriers, designed to create impermeable barriers against hydrostatic pressure and vapor transmission in building envelopes. SBS-modified variants deliver elastomeric performance across freeze-thaw cycles, while self-adhesive applied systems eliminate open-flame installation risks in confined basement and tunnel environments. Among application segments, green roofs command premium pricing due to root-resistance certification requirements and extended membrane lifespans, whereas parking decks represent a volume-driven segment where liquid-applied detailing compounds supplement sheet membrane primary barriers. Installation method selection increasingly tracks regulatory restrictions on torch-applied systems in urban cores with dense utility infrastructure.
The US EPA regulates volatile organic compound emissions from hot-applied bitumen through National Emission Standards for Hazardous Air Pollutants, while the EU F-Gas Regulation and REACH framework constrain solvent-based primer formulations and flame-retardant additives across European supply chains. India's BIS mandates IS 13262 certification for polymer-modified bitumen membranes in public infrastructure, creating compliance barriers for uncertified imports in state-level highway and metro projects. Stakeholders must monitor diverging regional fire-safety codes and polymer feedstock cost volatility as specification standards tighten for below-grade and transportation infrastructure applications.
Market Dynamics
Polymer-modified bitumen formulations are bifurcating the market into specification-grade systems for green roofs and commodity-grade APP-modified rolls for cost-sensitive residential roofing, with regulatory pressure on volatile organic compound emissions accelerating this split.
Growth Catalysts
- Green building mandates:Germany's evolving green building codes and REACH compliance thresholds are tightening specifications for low-emission installation methods across commercial roofing projects.
- Infrastructure corridors:India's western states are concentrating demand through Mumbai-Pune industrial corridor spending on basement and tunnel waterproofing contracts.
- Polymer SBS technology:Elastomeric performance across freeze-thaw cycles is expanding specification in North American warehouse and logistics park developments.
Market Restraints
- Crude-derived input volatility:Oxidized asphalt and styrene-butadiene-styrene polymer feedstock costs fluctuate with petrochemical pricing, compressing margins on fixed-price infrastructure tenders.
- Torch-applied regulatory friction:US EPA National Emission Standards for Hazardous Air Pollutants and EU F-Gas Regulation are constraining hot-applied installation methods in dense urban cores with utility infrastructure congestion.
- Liquid-applied membrane substitution:Cold-applied polyurethane and polyurea systems are capturing detailing work on complex geometries where sheet membrane seaming creates vulnerability.
Strategic Opportunities
- Self-adhesive system penetration:Flame-free installation technology eliminates open-flame risks in confined basement and tunnel environments, opening specification in safety-restricted urban projects.
- Root-resistance certification:Green roof assemblies command premium positioning through extended membrane lifespans and specialized performance testing requirements.
- India BIS compliance pathways:IS 13262 certification mandates for polymer-modified bitumen membranes in public infrastructure create barriers for uncertified imports, favoring localized supply chain investment.
Industry Challenges
- Skilled torch-applied labor scarcity:Hot-applied installation requires certified technicians with confined-space safety training, creating bottlenecks as regulatory restrictions expand.
- Multi-certification timeline compression:Manufacturers must simultaneously navigate REACH substance restrictions, BIS mark requirements, and regional fire-safety codes for below-grade specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitumen Waterproofing Membrane Market |
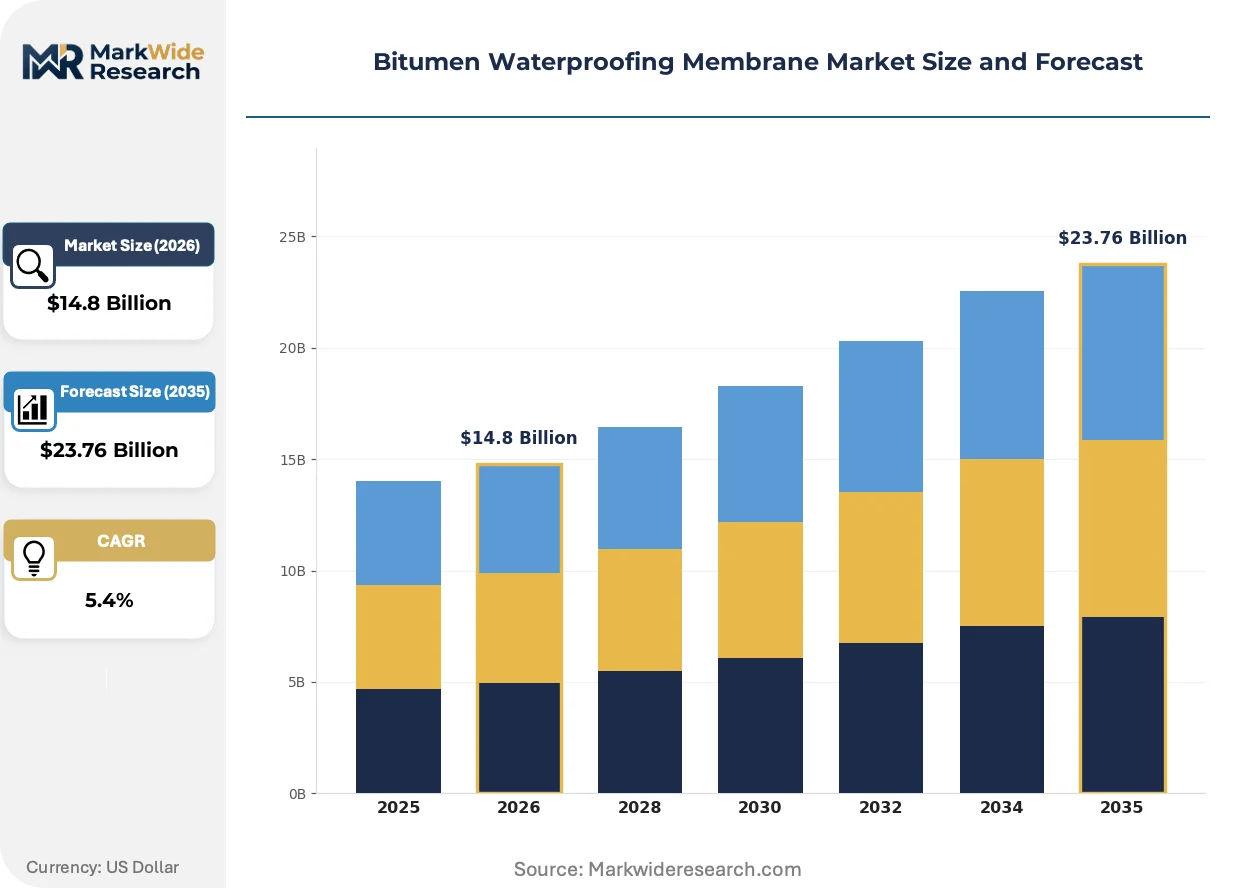
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SBS Modified, APP Modified, Coal Tar, Self-Adhesive, Polymer Modified Application: Roofs, Basements, Tunnels, Bridges, Parking Decks, Green Roofs Installation Method: Hot Applied, Cold Applied, Torch Applied, Self-Adhesive Applied, Liquid Applied End User Industry: Construction Companies, Infrastructure Developers, Real Estate Firms, Civil Engineering Contractors |
| Companies Covered | Sika AG, SOPREMA Group, GAF Materials LLC, BMI Group, IKO PLC, Johns Manville, Carlisle Companies, Tremco Incorporated, Standard Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitumen Waterproofing Membrane Market Trends and Innovations
Installation method selection is decoupling from performance specifications as regulatory restrictions and safety protocols reshape contractor procurement behavior across commercial and infrastructure segments.
Self-adhesive cold-applied membrane technology is consolidating market share in below-grade and confined-space applications. Tunnel and basement contractors in Germany and India are specifying these systems to eliminate open-flame ignition risks near utility infrastructure. This consolidation is compressing demand for traditional torch-applied methods in urban cores where fire-safety codes have tightened.
REACH and the EU F-Gas Regulation are constraining solvent-based primer formulations and flame-retardant additive chemistries across European supply chains. Manufacturers are reformulating bitumen compounds to maintain adhesion performance without restricted substances. Green roof and parking deck specifications in Germany are absorbing these compliance costs through premium positioning.
Certification-driven procurement is rotating demand toward BIS-marked and EPA-compliant membrane systems in public infrastructure. State-level highway and metro authorities in India and municipal procurement offices in the US are embedding compliance documentation into tender requirements. This pattern concentrates specification power among vertically integrated manufacturers with captive testing and certification capabilities.
Bitumen Waterproofing Membrane Market Segmentation
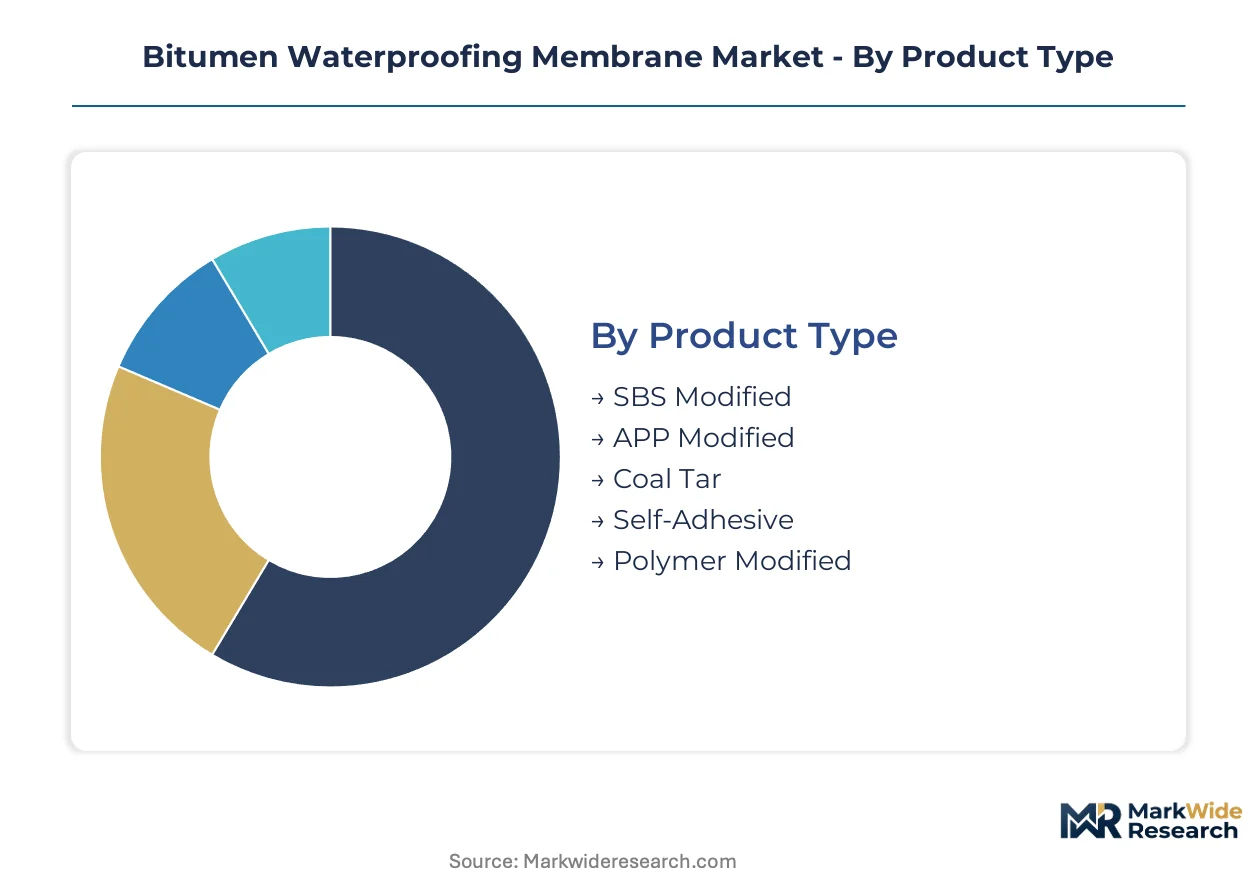
Segmentation in bitumen waterproofing membranes tracks divergent specification pathways between standalone commodity rolls and integrated system solutions. Product chemistry, installation risk profiles, and end-user procurement sophistication create distinct competitive arenas with margin structures that rarely overlap.
Product Type:
Integration depth varies sharply across chemistries, with some formulations functioning as standalone barriers while others require complementary detailing compounds to achieve system integrity.
- SBS Modified:Styrene-butadiene-styrene elastomeric formulations deliver superior low-temperature flexibility and fatigue resistance across freeze-thaw cycling. Demand concentrates in German green roof specifications and North American logistics park roofing where dimensional stability under thermal stress is non-negotiable.
- APP Modified:Atactic polypropylene plastomeric compounds dominate cost-sensitive residential re-roofing through high-temperature flow resistance and simpler torch-applied handling. Volumes cluster in Indian western state housing developments and US Sun Belt residential construction where first-cost procurement governs contractor selection.
- Coal Tar:Traditional pitch-based membranes retain specification in select below-grade applications requiring exceptional chemical resistance to hydrocarbon exposure.
- Self-Adhesive:Pressure-sensitive adhesive layers eliminate open-flame installation, capturing specification in confined urban basements and tunnel segments where fire safety protocols restrict torch methods.
- Polymer Modified:Advanced multi-polymer blends targeting premium infrastructure tenders with extended service life guarantees and root-resistance certification for vegetated assemblies.
APP Modified leads volumes today; Self-Adhesive is gaining share fastest.
Application:
Cost tier stratification separates specification-grade assemblies with certification burdens from commodity applications where material cost dominates procurement calculus.
- Roofs:The volume foundation of commercial and residential waterproofing, spanning flat built-up systems to pitched underlayment. Indian infrastructure corridors and North American warehouse developments drive specification differentiation between commodity APP and premium SBS systems.
- Basements:Below-grade hydrostatic pressure applications demand seamless integration with drainage composites and soil-gas barriers. Mumbai-Pune industrial corridor spending accelerates contract awards for multi-layer systems with self-adhesive installation.
- Tunnels:Confined-space waterproofing with stringent fire-resistance and chemical exposure requirements. German regulatory pressure on torch-applied methods rotates demand toward cold-applied alternatives.
- Bridges:Expansion joint detailing and deck waterproofing with dynamic load considerations. Public infrastructure tenders embed BIS and EPA compliance documentation into award criteria.
- Parking Decks:Traffic-bearing membrane systems with wear-course integration. Volume-driven segment where liquid-applied detailing supplements sheet membrane primary barriers on complex geometries.
- Green Roofs:Vegetated assemblies requiring root-puncture resistance and extended durability certification. German REACH compliance and green building codes absorb premium positioning through specialized testing requirements.
Roofs command absolute volume; Green Roofs carry the steepest expansion trajectory.
Installation Method:
Application context and regulatory geography dictate method selection more than performance specifications, decoupling technical merit from procurement behavior.
- Hot Applied:Molten bitumen kettle application for built-up roofing systems with established contractor familiarity. US EPA National Emission Standards constrain specification in dense urban cores.
- Cold Applied:Solvent-based or water-based adhesive systems eliminating open-flame risks. REACH and EU F-Gas Regulation drive reformulation away from restricted solvent carriers.
- Torch Applied:Propane-fired heating of membrane underside for seam welding and adhesion. Regulatory friction accumulates across German urban construction and Indian safety-conscious infrastructure authorities.
- Self-Adhesive Applied:Peel-and-stick membrane installation with factory-applied adhesive layers. Expanding fastest in tunnel and basement segments where confined-space fire protocols dominate.
- Liquid Applied:Cold-fluid membrane systems for complex detailing and irregular substrates. Capturing share on parking deck geometries where sheet seaming creates vulnerability points.
Torch Applied retains installed base dominance; Self-Adhesive Applied climbs the fastest.
End User Industry:
Customer type determines procurement sophistication, with infrastructure developers embedding multi-certification requirements while residential contractors prioritize material cost and installation speed.
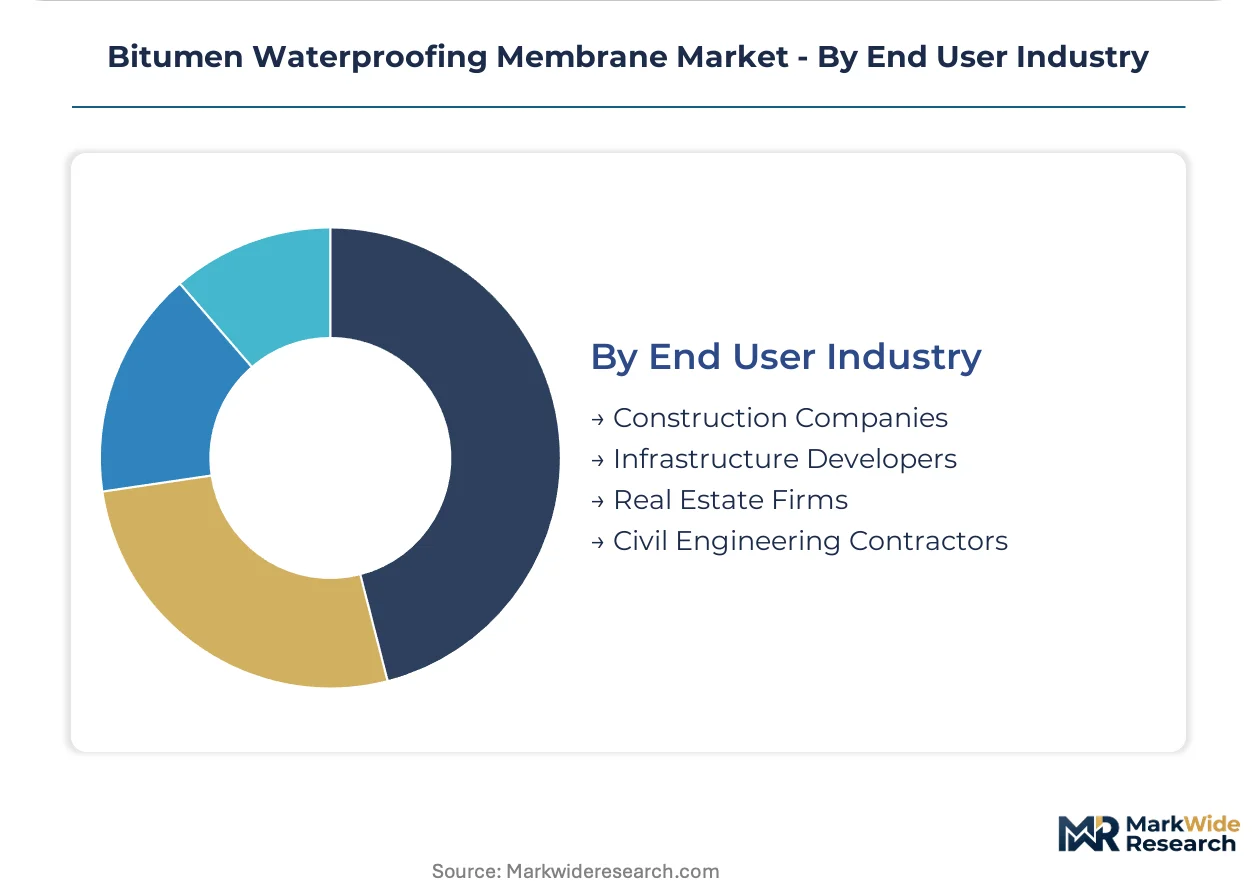
- Construction Companies:General building contractors with project-specific specification authority. Procurement patterns bifurcate between green building mandate compliance and first-cost minimization.
- Infrastructure Developers:State-level highway authorities, metro corporations, and industrial corridor agencies. Indian BIS IS 13262 mandates and US EPA documentation requirements concentrate specification power among certified suppliers.
- Real Estate Firms:Commercial and residential property developers with portfolio-scale procurement. German green building codes and REACH thresholds filter supplier qualification.
- Civil Engineering Contractors:Specialized tunnel, bridge, and marine structure builders. Safety protocols and confined-space regulations rotate method selection toward flame-free alternatives.
Construction Companies anchor current volumes; Infrastructure Developers are expanding procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's REACH compliance frameworks and green building codes absorb premium positioning costs for polymer-modified systems, while India's BIS certification mandates concentrate specification power among domestic supply chains for Mumbai-Pune corridor infrastructure.
United States
Commercial roofing contractors across warehouse and logistics park developments in Texas and Georgia specify SBS-modified membranes for thermal cycling performance. EPA National Emission Standards for Hazardous Air Pollutants constrain torch-applied installation methods in dense urban cores with utility infrastructure congestion. Chicago and New York metropolitan procurement offices embed compliance documentation into municipal tender requirements.
Germany
Evolving green building codes and REACH volatile organic compound thresholds tighten specifications for low-emission installation methods across commercial roofing projects. ECHA substance restrictions drive reformulation of solvent-based primer formulations and flame-retardant additive chemistries. Frankfurt and Munich urban construction segments rotate demand toward self-adhesive cold-applied systems in confined basement environments.
India
Mumbai-Pune industrial corridor infrastructure spending accelerates basement and tunnel waterproofing contract awards across Maharashtra state. BIS mandates IS 13262 certification for polymer-modified bitumen membranes in public highway and metro projects, creating compliance barriers for uncertified imports. Western state housing developments in Gujarat and Karnataka cluster APP-modified roll demand for cost-sensitive residential re-roofing.
China
Dual carbon goals and GB standards for building energy efficiency expand specification-grade membrane demand in green roof assemblies across Yangtze River Delta commercial developments. MEE environmental compliance frameworks constrain manufacturing emissions from oxidized asphalt processing. Shanghai and Shenzhen municipal procurement embeds extended membrane lifespan requirements into public infrastructure tenders.
United Arab Emirates
MOHAP safety protocols and Dubai Municipality fire codes restrict torch-applied methods in high-density commercial districts with underground utility congestion. Specifiers in Abu Dhabi and Sharjah infrastructure tenders prioritize cold-applied and self-adhesive systems for tunnel and basement waterproofing. NEOM Northwest development contracts embed polymer-modified membrane specifications for below-grade hydrostatic pressure applications.
Bitumen Waterproofing Membrane Market Competitive Landscape
Top-tier vendors anchor specification-grade polymer-modified systems for green roof and infrastructure tenders, while mid-tier commodity producers compete on APP-modified roll volumes for cost-sensitive residential roofing. The vendor base stratifies across formulation expertise, captive asphalt sourcing, and multi-certification testing capabilities. Three archetypes dominate: European formulation specialists with REACH compliance depth, North American vertically integrated asphalt producers, and emerging Asian fabricators with BIS certification pathways. Competitive moves concentrate on backward integration into polymer feedstock supply and geographic expansion through localized testing facility investment.
Among European formulation specialists, Sika AG exemplifies premium-tier positioning through elastomeric SBS technology for green roof assemblies. SOPREMA Group occupies a parallel position with multi-polymer blend capabilities targeting extended service life guarantees. GAF Materials LLC anchors the North American vector through upstream control over asphalt sourcing and contractor certification program scale. BMI Group sits within the infrastructure-focused tier, competing across Middle Eastern tunnel and bridge tenders where hot-applied methods persist despite labor safety constraints.
| Leading Market Players |
|---|
| Sika AG |
| SOPREMA Group |
| GAF Materials LLC |
| BMI Group |
| IKO PLC |
| Johns Manville |
| Carlisle Companies |
| Tremco Incorporated |
| Standard Industries Inc. |
| Others |
Pricing and Supply Chain Analysis
German green building codes and REACH volatile organic compound thresholds are forcing specification shifts toward low-emission polymer-modified systems, compelling manufacturers to absorb reformulation costs while passing premium positioning downstream to certified installers and infrastructure developers.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for commodity-grade APP-modified rolls while polymer SBS formulations retain premium positioning through certification burdens. Three-tier pricing structure across premium, standard, and economy levels separates root-resistant green roof assemblies from warehouse roofing and residential re-roofing tiers. Cost compression in APP-modified segments is intensifying because of crude-derived asphalt volatility and fixed-price infrastructure tender competition. Residential contractors in India's western states exhibit highest price sensitivity; German infrastructure developers demonstrate lowest sensitivity due to mandated compliance documentation.
Supply Chain Analysis
Scrap membrane recovery and reprocessing flows remain underdeveloped across the bitumen waterproofing sector, though European manufacturers are piloting oxidized asphalt reclamation from demolition sites to offset virgin feedstock exposure. Manufacturing concentrates in Germany, China, and India, with polymer modification compounding anchored near petrochemical hubs in each geography. Production draws from styrene-butadiene-styrene polymer, oxidized asphalt, and polyester reinforcement carriers, with SBS feedstock costs tethered to benzene and butadiene pricing cycles. Single-source vulnerability sits with specialized root-resistance additive suppliers serving green roof certification pathways. Distribution runs through certified contractor networks and direct infrastructure tender channels rather than traditional wholesale building materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where evolving volatile organic compound thresholds and fire-safety codes continuously reprice specification-grade systems upward, with Germany's REACH framework serving as the dominant demand catalyst across European and export-oriented supply chains.
For Market Incumbents: Anticipate accelerated substitution pressure from cold-applied polyurethane and polyurea detailing systems by deepening backward integration into captive SBS polymer supply and expanding self-adhesive manufacturing capacity in India to capture BIS IS 13262-mandated infrastructure awards. Certification investment represents the critical lever for defending premium positioning as municipal procurement offices embed compliance documentation into tender requirements. For New Entrants and Emerging Players: Enter via India's western state industrial corridor basement and tunnel waterproofing contracts, where IS 13262 certification barriers favor localized production investment over import competition. The most penetrable white space sits with flame-free self-adhesive systems for confined urban basements in German metropolitan construction. A go-to-market angle anchored to contractor safety training partnerships unlocks specification access faster than price competition against established torch-applied incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier European formulation specialists possessing REACH compliance depth but lacking scale to compete for Indian infrastructure tenders. Long-term viability across the projection horizon favors manufacturers with vertically integrated asphalt sourcing and captive multi-certification testing capabilities. Acquisition targets should demonstrate established BIS mark pathways or EPA documentation infrastructure. The signal to watch is municipal procurement office adoption of extended membrane lifespan requirements into public infrastructure tender criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SBS Polymer Supply | Captive styrene-butadiene-styrene production insulates margin compression from petrochemical price volatility. |
| BIS IS 13262 Certification Investment | Indian public infrastructure mandates create compliance barriers favoring localized testing facility deployment. |
| Self-Adhesive Manufacturing Scale-Up | Flame-free systems capture specification in German urban basement and tunnel segments with fire-safety restrictions. |
| Green Roof Root-Resistance Certification | Specialized testing requirements absorb premium positioning through extended membrane lifespan guarantees. |
| Contractor Safety Training Partnerships | Certified installation networks concentrate procurement power away from commodity distributors toward system suppliers. |
Research Methodology
Coverage spans Germany, India, China, the United States, and the United Arab Emirates, with primary inputs from each geography combined through structured interviews with commercial roofing contractors, infrastructure procurement officers, polymer formulation chemists, and certified waterproofing installers, validated against secondary sources including EPA National Emission Standards documentation, ECHA REACH substance restriction registers, BIS certification databases, and customs trade data for bitumen membrane imports. Bottom-up project pipeline analysis and top-down construction spending allocation triangulate volume estimates.
Rate-of-change decomposition across the analysis window isolates polymer chemistry substitution effects, regulatory compliance cost absorption, and installation method shifts from underlying construction activity growth. Segmentation dimensions modeled include product chemistry tier, application environment, installation risk profile, and end-user procurement sophistication, with CAGRs derived from elasticity-adjusted construction spending forecasts and technology penetration curves. Industry-specific inputs incorporate green roof assembly specification rates and tunnel waterproofing contract award patterns.
Inputs from regulatory filing databases and certified contractor networks were available through the study window; gaps in real-time project-level pricing data introduce uncertainty bands around premium segment value estimates. Forecasts reflect assumptions regarding REACH substance restriction timelines and BIS enforcement consistency across Indian state-level authorities. Practitioners should monitor municipal procurement office adoption of extended membrane lifespan requirements and torch-applied method restriction expansions for early signals of specification-grade demand acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
SBS Modified Bitumen Membrane Market
Membrane Materials
Polysulfone Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
TPO Roofing Membrane Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Self-Adhered Roofing Membranes Market