
 Europe Powder Coatings Market | 2026-2036
Europe Powder Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Powder Coatings Market Insights
Germany's industrial heartland is tilting toward expanded powder coating capacity as automotive and appliance OEMs reshore finishing operations. BASF SE leverages its Ludwigshafen integrated chemical complex to captive-supply resin intermediates for polyester formulations. Akzo Nobel N.V. anchors its European powder position through dedicated plants in the Netherlands and Sweden, sustaining R&D intensity in low-cure chemistries. TIGER Coatings GmbH & Co. KG specializes in metallic effect powders, occupying a defensible niche among premium architectural and furniture accounts.
Powder coatings are thermoset or thermoplastic polymer systems applied as free-flowing dry powder and cured under heat to form a protective film, typically applied at 60–120 micrometres thickness via electrostatic spray or fluidised bed immersion. The technology eliminates solvent carriers, delivering near-zero VOC emissions for compliance-sensitive industries. Polyester formulations dominate volume in European architectural and general industrial applications due to exterior durability and cost efficiency. Epoxy systems retain strength in functional appliance and interior machinery segments where chemical resistance outweighs UV stability. Thermoset formulations command the broadest application base, while specialty powder blends capture margin pools in automotive under-hood and electrical insulation uses.
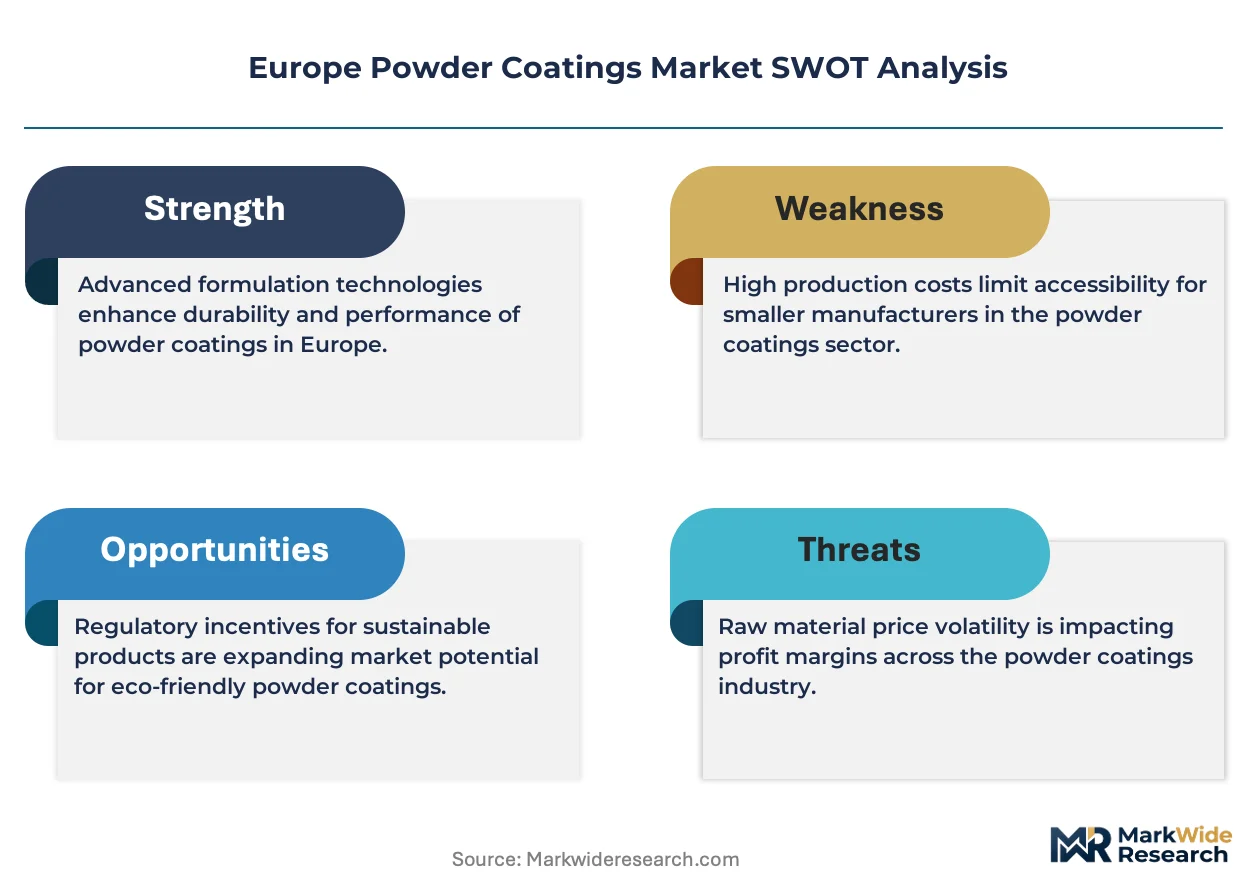
REACH restrictions on hazardous substances and the EU F-Gas Regulation on fluorinated gases are reshaping formulation chemistry, pushing manufacturers toward HAA-cured polyesters and TGIC-free alternatives. CE marking under the Construction Products Regulation governs architectural powder performance claims across member states, creating divergent testing burdens for pan-European suppliers. ECHA's SVHC candidate list expansion continues to restrict certain epoxy hardeners and pigment chemistries, forcing reformulation cycles. Stakeholders must monitor the interplay between the EU Green Deal's industrial decarbonisation targets and emerging national building energy codes, as these will determine whether low-bake and UV-curable powder technologies achieve specification scale.
Market Dynamics
The EU F-Gas Regulation and REACH compliance frameworks are systematically eliminating solvent-based finishing alternatives, redirecting specification flows toward zero-VOC powder systems across automotive and industrial verticals.
Growth Catalysts
- EV Battery Enclosure Demand:Automotive OEMs in Germany and France are expanding powder coating specifications for EV battery enclosures and chassis components, creating specification pull for high-durability polyester formulations.
- REACH-Driven Substitution:ECHA's SVHC candidate list expansion continues to restrict epoxy hardeners and pigment chemistries, forcing reformulation toward compliant powder alternatives.
- Industrial Corridor Retrofitting:Germany's appliance and machinery manufacturers are converting liquid coating lines to electrostatic spray processes, concentrating demand in the Rhine-Ruhr and Baden-Württemberg regions.
Market Restraints
- TGIC Supply Concentration:European production of triglycidyl isocyanurate crosslinkers concentrates among a limited supplier base, creating input cost volatility and reformulation pressure for architectural coating producers.
- Cure Temperature Limitations:Standard thermoset powders require 180–200°C substrate temperatures, excluding heat-sensitive substrates such as engineered plastics and pre-assembled components from application scope.
- Line Conversion Economics:Existing liquid coating infrastructure in Southern European metal fabrication carries high capital write-off costs, slowing adoption curves in Italy and Spain relative to Northern Europe.
Strategic Opportunities
- Low-Cure Technology Penetration:HAA-cured polyester systems enabling 140–160°C cure windows are opening specification access to MDF furniture and assembled electrical enclosures previously excluded from powder coating.
- UV-Curable Powder Expansion:Photoinitiated powder systems eliminate thermal cure requirements entirely, positioning suppliers to capture premium segments in heat-sensitive automotive interior trim and medical device housings.
- National Building Energy Codes:Emerging EU Green Deal implementation through national building energy performance standards is accelerating demand for low-bake architectural finishes that reduce process energy intensity.
Industry Challenges
- Electrostatic Application Expertise Gap:The shift from liquid to powder coating requires specialized technician training in Faraday cage management and film thickness control, creating workforce bottlenecks in Eastern European manufacturing clusters.
- CE Marking Divergence:The Construction Products Regulation creates divergent testing burdens across member states for architectural powder performance claims, extending certification timelines for pan-European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Powder Coatings Market |
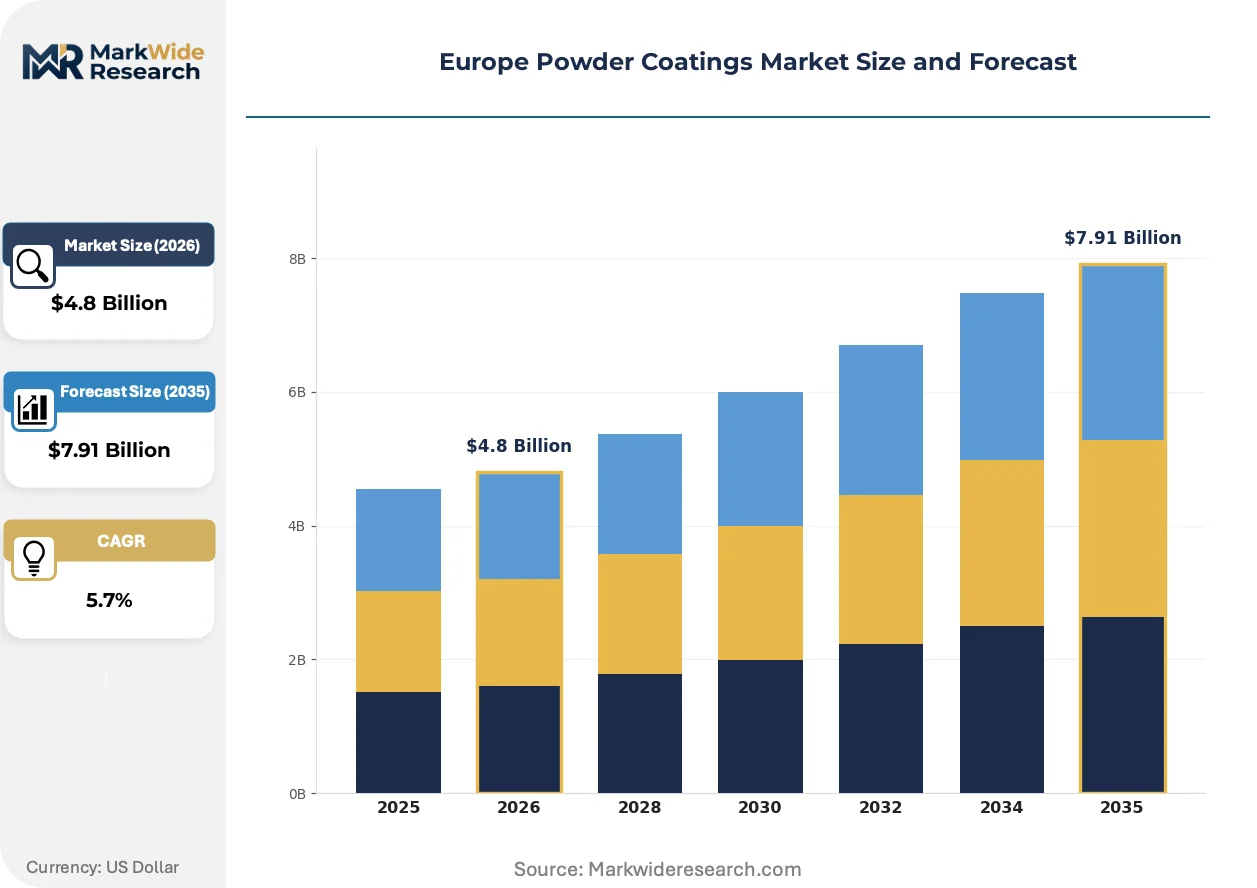
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyester, Acrylic, Hybrid Application: Automotive, Furniture, Appliances, General Industrial End User: Manufacturers, Contractors, Distributors, OEMs Formulation: Thermoset, Thermoplastic, Powder Blend, Specialty |
| Companies Covered | Jotun A/S, BASF SE, Akzo Nobel N.V., TIGER Coatings GmbH & Co. KG, Sika AG, PPG Industries, Inc., Axalta Coating Systems LLC, Teknos Group Oy, The Sherwin-Williams Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Powder Coatings Market Trends and Innovations
Formulation chemistry and application technology are converging to expand powder coating addressable markets beyond traditional metal substrates and high-temperature cure requirements.
Digital twin simulation of electrostatic spray patterns is digitizing coating line commissioning and process optimization. Automotive OEMs in Stuttgart and Munich are deploying virtual coating booths to reduce physical trial runs by sixty percent. The technology is digitizing quality assurance workflows and compressing new color introduction cycles from months to weeks.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon propellants is eliminating fluoropolymer liquid coating alternatives in architectural applications. Powder fluoropolymer formulations are capturing specification share in high-performance facade systems previously served by solvent-borne PVDF. Western European curtain wall manufacturers are accelerating qualification of FEVE-based powder alternatives to maintain project compliance.
Coating service procurement is consolidating toward integrated finishing partnerships rather than transactional powder supply. Major appliance manufacturers in Poland and Turkey are outsourcing entire coating operations to toll applicators with captive powder supply agreements. This model is most visible in white goods manufacturing, where OEMs prioritize capital efficiency over in-house finishing asset ownership.
Europe Powder Coatings Market Segmentation
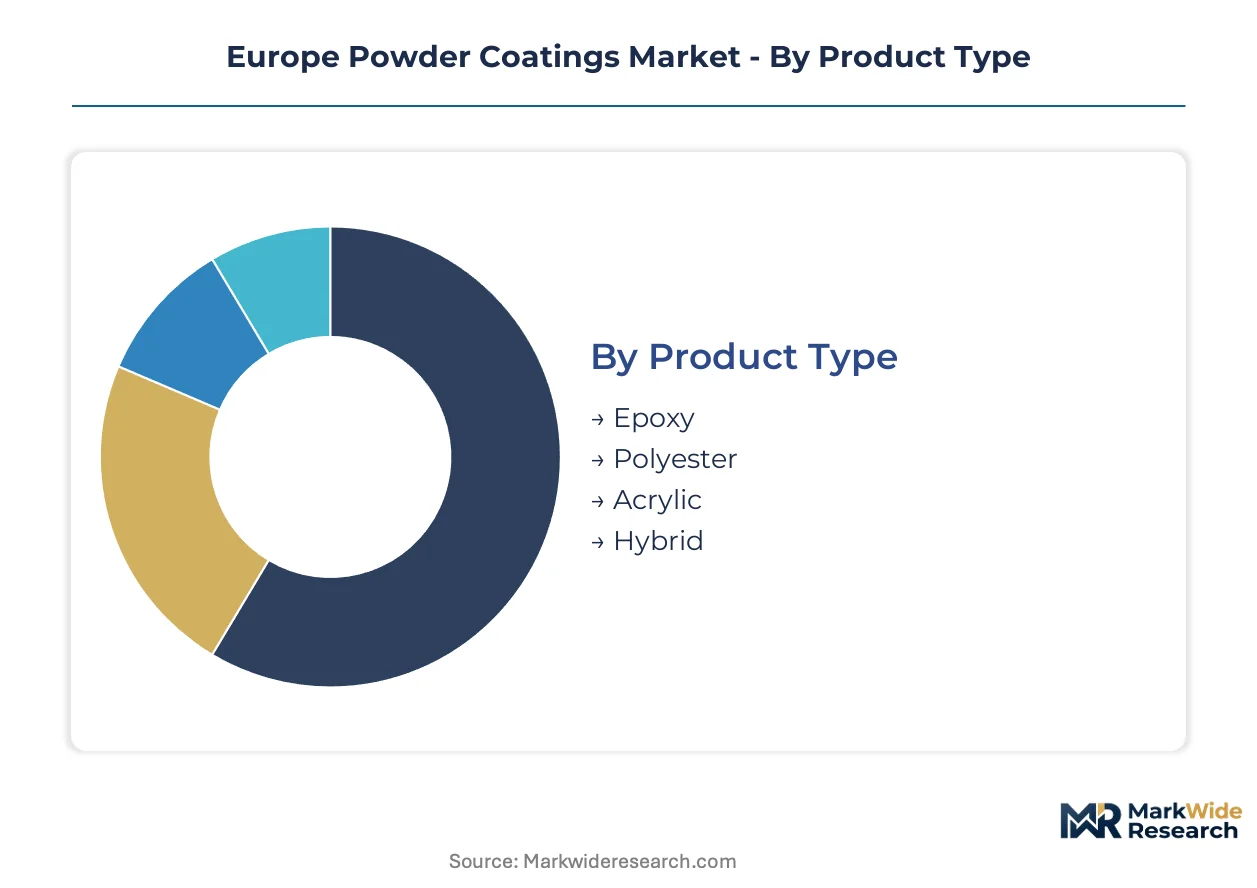
Segmentation in Europe powder coatings reveals how formulation chemistry, cure requirements, and end-use durability demands create distinct margin pools. Suppliers configure production assets and technical service teams around these boundaries.
Product Type:
Cost tier stratification separates commodity architectural formulations from premium functional systems serving chemical resistance specifications.
- Epoxy:Cross-linked with amine or phenolic hardeners, epoxy powders deliver superior chemical resistance and adhesion to metal substrates. Appliance manufacturers in Germany's industrial corridor specify these for washing machine drums and dishwasher racks where detergent exposure dominates. REACH restrictions on certain hardeners are forcing reformulation toward compliant alternatives.
- Polyester:Saturated polyester resins cured with TGIC or HAA crosslinkers dominate exterior architectural applications. Façade fabricators across France and the Netherlands favor these for UV stability and chalking resistance. The EU F-Gas Regulation is accelerating substitution for solvent-borne fluoropolymer alternatives in curtain wall systems.
- Acrylic:Acrylic formulations offer exceptional gloss retention and color stability for premium automotive and furniture segments.
- Hybrid:Epoxy-polyester hybrids balance cost and performance for general industrial metal finishing.
Polyester holds installed capacity. Acrylic is rotating up the share rankings.
Application:
Volume concentration varies dramatically by cure temperature compatibility and substrate heat tolerance across European manufacturing clusters.
- Automotive:EV battery enclosures and chassis components demand high-durability polyester systems with edge coverage and dielectric properties. Stuttgart and Munich OEMs are qualifying powder for under-hood applications previously reserved for liquid coatings. The shift requires low-cure formulations compatible with assembled component thermal limits.
- Appliances:White goods manufacturers in Poland and Turkey operate the highest-throughput powder lines in Europe, favoring epoxy and hybrid systems for interior cavities and exteriors respectively. Toll coating partnerships are consolidating finishing operations away from captive OEM assets.
- Furniture:MDF and engineered wood applications are expanding as HAA-cured low-bake polyesters open heat-sensitive substrates.
- General Industrial:Agricultural machinery and electrical enclosure fabricators across Northern Europe specify standard polyester and epoxy systems.
Appliances command volume leadership. Automotive is climbing the fastest on specification intensity.
End User:
Customer type determines procurement structure, with integrated manufacturers and outsourced toll applicators diverging on technical service requirements.
- Manufacturers:Captive finishing operations at major appliance and automotive OEMs demand just-in-time powder supply with color-matching laboratory support. BASF and Akzo Nobel maintain dedicated technical service teams at key accounts.
- OEMs:Automotive and machinery original equipment manufacturers specify powder performance standards while increasingly outsourcing application to qualified toll coaters.
- Contractors:Architectural metal fabricators and job shops purchase through distribution with emphasis on batch consistency and rapid color availability.
- Distributors:Pan-European distributors stock standard colors while managing custom formulation logistics for regional accounts.
Manufacturers retain specification authority. OEMs are rotating up the share rankings on outsourcing momentum.
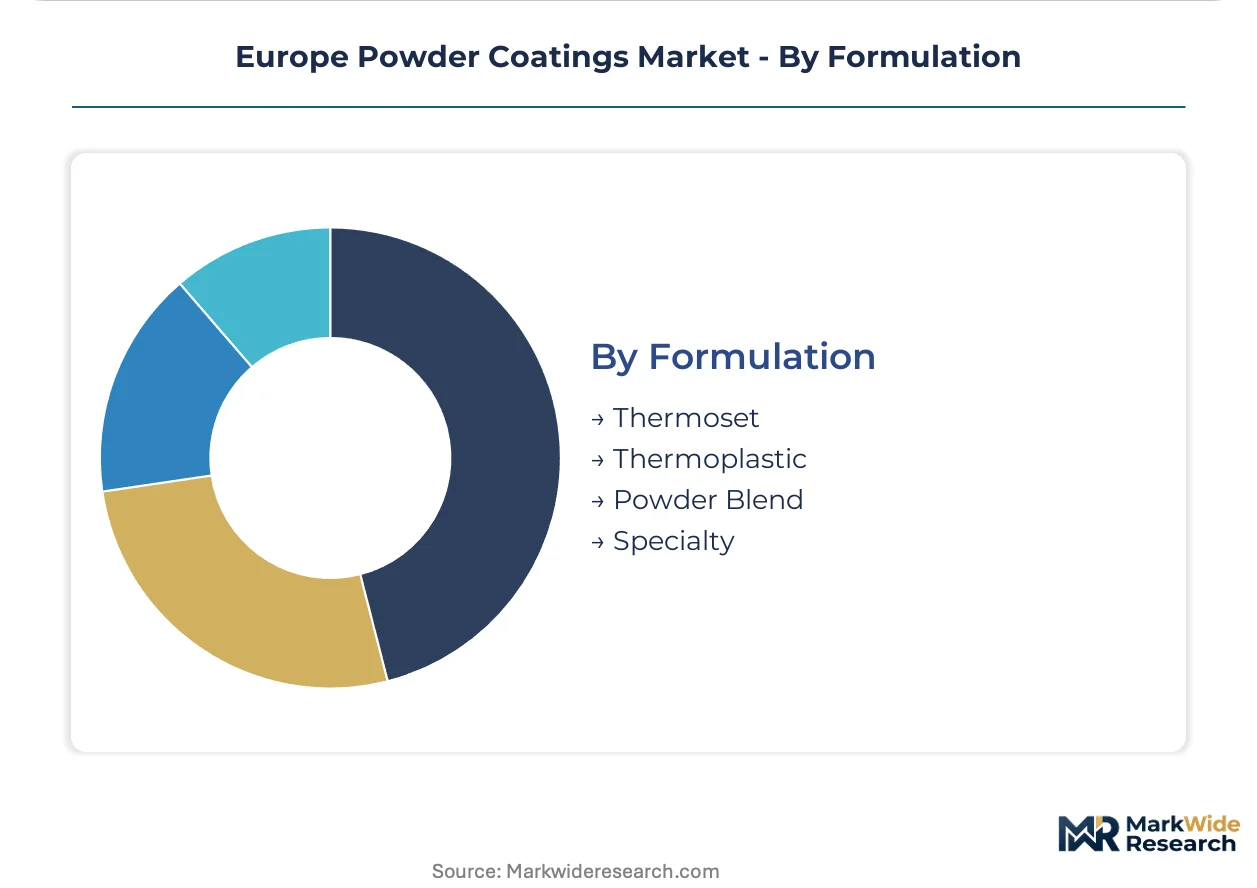
Formulation:
Supply concentration and margin structure diverge between commodity thermoset production and specialty blend capabilities.
- Thermoset:Cross-linked polyester, epoxy, and acrylic systems cure via heat-initiated chemical reaction, forming irreversible polymer networks. These command the broadest application base across European metal finishing.
- Thermoplastic:PVC and nylon-based powders melt and flow without chemical crosslinking, enabling rework and repair for functional applications.
- Powder Blend:Pre-mixed color and effect combinations streamline job shop operations.
- Specialty:Electrical insulation, antimicrobial, and low-friction formulations capture premium pricing in narrow verticals.
Thermoset holds installed capacity. Specialty is expanding most quickly on functional specification growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resin production clusters in Germany, the Netherlands, and Belgium supply formulation feedstock across the continent. Manufacturing capacity tilts toward Northern Europe, while Southern European adoption lags on line conversion economics.
Germany
Automotive OEMs in Stuttgart and Munich specify powder coatings for EV battery enclosures and chassis components. REACH compliance frameworks and the EU F-Gas Regulation eliminate solvent-based alternatives, redirecting demand toward zero-VOC systems. The Rhine-Ruhr and Baden-Württemberg industrial corridors concentrate appliance and machinery manufacturers retrofitting liquid lines to electrostatic spray processes.
France
Façade fabricators across the Paris region and Lyon metropolitan area favor polyester formulations for UV stability in architectural applications. The EU Green Deal's industrial decarbonisation targets accelerate specification of low-bake finishes. Curtain wall manufacturers in Île-de-France qualify FEVE-based powder alternatives to replace solvent-borne fluoropolymer systems.
Netherlands
Akzo Nobel anchors European powder operations through dedicated plants serving Benelux and export markets. CE marking under the Construction Products Regulation governs performance claims for architectural powders. The Rotterdam-Antwerp chemical cluster enables integrated resin supply chains for polyester formulation.
Italy
Metal fabrication infrastructure in Northern Italy carries high capital write-off costs, slowing powder adoption relative to Northern Europe. ECHA's SVHC candidate list restrictions force reformulation of epoxy hardeners used in appliance coatings. The Lombardy and Veneto regions maintain liquid coating dominance in furniture and general industrial segments.
Poland
White goods manufacturers operate the highest-throughput powder lines in Europe, favoring epoxy and hybrid systems. Toll coating partnerships consolidate finishing operations away from captive OEM assets. The country's manufacturing clusters supply appliance exports across the EU single market.
Europe Powder Coatings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin and crosslinker supply. The vendor base stratifies between integrated chemical conglomerates with captive raw material positions and focused coating formulators. Three archetypes dominate: diversified chemical majors with backward integration into resin intermediates, dedicated powder specialists with metallic effect capabilities, and toll applicators consolidating service procurement. Capacity expansion and low-cure technology licensing represent the dominant competitive vectors.
Among integrated chemical conglomerates, BASF SE exemplifies the captive-supply archetype through its Ludwigshafen complex. Akzo Nobel N.V. and TIGER Coatings GmbH & Co. KG occupy distinct positions—Akzo Nobel through dedicated European plants and R&D intensity, TIGER through specialization in metallic effect powders for premium architectural and furniture accounts. These three represent the competitive spectrum from commodity scale to niche margin capture.
| Leading Market Players |
|---|
| Jotun A/S |
| BASF SE |
| Akzo Nobel N.V. |
| TIGER Coatings GmbH & Co. KG |
| Sika AG |
| PPG Industries, Inc. |
| Axalta Coating Systems LLC |
| Teknos Group Oy |
| The Sherwin-Williams Company |
| Others |
Pricing and Supply Chain Analysis
The Ludwigshafen chemical complex anchors European resin supply, with BASF's captive production of polyester intermediates creating pricing leverage over downstream formulators dependent on spot resin markets. REACH compliance costs and TGIC crosslinker supply concentration in a limited supplier base amplify input cost volatility, compressing margins for architectural coating producers while integrated players defend position through backward control over critical feedstocks.
Pricing Analysis
REACH and the EU F-Gas Regulation dictate the pricing tier structure across the Europe powder coatings market, separating premium low-cure and UV-curable formulations from standard thermoset offerings. Pricing stratifies across premium, standard, and economy tiers based on certification grade under CE marking and volume scale of procurement. Cost compression in standard architectural polyester runs through TGIC supply bottlenecks and energy-intensive cure requirements. Toll coating partnerships exhibit the highest price sensitivity due to pass-through contract structures, while captive OEM operations absorb volatility through integrated supply agreements.
Supply Chain Analysis
Export-control restrictions on fluorinated gas technologies under the EU F-Gas Regulation limit flows of solvent-borne fluoropolymer alternatives, redirecting specification toward powder-based FEVE formulations. Resin production concentrates in Germany, the Netherlands, and Belgium, with polyester intermediates drawing from the Rotterdam-Antwerp chemical cluster. Raw material dependencies center on saturated polyester resins, TGIC and HAA crosslinkers, and specialized effect pigments. Single-source vulnerability in TGIC crosslinker supply creates structural risk for architectural producers. Distribution runs through pan-European distributors stocking standard colors alongside direct technical service relationships for major appliance and automotive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through toll coating consolidation in Poland and Turkey, where white goods manufacturers outsource entire finishing operations to qualified applicators with captive powder supply agreements. This procurement shift elevates volume leverage among fewer purchasing decision-makers.
For Market Incumbents: Build formulation-locked relationships as the defensive moat, embedding technical service teams at major automotive OEMs in Stuttgart and Munich to capture EV battery enclosure specifications. Deepen backward integration into HAA crosslinker production to offset TGIC supply volatility. Secure CE marking pre-qualification across multiple member states to compress certification timelines for pan-European architectural contracts. For New Entrants and Emerging Players: Pursue low-cure technology licensing as the primary penetration vector, targeting MDF furniture and assembled electrical enclosure segments previously excluded by thermal cure limitations. Southern European metal fabrication in Italy and Spain offers the most penetrable geography due to high liquid line conversion costs delaying incumbent powder adoption. Position through toll coating partnerships rather than direct powder supply to bypass established distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH and F-Gas phasedown create irreversible substitution tailwinds for zero-VOC powder systems. Acquisition targets should display specialty formulation capabilities in electrical insulation or antimicrobial powders, or toll coating assets with captive OEM relationships. Monitor national building energy code implementation across EU member states as the signal for low-bake technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Cure Technology Licensing | Opens MDF furniture and electrical enclosures to powder coating penetration. |
| Backward Integration into Crosslinkers | Defends margin position against TGIC supply concentration and price volatility. |
| Toll Coating Partnership Consolidation | Captures procurement shift among Polish and Turkish white goods manufacturers. |
| CE Marking Pre-Qualification Expansion | Reduces certification burden under Construction Products Regulation divergence. |
| UV-Curable Powder Scale-Up | Eliminates thermal cure constraints for automotive interior and medical device segments. |
Research Methodology
Operator-level perspectives from plant managers at coating facilities, procurement leads at appliance OEMs, distribution channel partners, and technical R&D directors anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, Cefic chemical industry reports, SEC 10-K filings of listed coating suppliers, and ECHA regulatory databases. Bottom-up volume modeling across resin types and cure technologies triangulated against top-down market sizing from production capacity and utilization rates.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation dimensions covering formulation chemistry, cure temperature tier, end-use industry vertical, and regional production hub. CAGRs derived from trend extrapolation of line conversion economics, regulatory compliance cost trajectories, and substitution elasticity estimates. Industry-specific forecast inputs included EV battery enclosure specification timelines and national building energy code implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese resin suppliers or accelerated UV-curable powder adoption by automotive OEMs would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Canada Industrial Wood Coatings Market
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
Ethylene Tetrafluoroethylene (ETFE) Coatings Market
Coatings
Self-Healing Coatings Market
Coatings
Coating Pigments Market
Coatings
Epoxy Powder Coatings Market
Coatings
Russia Architectural Coatings Market
Coatings
Global Anti Slip Coatings Market
Coatings
Global Water-Based Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Silicate Coatings Market
Coatings
Global Optical Coating Market
Coatings
Global Coated Steel Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
Insulation Coating Market
Coatings
Heavy Duty Glass Coating Market