
 ASEAN Automotive OEM Coatings Market | 2026-2036
ASEAN Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Automotive OEM Coatings Market Outlook
Modular coating system bundling is recalibrating how ASEAN vehicle assemblers procure paint shop inputs. PPG Industries Inc. leverages integrated primer-to-clear-coat packages to deepen its relationship with Thai and Indonesian OEM assembly networks. AkzoNobel N.V. anchors its regional position through waterborne technology leadership and localized technical service centers. Axalta Coating Systems differentiates by specializing in compact process configurations that reduce paint shop footprint for emerging two-wheeler manufacturers.
ASEAN Automotive OEM Coatings encompass liquid and powder-applied protective and decorative layers formulated with polyurethane, epoxy, or acrylic resin systems, typically applied in 15-40 micron dry film thicknesses across electrocoat, primer, base coat, and clear coat stages to provide corrosion resistance, color fidelity, and weathering durability for factory-new vehicles. Clear coat and base coat categories command the dominant value share given their direct visibility and color-matching complexity requirements. Waterborne technology leads volume adoption across Thailand and Vietnam assembly plants, while UV-cured systems represent the fastest-growing technology segment as manufacturers seek reduced curing energy and accelerated line speeds.
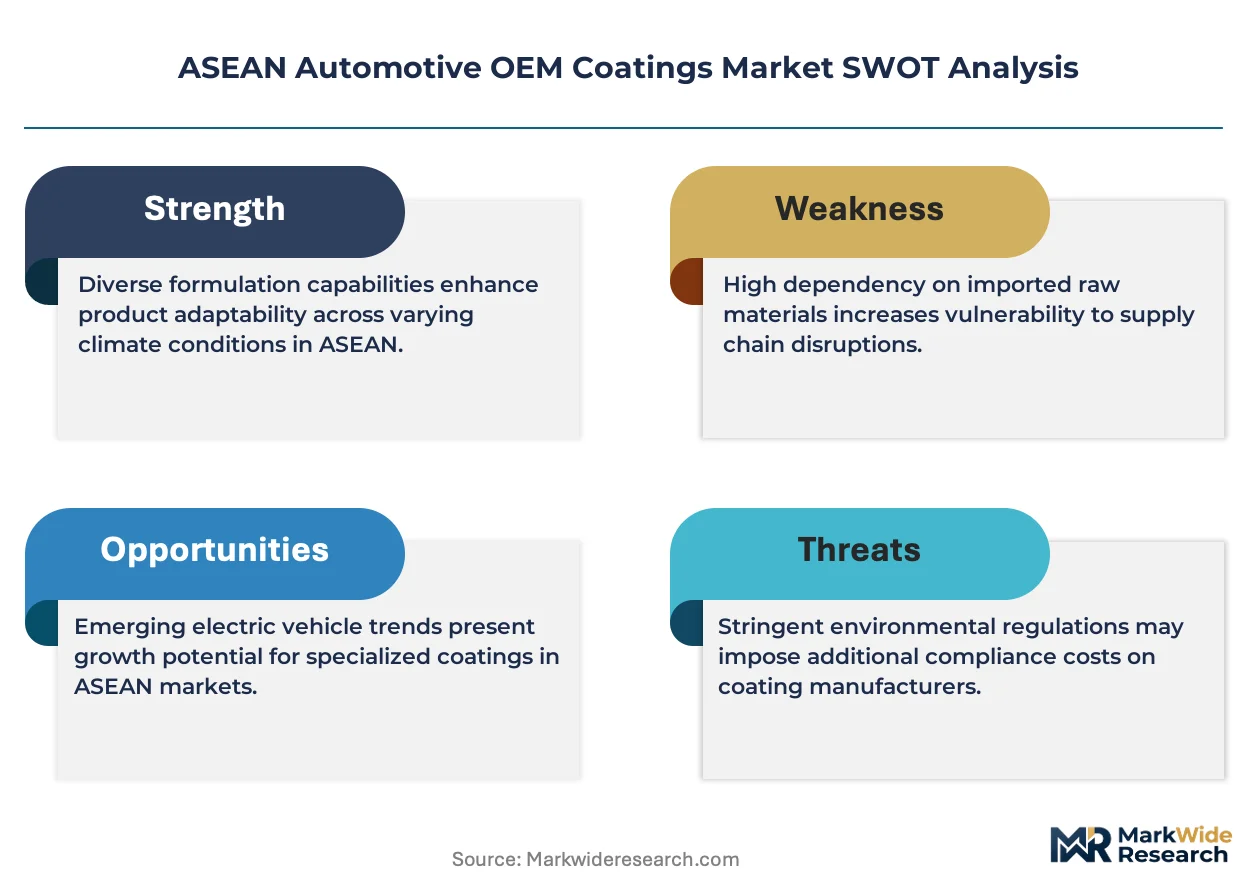
Thailand's Department of Industrial Works enforces volatile organic compound emission limits that compel coating reformulation toward waterborne and high-solids systems, while Indonesia's Ministry of Environment and Forestry implements comparable air quality standards affecting Jakarta and Bekasi manufacturing zones. Vietnam's Ministry of Natural Resources and Environment is tightening industrial discharge rules around Hanoi and Ho Chi Minh City automotive clusters. Stakeholders must monitor regulatory divergence across these three jurisdictions to align product registration strategies and avoid non-compliance delays at plant commissioning stages.
Market Dynamics
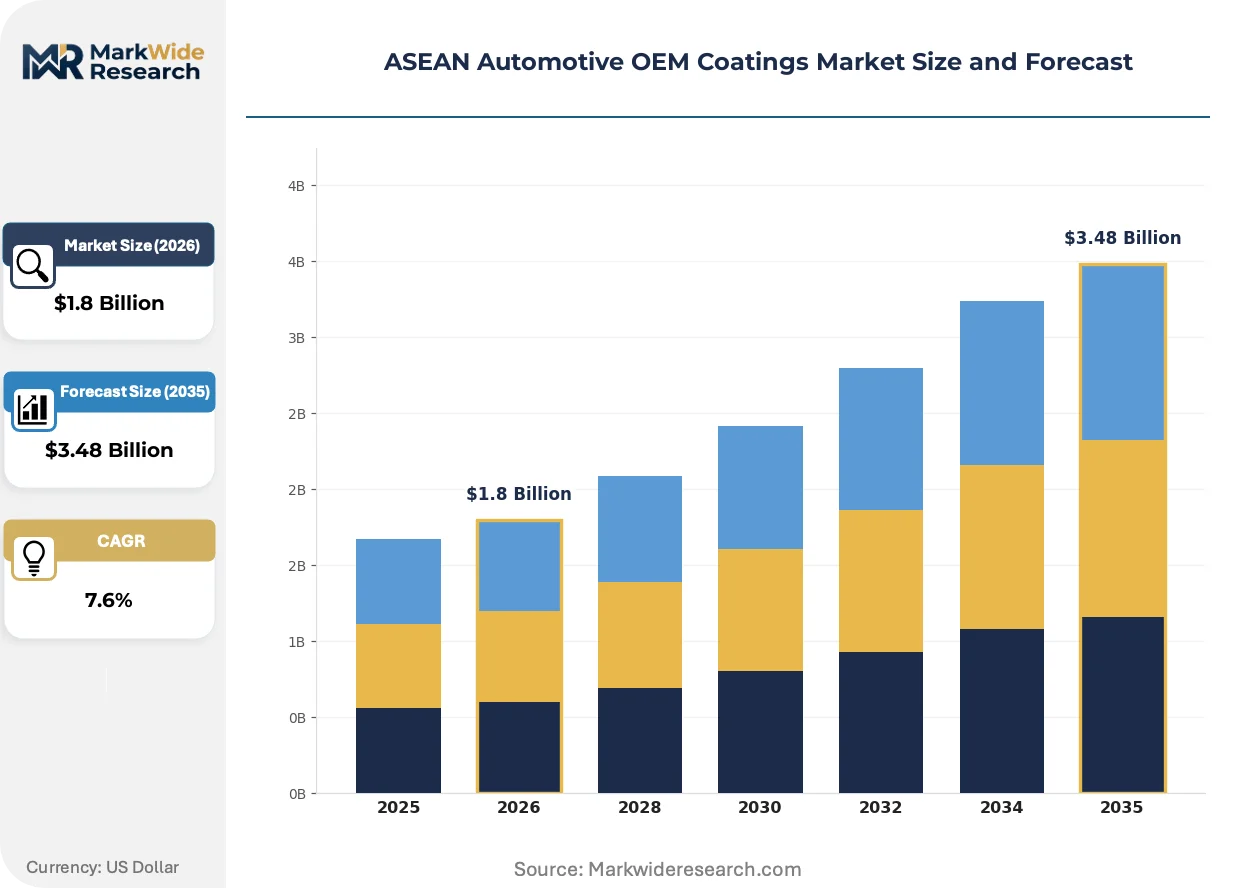
ASEAN Automotive OEM Coatings market dynamics pivot on waterborne system conversion mandates from Thailand's Department of Industrial Works, which are forcing assembly plants across the Eastern Economic Corridor to retool electrocoat and base coat lines while suppliers scramble to localize technical service capabilities.
Growth Catalysts
- Thailand's VOC emission caps:The Department of Industrial Works enforces strict volatile organic compound limits that compel coating reformulation toward waterborne systems, creating immediate replacement demand across primer and base coat categories.
- Two-wheeler electrification:Indonesia's expanding electric motorcycle assembly sector drives procurement of compact paint shop configurations with reduced curing footprints and energy-efficient UV clear coat systems.
- UV-cured clear coat throughput:This technology accelerates line speeds while cutting curing energy consumption, attracting adoption from Vietnamese passenger vehicle assemblers seeking productivity gains in Hanoi and Ho Chi Minh City manufacturing clusters.
Market Restraints
- Petrochemical resin volatility:Polyurethane and acrylic resin feedstock costs fluctuate with regional naphtha pricing, compressing margin predictability for coating formulators serving Thai assembly networks.
- Technical service concentration:Waterborne system troubleshooting expertise clusters in Bangkok and Jakarta technical centers, creating response-time disadvantages for Vietnamese plants requiring rapid color-matching support.
- High-solids regulatory friction:Indonesia's Ministry of Environment and Forestry air quality standards create compliance complexity when waterborne alternatives face humidity-related application challenges during monsoon seasons.
Strategic Opportunities
- Vietnam's industrial discharge tightening:The Ministry of Natural Resources and Environment is strengthening effluent rules around Hanoi automotive clusters, opening specification windows for low-VOC coating packages with integrated wastewater treatment compatibility.
- UV-waterborne hybrid convergence:Combining UV-cured clear coats with waterborne base coats enables energy-efficient multi-layer systems that meet Thai VOC rules while delivering premium gloss durability.
- Direct technical service localization:Establishing coating application laboratories within Ho Chi Minh City industrial zones shortens color development cycles for Vietnamese OEMs previously dependent on distant Bangkok or Singapore support hubs.
Industry Challenges
- Waterborne application skill gaps:Thai and Indonesian paint shop technicians require retraining on humidity-controlled spray booth management and flash-off timing, stretching workforce development timelines during plant conversion projects.
- Legacy solvent-borne inventory stranding:Assembly plants holding high-solids coating stocks face write-down pressure as Thailand's Department of Industrial Works enforcement windows compress transition schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Automotive OEM Coatings Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Coat, Primer, Base Coat, Electrocoat Technology: Waterborne, Solventborne, Powder Coating, UV-Cured Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Vehicle Assemblers End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships |
| Companies Covered | PPG Industries Inc., AkzoNobel N.V., Axalta Coating Systems, Jotun, The Sherwin-Williams Company, BASF SE, Kansai Paint Co., Ltd., KCC Corporation, Nippon Paint Holdings Co., Ltd., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Automotive OEM Coatings Market Strategic Shifts
Coating technology trajectories across ASEAN assembly plants center on curing energy reduction and process footprint compression, with regulatory compliance timelines acting as the primary adoption accelerant rather than pure performance differentiation.
UV-cured clear coat systems is rewriting competitive positioning in Thai passenger vehicle assembly. These formulations enable 30-40 second cure cycles versus 20-30 minute thermal baking, allowing PPG Industries and Axalta to pitch line-speed expansion without additional oven infrastructure. Eastern Economic Corridor plants adopting this technology compress their paint shop physical footprint while maintaining premium gloss and scratch-resistance specifications demanded by export-oriented OEMs.
Thailand's Department of Industrial Works volatile organic compound emission limits are tightening enforcement mechanisms across electrocoat, primer, and base coat stages. Industrial consequence includes mandatory waterborne system conversion for plants above specified throughput thresholds, with compliance verification now tied to annual operating permit renewals. Vietnamese assembly plants in Hanoi and Ho Chi Minh City are accelerating similar specification reviews in anticipation of comparable Ministry of Natural Resources and Environment rulemaking.
Modular coating procurement is consolidating specification authority at Thai and Indonesian OEM headquarters, displacing decentralized plant-level purchasing. Tier-1 suppliers now negotiate integrated primer-to-clear-coat packages directly with regional technical teams, compressing the number of approved vendor relationships per assembly network. This concentration is most visible in Thailand's Eastern Economic Corridor, where Eastern Seaboard industrial estates host clustered paint shop operations serving multiple export-oriented vehicle programs.
ASEAN Automotive OEM Coatings Market Segmentation
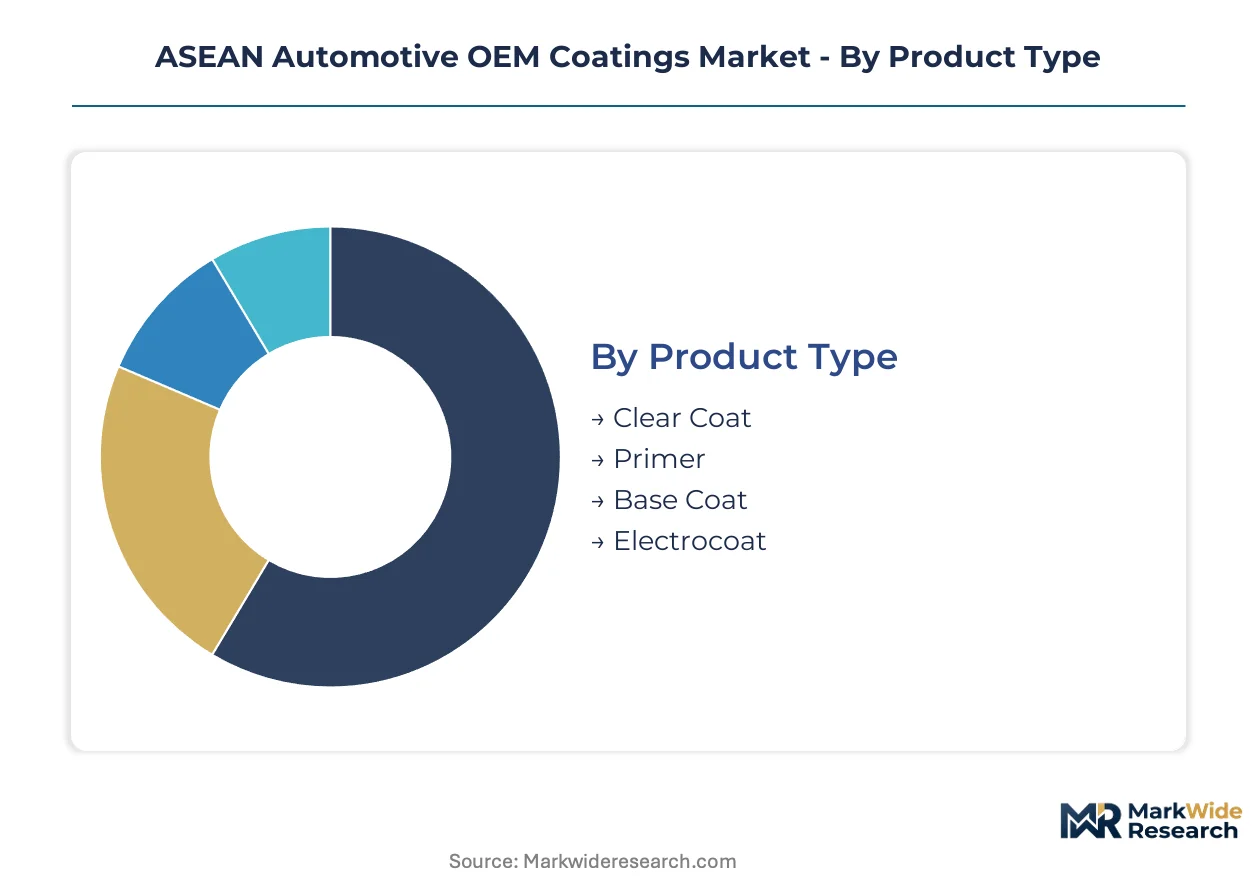
ASEAN Automotive OEM Coatings procurement patterns diverge sharply across product types, curing technologies, and vehicle application categories. Assembly plants in Thailand's Eastern Economic Corridor and Indonesia's Bekasi manufacturing zones specify coatings differently based on regulatory compliance timelines, line speed requirements, and export market destination standards.
Product Type:
Capital intensity peaks in clear coat and base coat installations, where precision color-matching infrastructure and controlled-environment spray booths dominate paint shop investment profiles across Thai and Vietnamese assembly networks.
- Clear Coat:Acrylic-urethane formulations deliver final surface gloss, scratch resistance, and UV weathering protection in 30-40 micron dry film builds. Thai passenger vehicle exporters in the Eastern Economic Corridor prioritize premium scratch-resistant grades for European and Australian destination markets where appearance durability carries warranty implications.
- Base Coat:Pigmented layers provide color fidelity and metallic effect control through waterborne or solventborne resin systems. Indonesian two-wheeler manufacturers in the Jakarta-Bekasi corridor drive specification diversity here, requiring rapid color change capabilities for high-mix production environments.
- Primer:Intermediate adhesion and stone-chip protection layers bridge electrocoat and base coat stages.
- Electrocoat:Cathodic epoxy immersion systems deliver uniform corrosion protection across complex vehicle body geometries.
Most installed capacity flows through Clear Coat. Expansion is steepest in Base Coat as Vietnamese passenger vehicle programs multiply color options for domestic and export variants.
Technology:
Application complexity and energy infrastructure requirements separate coating technologies, with waterborne systems demanding humidity-controlled spray environments that reshape plant utility investments.
- Waterborne:Acrylic and polyurethane dispersions replace organic solvents with water as primary carrier, cutting volatile organic compound emissions to comply with Thailand's Department of Industrial Works limits. Vietnamese assembly plants in Hanoi and Ho Chi Minh City are retrofitting spray booths to accommodate these systems ahead of anticipated Ministry of Natural Resources and Environment rulemaking.
- UV-Cured:Photoinitiator-activated clear coats polymerize in seconds under ultraviolet lamps, eliminating thermal oven curing. Thai passenger vehicle assemblers adopt these for throughput gains without footprint expansion, particularly in Eastern Seaboard industrial estates where land constraints limit paint shop expansion.
- Solventborne:Traditional high-solids formulations persist where humidity challenges waterborne application quality.
- Powder Coating:Thermoset epoxy and polyester systems serve specific component applications outside full-body automotive finishing.
Waterborne systems anchor current installation volumes. UV-Cured technology is climbing the fastest as energy efficiency targets harden across Thai and Indonesian manufacturing.
Application:
Vehicle category scale and export orientation determine coating specification sophistication, with passenger vehicle programs demanding multi-layer premium finishes absent from utility-focused commercial segments.
- Passenger Vehicles:Full decorative and protective coating stacks across electrocoat, primer, base coat, and clear coat stages, with color-matching precision to OEM design studio specifications. Thailand's Eastern Economic Corridor hosts the densest concentration, serving export-oriented programs for Japanese and Chinese brand parent companies.
- Two-Wheelers:Compact paint shop configurations favor single-stage or simplified two-layer systems with rapid cure cycles. Indonesia's electric motorcycle assembly expansion in Bekasi and Cikarang industrial zones drives demand for reduced-footprint coating lines.
- Commercial Vehicles:Durability-focused specifications prioritize corrosion protection over aesthetic complexity.
- Vehicle Assemblers:Contract manufacturing arrangements where coating procurement flows through multinational OEM technical specifications.
Passenger Vehicles absorb the majority of coating value. Two-Wheelers are expanding most quickly as Indonesia's electrification programs scale assembly capacity.
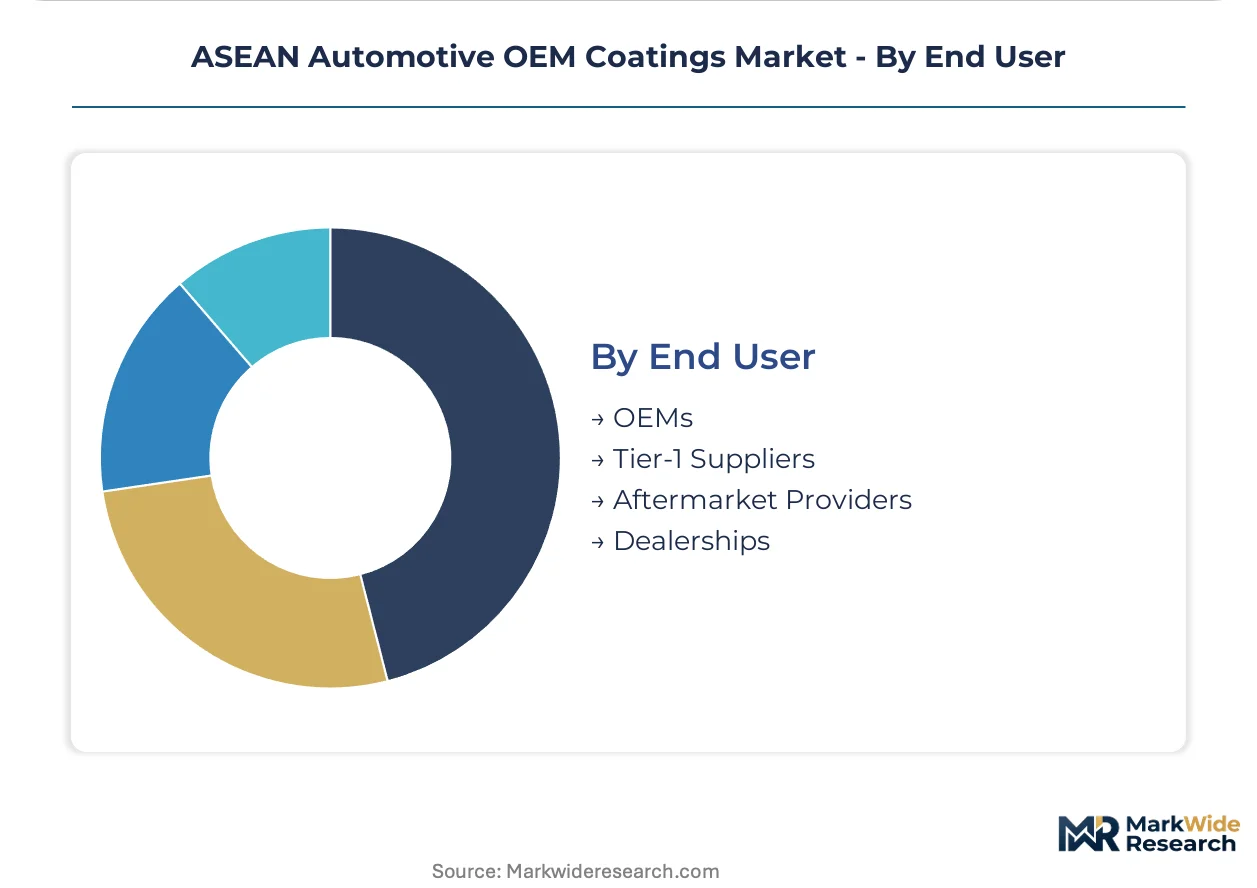
End User:
Specification authority concentration varies by end user type, with OEM headquarters technical teams increasingly overriding plant-level procurement decisions across ASEAN assembly networks.
- OEMs:Original equipment manufacturers with integrated paint shop operations at owned assembly plants in Thailand, Indonesia, and Vietnam. These entities drive technology roadmaps, mandating waterborne conversions and UV clear coat trials through centralized technical specifications.
- Tier-1 Suppliers:Component manufacturers supplying painted body panels, bumpers, and trim modules to final assembly. Thai tier-1 operations in the Eastern Economic Corridor coordinate coating specifications directly with OEM regional technical centers, consolidating vendor relationships.
- Aftermarket Providers:Refinish coating demand for collision repair and restoration outside factory-new applications.
- Dealerships:Minor touch-up and cosmetic repair services using matched refinish systems.
OEMs command the dominant specification share. Tier-1 Suppliers are gaining procurement influence as modular assembly outsourcing expands across Indonesian and Vietnamese vehicle programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive coating demand across Southeast Asia traces its industrial lineage to Thailand's 1980s Board of Investment incentives that established the region's first integrated vehicle export platforms. Japanese transplants seeded coating supply chains in the Eastern Seaboard, later replicated in Indonesian and Vietnamese manufacturing zones as ASEAN trade integration deepened.
Thailand
Passenger vehicle exporters in the Eastern Economic Corridor drive specification upgrades toward UV-cured clear coats and waterborne base systems. The Department of Industrial Works enforces volatile organic compound caps tied to annual operating permit renewals. Rayong and Chonburi industrial estates host clustered paint shop operations serving Japanese and Chinese OEM parent companies with premium gloss requirements for European and Australian destination markets.
Indonesia
Two-wheeler electrification programs in Bekasi and Cikarang industrial zones generate procurement of compact paint shop configurations with reduced curing footprints. The Ministry of Environment and Forestry implements air quality standards creating compliance complexity during monsoon humidity conditions. Jakarta-Bekasi corridor assemblers negotiate integrated primer-to-clear-coat packages directly with regional OEM technical teams.
Vietnam
Passenger vehicle assemblers in Hanoi and Ho Chi Minh City manufacturing clusters accelerate specification reviews ahead of anticipated Ministry of Natural Resources and Environment rulemaking. The ministry is tightening industrial discharge rules around automotive clusters. Assembly plants retrofit spray booths to accommodate waterborne systems while seeking localized technical service capabilities to reduce dependency on distant Bangkok support hubs.
Malaysia
Commercial vehicle and component manufacturing in Selangor and Johor maintains steady coating procurement focused on durability specifications over aesthetic complexity. The Department of Environment administers factory emission standards affecting paint shop operations. Shah Alam industrial zones host tier-1 suppliers coordinating coating specifications with regional OEM technical centers for modular assembly outsourcing.
Philippines
Vehicle assembly in Laguna and Cavite provinces relies on imported coating systems with limited local formulation capability. The Department of Environment and Natural Resources oversees industrial air emission regulations. Calabarzon manufacturing zones concentrate the archipelago's automotive finishing demand through contract assemblers serving multinational brand programs with specification authority flowing from regional headquarters.
ASEAN Automotive OEM Coatings Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology sophistication and technical service density. The supplier base concentrates around integrated coating system providers with localized application laboratories and OEM-direct specification relationships. Three archetypes dominate: multinational chemical conglomerates with full-stack primer-to-clear-coat portfolios, specialized automotive coating divisions of broader paint companies, and Asia-Pacific regional specialists with cost-optimized formulations. Competitive moves center on technical service center localization and modular system bundling that consolidates vendor relationships per assembly network.
Within the multinational tier, PPG Industries Inc. and AkzoNobel N.V. represent archetypes of integrated system providers with regional technical infrastructure. Axalta Coating Systems occupies a position exemplifying specialized automotive focus with compact process configurations. These three names anchor the competitive landscape visible in procurement patterns across Thai and Indonesian assembly networks, with each representing distinct strategic positioning around technology leadership, service localization, or footprint efficiency.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| AkzoNobel N.V. |
| Axalta Coating Systems |
| Jotun |
| The Sherwin-Williams Company |
| BASF SE |
| Kansai Paint Co., Ltd. |
| KCC Corporation |
| Nippon Paint Holdings Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Waterborne coating application specialists concentrated in Bangkok and Jakarta command wage premiums that compress margin spreads between premium-grade UV-cured systems and standard waterborne packages. Thai assembly plants in the Eastern Economic Corridor absorb these labor-cost differentials while Vietnamese facilities face extended color-matching cycles that erode throughput economics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates UV-cured clear coats with sub-60-second cure cycles from conventional thermal-baked systems and basic high-solids formulations. Price differentiation hinges on certification tier against Thailand's Department of Industrial Works VOC limits and volume scale of coating procurement per assembly network. Pricing pressure stems from petrochemical resin feedstock volatility tied to regional naphtha pricing. Tier-1 suppliers in Indonesia's Bekasi corridor exhibit highest price sensitivity due to contract manufacturing margins, while Thai export-oriented OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
OEM qualification gating through centralized technical specifications at Thai and Indonesian headquarters consolidates approved vendor lists to three integrated system providers. Resin supply concentrates in Japan, South Korea, and Singapore, with polyurethane and acrylic feedstocks drawing from regional petrochemical complexes. Supply chain risk centers on single-source vulnerability for photoinitiator chemicals in UV-cured formulations. Distribution runs through direct technical service agreements with localized application laboratories rather than merchant chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Vietnam's lagging regulatory enforcement against Thailand's Department of Industrial Works compliance deadlines creates specification-timing windows for coating suppliers with portable technical service capabilities.
For Market Incumbents: Anticipate margin compression from emerging regional specialists offering cost-optimized waterborne formulations by deepening backward integration into acrylic resin production and expanding Ho Chi Minh City technical service capacity ahead of Vietnam's Ministry of Natural Resources and Environment rulemaking. Certification investment against anticipated ASEAN-wide VOC harmonization represents the priority defensive lever. For New Entrants and Emerging Players: Enter via Vietnamese passenger vehicle assembly networks in Hanoi industrial zones where incumbent technical service density remains lowest and waterborne system conversion timelines stretch procurement decision cycles. White-space concentration in compact UV-cured configurations for Indonesia's electric two-wheeler sector offers the most penetrable entry point, with direct OEM technical team engagement as the essential go-to-market angle. For Investors and Strategic Acquirers: Chemical conglomerates with automotive coating divisions are the most active acquirer in this space, targeting regional specialists with established OEM qualification status and localized application laboratories. Long-term viability over a multi-year horizon depends on regulatory compliance technology portability across Thailand, Indonesia, and Vietnam. The signal to watch is Vietnam's Ministry of Natural Resources and Environment discharge rule finalization timing as inflection indicator for specification authority consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Technical Service Localization | Ho Chi Minh City laboratories shorten Vietnamese OEM color development cycles previously dependent on Bangkok support. |
| UV-Waterborne Hybrid Development | Combined systems meet Thai VOC rules while delivering premium gloss durability for Eastern Economic Corridor exporters. |
| Backward Integration into Resins | In-house acrylic production insulates margin predictability against regional naphtha price volatility. |
| Compact Process Configuration | Reduced paint shop footprint targets Indonesia's electric motorcycle assembly expansion in Bekasi industrial zones. |
| Regulatory Pre-Qualification Investment | Early Vietnam certification positioning captures specification windows ahead of Ministry rulemaking enforcement. |
Study Parameters
Coverage spans Thailand, Indonesia, and Vietnam, with primary inputs from each market combining structured interviews with OEM platform engineers, Tier-1 supplier procurement leads, coating application technicians, and regional technical service directors alongside secondary validation. Secondary sources include vehicle production databases, customs and trade flow records, Department of Industrial Works regulatory filings, and ASEAN automotive industry association reports. Bottom-up coating volume estimates triangulate against top-down OEM assembly capacity assessments.
Rate-of-change decomposition separates volume growth from value-per-unit shifts across the projection horizon. The analytical framework models segmentation dimensions including coating layer type, curing technology, vehicle application category, and end-user procurement authority. CAGRs derive from regression-based trend extrapolation moderated by regulatory enforcement timeline assumptions. Industry-specific forecast inputs encompass VOC compliance phase-in schedules and electric vehicle assembly capacity announcements.
Inputs from regulatory agencies and OEM technical specifications were available through the study window; gaps in proprietary formulation cost structures introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding enforcement consistency and technology adoption elasticity. A model refresh is warranted upon material change in Vietnam's Ministry of Natural Resources and Environment rulemaking timeline or Thailand's Department of Industrial Works permit renewal enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Graphene Coatings Market
Coatings
PU Coatings Market
Coatings
Powder Coating Booth Market
Coatings
Global Hydrophobic Coating Market
Coatings
Global Anti Slip Coatings Market
Coatings
Marine Coatings Market
Coatings
Global Antiviral Coatings Market
Coatings
Coating Thickness Gauge Market
Coatings
Yacht Coatings Market
Coatings
Shipping Container Coatings Market
Coatings
Epoxy Powder Coatings Market
Coatings
Acrylic Coating Market
Coatings
Ethylene Tetrafluoroethylene (ETFE) Coatings Market
Coatings
North America Epoxy Powder Coatings Market
Coatings
Global Powder Coating Market
Coatings
Global Fire-Resistant Coating Market