
 Extrusion Coating Market | 2026-2036
Extrusion Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Extrusion Coating Market Analysis
Food packaging is expanding as the dominant demand vertical for extrusion coating, displacing slower-growing industrial segments. Dow leverages its polyethylene resin leadership to anchor supply relationships with major flexible packaging converters. SABIC competes through backward integration into petrochemical feedstocks across Middle Eastern production complexes. LyondellBasell Industries Holdings B.V. differentiates via specialized polypropylene grades engineered for high-speed coating lines.
Extrusion coating applies molten polymer—typically polyethylene or polypropylene at 300–350°C—onto substrates such as paper, aluminum foil, or oriented films to create moisture and oxygen barriers. The process operates through a flat die extruding a thin, uniform layer onto a moving web, with line speeds reaching 1,000 meters per minute for commodity packaging grades. Polyethylene formulations occupy the largest volume share given their cost position and heat-seal performance, though multi-layer co-extrusion techniques command premium positioning in medical and retort applications where barrier stacking replaces monolayer limitations. Ethylene vinyl acetate segments sustain above-average growth in frozen food and deep-draw thermoforming formats.
FDA food-contact regulations govern substrate and additive migration limits in the United States, while REACH and EU Packaging and Packaging Waste Directive reshape material selection across European supply chains. EMA and FDA standards for medical packaging impose sterility validation protocols that elevate qualification barriers for new entrants. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based content mandates as these mechanisms increasingly determine market access and contract eligibility.
Market Dynamics
REACH compliance in Europe and FDA migration limits in the United States are forcing material reformulation across the extrusion coating supply chain, compressing qualification timelines while elevating barrier performance requirements for food-contact applications.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Extended producer responsibility frameworks in Europe mandate higher recycled content thresholds, pulling investment toward compatible coating technologies that maintain heat-seal integrity with post-consumer feedstocks.
- India packaging hub maturation:Regional converters in Maharashtra and Gujarat are scaling multi-layer co-extrusion capacity to serve frozen food and dairy export demand, anchoring polyethylene consumption growth across South Asia.
- Retort sterilization protocols:EMA sterility validation requirements for medical packaging are expanding addressable demand for high-barrier co-extruded structures that replace aluminum laminates in sterilizable pouches.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker economics in the Middle East and Asia expose coating resin pricing to crude oil oscillations, compressing converter margins during upstream cost spikes.
- Monolayer performance ceiling:Single-layer polyethylene structures face oxygen transmission rate limitations below 0.1 cc/m²/day, excluding them from wine and nutraceutical applications where ethylene vinyl alcohol co-extrusion commands necessary barrier stacking.
- REACH authorization delays:ECHA substance of very high concern listings for certain slip additives extend reformulation cycles by 18-24 months, freezing specification approvals for European food-contact grades.
Strategic Opportunities
- Indonesia flexible packaging expansion:Underpenetrated cold-chain infrastructure in Java and Sumatra creates white space for deep-draw thermoforming grades with modified atmosphere barrier properties.
- Bio-based polyethylene certification:ISCC PLUS mass-balance verification opens contract eligibility with European brand owners facing Scope 3 emissions disclosure under CSRD corporate sustainability reporting mandates.
- Digital print substrate convergence:Water-based ink compatibility requirements from HP Indigo and Xeikon installations are pulling investment toward corona-treated coating surfaces that eliminate primer layers.
Industry Challenges
- Multi-layer die engineering expertise:Co-extrusion manifold design for viscosity-mismatched polymers requires specialized rheological knowledge concentrated among veteran toolmakers in Germany and Italy.
- FDA food-contact notification timelines:New substance petitions for novel barrier additives face 120-day review windows that delay product launches against faster-moving competitors with grandfathered approvals.
- Legacy extruder retrofit complexity:Existing 3-meter chill-roll lines require screw and L/D ratio modifications to process higher-melt-strength polypropylene grades, stranding capital in suboptimal configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extrusion Coating Market |
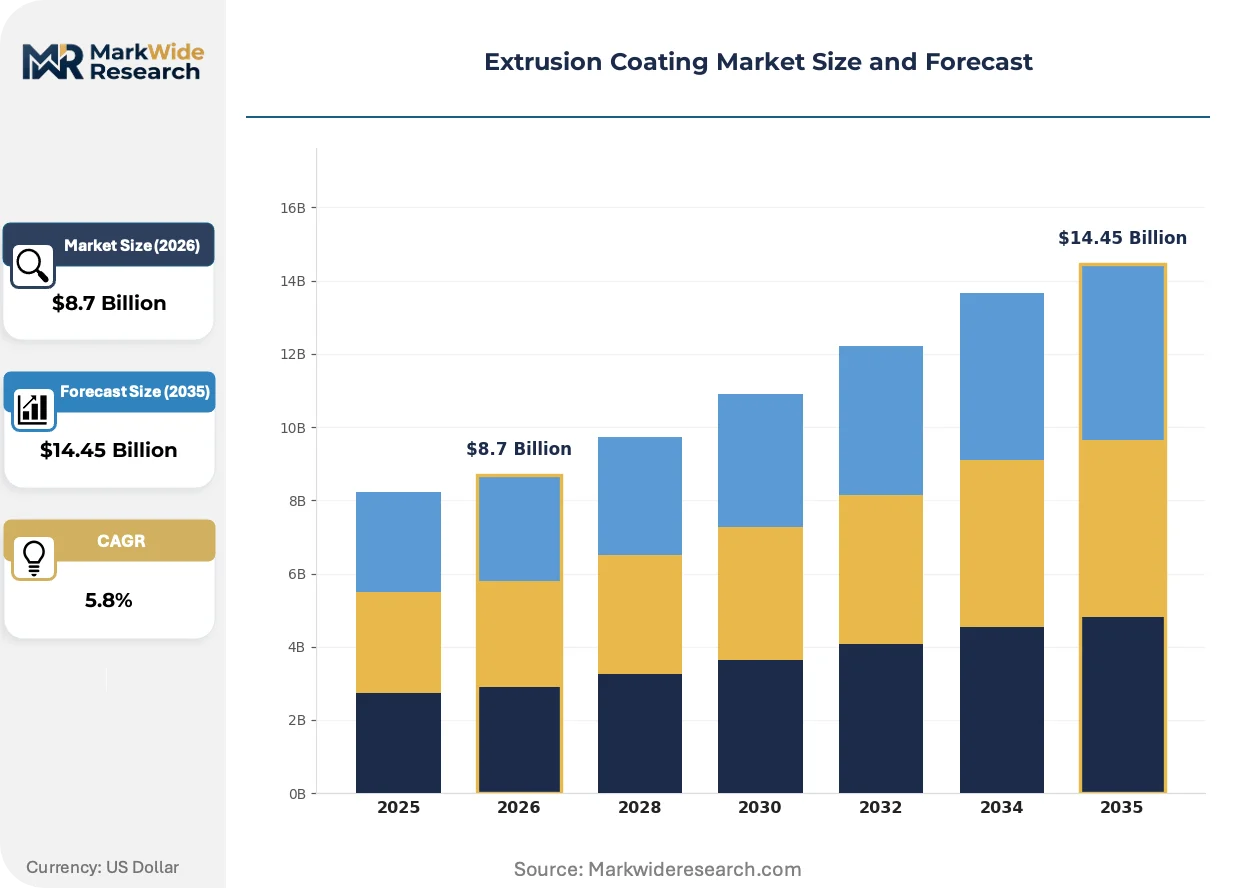
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Ethylene Vinly Acetate, Others Technique: Co-extrusion, Single Layer, Multi-layer, Others Application: Food Packaging, Medical Packaging, Industrial Applications, Automotive Components End User: Consumer Goods, Packaging Industry, Automotive, Electronics |
| Companies Covered | Axalta Coating Systems, Dow, PPG Industries, Inc., Chevron Phillips Chemical Company LLC, SABIC, The Sherwin-Williams Company, LyondellBasell Industries Holdings B.V., Borealis AG, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extrusion Coating Market Emerging Trajectories
Barrier engineering is migrating from monolayer commodity structures toward functional stacking that addresses specific oxygen and moisture transmission requirements, while regulatory chemistry restrictions accelerate material substitution cycles.
Multi-layer co-extrusion with tie-layer adhesives is rewriting the competitive map for high-performance packaging. Pharmaceutical blister packs and retort pouches in Germany and Switzerland are adopting five-layer structures incorporating ethylene vinyl alcohol and polyamide skins. This architecture compresses aluminum foil consumption in sterilizable formats while meeting EMA extractables and leachables protocols.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer process aids from European extrusion coating operations. Converters in the Netherlands and Belgium are qualifying silicone-based alternatives that maintain die lip cleanliness without compromising heat-seal initiation temperatures. Medical packaging specifications in the EU face the steepest reformulation curves given FDA-EU mutual recognition agreement complexities.
Brand-owner sustainability scorecards are reshaping procurement specifications for substrate suppliers. Nestlé and Unilever purchasing teams in the United Kingdom and France now require mass-balance certificates for bio-based content claims, displacing conventional resin tenders that lack third-party verification. This behavioral shift concentrates contract awards among converters with integrated ISCC auditing capabilities.
Extrusion Coating Market Segmentation
Extrusion coating procurement decisions pivot on barrier performance requirements, regulatory compliance burdens, and line-speed compatibility with existing converter assets. Material selection and process technique choices cascade through specification approvals, tooling investments, and end-use qualification timelines.
Product Type:
Cost-performance positioning at the resin level determines converter margin structures and substitution elasticity against alternative barrier technologies.
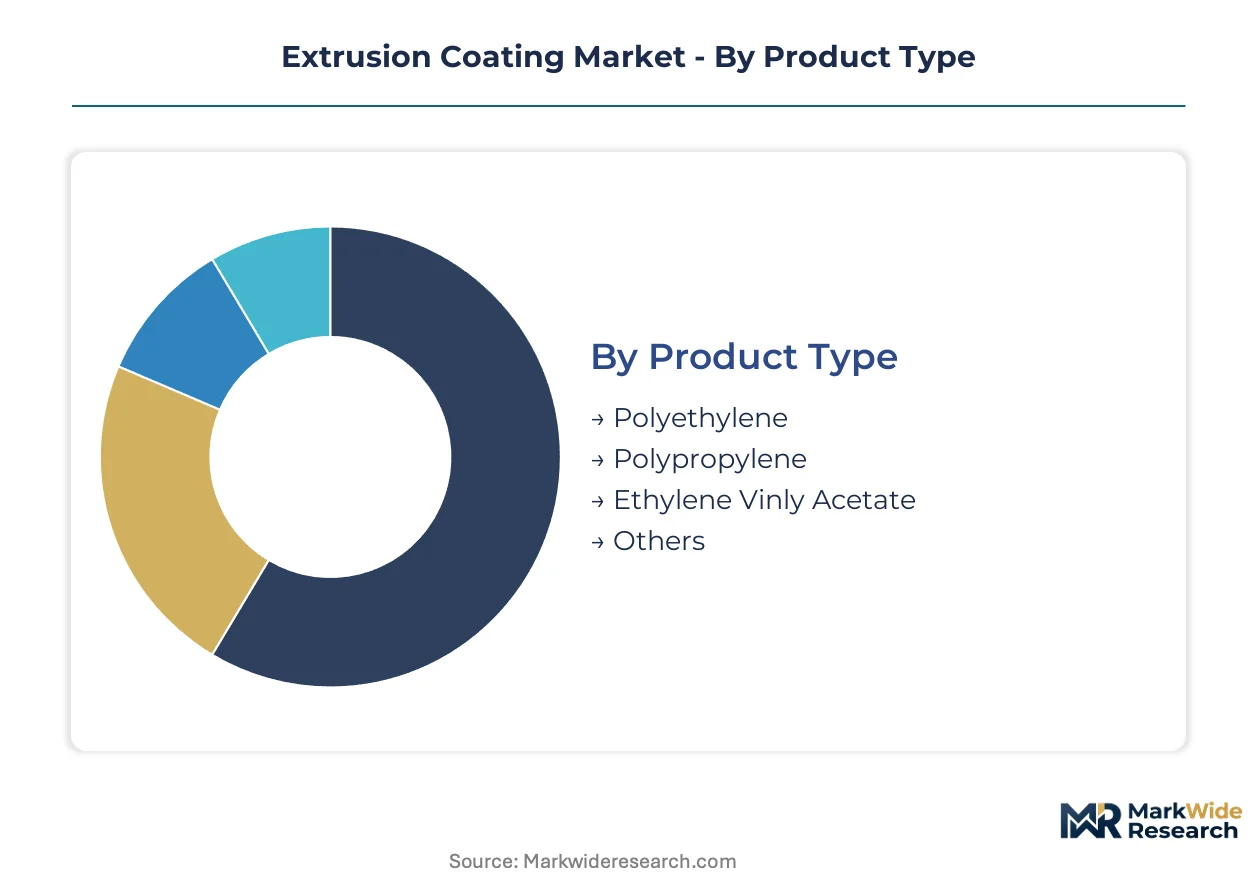
- Polyethylene:Low-density and linear-low-density formulations dominate commodity flexible packaging due to heat-seal initiation temperatures below 110°C and compatibility with high-speed coating lines. Demand concentrates in Maharashtra and Gujarat export corridors serving frozen food and dairy applications, though naphtha-cracker feedstock volatility compresses margin predictability during crude oil oscillations.
- Polypropylene:Higher-melt-strength grades engineered for 300-meter-per-minute lines deliver stiffness advantages in retort pouch structures and medical sterilizable formats. Adoption accelerates in Germany and Switzerland pharmaceutical packaging where EMA extractables protocols favor polypropylene's lower migration profile against polyethylene alternatives.
- Ethylene Vinyl Acetate:Copolymer formulations with 9-18% vinyl acetate content provide low-temperature sealability for frozen food and deep-draw thermoforming applications.
- Others:Specialty ionomers and acid copolymers serve niche oil-resistance requirements in industrial laminates and automotive underhood applications.
Polyethylene leads on scale; polypropylene leads on momentum as medical and retort specifications displace commodity formats.
Technique:
Barrier architecture complexity separates qualification-capable suppliers from commodity converters locked in monolayer competition.
- Co-extrusion:Simultaneous extrusion of 3-7 polymer layers through a single manifold die enables functional stacking with tie-layer adhesives binding dissimilar materials. Pharmaceutical blister packs in Germany and retort pouches in Switzerland adopt five-layer EVOH-polyamide structures that displace aluminum laminates while meeting EMA sterility validation protocols.
- Single Layer:Monolayer polyethylene structures face oxygen transmission rate limitations below 0.1 cc/m²/day, excluding wine and nutraceutical applications where barrier performance minimums mandate multi-layer alternatives.
- Multi-layer:Sequential lamination of pre-extruded films permits combining oriented substrates with molten polymer coatings for high-barrier medical packaging.
- Others:Tandem extrusion and extrusion lamination hybrids serve specialized photographic and electronics packaging with unique surface energy requirements.
Co-extrusion commands premium positioning; single-layer faces displacement pressure from regulatory barrier escalation.
Application:
End-use sterility and migration requirements segment the supplier base by validation capability and regulatory geography coverage.
- Food Packaging:Flexible pouch and lidding structures for frozen, chilled, and shelf-stable formats constitute the dominant demand vertical. Regional converters in India and Southeast Asia scale multi-layer capacity to serve export dairy and processed meat demand, anchoring polyethylene consumption growth.
- Medical Packaging:Sterilizable pouches, blister packs, and lidding for pharmaceutical products require EMA and FDA dual compliance. REACH restrictions on fluoropolymer process aids force Dutch and Belgian converters to qualify silicone-based alternatives without compromising heat-seal performance.
- Industrial Applications:Protective films and release liners for construction and electronics manufacturing leverage cost-optimized monolayer structures.
- Automotive Components:Underhood insulation and carpet backing applications demand oil and heat resistance from specialized polypropylene and ionomer formulations.
Food packaging anchors volume; medical packaging expands most quickly as aluminum replacement accelerates under sustainability procurement mandates.
End User:
Customer concentration and specification ownership patterns determine contract tenure and pricing leverage dynamics.
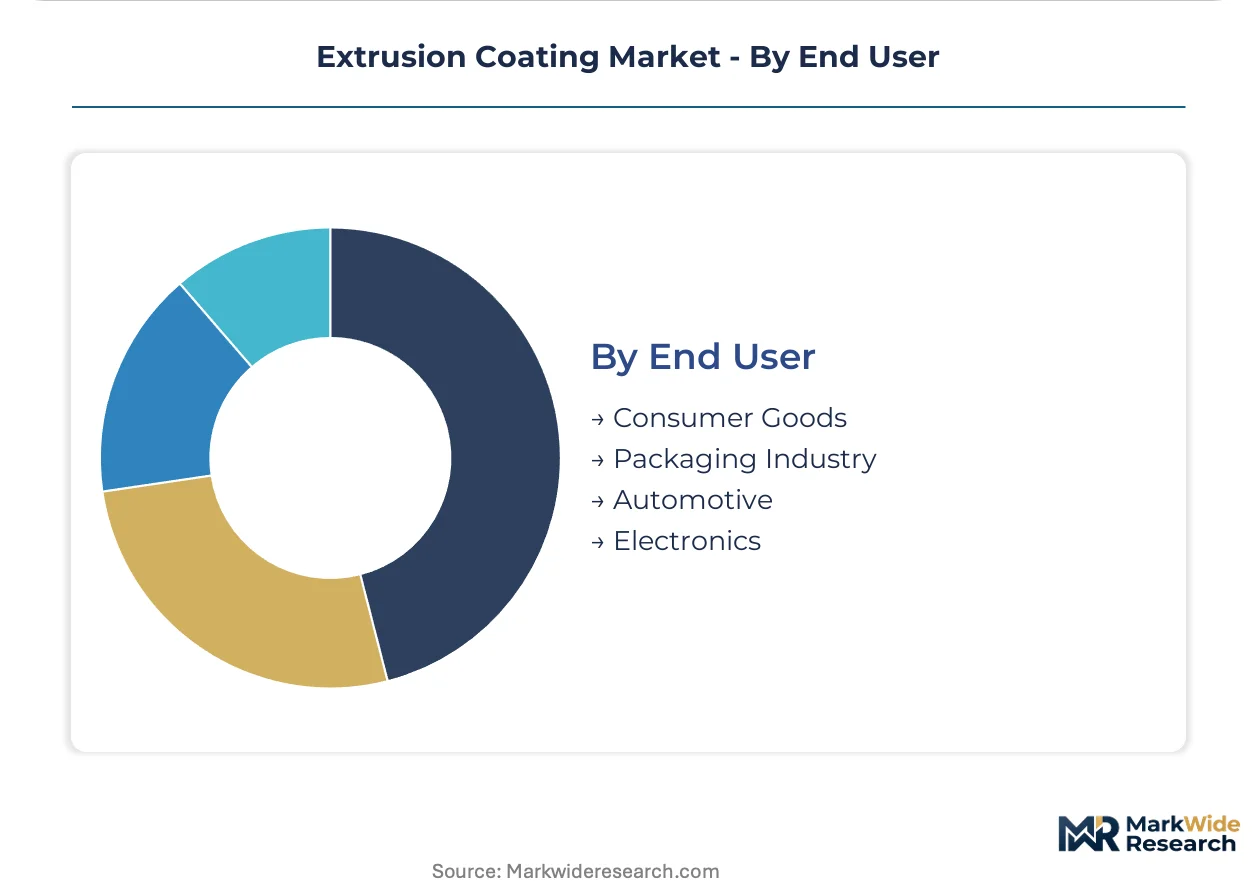
- Consumer Goods:Nestlé and Unilever purchasing teams in the United Kingdom and France require ISCC PLUS mass-balance certificates for bio-based content claims, concentrating contract awards among converters with integrated auditing capabilities.
- Packaging Industry:Flexible packaging converters serving retail and institutional food channels represent the intermediary demand layer with highest volume throughput and greatest price sensitivity to resin cost movements.
- Automotive:Tier-1 interior trim suppliers specify coated fabrics and insulation materials with OEM-directed material approval systems.
- Electronics:Cleanroom-compatible packaging for semiconductor and display components requires particulate control and static dissipation properties.
Packaging industry intermediaries dominate volume throughput; consumer goods direct procurement climbs fastest as brand-owner sustainability scorecards reshape supplier selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Gujarat industrial corridors anchor polyethylene consumption growth as regional converters scale multi-layer co-extrusion capacity for frozen food and dairy export demand. FDA migration limits and REACH compliance reshape material selection across major supply chains.
United States
Frozen food pouch demand from Midwest retail channels drives polyethylene coating consumption. FDA food-contact regulations govern substrate and additive migration limits, compressing qualification timelines for new barrier formulations. Chicago-area flexible packaging converters invest in high-speed coating lines serving private-label dairy and meat brands.
Germany
Pharmaceutical blister pack specifications pull five-layer EVOH-polyamide structures into medical packaging. REACH restrictions on per- and polyfluoroalkyl substances eliminate fluoropolymer process aids from extrusion operations. Rhine-Ruhr industrial clusters host converters qualifying silicone-based alternatives for EMA sterility validation protocols.
India
Regional packaging hubs in Maharashtra and Gujarat mature as export-oriented dairy and processed meat demand accelerates. FSSAI food safety standards align with EU import requirements for coated paperboard structures. Ahmedabad-based converters expand co-extrusion capacity to serve Middle East and Southeast Asian distribution networks.
Indonesia
Underpenetrated cold-chain infrastructure in Java and Sumatra creates demand for deep-draw thermoforming grades with modified atmosphere barrier properties. National food safety agency regulations tighten substrate migration testing for imported coating resins. Surabaya industrial zones attract polyethylene resin distributors targeting emerging flexible packaging converters.
Switzerland
Retort pouch sterilization protocols for pharmaceutical applications sustain premium positioning for high-barrier co-extruded structures. Swissmedic medical device regulations impose extractables and leachables testing that favors polypropylene's lower migration profile. Basel-area packaging specialists displace aluminum laminates in sterilizable formats through EMA-compliant multi-layer engineering.
Extrusion Coating Market Vendor Landscape
Capacity expansion dominates the current landscape as resin producers and coating specialists position for food packaging demand growth. The supplier base consolidates around petrochemical majors with captive polyethylene supply, mid-tier converters with regional qualification expertise, and specialty compounders serving medical sterility protocols. Three archetypes define positioning: integrated resin-coating operations, independent converters with multi-layer die engineering capabilities, and niche suppliers focused on bio-based certification. M&A activity and strategic partnerships concentrate among European and Asian players seeking REACH-compliant formulation portfolios.
Among integrated petrochemical suppliers, Dow and SABIC occupy positions defined by upstream resin leadership and downstream coating relationships. LyondellBasell Industries Holdings B.V. exemplifies the specialty-grade tier through engineered polypropylene formulations. These three entities represent distinct competitive vectors: Dow anchors North American polyethylene supply chains, SABIC leverages Middle Eastern feedstock integration, and LyondellBasell targets European medical and retort specifications requiring higher-melt-strength materials.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Dow |
| PPG Industries, Inc. |
| Chevron Phillips Chemical Company LLC |
| SABIC |
| The Sherwin-Williams Company |
| LyondellBasell Industries Holdings B.V. |
| Borealis AG |
| Akzo Nobel N.V. |
| Others |
Supply Flow & Price Mechanics
Backward integration into naphtha-cracker operations anchors pricing power for Middle Eastern and Asian resin producers, while converters in Europe and North America absorb feedstock volatility through contract structures that lag spot ethylene movements by 90-120 days.
Pricing Analysis
Input-cost pass-through from naphtha-cracker economics governs polyethylene resin quotations, with Gulf Coast and Singapore spot ethylene benchmarks feeding monthly price adjustments for coating-grade materials. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade polypropylene with EMA extractables documentation from commodity flexible packaging grades. Price differentiation hinges on certification tier and volume scale, with ISCC PLUS mass-balance verification commanding 8-12% premiums in European procurement. Cost compression in standard-grade polyethylene is intensifying because Indian and Southeast Asian converters are scaling co-extrusion capacity faster than regional resin supply expansion. Brand-owner sustainability scorecards show least price sensitivity; independent flexible packaging converters in Maharashtra and Gujarat exhibit highest sensitivity to resin cost movements.
Supply Chain Analysis
Direct-to-converter channels handle hyperscale demand from Nestlé and Unilever procurement teams, while distributor networks serve mid-tier flexible packaging converters across India's industrial corridors. Geographic supply concentration centers on Saudi Arabia, the United Arab Emirates, and South Korea for polyethylene resin feedstock. Raw material dependencies draw from naphtha-cracker ethylene, catalyst systems for polymerization, and specialty additives for slip and antiblock functionality. Single-source vulnerability runs through Middle Eastern feedstock integration, where SABIC and regional national oil companies control upstream aromatics supply. Distribution runs through regional resin distributors in Ahmedabad, Mumbai, and Surabaya who manage inventory positions and technical service for converter qualification protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The extrusion coating market represents a late-cycle quality story as pharmaceutical and retort packaging specifications displace commodity flexible formats, with EMA sterility validation requirements and REACH fluoropolymer restrictions accelerating premium-grade procurement.
For Market Incumbents: Cement multi-layer co-extrusion engineering capabilities through acquisition of German and Italian die toolmakers, where rheological expertise for viscosity-mismatched polymers remains concentrated. Prioritize ISCC PLUS certification investment to defend contract eligibility against European brand-owner sustainability scorecards. Capacity addition in Maharashtra and Gujarat secures anchor positions in India's export-oriented dairy and processed meat packaging corridors. For New Entrants and Emerging Players: E-commerce-enabled technical service platforms offer low-friction entry for Indonesian flexible packaging converters seeking deep-draw thermoforming qualification support. Target underpenetrated cold-chain infrastructure in Java and Sumatra where modified atmosphere barrier specifications remain nascent. Lead with digital substrate compatibility credentials for HP Indigo and Xeikon installations to bypass incumbent primer-layer relationships. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier European converters with REACH-compliant formulation portfolios because regulatory authorization delays of 18-24 months for novel additives create acquisition premiums over greenfield qualification timelines. Monitor EMA-FDA mutual recognition agreement negotiations as the inflection indicator for medical packaging contract concentration toward dual-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha-Cracker Feedstock | SABIC and regional producers in Saudi Arabia secure captive ethylene supply against crude oil volatility. |
| Multi-Layer Co-Extrusion Capacity Expansion | Ahmedabad-based converters scale five-layer EVOH-polyamide lines for EMA-compliant pharmaceutical blister packs. |
| ISCC PLUS Mass-Balance Certification | European converters unlock Nestlé and Unilever contract eligibility under CSRD Scope 3 disclosure mandates. |
| Silicone-Based Process Aid Qualification | Dutch and Belgian converters replace fluoropolymer additives banned under REACH restrictions. |
| Digital Print Substrate Convergence | Corona-treated coating surfaces eliminate primer layers for HP Indigo water-based ink compatibility. |
Methodological Framework
Direct dialogue with extrusion coating plant managers, flexible packaging procurement leads at consumer goods multinationals, resin distribution channel partners, and technical R&D directors at die engineering specialists grounded the qualitative assessment. Secondary validation drew from customs and trade data for polyethylene resin movements, ACC and Cefic chemical industry reports, SEC 10-K filings for integrated petrochemical suppliers, and ECHA substance authorization databases. Bottom-up and top-down triangulation cross-checked converter capacity announcements against resin demand forecasts.
Segmentation outputs across resin type, co-extrusion technique complexity, end-use sterility requirements, and regional regulatory cluster modeled value and volume trajectories throughout the forecast period. CAGRs were derived from elasticity-adjusted demand projections for food packaging, medical sterilizable formats, and industrial laminates, with specific inputs including naphtha-cracker operating rates in the Middle East and India packaging hub investment pipelines.
The model assumes a particular technology adoption path; alternative pathways for bio-based polyethylene scale-up through mass-balance verification would alter the outlook for European contract concentration. Forecasts reflect assumptions about REACH authorization timelines and FDA food-contact notification review windows. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Acrylic Protective Coating Market
Coatings
Epoxy Powder Coatings Market
Coatings
Global Coil Coatings Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
Coating Thickness Gauge Market
Coatings
Global Sputter Coater Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Japan Marine Coatings Market
Coatings
Silicate Coatings Market
Coatings
Asia-Pacific Marine Coatings Market
Coatings
Industrial Coatings Market
Coatings
Marine Nanocoating Market
Coatings
North America Polyimide Coating Market
Coatings
Canada Floor Coatings Market
Coatings
North America Anti-Friction Coatings Market