
 Italy Industrial Wood Coatings Market | 2026-2036
Italy Industrial Wood Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Industrial Wood Coatings Market Insights
Italy's northern manufacturing corridor is reconfiguring supply chains around stricter environmental protocols and just-in-time furniture production. Axalta Coating Systems leverages its automotive heritage to transfer high-durability resin technology into industrial wood applications. Sirca SpA anchors domestic formulation expertise through deep ties with Brianza's furniture district. Akzo Nobel competes on waterborne portfolio breadth, positioning its Italian operations as a southern European hub for compliant coating systems.
Italy industrial wood coatings encompass protective and decorative film-forming materials applied to timber substrates in factory settings, typically comprising binders, pigments, solvents or water carriers, and functional additives that cure through oxidative, thermal, or ultraviolet mechanisms to yield hardness, gloss retention, and chemical resistance. Waterborne formulations are gaining share as furniture exporters face downstream sustainability audits, while UV-cured systems dominate high-throughput flooring lines where seconds-per-board throughput governs capital returns. Solventborne technology retains pockets of demand in musical instrument finishing where traditional lacquer aesthetics command premium positioning.
Italy's Ministry of Ecological Transition enforces National Recovery and Resilience Plan targets that channel industrial investment toward reduced-emission processes, while REACH registration requirements filter imported raw materials through toxicity documentation thresholds. BIS-equivalent conformity assessments under Italy's UNI standards framework shape product labeling and performance claims for coatings sold into public building contracts. Stakeholders must weigh whether to absorb reformulation costs for EU Green Deal alignment or cede share to competitors already certifying cradle-to-gate carbon footprints.
Market Dynamics
Italy's industrial wood coatings sector faces a structural pivot as waterborne formulation mandates from the EU Green Deal compress solventborne margins while Brianza furniture exporters demand faster-curing systems to match just-in-time production schedules.
Growth Catalysts
- REACH Phase-Out Deadlines:Restrictions on high-VOC solvent carriers are redirecting R&D investment toward compliant waterborne alternatives, creating first-mover advantages for domestic formulators.
- Brianza Furniture Cluster Expansion:Concentrated demand from Lombardy's high-end residential and contract furniture manufacturers sustains premium coating volumes despite broader industrial softness.
- UV-Cured Flooring Lines:Seconds-per-board throughput requirements in Verona's engineered wood flooring plants are accelerating capital deployment toward electron-beam and ultraviolet curing infrastructure.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic and polyurethane resin costs fluctuate with naphtha pricing, compressing formulation margins for mid-tier producers serving price-sensitive kitchen cabinet manufacturers.
- Import Concentration in Photoinitiators:UV-cured system growth depends on photoinitiator supply concentrated among German and Chinese specialty chemical producers, exposing formulators to tariff and logistics risk.
- Waterborne Performance Gap:Musical instrument and antique reproduction finishers reject waterborne alternatives due to inferior depth-of-image and repairability versus traditional nitrocellulose lacquers.
Strategic Opportunities
- Southern Italy Industrialization:Puglia and Sicily furniture manufacturing parks remain underpenetrated by industrial coating distributors, offering whitespace for localized service depots.
- EU Taxonomy Alignment:Green financing eligibility under the EU Green Deal's technical screening criteria rewards coatings producers certifying cradle-to-gate carbon footprints, unlocking preferential lending for facility upgrades.
- Bio-Based Binder Convergence:Integration of lignin-derived and vegetable oil polyurethane dispersions with existing waterborne infrastructure allows premium positioning without capital-intensive line replacement.
Industry Challenges
- Formulation Chemist Scarcity:Italy's technical universities produce insufficient polymer and coatings chemistry graduates, forcing employers to recruit from Germany's FH Aachen and Switzerland's ETH Zürich pipelines.
- Multi-Site Certification Burden:UNI EN ISO 9001 and FSC chain-of-custody audits require dedicated compliance staff at each Brianza and Veneto production facility, elevating overhead for sub-scale operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Industrial Wood Coatings Market |
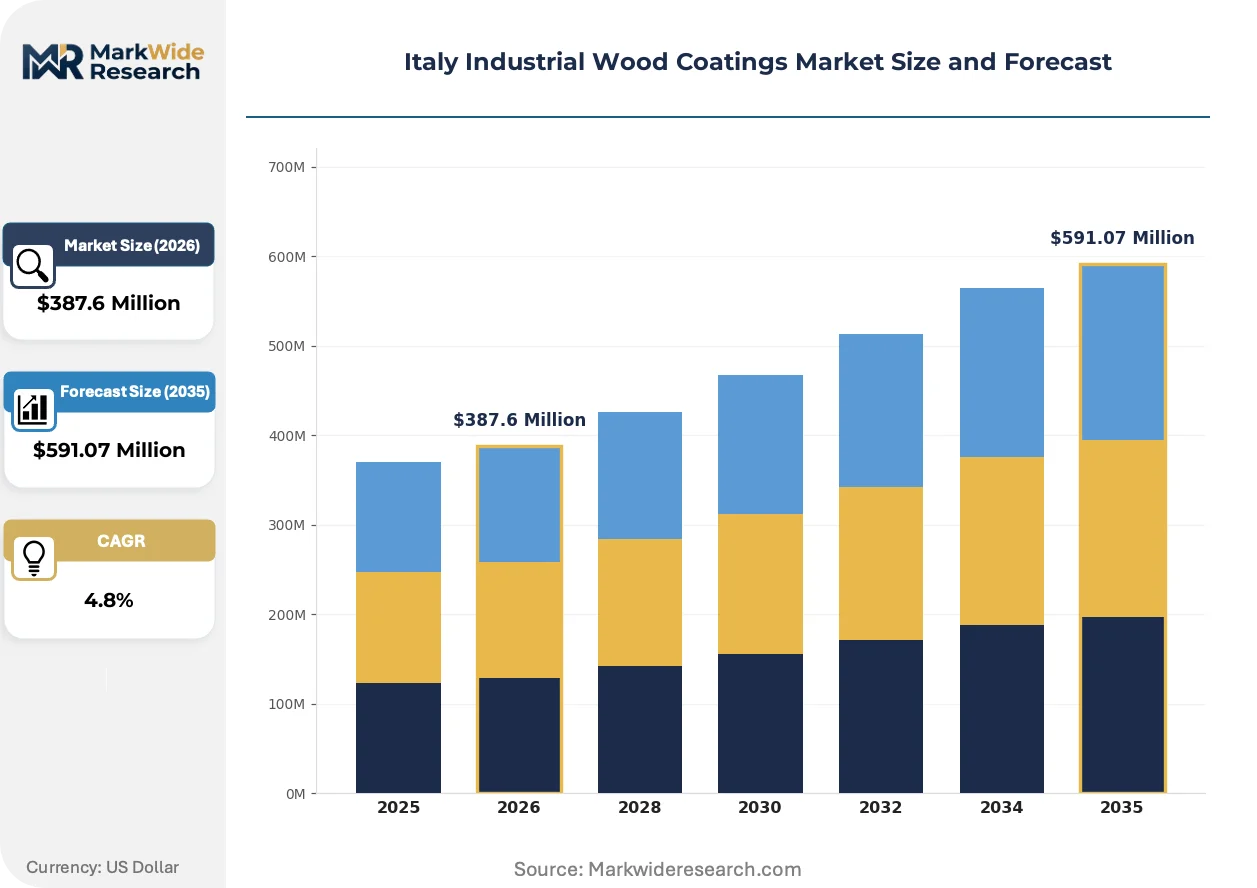
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne, Solventborne, UV-Cured, Powder Coating Application: Furniture, Flooring, Cabinetry, Musical Instruments End User: Manufacturers, Distributors, Retailers, Contractors Technology: Coating Techniques, Drying Methods, Application Equipment, Surface Preparation |
| Companies Covered | Axalta Coating Systems, Jotun, PPG Industries, Sirca SpA, Astra Vernici Srl, Akzo Nobel, RPM International, Weilburger Coatings, The Sherwin-Williams Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Industrial Wood Coatings Market Trends and Innovations
Formulation priorities across Italy's northern furniture belt are converging on speed-to-market and environmental compliance, compressing development cycles while expanding performance verification requirements.
Hybrid UV-waterborne systems are collapsing the historical trade-off between throughput and emissions compliance. Verona flooring manufacturers deploy these dual-cure platforms to achieve sub-30-second board processing while satisfying downstream retailer sustainability audits. The technology is collapsing capital planning horizons as producers defer full electron-beam line investments in favor of retrofit-compatible hybrid units.
Italy's National Recovery and Resilience Plan channels industrial transition funding toward reduced-emission manufacturing processes, with coating system upgrades eligible for subsidized financing through Invitalia. Furniture exporters in Brianza face downstream pressure from French and German retail buyers requiring EU Taxonomy-aligned supply chain documentation, accelerating waterborne adoption in previously solvent-dependent finishing shops.
Specification authority is migrating from production managers to procurement departments armed with lifecycle assessment tools and consolidated supplier scorecards. Large kitchen cabinet manufacturers in the Veneto region now bundle coating procurement with hardware and panel sourcing, displacing independent distributor relationships that dominated the 2010s. This concentration is most visible among contract furniture exporters serving Northern European markets, where buyer-side sustainability teams veto non-compliant finish specifications.
Italy Industrial Wood Coatings Market Segmentation
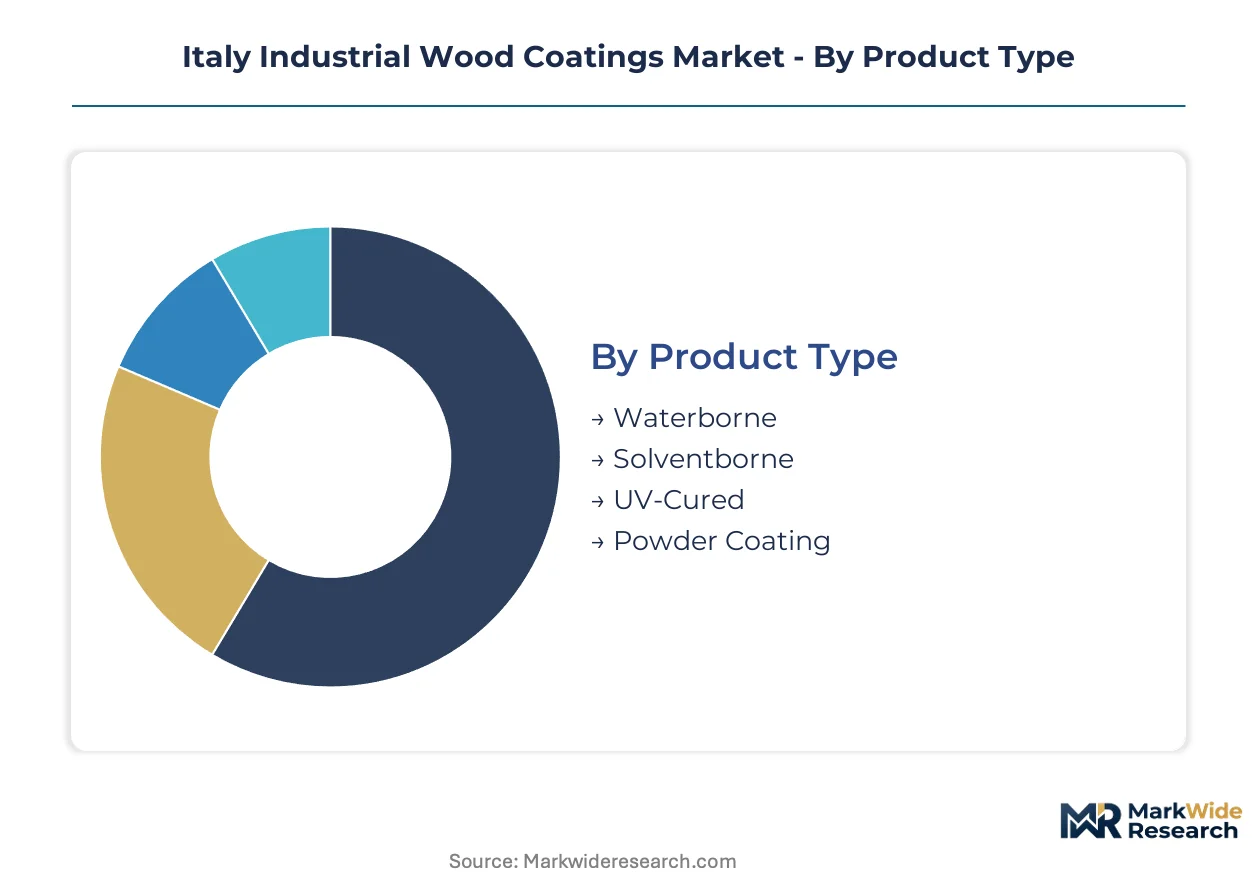
Italy's industrial wood coatings market fragments across formulation chemistry, end-use application, and supply chain position. Each dimension reveals distinct margin structures and regulatory exposure that shape competitive strategy.
Product Type:
Formulation chemistry spans aqueous dispersions, solvent carriers, radiation-cure systems, and thermoset powders, each commanding different capital requirements and compliance burdens.
- Waterborne:Acrylic and polyurethane dispersions in water carriers cure through oxidative or forced-air drying. Brianza furniture exporters facing French and German retailer sustainability audits are converting finishing lines to these systems despite slower dry times than solvent alternatives.
- Solventborne:Nitrocellulose, acid-curing, and polyurethane lacquers in hydrocarbon or oxygenated solvents retain dominance in musical instrument finishing and antique reproduction where depth-of-image and repairability prove non-negotiable.
- UV-Cured:Photoinitiator-acrylate formulations polymerize under ultraviolet lamps in sub-30-second cycles. Verona engineered flooring plants deploy these for seconds-per-board throughput.
- Powder Coating:Thermoset epoxy and polyester resins applied electrostatically to conductive primed wood. Kitchen cabinet manufacturers in Veneto experiment with these zero-VOC systems for flat panel surfaces.
The dominant share belongs to Waterborne, while UV-Cured is closing the gap fastest.
Application:
End-use segments diverge sharply in performance specifications, batch sizes, and aesthetic requirements.
- Furniture:Residential and contract seating, tables, and case goods require scratch-resistant topcoats with gloss retention. Lombardy's Brianza district concentrates demand for high-end residential finishes.
- Flooring:Engineered wood and parquet surfaces demand extreme abrasion resistance and chemical tolerance. Verona's industrial flooring belt specifies UV-cured systems exclusively.
- Cabinetry:Kitchen and bath cabinets need moisture-resistant film builds with consistent color matching. Veneto manufacturers bundle coating procurement with hardware sourcing.
- Musical Instruments:Violins, guitars, and pianos require traditional nitrocellulose lacquer aesthetics. Cremona's luthier community resists waterborne conversion.
Furniture captures the largest volume, though Flooring demonstrates the steepest expansion trajectory as engineered wood exports accelerate.
End User:
Supply chain position determines specification authority and technical service intensity.
- Manufacturers:Industrial furniture, flooring, and cabinet producers operate captive finishing departments. Large Brianza exporters now centralize procurement decisions with sustainability teams.
- Distributors:Regional coating distributors maintain local inventory and color-matching services. Independent distributors face displacement as manufacturers consolidate supplier relationships.
- Retailers:Big-box and specialty furniture retailers exert downstream pressure through supplier scorecards. French and German buyers mandate EU Taxonomy-aligned documentation.
- Contractors:On-site finishers and refinishers purchase industrial coatings for commercial projects. This channel remains fragmented across Italy's construction sector.
Manufacturers retain specification control, while Retailers are gaining influence fastest through consolidated procurement and sustainability mandates.
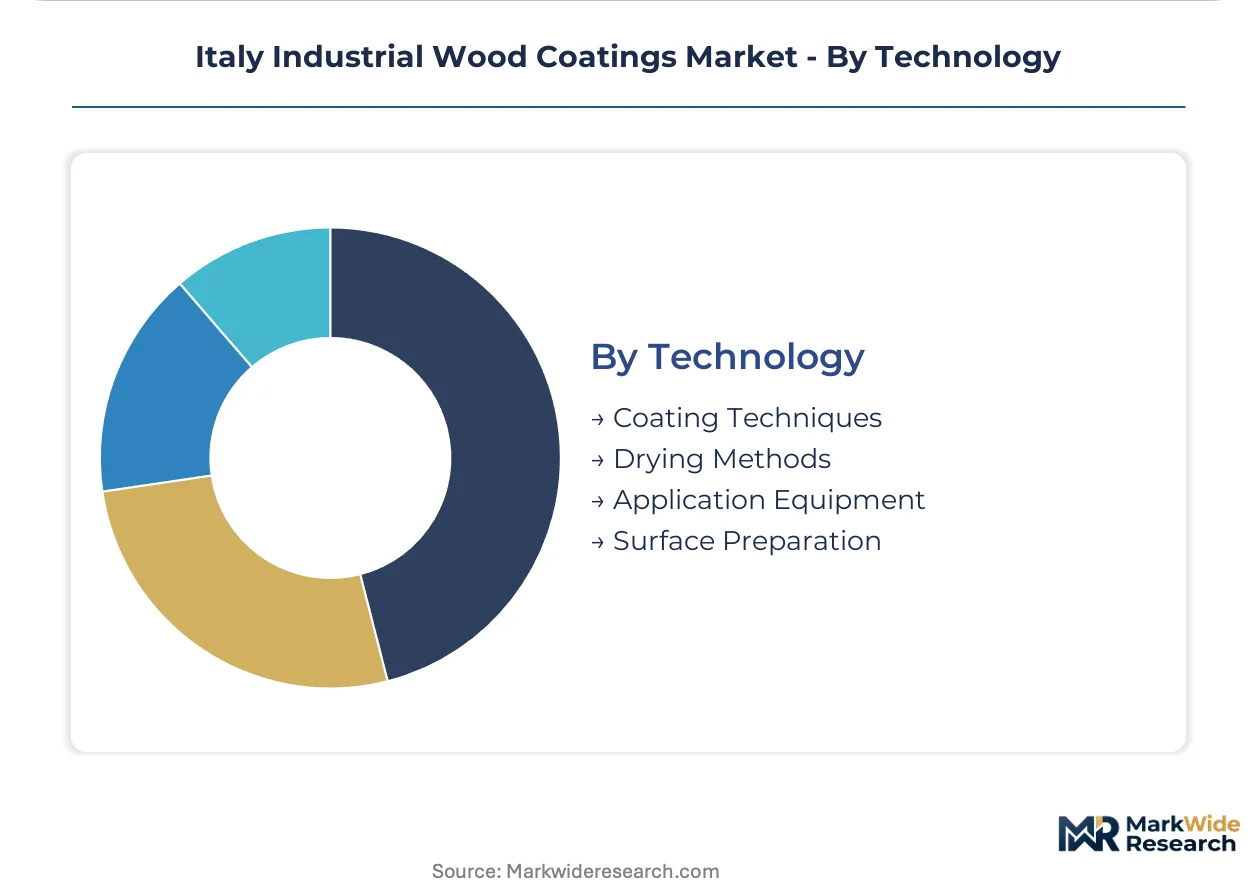
Technology:
Process technology spans application methods, curing systems, substrate preparation, and equipment platforms.
- Coating Techniques:Spray, curtain coat, roll coat, and vacuum coating methods match substrate geometry and throughput requirements. Flat panels favor curtain coating for film uniformity.
- Drying Methods:Convection ovens, infrared radiation, ultraviolet lamps, and electron beam systems govern cycle time and energy consumption. Hybrid UV-waterborne platforms are collapsing the throughput-versus-emissions trade-off.
- Application Equipment:Automated spray robots, reciprocators, and manual spray guns deliver material with varying transfer efficiency. High-volume flooring lines deploy fully automated systems.
- Surface Preparation:Sanding, cleaning, and priming operations determine adhesion and final appearance. Brianza's high-end furniture sector maintains manual sanding for premium positioning.
Coating Techniques anchor the installed base, though Drying Methods are attracting capital fastest as energy costs and throughput pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's industrial wood coatings supply concentrates in the northern manufacturing corridor, where Lombardy and Veneto host the densest clusters of furniture and flooring production. Formulators align distribution networks with these industrial geographies.
Lombardy
Brianza's high-end residential furniture manufacturers drive premium waterborne coating volumes as French and German retailers mandate EU Taxonomy-aligned documentation. Italy's Ministry of Ecological Transition channels National Recovery and Resilience Plan subsidies toward reduced-emission finishing processes. The province of Monza and Brianza anchors captive finishing departments for export-oriented seating and case goods producers.
Veneto
Engineered wood flooring plants around Verona specify UV-cured systems exclusively for seconds-per-board throughput requirements. REACH Phase-Out Deadlines on high-VOC carriers redirect capital toward hybrid UV-waterborne retrofit platforms. The industrial belt between Verona and Vicenza concentrates electron-beam curing infrastructure deployment.
Piedmont
Turin's automotive heritage spills into industrial coatings expertise, with formulators leveraging polymer chemistry capabilities for wood applications. EU Green Deal technical screening criteria shape green financing eligibility for facility upgrades. The metropolitan area hosts specialty resin development operations serving northern Italian furniture clusters.
Emilia-Romagna
Kitchen cabinet manufacturers around Modena and Bologna consolidate coating procurement with hardware and panel sourcing, displacing independent distributors. BIS-equivalent UNI standards conformity assessments govern product labeling for public building contracts. The region's packaging machinery ecosystem supports automated spray line integration.
Tuscany
Antique reproduction and musical instrument finishers in Florence and Pisa resist waterborne conversion, preserving solventborne nitrocellulose lacquer demand. Traditional aesthetics command premium positioning in export markets. The province of Cremona's luthier community maintains heritage finishing techniques despite regulatory pressure.
Italy Industrial Wood Coatings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying resin and photoinitiator inputs. Italy's market structures around three tiers: multinational coating conglomerates with southern European hub operations, domestic formulators embedded in regional furniture districts, and specialty distributors facing procurement consolidation. Archetypes include automotive-heritage technology transferors, Brianza-anchored local formulators, and waterborne portfolio aggregators. Competitive moves center on hybrid curing technology licensing and backward integration into bio-based binder supply.
Among the named players, Axalta Coating Systems exemplifies automotive-heritage technology transfer into industrial wood applications. Sirca SpA occupies a position as a domestic formulator anchored in the Brianza furniture district. Akzo Nobel represents the multinational waterborne portfolio breadth archetype, with Italian operations positioned as a southern European compliance hub.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Jotun |
| PPG Industries |
| Sirca SpA |
| Astra Vernici Srl |
| Akzo Nobel |
| RPM International |
| Weilburger Coatings |
| The Sherwin-Williams Company |
| Others |
Pricing and Supply Chain Analysis
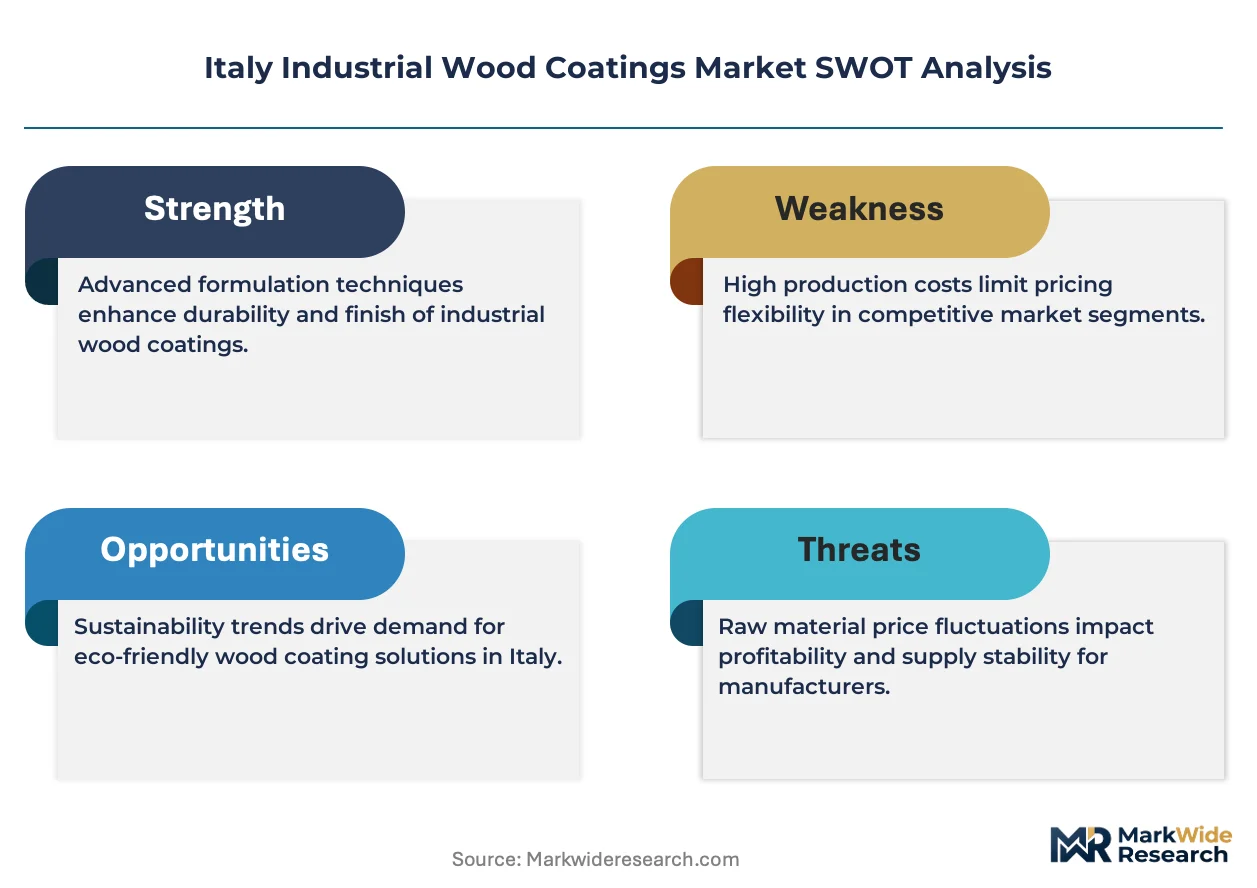
Photoinitiator supply concentrated among German and Chinese specialty chemical producers anchors margin pools at the formulation tier, where Italian wood coating manufacturers absorb volatility through long-term offtake contracts or pass-through clauses to Brianza furniture exporters.
Pricing Analysis
REACH Phase-Out Deadlines dictate the pricing tier structure across Italy's industrial wood coatings market. Three-tier pricing structure across premium, standard, and economy levels separates EU Taxonomy-certified waterborne systems from compliant mid-tier hybrids and legacy solventborne formulations. Price differentiation rests on certification grade and volume scale, with large kitchen cabinet manufacturers in Veneto extracting scale discounts unavailable to Cremona luthiers. Cost compression in mid-tier waterborne acrylics is intensifying because petrochemical feedstock volatility feeds directly into resin costs. Musical instrument finishers exhibit least price sensitivity, preserving premium positioning for traditional nitrocellulose lacquers despite regulatory pressure.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now characterize supplier-finance relationships across the northern Italian furniture belt, squeezing working capital for sub-scale formulators. Raw material flows draw from Germany for photoinitiators, China for specialty acrylates, and domestic Piedmont resin operations for polyurethane dispersions. Supply chain risk centers on single-source vulnerability in photoinitiator procurement, where tariff exposure on Chinese imports compounds logistics fragility. Distribution runs through consolidated manufacturer procurement departments in Brianza and Verona, displacing the independent distributor networks that dominated prior decades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and color-matching subscriptions now expand faster than base coating volumes, transforming Italy's industrial wood coatings market into a service-attach opportunity where formulation expertise locks in multi-year supplier relationships.
For Market Incumbents: Pre-empt displacement by procurement consolidation through captive technical service teams embedded in Brianza furniture plants. Backward integration into bio-based binder supply secures margin control as EU Green Deal technical screening criteria harden. Defend against hybrid UV-waterborne platform licensing from automotive-heritage competitors by accelerating in-house electron-beam curing R&D. For New Entrants and Emerging Players: Southern Italy furniture manufacturing parks in Puglia and Sicily represent the most penetrable entry point, with localized service depots capturing whitespace unaddressed by northern formulators. Target mid-tier kitchen cabinet manufacturers in Emilia-Romagna bundling coating procurement with hardware sourcing. A go-to-market angle anchored in EU Taxonomy-aligned documentation compliance unlocks access to green financing-eligible facility upgrades. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulators holding Brianza distributor relationships but lacking waterborne portfolio breadth. Five-to-ten year viability hinges on REACH compliance completion and hybrid curing technology deployment. The signal to watch is consolidation in photoinitiator supply, where German specialty chemical producers may restrict Italian formulator access through preferential allocation to captive customers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Binders | Lignin-derived polyurethane dispersions from Piedmont agricultural waste secure EU Green Deal alignment without capital-intensive line replacement. |
| Hybrid UV-Waterborne Platform Licensing | Electron-beam curing technology transfer from Turin's automotive coating heritage collapses seconds-per-board throughput for Verona flooring plants. |
| EU Taxonomy Certification Program | Cradle-to-gate carbon footprint documentation unlocks Invitalia subsidized financing for Brianza furniture exporter facility upgrades. |
| Southern Italy Distribution Expansion | Localized service depots in Puglia and Sicily capture underpenetrated furniture manufacturing park demand outside northern industrial corridors. |
| Technical Service Contract Bundling | Embedded color-matching and application engineering teams lock in multi-year relationships with procurement-consolidated kitchen cabinet manufacturers. |
Research Methodology
The analysis maps waterborne, solventborne, UV-cured, and powder coating sub-sectors, each validated through plant managers at Brianza furniture manufacturers, procurement leads at Verona flooring plants, distribution channel partners in Emilia-Romagna, and technical R&D directors at Piedmont resin operations. Secondary validation drew from REACH registration databases, UNI standards conformity assessments, customs/trade data on photoinitiator imports, and Invitalia subsidy disbursement records. Bottom-up coating volume estimates triangulated against top-down furniture production statistics from Italy's National Institute of Statistics.
Assumptions held fixed across the modeling period include REACH Phase-Out Deadlines enforcement timelines, EU Green Deal technical screening criteria stability, and Invitalia subsidy eligibility thresholds. Segmentation dimensions modeled span formulation chemistry, end-use application, curing technology, and regional production hub. CAGRs derived from regression analysis against historical furniture export volumes and flooring line capacity expansion announcements. Industry-specific inputs incorporated photoinitiator supply constraints and hybrid curing technology adoption curves.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial production indices, naphtha pricing volatility, or German-Chinese trade flows would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Nigeria Paint and Protective Coatings Market
Paints & Coatings
Epoxy Paint Thinner Market
Paints & Coatings
Road Marking Paint Market
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Floor Paints Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Cement Paints Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Automotive Paints Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Automotive OEM Coatings Market