
 Global Fireproofing Coatings for Wood Market | 2026-2036
Global Fireproofing Coatings for Wood Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fireproofing Coatings for Wood Market Foresight
Specialty distributor networks for fireproofing coatings is narrowing as direct procurement from manufacturers gains share among large construction contractors. Teknos Group leverages its Nordic manufacturing base to sustain supply chain proximity across European mass timber projects. Sika AG anchors its position through integrated adhesive and coating systems that bundle fire performance with structural bonding. AkzoNobel competes on architectural specification relationships, while PPG Industries differentiates through color-matched intumescent topcoats for visible wood elements.
Fireproofing coatings for wood comprise reactive formulations that expand under heat exposure to form insulating char layers, with intumescent systems typically achieving thirty to sixty minutes of fire resistance rating on structural timber. These products protect load-bearing wood members in buildings where exposed aesthetics preclude conventional gypsum encapsulation. Intumescent coatings command the dominant value share due to their thin-film application and architectural compatibility, while cementitious alternatives occupy price-sensitive industrial segments. Residential structures represent the fastest-growing application dimension as single-family mass timber construction scales in North America and Central Europe.
Regulatory frameworks from the EU Construction Products Regulation, REACH chemical compliance, and US ICC-ES evaluation reports collectively determine market access and formulation constraints for wood fireproofing suppliers. ECHA scrutiny of halogenated flame retardants is forcing reformulation toward phosphorus-nitrogen intumescent chemistry. Stakeholders must monitor evolving reaction-to-fire test protocols as jurisdictions adopt performance-based building codes that reward demonstrated char containment over prescriptive coating thickness requirements.
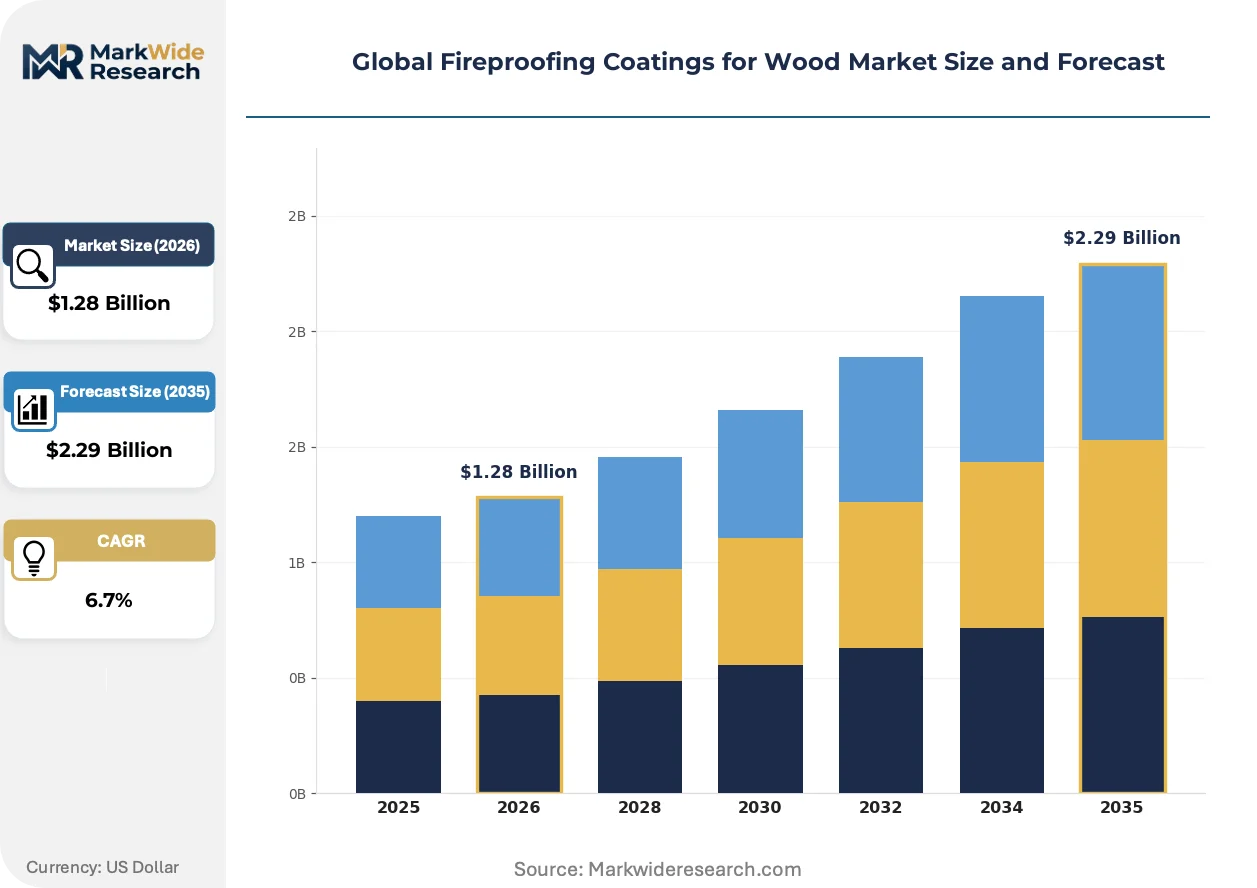
Market Dynamics
Mass timber construction codes are forcing a structural pivot toward thin-film intumescent systems as architects and engineers seek fire-rated exposed wood aesthetics without gypsum concealment.
Growth Catalysts
- EU Construction Products Regulation:Updated reaction-to-fire classification standards mandate enhanced certification for structural wood in commercial buildings above three stories.
- Phosphorus-nitrogen chemistry:Reformulation away from halogenated flame retardants under ECHA scrutiny is opening new formulation pathways with improved environmental profiles.
- Single-family mass timber:Residential construction in Germany and Austria is absorbing fireproofing coatings at accelerating rates as prefabrication scales.
Market Restraints
- Petrochemical feedstock volatility:Intumescent binder resins and phosphorus derivatives face input cost swings that compress coating margins unpredictably.
- Nordic supply concentration:Teknos Group and regional specialty manufacturers anchor production in Scandinavia, creating geographic vulnerability for southern European projects.
- Cementitious substitution:Industrial warehouse and non-aesthetic applications default to lower-cost spray-applied cementitious fireproofing, capping intumescent pricing power.
Strategic Opportunities
- US ICC-ES evaluation pathway:Alternative compliance routes for European formulations to access North American mass timber projects without full ASTM E119 retesting.
- Color-matched architectural specification:Visible wood elements in hospitality and cultural buildings create demand for tint-stable intumescent topcoats with design-grade finishes.
- Direct procurement channels:Large construction contractors bypassing distributor networks opens margin capture for manufacturers with logistics scale.
Industry Challenges
- Char containment certification:Performance-based building codes demand demonstrated fire resistance through full-scale furnace testing, extending product validation timelines.
- Application technician scarcity:Thin-film intumescent systems require spray-applied expertise distinct from conventional coatings, constraining installation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fireproofing Coatings for Wood Market |
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.29 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intumescent Coatings, Cementitious Coatings, Silicone-Based Coatings, Acrylic Coatings, Polyurethane Coatings Application: Residential Structures, Commercial Complexes, Institutional Buildings, Cultural Heritage Sites, Educational Facilities End User: Construction Contractors, Furniture Manufacturers, Interior Decorators, Shipbuilders, Woodworking Artisans Form: Liquid, Spray, Mastic, Powder, Gel |
| Companies Covered | The Sherwin-Williams Company, Teknos Group, Sika AG, Nordtreat, Lonza, Rudolf Hensel GmbH, BASF, AkzoNobel, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fireproofing Coatings for Wood Market Shifts & Advancements
Formulation chemistry and procurement architecture are simultaneously evolving as regulatory pressure and construction methodology reshape how fire protection integrates with exposed timber design.
Water-borne intumescent systems with expanded graphite and melamine phosphate cores are achieving Class B-s1,d0 ratings on CLT and glulam substrates. German and Austrian mass timber contractors specify these formulations for interior commercial applications. Solvent-borne legacy systems are rendering obsolete in occupied-space specifications where VOC emissions face heightened scrutiny.
REACH authorization procedures for halogenated flame retardants are forcing systematic reformulation across European coating portfolios. The restriction timeline compresses R&D cycles for suppliers serving EU member states. Phosphorus-nitrogen intumescent platforms are capturing specification share as ECHA substance evaluation advances.
Specification authority is migrating from general contractors to fire engineering consultants embedded in early design phases. Mass timber projects in France and Belgium now engage fire performance specialists before structural procurement. This front-loaded engagement compresss traditional coating selection windows and rewards manufacturers with established technical documentation libraries.
Global Fireproofing Coatings for Wood Market Segmentation
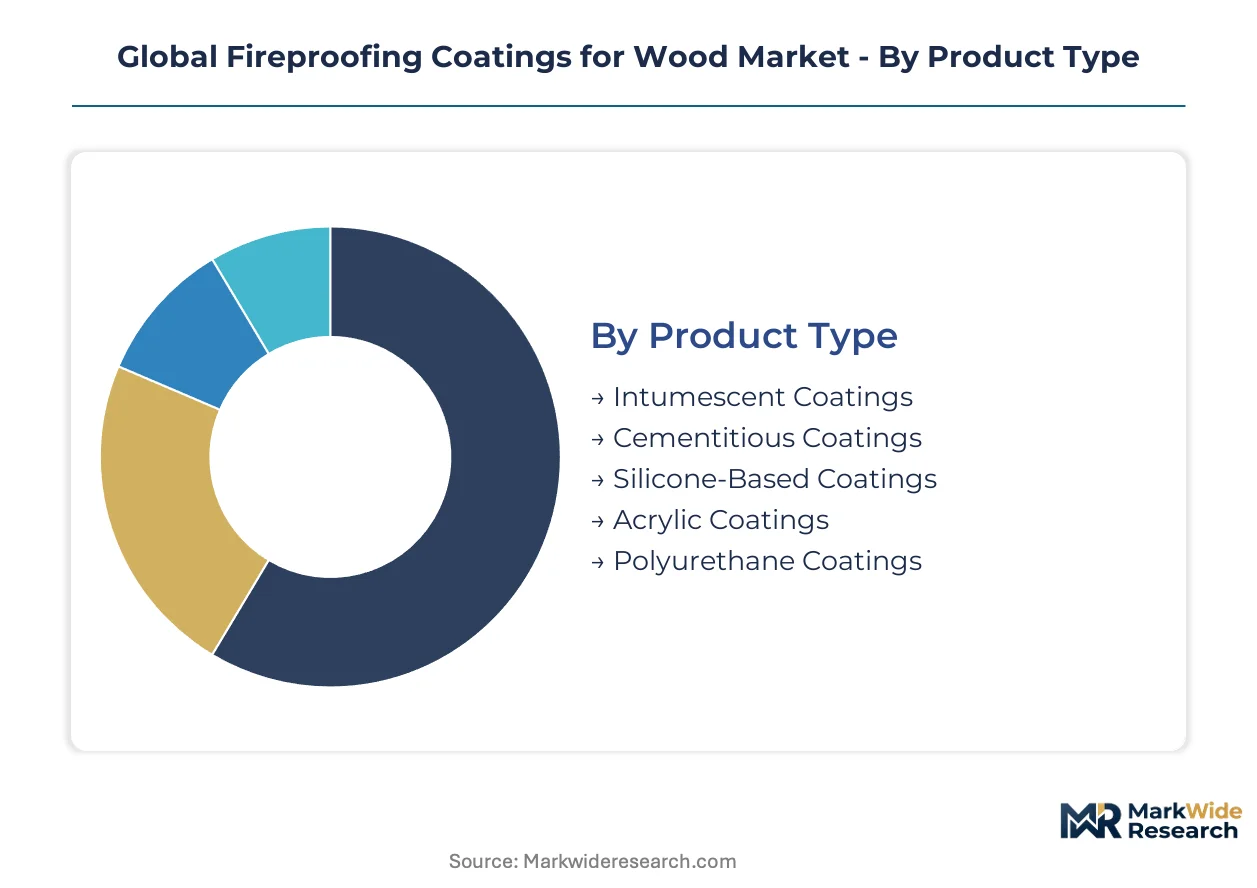
Fireproofing coatings for wood demand heterogeneous technical support across product categories, with specification complexity varying sharply between intumescent formulations and cementitious alternatives. Application method and substrate compatibility drive distinct service intensity requirements that reshape manufacturer-customer relationships throughout the value chain.
Product Type:
After-sales service intensity diverges dramatically across chemistry platforms, with intumescent systems demanding sustained technical consultation for spray application certification and performance validation.
- Intumescent Coatings:Reactive formulations containing ammonium polyphosphate and pentaerythritol expand 50-100x under heat to form insulating char barriers. German and Austrian mass timber contractors specify these systems for exposed CLT ceilings in commercial atriums, driven by EU Construction Products Regulation mandates for structures above three stories.
- Cementitious Coatings:Spray-applied mineral wool and Portland cement blends deliver fire resistance through thermal mass rather than chemical reaction. Industrial warehouse developers in the US Midwest default to these lower-cost alternatives where architectural concealment is acceptable, constraining pricing power for premium thin-film systems.
- Silicone-Based Coatings:Flexible elastomeric formulations maintain adhesion through wood's dimensional movement cycles.
- Acrylic Coatings:Water-borne systems with limited intumescent capability serve decorative fire-retardant primers in residential trim applications.
- Polyurethane Coatings:Two-component systems offering moisture resistance for exterior timber exposed to weathering cycles.
Intumescent coatings hold the largest share; momentum sits with phosphorus-nitrogen formulations displacing halogenated chemistry under ECHA pressure.
Application:
Cost tier stratification separates specification-grade commercial projects from price-sensitive residential deployments, with institutional procurement favoring bundled coating-adhesive systems.
- Residential Structures:Single-family mass timber construction in Germany and Austria absorbs fireproofing coatings at accelerating rates as prefabricated wall panels scale. REACH-compliant water-borne intumescents dominate this segment as VOC restrictions tighten in occupied-space specifications.
- Commercial Complexes:Mixed-use developments with exposed timber aesthetics require Class B-s1,d0 ratings achievable only through qualified intumescent application. Fire engineering consultants embedded in early design phases now control specification authority before general contractor involvement.
- Institutional Buildings:Public procurement frameworks in France and Belgium mandate extended warranty terms and documented char containment testing.
- Cultural Heritage Sites:Reversible treatment requirements limit formulation options for historic timber preservation.
- Educational Facilities:School construction codes in multiple jurisdictions impose enhanced reaction-to-fire standards for assembly occupancies.
Commercial complexes command premium pricing tiers; residential structures are expanding most quickly as mass timber prefabrication standardizes.
End User:
Customer type determines procurement channel architecture, with large construction contractors bypassing distributor networks for direct manufacturer relationships.
- Construction Contractors:Tier-one builders with in-house fire protection crews purchase intumescent systems through direct procurement agreements. Application technician scarcity constrains installation capacity for thin-film spray systems across European mass timber projects.
- Furniture Manufacturers:OEM specifications for hospitality and contract seating drive demand for tint-stable topcoats with design-grade finishes.
- Interior Decorators:Specification influence concentrates in high-end residential and boutique commercial renovations.
- Shipbuilders:IMO fire safety codes for passenger vessel interiors create niche demand for marine-certified formulations.
- Woodworking Artisans:Small-batch purchasers rely on distributor technical support for application guidance.
Construction contractors dominate volume absorption; furniture manufacturers represent the steepest expansion trajectory for color-matched architectural specifications.
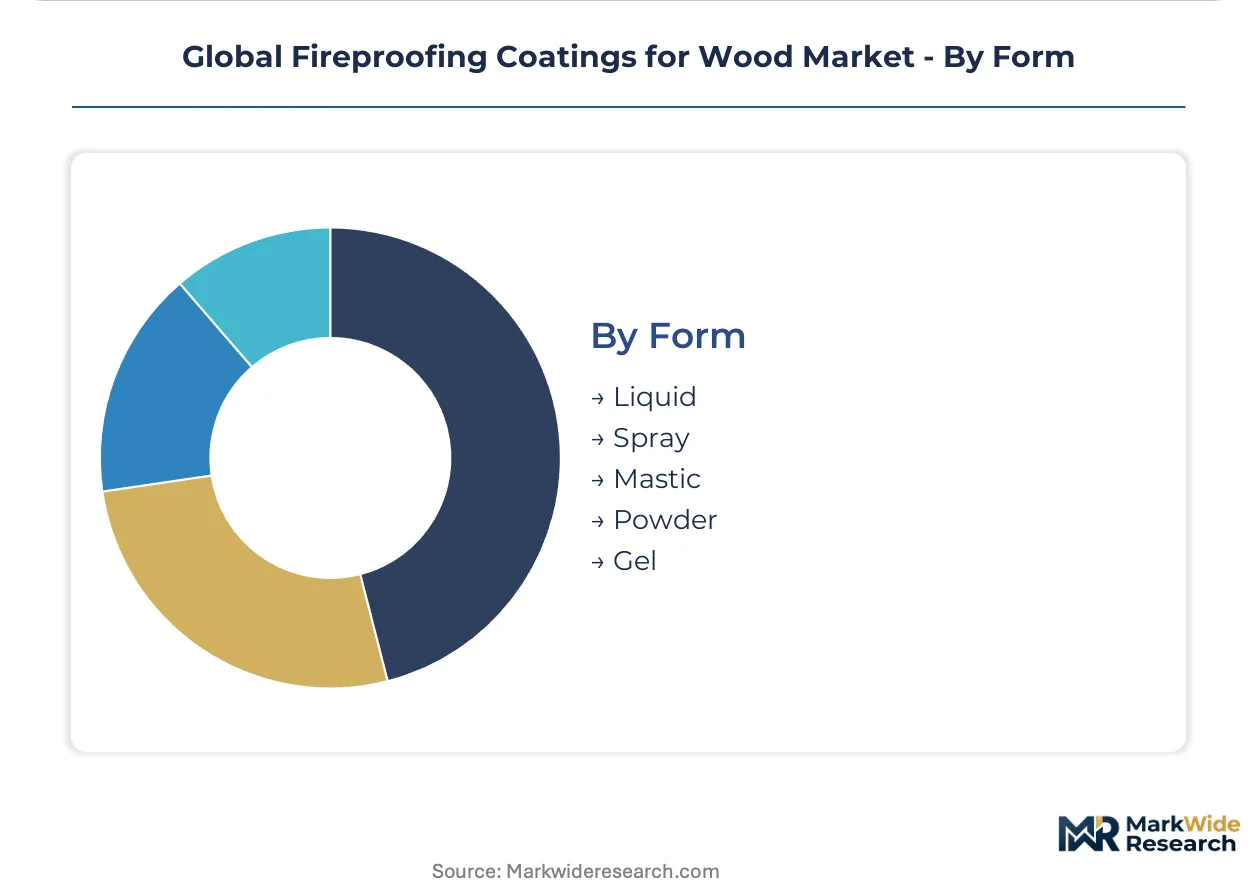
Form:
Supply concentration in liquid and spray formats reflects manufacturing scale economies, while powder and gel alternatives serve specialized repair and touch-up applications.
- Liquid:Factory-applied dip and flow-coat systems serve mass production of engineered wood components. Nordic manufacturers anchor supply for this format, creating geographic vulnerability for southern European projects.
- Spray:Site-applied intumescent systems require calibrated equipment and certified applicators. Full-scale furnace testing for performance-based code compliance extends validation timelines for new spray formulations.
- Mastic:Trowel-grade consistency for beam and column encasement in retrofit applications.
- Powder:Electrostatic application for metal-clad timber composite elements in transportation infrastructure.
- Gel:Thixotropic formulations for overhead surface application without sag or run.
Spray formulations capture the dominant value position; liquid systems gain share through prefabrication integration in Central European mass timber factories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Austria where mass timber building codes mandate enhanced fire performance, while southern European markets absorb coatings through Nordic supply chains at compressed margins.
Germany
Engineered wood building codes now require enhanced fire performance for structures above three stories, driving specification of phosphorus-nitrogen intumescent systems. The EU Construction Products Regulation mandates updated reaction-to-fire classification standards across commercial construction. Bavaria and Baden-Württemberg host prefabrication clusters where factory-applied liquid intumescents integrate directly into CLT panel production lines.
United States
Single-family mass timber construction scales rapidly in the Pacific Northwest and Mountain West regions as ICC-ES evaluation reports streamline code compliance. The International Code Council maintains alternative compliance pathways for European formulations seeking ASTM E119 equivalence. Seattle and Portland anchor demand clusters where exposed timber aesthetics in commercial atriums command specification-grade intumescent premiums.
Austria
Prefabricated wall panel manufacturers absorb fireproofing coatings at accelerating rates as residential mass timber standardizes. REACH-compliant water-borne formulations dominate occupied-space specifications under tightening VOC restrictions. Tyrol and Styria concentrate production gravity where Nordic manufacturers maintain supply chain proximity through direct procurement relationships.
France
Public procurement frameworks mandate extended warranty terms and documented char containment testing for institutional buildings. Fire engineering consultants now embed in early design phases, compressing traditional coating selection windows. The Île-de-France region concentrates specification authority where performance-based codes reward demonstrated fire resistance over prescriptive thickness requirements.
United Kingdom
Reaction-to-fire test protocols evolve as jurisdictions adopt performance-based building codes prioritizing char containment verification. London and the Southeast concentrate commercial development with exposed timber aesthetics in mixed-use hospitality projects. Regulatory alignment with EU Construction Products Regulation standards maintains certification continuity post-Brexit.
Global Fireproofing Coatings for Wood Market Competitive Landscape
Integrated coating-adhesive suppliers and standalone intumescent specialists split the market along bundled-system versus specification-purity lines. The vendor base concentrates among Nordic manufacturers with mass timber adjacency and diversified chemical conglomerates with construction portfolio breadth. Two strategic archetypes dominate: manufacturers with captive timber industry relationships, and formulators with architectural specification channel control. Competitive moves center on direct procurement channel capture and phosphorus-nitrogen chemistry transition ahead of ECHA authorization timelines.
Within the Nordic manufacturing tier, Teknos Group and Nordtreat exemplify supply chain proximity strategies anchored in Scandinavian production bases. Sika AG occupies a position among integrated construction chemical suppliers bundling fire performance with structural bonding systems. These three companies represent distinct competitive postures: geographic specialization versus portfolio diversification versus system integration.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Teknos Group |
| Sika AG |
| Nordtreat |
| Lonza |
| Rudolf Hensel GmbH |
| BASF |
| AkzoNobel |
| PPG Industries |
| Others |
Supply & Pricing Matrix
The Baltic Sea container corridor connects Nordic manufacturing bases to Central European mass timber projects, with freight cost volatility amplifying price spreads between phosphorus-nitrogen intumescents and cementitious alternatives while reinforcing supply concentration effects for southern European buyers.
Pricing Analysis
The customization-premium spread separates specification-grade intumescent systems from commodity cementitious alternatives. Project-based pricing dominates commercial complexes where Class B-s1,d0 certification and color-matched architectural finishes command substantial premiums over standard white intumescents. Price differentiation hinges on reaction-to-fire certification tier and volume scale, with large contractors extracting favorable terms through direct procurement agreements. Cost compression in cementitious tiers is intensifying because industrial warehouse developers prioritize thermal mass solutions over thin-film aesthetics. Furniture manufacturers exhibit the least price sensitivity, absorbing tint-stable topcoat premiums for visible wood elements in hospitality fit-outs.
Supply Chain Analysis
Export-control scrutiny of phosphorus derivatives under REACH authorization procedures limits formulation flows from non-EU sources, concentrating supply among Nordic and German manufacturers. Production gravity centers on Finland, Sweden, and Germany, with ammonium polyphosphate and pentaerythritol feedstocks drawing from Belgian and Dutch chemical clusters. Single-source vulnerability characterizes expanded graphite supply, with Chinese processing dominance creating chokepoint exposure. Distribution runs through direct procurement channels for tier-one construction contractors, while specialty distributors serve woodworking artisans and small-batch furniture manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass timber construction codes constitute a high-growth disruption, with EU Construction Products Regulation mandates for structures above three stories creating irreversible specification pull for certified intumescent systems.
For Market Incumbents: Entrench position through captive supply of phosphorus-nitrogen chemistry ahead of ECHA authorization timelines. Backward integration into melamine phosphate feedstocks defends margin structure against petrochemical volatility. Certification investment in ICC-ES evaluation pathways secures North American access before ASTM E119 equivalence disputes harden.
For New Entrants and Emerging Players: Build out application technician training networks to address scarcity constraints in spray-applied intumescent installation. The US Pacific Northwest offers the most penetrable geography, with ICC-ES streamlined compliance and accelerating single-family mass timber construction. A go-to-market angle bundling fire engineering consultation with coating supply captures specification authority migration in early design phases.
For Investors and Strategic Acquirers: Regional formulators with established Nordic timber industry relationships represent the priority acquisition archetype, offering supply chain proximity that strategic buyers cannot replicate organically. Long-term viability rests on phosphorus-nitrogen chemistry transition completion and performance-based code adoption persistence. The signal to watch is ECHA authorization timeline acceleration for halogenated flame retardants, which would compress reformulation windows and strand legacy inventories.
| Strategic Initiative | Industry Significance |
|---|---|
| Phosphorus-Nitrogen Chemistry Transition | ECHA REACH authorization timelines force systematic portfolio reformulation away from halogenated retardants. |
| Direct Procurement Channel Expansion | Large construction contractors bypassing distributors opens margin capture for manufacturers with logistics scale. |
| Application Technician Certification Programs | Spray-applied expertise scarcity constrains installation capacity across European mass timber projects. |
| ICC-ES Evaluation Pathway Investment | Alternative compliance routes streamline North American market access without full ASTM E119 retesting. |
| Color-Matched Architectural Specification Development | Visible wood elements in hospitality and cultural buildings demand tint-stable intumescent topcoats with design-grade finishes. |
Research Methodology
Operator-level perspectives from fire engineering consultants, mass timber contractors, coating applicators, and procurement directors at tier-one construction firms anchored the qualitative base. Secondary validation drew from EU Construction Products Regulation documentation, ECHA substance evaluation reports, ICC-ES evaluation report databases, and customs trade data for phosphorus derivative flows. Bottom-up triangulation across product type, application, and regional demand clusters converged with top-down macroeconomic framing.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning intumescent chemistry platform, substrate compatibility, and end-use vertical. CAGRs derived from installed base expansion rates in mass timber construction and replacement cycle assumptions for existing fire protection systems. Model inputs incorporated regulatory adoption curves for performance-based building codes and ECHA authorization timeline probabilities.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese phosphorus derivative suppliers would shift outcomes. Material shifts in EU reaction-to-fire classification standards or accelerated halogenated flame retardant restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Photocatalytic Coatings Market
Coatings
Asia-Pacific Epoxy Powder Coatings Market
Coatings
Waterborne Automobile Coating Market
Coatings
Global Performance Coating Market
Coatings
Europe Powder Coatings Market
Coatings
Canada Protective Coatings Market
Coatings
North America Thermal Spray Market
Coatings
Plastic-Coated Wires Market
Coatings
Coating Equipment Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
Marking Coatings Market
Coatings
Biopolymer Coatings Market
Coatings
Camouflage Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Vinyl Surface Coatings Market
Coatings
2K Protective Coatings Market