
 Diamond-Like Carbon Coatings Market | 2026-2036
Diamond-Like Carbon Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Diamond-Like Carbon Coatings Market Outlook
Capital-intensity divergence between large-scale PVD platform operators and niche CVD service shops is unwinding competitive stability in the DLC supply base. Oerlikon Management AG leverages its broad industrial coatings portfolio to anchor multi-sector contracts across automotive and medical device accounts. Morgan Advanced Materials plc specializes in ceramic-DLC hybrid formulations that differentiate its offering for extreme-wear aerospace applications. IHI Ionbond AG competes through geographic density in European precision manufacturing corridors.
Diamond-like carbon denotes amorphous carbon films with diamond-phase bonding fractions typically between 40% and 80%, deposited through plasma-enhanced chemical vapor deposition or physical vapor deposition to achieve hardness values exceeding 20 GPa with friction coefficients below 0.1. Thin films command the dominant share of product-type revenue due to their integration into miniaturized electronics and medical instruments, while coatings for heavy-wear automotive powertrain parts represent the fastest-growing application category. Magnetron sputtering leads technology adoption in high-volume manufacturing environments, whereas CVD platforms capture premium positioning for biocompatibility-certified medical device coatings.
FDA device coating standards, EPA emissions rules for deposition processes, and REACH substance restrictions on hexavalent chromium alternatives collectively redirect OEM sourcing toward validated DLC suppliers. The EU Medical Device Regulation tightens post-market surveillance for coated implants, raising compliance costs for smaller coating houses. Stakeholders must monitor evolving biocompatibility certification timelines and deposition equipment energy efficiency thresholds as selection criteria for capacity expansion.
Market Dynamics
REACH substance restrictions on hexavalent chromium alternatives are redirecting OEM sourcing toward validated DLC suppliers across automotive and medical device supply chains, compressing qualification timelines for coating houses.
Growth Catalysts
- Fuel injection system specifications:Automotive manufacturers in Germany specify DLC for direct-injection components to meet Euro 7 emissions thresholds, creating pull-through demand for PVD capacity.
- EU MDR post-market surveillance:The EU Medical Device Regulation mandates enhanced traceability for coated implants, favoring coating service providers with established quality management systems.
- Magnetron sputtering scale-up:High-volume manufacturing environments in Japan are adopting this deposition technology for powertrain component batches exceeding one million units annually.
Market Restraints
- Plasma source supply concentration:Specialized cathode arc and sputtering target production concentrates among a handful of German and Japanese suppliers, exposing coating houses to input bottlenecks.
- Biocompatibility certification friction:FDA 510(k) pathways for coated cardiovascular devices require 18-24 month validation cycles, delaying revenue recognition for medical coating specialists.
- Thermal spray substitution:Detonation-gun tungsten carbide coatings retain cost advantages for heavy-wear mining equipment, limiting DLC penetration in extractive industries.
Strategic Opportunities
- Indian precision manufacturing corridors:Pune and Bangalore clusters are expanding medical device and automotive component output, creating demand for localized coating service infrastructure.
- PLI scheme alignment:India's Production Linked Incentive schemes for advanced automotive components subsidize capital equipment for domestic coating capacity expansion.
- CVD-PVD hybrid platforms:Equipment manufacturers are converging plasma-enhanced CVD flexibility with sputtering throughput, enabling single-platform service across medical and automotive grades.
Industry Challenges
- Plasma physics specialist scarcity:Deposition process engineering requires expertise in vacuum technology and thin-film characterization that outpaces university pipeline output in the United States and Germany.
- Multi-standard compliance burden:Coating houses serving both FDA-regulated medical devices and EPA-permitted automotive lines must maintain parallel quality systems, inflating administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diamond-Like Carbon Coatings Market |
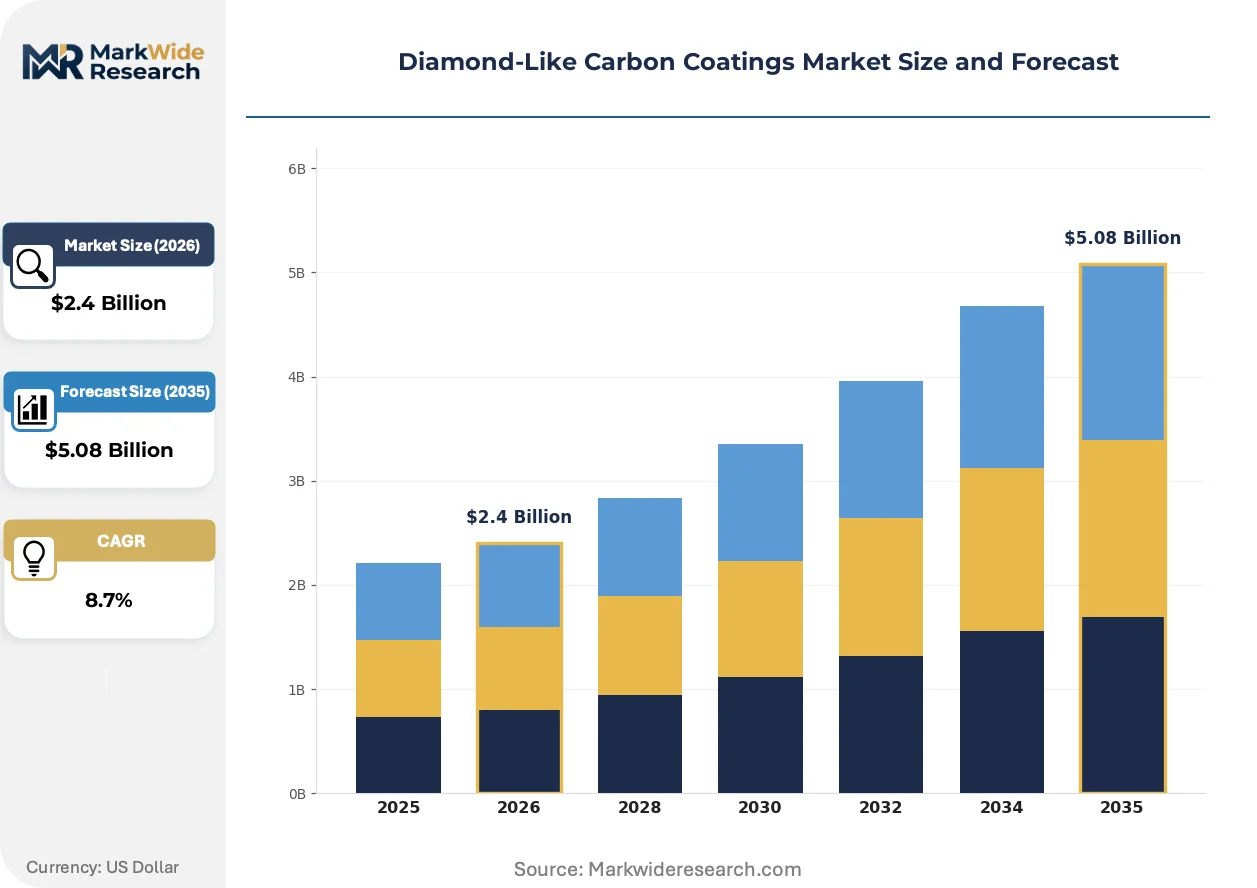
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Films, Coatings, Powders, Detectors End User: Aerospace, Automotive, Electronics, Medical Devices Application: Wear Resistance, Optical Applications, Biocompatibility, Thermal Conductivity Technology: PVD, CVD, Magnetron Sputtering, Laser Ablation |
| Companies Covered | Oerlikon Management AG, IBC Coatings Technologies, Morgan Advanced Materials plc, Renishaw plc, Sumitomo Electric Industries, IHI Ionbond AG, CemeCon, Acree Technologies, Wallwork Heat Treatment Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diamond-Like Carbon Coatings Market Strategic Shifts
Deposition equipment architecture and coating formulation chemistry are undergoing parallel evolution, with equipment scale and certification specificity becoming the primary axes of competitive differentiation.
Multi-layer DLC architectures incorporating silicon or metal-doped interlayers are decomposing the traditional trade-off between hardness and toughness in automotive powertrain coatings. Tier-1 suppliers in Germany and Japan are specifying these formulations for camshaft and piston pin applications where contact stresses exceed 1.5 GPa. The technology is decomposing incumbent single-layer DLC positions in high-load engine components by delivering wear rates below 10^-7 mm³/Nm without spallation.
EPA National Emission Standards for Hazardous Air Pollutants for surface coating operations are tightening permissible volatile organic compound and particulate matter limits from PVD and CVD processes. Coating facilities in Michigan and Ohio face retrofit requirements for abatement equipment or process substitution by 2027. Medical device coating specialists are responding by migrating hydrogenated DLC production to closed-loop plasma systems that eliminate methane venting.
Automotive OEMs are consolidating approved supplier lists for coated fuel system components from regional coating job shops toward vertically integrated Tier-1s with captive PVD lines. Bosch, Denso, and Continental are absorbing coating capacity that previously served fragmented injection component manufacturers. This concentration is most visible in Germany's Baden-Württemberg automotive cluster, where remaining independent coating houses specialize exclusively on aftermarket or racing applications outside OEM supply chains.
Diamond-Like Carbon Coatings Market Segmentation
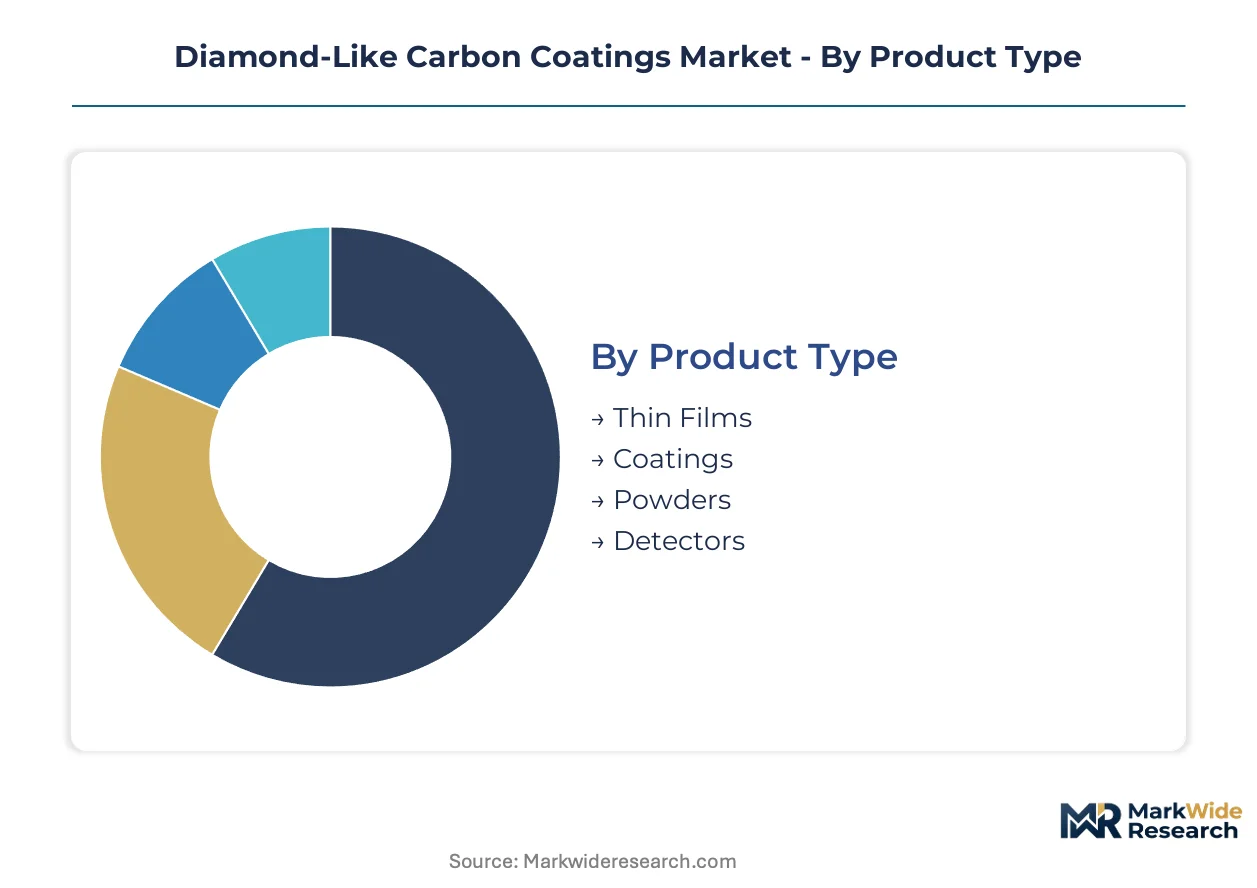
Segmentation in the Diamond-Like Carbon Coatings Market reveals how deposition technology and end-use specifications fragment demand across distinct supply channels. Each category channels different margin profiles and qualification barriers.
Product Type:
Thin films and coatings dominate commercial throughput, flowing through precision manufacturing job shops and Tier-1 captive lines, while powders and detectors occupy specialized distribution through research equipment vendors.
- Thin Films:Amorphous carbon layers under 5 micrometers thick deliver hardness exceeding 20 GPa with friction coefficients below 0.1. Demand concentrates in German and Japanese medical device clusters where miniaturized instrument manufacturers require ISO 13485-certified deposition services for surgical tools.
- Coatings:Multi-micrometer architectures incorporating silicon or metal-doped interlayers decompose the hardness-toughness trade-off for automotive powertrain components. Camshaft and piston pin applications in Baden-Württemberg specify these formulations where contact stresses exceed 1.5 GPa.
- Powders:Nanocrystalline DLC particulates serve additive manufacturing feedstock and thermal spray applications through industrial materials distributors.
- Detectors:Radiation-hardened DLC windows for particle physics instrumentation move through scientific equipment OEMs and national laboratory procurement channels.
By volume, thin films lead. By growth pace, coatings for heavy-wear automotive parts are climbing the fastest.
End User:
Cost tiers separate these segments: medical and aerospace command premium pricing for certification overhead, while automotive and electronics compete on throughput scale.
- Automotive:Fuel injection systems and valve train components in Germany specify DLC to meet Euro 7 emissions thresholds, pulling PVD capacity expansion. Direct-injection component batches exceed one million units annually in Japanese manufacturing environments.
- Medical Devices:Cardiovascular implants and surgical instruments require FDA 510(k) validation cycles of 18-24 months, compressing supplier margins with extended qualification timelines. EU MDR post-market surveillance mandates favor established quality management systems.
- Aerospace:Ceramic-DLC hybrid formulations differentiate offerings for extreme-wear applications in landing gear and actuation systems.
- Electronics:Miniaturized sensor housings and connector interfaces in consumer devices prioritize thin-film deposition for form factor constraints.
Automotive generates the highest absolute volume. Medical devices sustain the steepest margin premiums.
Application:
Volume concentration varies by functional requirement: wear resistance scales with automotive production, while biocompatibility ties to medical device approval timelines.
- Wear Resistance:Hardness values above 20 GPa with friction coefficients below 0.1 serve powertrain and industrial machinery. German automotive OEMs consolidate approved supplier lists toward vertically integrated Tier-1s with captive PVD lines.
- Biocompatibility:Hydrogenated DLC for cardiovascular and orthopedic implants requires closed-loop plasma systems eliminating methane venting under tightening EPA National Emission Standards.
- Optical Applications:Transparent DLC windows for infrared sensors and laser systems transmit specific wavelengths while protecting underlying substrates.
- Thermal Conductivity:Heat-spreading layers in electronics packaging manage thermal loads in miniaturized power devices.
Wear resistance commands volume leadership. Biocompatibility applications are gaining share fastest through regulatory substitution of hexavalent chromium alternatives.
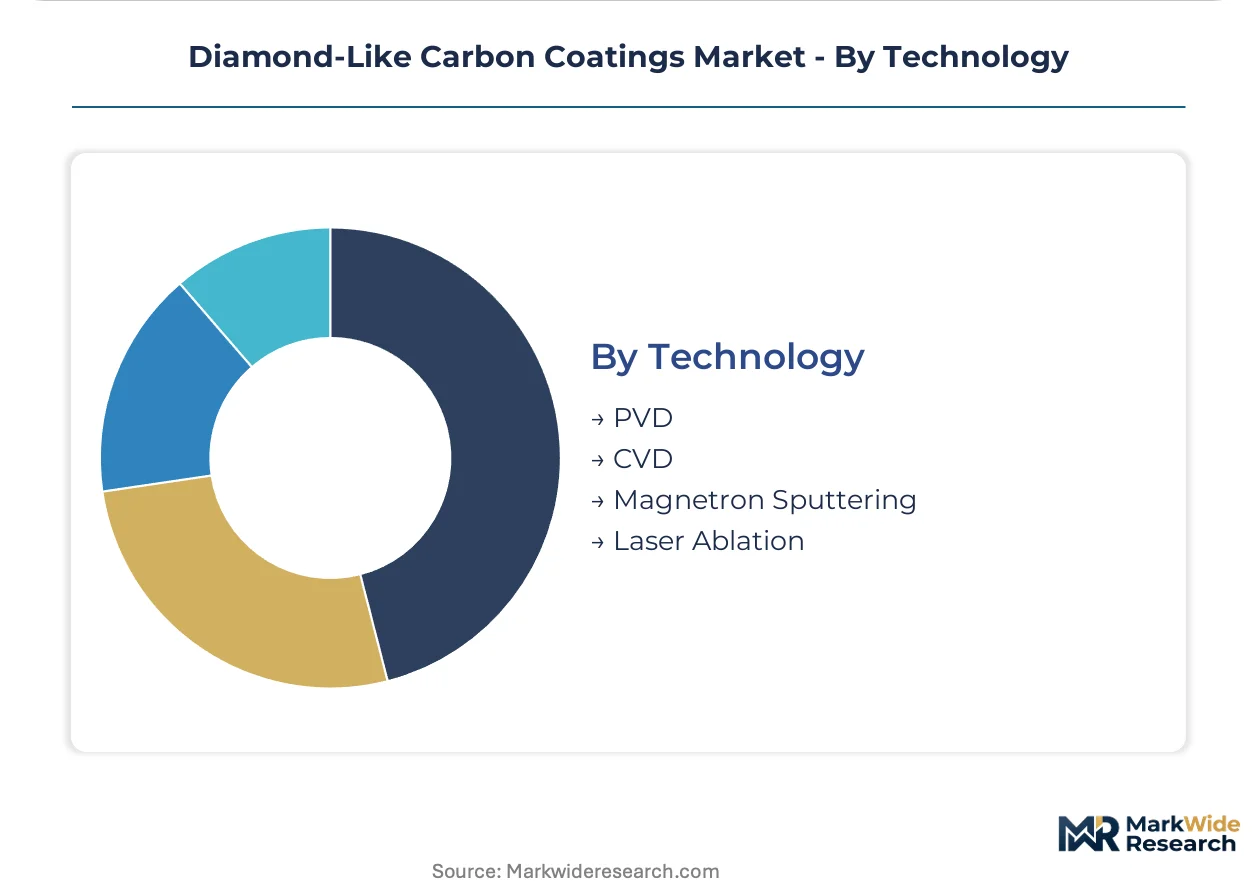
Technology:
Equipment capital intensity and certification specificity fragment the supplier base: magnetron sputtering scales for automotive volume, while CVD captures medical premium positioning.
- Magnetron Sputtering:High-throughput deposition dominates automotive powertrain coating with batch sizes exceeding one million units annually. Japanese manufacturing environments favor this platform for cost efficiency at scale.
- CVD:Plasma-enhanced chemical vapor deposition achieves superior adhesion and conformal coverage for complex medical device geometries. REACH substance restrictions redirect OEM sourcing toward validated European suppliers with established biocompatibility certifications.
- PVD:Physical vapor deposition spans both high-volume automotive and precision medical applications through arc evaporation and sputtering variants.
- Laser Ablation:Pulsed laser deposition serves research applications and specialized optical coatings requiring precise stoichiometric control.
Magnetron sputtering leads by installed base. CVD platforms are expanding most quickly in medical device corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German coating service providers command 15-20% pricing premiums over Indian counterparts for equivalent automotive DLC specifications, reflecting divergent regulatory compliance burdens and certification infrastructure density.
Germany
Baden-Württemberg's automotive cluster drives concentrated demand for fuel injection system coatings meeting Euro 7 emissions thresholds. REACH substance restrictions on hexavalent chromium alternatives redirect OEM sourcing toward validated DLC suppliers with established quality management systems. Stuttgart-based Tier-1 suppliers are consolidating captive PVD capacity for direct-injection component batches.
United States
Michigan and Ohio coating facilities face EPA National Emission Standards retrofit requirements for abatement equipment by 2027. FDA 510(k) validation cycles for cardiovascular device coatings compress supplier margins with 18-24 month qualification timelines. Detroit-area automotive OEMs are absorbing previously independent coating capacity into vertically integrated Tier-1 operations.
Japan
Magnetron sputtering platforms dominate high-volume powertrain manufacturing environments with annual batches exceeding one million units. METI industrial standards shape deposition equipment energy efficiency thresholds for capacity expansion decisions. Nagoya and Tokyo precision manufacturing corridors sustain specialized coating service demand for miniaturized electronics applications.
India
Pune and Bangalore clusters are expanding medical device and automotive component output, creating demand for localized coating service infrastructure. The Production Linked Incentive scheme subsidizes capital equipment for domestic coating capacity expansion. Maharashtra-based precision manufacturers are qualifying DLC suppliers for export-oriented automotive component contracts.
Switzerland
Swissmedic biocompatibility certification requirements favor established European coating houses with ISO 13485-accredited deposition facilities. The country's precision instrument manufacturers specify thin-film DLC for surgical tool applications requiring hardness above 20 GPa. Geneva and Basel medical device hubs sustain premium pricing for certified coating services.
Diamond-Like Carbon Coatings Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with plasma-enhanced CVD specialists capturing medical premium positioning while magnetron sputtering operators dominate automotive volume contracts. The supplier base concentrates around three strategic archetypes: broad industrial coatings portfolios anchoring multi-sector contracts, ceramic-DLC hybrid formulators serving extreme-wear applications, and geographic density players embedded in European precision manufacturing corridors. Competitive dynamics center on M&A absorption of independent coating houses by Tier-1 automotive suppliers and strategic partnerships between equipment manufacturers and coating service providers.
Within the broad-portfolio tier, Oerlikon Management AG and Morgan Advanced Materials plc exemplify divergent specialization strategies—Oerlikon leveraging multi-sector industrial coatings reach across automotive and medical accounts, Morgan occupying a position anchored in ceramic-DLC hybrid formulations for aerospace applications. IHI Ionbond AG represents the geographic density archetype, with positioning concentrated in European precision manufacturing corridors.
| Leading Market Players |
|---|
| Oerlikon Management AG |
| IBC Coatings Technologies |
| Morgan Advanced Materials plc |
| Renishaw plc |
| Sumitomo Electric Industries |
| IHI Ionbond AG |
| CemeCon |
| Acree Technologies |
| Wallwork Heat Treatment Ltd |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) validation cycles and EU MDR post-market surveillance requirements gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified coating houses while enabling 15-20% pricing premiums for validated European service providers serving automotive and medical device OEMs.
Pricing Analysis
Configured-to-order pricing for biocompatibility-certified medical device coatings commands substantial premiums over standard automotive powertrain specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with medical-grade CVD platforms capturing the highest tier. Pricing pressure stems from automotive OEM consolidation toward captive Tier-1 coating capacity, squeezing independent job shops. Tier-1 automotive buyers exhibit highest price sensitivity, while medical device manufacturers prioritize certification reliability over unit cost.
Supply Chain Analysis
Strategic stockpiling of specialized cathode arc and sputtering targets prevails among German and Japanese coating houses facing concentrated plasma source supply. Raw material procurement draws from Germany, Japan, and the United States for precision manufacturing inputs, with graphite and hydrocarbon precursor sourcing tethered to petrochemical supply chains. Single-source vulnerability in specialized cathode production exposes coating facilities to input bottlenecks. Distribution runs through Tier-1 automotive supplier networks and medical device OEM captive lines, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Euro 7 emissions thresholds and REACH substance restrictions on hexavalent chromium alternatives constitute a regulatory inflection reshaping competitive positioning, accelerating substitution demand across automotive and medical supply chains.
For Market Incumbents: Secure captive PVD capacity expansion in Baden-Württemberg and Nagoya corridors to defend automotive volume contracts against Tier-1 backward integration. Invest in parallel FDA and EU MDR quality system certification to capture medical device premium pricing before qualification timelines compress further.
For New Entrants and Emerging Players: Anchor in Pune and Bangalore precision manufacturing clusters where PLI scheme subsidies reduce capital barriers and export-oriented automotive component demand outpaces localized coating infrastructure. Pursue CVD-PVD hybrid platform partnerships with equipment manufacturers to serve both medical certification and automotive throughput requirements.
For Investors and Strategic Acquirers: EPA National Emission Standards retrofit deadlines reshape the acquisition landscape toward coating houses with closed-loop plasma systems already deployed. Target mid-cap European service providers with established ISO 13485 accreditation and automotive Tier-1 relationships for platform consolidation. Monitor FDA 510(k) approval velocity for coated cardiovascular devices as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| CVD-PVD Hybrid Platform Deployment | Enables single-facility service across medical biocompatibility and automotive wear-resistance specifications. |
| Backward Integration into Sputtering Target Production | Reduces exposure to German and Japanese cathode supplier concentration. |
| EU MDR Quality System Certification | Qualifies coating houses for post-market surveillance mandates on implanted devices. |
| Closed-Loop Plasma System Migration | Ensures EPA National Emission Standards compliance without methane venting penalties. |
| Pune-Bangalore Geographic Expansion | Captures PLI-subsidized automotive component coating demand in Indian precision corridors. |
Study Parameters
A spread of perspectives from coating service executives, automotive Tier-1 procurement managers, medical device regulatory affairs leads, and plasma equipment engineers converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC filings of industrial coatings companies, EPA enforcement databases, EU MDR notified body registers, and Japanese METI industrial standards documentation. Bottom-up capacity utilization estimates and top-down end-use demand aggregation provided cross-verification.
Segmentation dimensions modeled span deposition technology, product architecture, end-use industry, and regional regulatory cluster across the projection horizon. CAGRs derive from installed base expansion rates, qualification timeline compression, and substitution elasticity against incumbent coating technologies. Industry-specific inputs include PVD platform throughput benchmarks and biocompatibility certification pipeline velocities.
Material uncertainties — regulatory timeline delays, plasma source supply disruptions, and automotive OEM captive integration acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Self-Healing Coatings Market
Coatings
Mexico Floor Coatings Market
Coatings
France Protective Coatings Market
Coatings
Coating Binders Market
Coatings
Global Graphite Coatings Market
Coatings
Antifouling Coatings Market
Coatings
Anti Fog Coatings Market
Coatings
Italy Protective Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Carbon Fiber Coatings Market
Coatings
Wood Sealer Market
Coatings
Global Water-Based Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Asia-Pacific Thermal Spray Market