
 Global Plastic Coatings Market | 2026-2036
Global Plastic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Coatings Market Foresight
Direct supply from resin producers to automotive OEMs is narrowing as formulation houses build captive technical service capabilities. Axalta Coating Systems leverages its color-matching infrastructure to anchor long-term contracts with tier-one suppliers. BASF SE sustains polymer R&D intensity across polyurethane and acrylic platforms. PPG Industries competes through regional manufacturing scale in Asia-Pacific and Europe.
Plastic coatings are polymer-based protective or decorative layers applied to thermoplastic and thermoset substrates, typically ranging from 25 to 200 microns in cured film thickness, formed through solvent-borne, water-borne, or powder deposition processes. Their primary purpose is to extend substrate lifespan, enhance surface aesthetics, and impart functional properties including chemical resistance and electrical insulation. Powder coating leads product-type value pools due to near-zero VOC emissions and overspray recyclability, while UV coating represents the fastest-expanding technology segment driven by instant cure speeds and energy efficiency in electronics manufacturing. Liquid coating remains the most mature category, with margin concentration in aerospace and marine specialty grades.
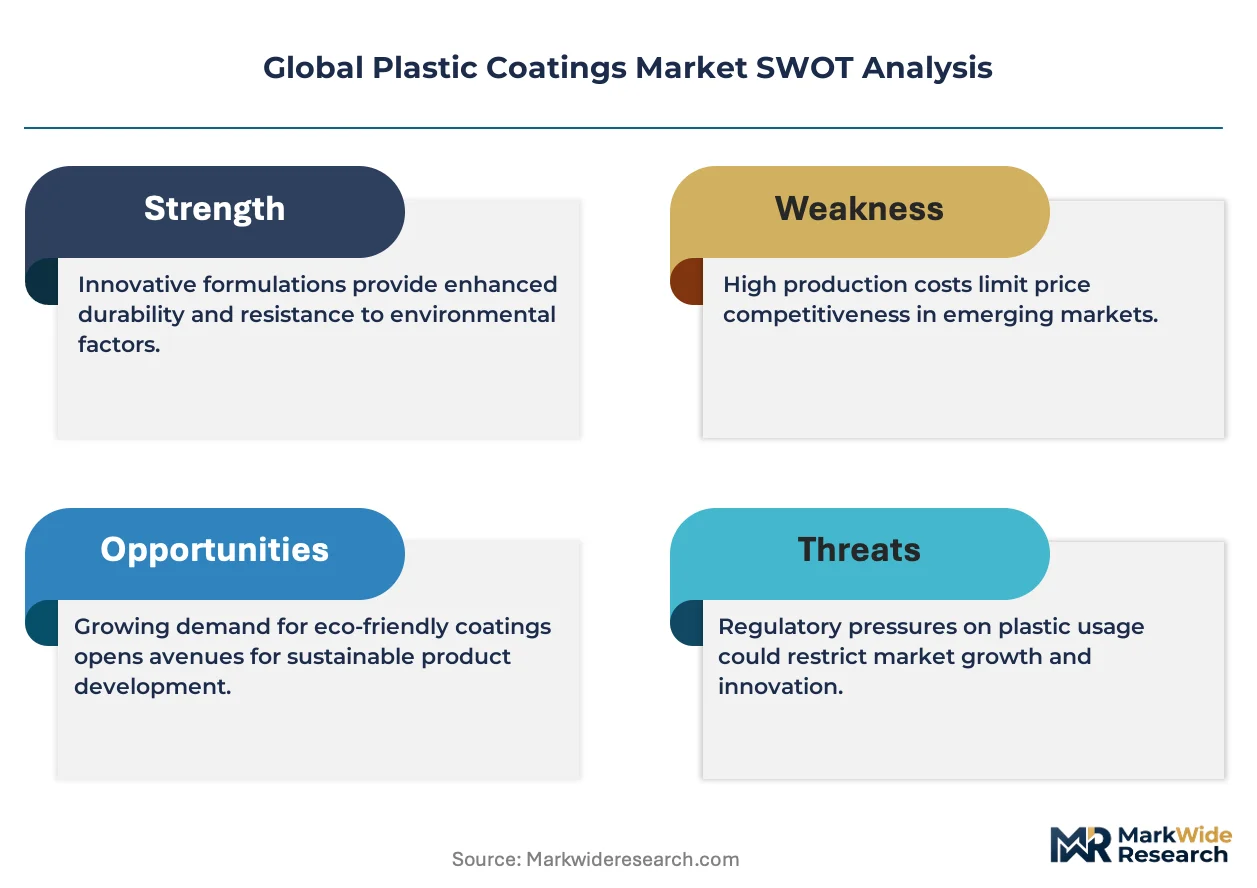
REACH restricts solvent-borne formulations across Europe, compelling reformulation toward water-borne and high-solids systems. EPA air-quality standards in the United States impose maximum achievable control technology requirements on coating operations, reshaping capital allocation toward compliant application equipment. China's MEE enforces dual carbon-aligned emission controls at manufacturing facilities, influencing local production chemistry. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and certification timelines.
Market Dynamics
REACH and the EU Green Deal are compressing solvent-borne coating margins while accelerating capital flows into water-borne and powder alternatives, reshaping formulation priorities across automotive and electronics supply chains.
Growth Catalysts
- Automotive lightweighting mandates:OEMs are specifying advanced coating systems for thermoplastic body panels and interior trim to meet fuel-efficiency targets without sacrificing durability.
- China's dual carbon alignment:MEE emission controls at manufacturing facilities are standardizing low-VOC coating consumption across electronics and consumer goods production clusters.
- UV cure acceleration:Electronics manufacturers are adopting instant-cure UV coating to compress production cycles and reduce energy intensity in smartphone and wearable assembly.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and polyurethane resin costs fluctuate with crude oil derivatives, compressing formulation margins during upstream price spikes.
- Specialty additive concentration:Photoinitiator and crosslinker supply concentrates among German and Japanese chemical producers, creating single-source vulnerability for UV and powder systems.
- High-solids application limits:Viscosity constraints prevent solvent-borne high-solids formulations from achieving uniform film thickness below 50 microns on complex geometries.
Strategic Opportunities
- Bio-based formulation white space:EU Green Deal procurement preferences create first-mover advantage for coatings with >25% bio-derived content in automotive and appliance segments.
- India electronics manufacturing:PLI scheme incentives for domestic mobile and component production are expanding addressable coating demand in Noida and Sri City clusters.
- AI-driven color matching:Machine vision integration with cloud-based pigment databases is digitizing custom color development, compressing OEM approval cycles from weeks to days.
Industry Challenges
- Formulation chemist scarcity:Expertise in water-borne resin stabilization and UV oligomer design concentrates among aging specialists in Germany and Japan.
- Application equipment capex:Electrostatic powder booths and UV LED curing arrays require substantial capital outlay, disadvantaging smaller job shops.
- Multi-jurisdiction certification lag:Separate EPA, REACH, and GB standard testing protocols extend product launch timelines by 8-14 months for global formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Coatings Market |
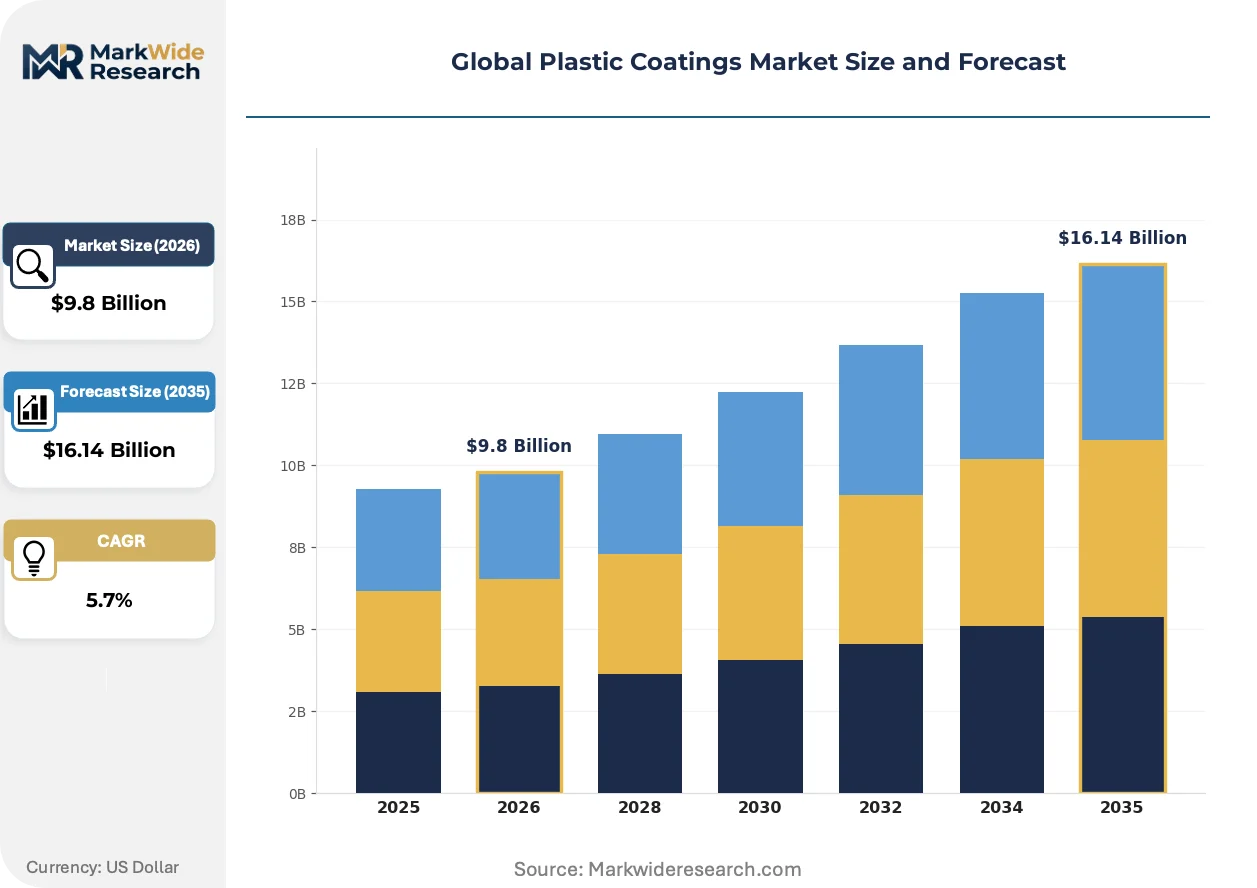
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
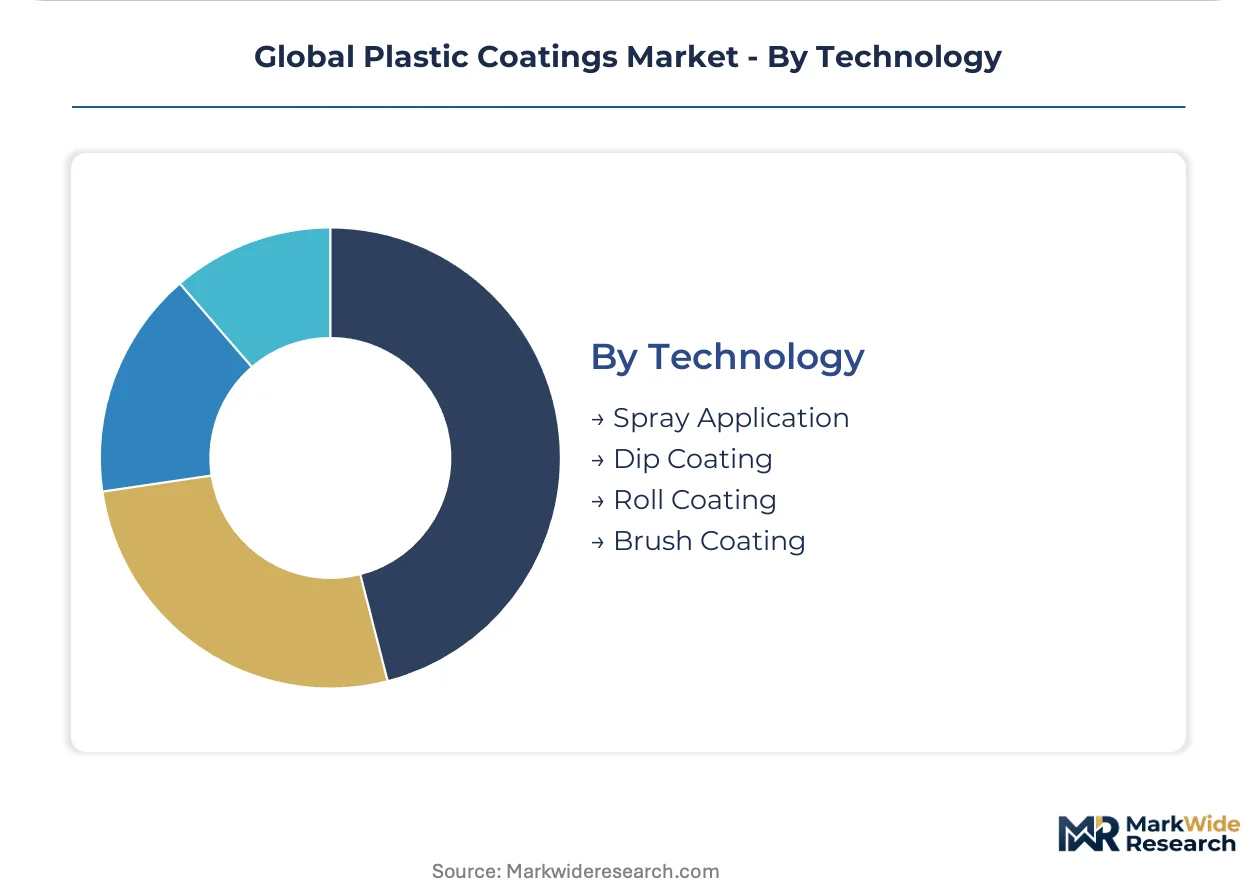
| Segmentation | Product Type: Powder Coating, Liquid Coating, UV Coating, Electrostatic Coating End User: Automotive OEMs, Construction, Electronics, Consumer Goods Application: Decorative Finishes, Corrosion Protection, Electrical Insulation, Chemical Resistance Technology: Spray Application, Dip Coating, Roll Coating, Brush Coating |
| Companies Covered | Axalta Coating Systems, 3M, The Sherwin-Williams Company, Dow Chemical Company, Covestro AG, Akzo Nobel N.V., BASF SE, Wanhua Chemical Group Co. Ltd., PPG Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Coatings Market Shifts & Advancements
Digital integration across formulation, application, and quality assurance is compressing development cycles and enabling mass customization previously uneconomical at coating volumes.
Smart coating systems incorporating embedded sensors and conductive layers are digitizing substrate monitoring capabilities. Automotive tier-one suppliers are piloting these materials for real-time corrosion detection in underbody applications. The technology is digitizing predictive maintenance models, shifting value capture from commodity film supply to integrated surface intelligence.
REACH authorization requirements for chromium trioxide in corrosion-resistant primers are forcing reformulation toward trivalent chrome and thin-film pretreatment alternatives. The restriction affects aerospace and marine coating specifications most acutely, with OEMs in France and Germany accelerating qualification of chrome-free systems ahead of 2025 sunset dates.
Consolidated procurement by multinational appliance and electronics brands is displacing fragmented distributor networks with direct formulation house contracts. Buyers in China's Pearl River Delta are centralizing coating specification authority at headquarters level, compressing supplier counts and demanding captive technical service support. The shift concentrates volume among three to five global suppliers per substrate category.
Global Plastic Coatings Market Segmentation
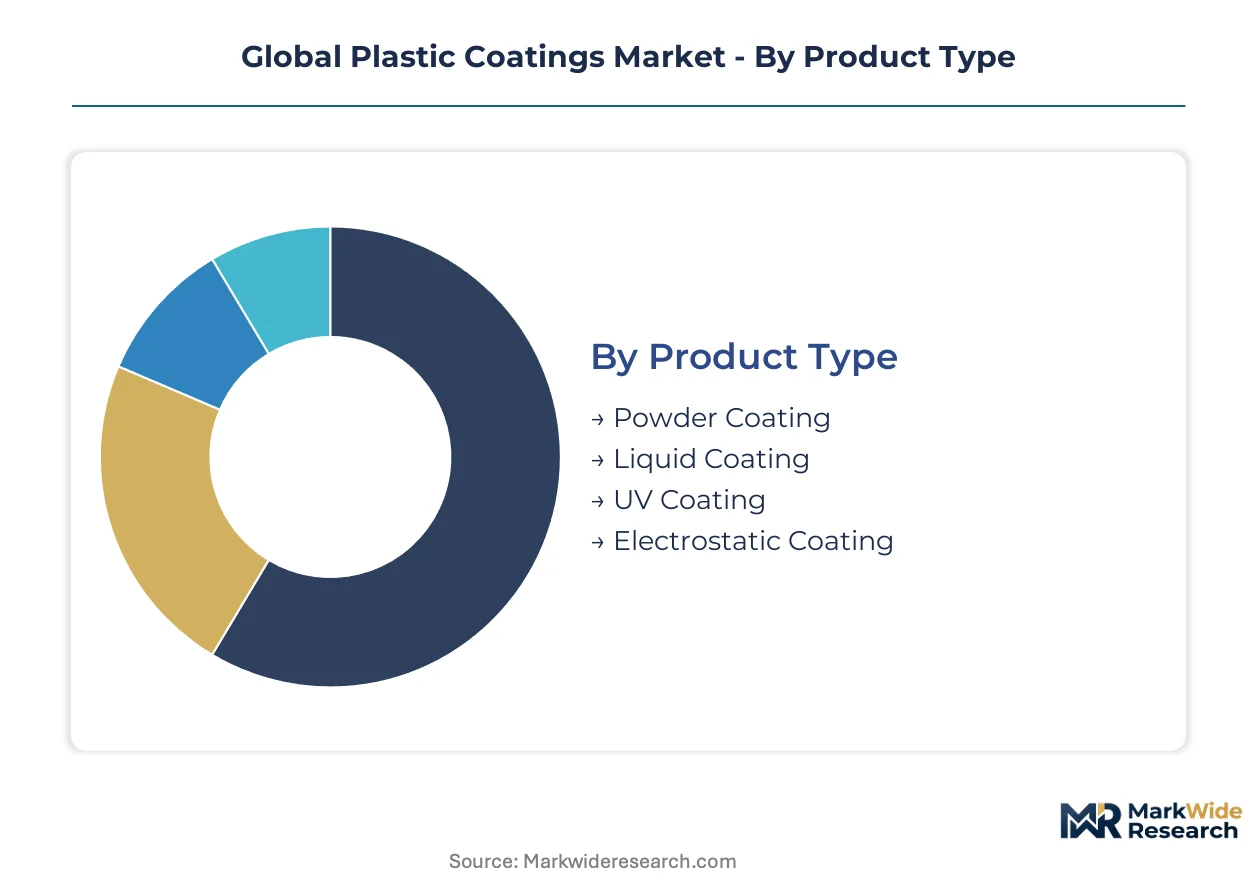
Segmentation in plastic coatings separates volume-driven commodity grades from specification-driven specialty formulations. Technology and application splits determine capital intensity and reformulation exposure, while end-user concentration shapes pricing power and contract duration.
Product Type:
Powder coating cycles inventory fastest in automotive tier-one operations, while liquid coating maintains the longest specification lock-in periods across aerospace and marine.
- Powder Coating:Thermoset polymer films applied electrostatically to grounded substrates, then cured at 180-200°C to form crosslinked barriers. Demand concentrates in automotive underbody and appliance exterior lines in Germany and China, driven by near-zero VOC compliance with REACH and MEE emission ceilings. Overspray recyclability compresses material waste below 5%.
- Liquid Coating:Solvent-borne or water-borne resin systems delivered through conventional spray or dip methods, spanning 25-150 micron dry film thickness. Demand anchors in French and Italian aerospace finishing facilities, constrained by viscosity limits below 50 microns on complex geometries and prolonged cure cycles.
- UV Coating:Photoinitiator-acrylate oligomer systems curing instantly under 395nm LED arrays. Electronics manufacturers in South Korea and Taiwan deploy these for smartphone housing finishing.
- Electrostatic Coating:Charged particle deposition optimizing wrap-around coverage on three-dimensional substrates. Automotive interior trim operations in Michigan and Bavaria favor this for uniform edge coverage.
Powder coating dominates installed base. UV coating is where expansion concentrates.
End User:
Cost tier separation runs deepest here: automotive OEMs and electronics brands command formulation house R&D investment, while construction and consumer goods buyers prioritize unit cost minimization.
- Automotive OEMs:Specification authority resides with German and Japanese headquarters engineering teams, mandating corrosion resistance to 3,000+ salt spray hours and chip resistance to SAE J400 standards. Tier-one suppliers in Detroit, Stuttgart, and Shanghai carry inventory risk through just-in-sequence delivery contracts.
- Electronics:Smartphone and wearable manufacturers in Shenzhen and Seoul drive UV coating qualification for instant-cure throughput. NMPA-aligned GB standards govern electrical insulation properties in domestic Chinese production.
- Construction:Window profile and cladding fabricators in Poland and Vietnam specify powder coating for exterior durability, prioritizing color retention over functional performance.
- Consumer Goods:Appliance brands in Turkey and Mexico centralize coating procurement at regional headquarters, compressing supplier counts to three per substrate category.
Automotive OEMs anchor premium pricing tiers. Electronics manufacturing is climbing the fastest.
Application:
Margin concentration follows functional complexity: electrical insulation and chemical resistance command formulation premiums, while decorative finishes compete on color library breadth.
- Corrosion Protection:Barrier primers and topcoats extending substrate lifespan in salt-laden and industrial atmospheres. Marine OEMs in Norway and Japan specify these for offshore equipment, with trivalent chrome alternatives displacing REACH-restricted hexavalent systems.
- Electrical Insulation:Dielectric coatings maintaining 2,000V+ breakdown strength on motor housings and circuit board enclosures. Demand clusters in German industrial motor production and Chinese EV battery module assembly.
- Decorative Finishes:Aesthetic layers prioritizing gloss retention, color stability, and haptic quality. Italian furniture and French cosmetic packaging producers drive specification.
- Chemical Resistance:Fluoropolymer and epoxy systems protecting against solvent, acid, and base exposure. Laboratory equipment manufacturers in Massachusetts and Baden-Württemberg specify these.
Decorative finishes dominate installed base. Electrical insulation is where expansion concentrates.
Technology:
Application equipment capex separates segments: electrostatic spray and roll coating demand six-figure capital outlays, while brush coating sustains job-shop entry.
- Spray Application:Atomized deposition through airless, air-assisted, or electrostatic guns, accommodating complex geometries and variable film builds. Automotive refinishing operations in Ohio and São Paulo standardize on robotic electrostatic cells for transfer efficiency above 75%.
- Roll Coating:Metered nip or reverse-roll systems delivering 5-50 micron films on flat or lightly contoured substrates. Coil coating lines in Alabama and the Netherlands deploy these for appliance and building product pre-coating.
- Dip Coating:Submersion and withdrawal cycles forming uniform films on intricate shapes. Small-batch job shops in India and Mexico retain this for custom runs.
- Brush Coating:Manual application for touch-up, repair, and prototype volumes. Maintenance operations in Indonesian shipyards and Brazilian infrastructure projects rely on this.
Spray application dominates installed base. Roll coating is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical throughput infrastructure underwrites Europe's coating raw material flows. China's Yangtze River Delta manufacturing belt connects resin production to electronics assembly through dedicated chemical logistics corridors.
United States
Automotive OEMs in Detroit and aerospace finishing in Wichita drive solvent-borne and powder coating consumption. EPA maximum achievable control technology requirements reshape capital allocation toward compliant application equipment. Ohio's automotive refinishing corridor standardizes on robotic electrostatic cells for transfer efficiency.
Germany
Bavarian automotive tier-one suppliers and Baden-Württemberg industrial motor manufacturers anchor premium formulation demand. REACH authorization timelines for chromium trioxide accelerate qualification of chrome-free pretreatment alternatives. Stuttgart headquarters engineering teams mandate corrosion resistance specifications that tier-one suppliers carry through just-in-sequence contracts.
China
Shenzhen electronics manufacturers and Shanghai automotive clusters consume UV and water-borne coatings at scale. MEE dual carbon-aligned emission controls standardize low-VOC chemistry across Pearl River Delta production facilities. Domestic manufacturing scale and NMPA-aligned GB standards support coating consumption across electronics and consumer goods sectors.
Japan
Photoinitiator and crosslinker supply concentration among specialty chemical producers creates upstream leverage for UV coating systems. METI industrial standards govern electrical insulation properties in industrial motor and battery module applications. Nagoya-area automotive suppliers pilot smart coating systems for real-time corrosion detection.
South Korea
Seoul Capital Area electronics brands drive UV coating qualification for smartphone and wearable assembly throughput. MFDS-aligned industrial standards support coating specification in domestic production. Busan-Ulsan chemical processing infrastructure feeds resin supply to regional formulation operations.
Global Plastic Coatings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin and additive supply. The vendor base concentrates among formulation houses with captive technical service capabilities and regional manufacturing scale. Three archetypes dominate: global coating systems integrators, regional formulation specialists, and captive resin producers. Competitive moves center on strategic partnerships for bio-based feedstock access and geographic expansion through technical service center deployment.
Among diversified chemical conglomerates, BASF SE and Covestro AG occupy positions spanning polyurethane and acrylic resin platforms through integrated polymer R&D operations. Axalta Coating Systems anchors the formulation house tier with color-matching infrastructure supporting long-term automotive supplier contracts. PPG Industries exemplifies regional manufacturing scale concentration across Asia-Pacific and European production networks. These three represent distinct competitive positioning vectors: upstream resin control, technical service integration, and geographic manufacturing footprint.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| 3M |
| The Sherwin-Williams Company |
| Dow Chemical Company |
| Covestro AG |
| Akzo Nobel N.V. |
| BASF SE |
| Wanhua Chemical Group Co. Ltd. |
| PPG Industries Inc. |
| Others |
Supply & Pricing Matrix
The Port of Rotterdam's chemical throughput infrastructure channels resin feedstock flows between German polyurethane producers and French automotive tier-one suppliers, with freight cost volatility amplifying margin compression at formulation houses while enabling price differentiation between REACH-compliant water-borne grades and legacy solvent-borne systems.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automotive OEM specification-grade coatings from construction commodity powders and job-shop liquid volumes. Price differentiation rests on REACH certification tier and captive technical service bundling. Cost compression in economy-tier construction powders is intensifying because Chinese resin exports displace European domestic supply. Appliance brands in Turkey and Mexico exhibit highest price sensitivity, while German automotive headquarters engineering teams accept formulation premiums for corrosion resistance validation.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for photoinitiator-dependent UV coating systems. Raw material concentration centers on German acrylic resin producers, Japanese crosslinker specialists, and Chinese titanium dioxide suppliers. Formulation houses draw from petrochemical derivatives and specialty additive streams vulnerable to single-source concentration among Nagoya-area chemical producers. Distribution runs through consolidated direct contracts with multinational appliance and electronics brands, displacing fragmented regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is accelerating toward consolidated procurement desks at electronics and appliance headquarters, compressing supplier counts from fragmented regional networks to three-to-five global formulation houses per substrate category.
For Market Incumbents: Insulate specification lock-in through captive technical service center deployment in China's Yangtze River Delta and Germany's Baden-Württemberg corridor. Backward integration into bio-based resin platforms defends margin position against REACH-driven reformulation costs. Axalta Coating Systems' color-matching infrastructure exemplifies the R&D intensity required to anchor long-term automotive contracts.
For New Entrants and Emerging Players: Pursue white-space qualification in India's PLI-supported electronics manufacturing clusters at Noida and Sri City, where domestic coating consumption is expanding without incumbent technical service saturation. Bio-based formulation segments with EU Green Deal procurement preferences offer the most penetrable entry point. Partner with regional resin distributors to bypass capital-intensive electrostatic powder booth requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core coating formulation assets amid portfolio rationalization pressures. Long-term viability favors specialists with captive UV oligomer design capabilities and NMPA-aligned GB standard certification in China. Watch for inflection when automotive OEMs accelerate chrome-free pretreatment qualification ahead of REACH sunset enforcement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resin Supply | Secures feedstock access for EU Green Deal-compliant formulations ahead of procurement preference deadlines. |
| Technical Service Center Deployment | Anchors long-term contracts with tier-one automotive suppliers in Stuttgart and Shanghai corridors. |
| UV LED Curing Array Capital Investment | Compresses energy intensity for South Korean and Taiwanese electronics manufacturers. |
| Chrome-Free Pretreatment Qualification | Addresses REACH authorization timelines affecting French and German aerospace coating specifications. |
| Joint Venture with Indian Resin Distributor | Enables PLI-scheme electronics cluster penetration without full electrostatic booth capital outlay. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA REACH registration dossiers, SEC 10-K chemical segment disclosures, and Cefic industry reports. Interviews with plant managers at German automotive tier-one suppliers, procurement leads at Shenzhen electronics manufacturers, distribution channel partners in India's coating corridors, and technical R&D directors at polyurethane resin houses informed demand-side validation. Bottom-up volume triangulation across product type, end-user, and application segments was cross-checked against top-down macroeconomic drivers.
Forecast inputs span automotive lightweighting mandate intensity, MEE dual carbon enforcement trajectory, and UV cure adoption rates in smartphone assembly. The analytical framework models powder, liquid, UV, and electrostatic coating technologies across automotive OEM, electronics, construction, and consumer goods end-users throughout the projection horizon. CAGRs derive from segment-level volume build-ups adjusted for regulatory reformulation timelines and application equipment capex cycles. Petrochemical feedstock volatility and photoinitiator supply concentration serve as scenario sensitivity anchors.
Sensitivities concentrate around REACH authorization enforcement timing, crude oil derivative price spikes, and Chinese MEE emission control stringency revisions. Forecasts reflect assumptions about regulatory alignment and technology substitution rates without guaranteeing outcome realization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
US Antifouling Yacht Coatings Market
Coatings
Coating Resins Market
Coatings
Batters and Coatings Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
Concrete Floor Coatings Market
Coatings
North America Thermal Spray Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Asia-Pacific Flat Glass Coating Market
Coatings
Industrial Coatings Market
Coatings
BPA-Free Coatings Market
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market
Coatings
Automotive Conformal Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
South Korea Automotive OEM Coatings Market