
 US Institutional Cleaning Detergents Market | 2026-2036
US Institutional Cleaning Detergents Market Size, Share, and Industry Trends Forecast 2026-2036
US Institutional Cleaning Detergents Market Analysis
Hospital-grade disinfectant certification is reorganizing supplier priorities across the institutional channel. Ecolab Inc anchors its position through captive service networks that bundle chemical supply with dispensing equipment and compliance auditing. Diversey Holdings Ltd specializes in healthcare-specific formulations that meet Joint Commission and CDC surface disinfection protocols. Spartan Chemical Company leverages regional manufacturing in the Midwest to control delivery timelines for school district and municipal contracts.
US institutional cleaning detergents are formulated surfactant systems, typically blending quaternary ammonium compounds, peroxygens, or phenolic actives at use-dilution concentrations between 400 and 800 ppm for healthcare applications, designed to remove soil and reduce bioburden on non-porous environmental surfaces. Liquid cleaners dominate procurement volumes due to automated dilution control systems that reduce waste and standardize concentration accuracy. Disinfectants capture disproportionate margin pools because EPA registration requirements create regulatory moats that limit competitor entry. Healthcare Facilities application demand outpaces other segments as infection control budgets expand post-pandemic and ambulatory surgery centers multiply.
EPA registration under FIFRA, OSHA Hazard Communication Standard compliance, and state-level green chemistry mandates such as California's Cleaning Product Right to Know Act shape formulation disclosure, worker safety labeling, and market access for new entrants. FDA oversight of medical device cleaning chemistries in sterile processing departments adds a second compliance layer for suppliers targeting integrated health systems. Stakeholders must monitor how pending EPA updates to disinfectant efficacy testing protocols and emerging state restrictions on per- and polyfluoroalkyl substances reshape acceptable active ingredient portfolios.
Market Dynamics
Hospital-grade disinfectant certification under EPA FIFRA is reorganizing supplier priorities across the US institutional channel, forcing reformulation investments and captive service bundling to defend contract renewals.
Growth Catalysts
- EPA Safer Choice program expansion:Federal procurement preference for lower-toxicity chemistries is accelerating quaternary ammonium compound reformulation across federal healthcare facilities and Veterans Affairs medical centers.
- Ambulatory surgery center construction:De novo ASC development in Texas, Florida, and North Carolina is generating concentrated demand for turnkey infection control programs with automated dilution systems.
- Peracetic acid technology maturation:Sporicidal efficacy without corrosion damage to endoscopic equipment is displacing glutaraldehyde in sterile processing departments of integrated health systems.
Market Restraints
- Petrochemical feedstock volatility:Surfactant input costs tied to ethylene oxide and linear alkylbenzene fluctuate with Gulf Coast refinery capacity, compressing margin predictability for mid-tier formulators.
- EPA registration timelines:FIFRA Section 3 submissions for novel active ingredients require 18-36 month review cycles, freezing innovation pipelines for emerging antimicrobial chemistries.
- Concentrated manufacturing geography:Liquid detergent production clusters in Ohio, Illinois, and Texas create hurricane and winter storm exposure that disrupts just-in-time delivery to Southeast healthcare networks.
Strategic Opportunities
- Electrolyzed water systems:On-site generation technology eliminates shipping costs and EPA registration requirements for end-users, opening municipal and K-12 district accounts previously locked by incumbent chemical suppliers.
- California Cleaning Product Right to Know Act compliance services:Ingredient disclosure mandates create advisory revenue streams for distributors able to navigate Prop 65 and SB 258 documentation requirements for multi-state operators.
- UV-C and chemical hybrid protocols:Convergence of no-touch disinfection robotics with residual chemistries is creating premium service tiers in long-term care facilities seeking labor substitution.
Industry Challenges
- EPA efficacy testing protocol transitions:Pending updates to disinfectant test methods for emerging viral pathogens require costly laboratory revalidation and label amendment submissions.
- Automated dilution control integration:Legacy dispensing equipment from disparate manufacturers lacks IoT connectivity, complicating remote monitoring and compliance auditing for facility management contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Institutional Cleaning Detergents Market |
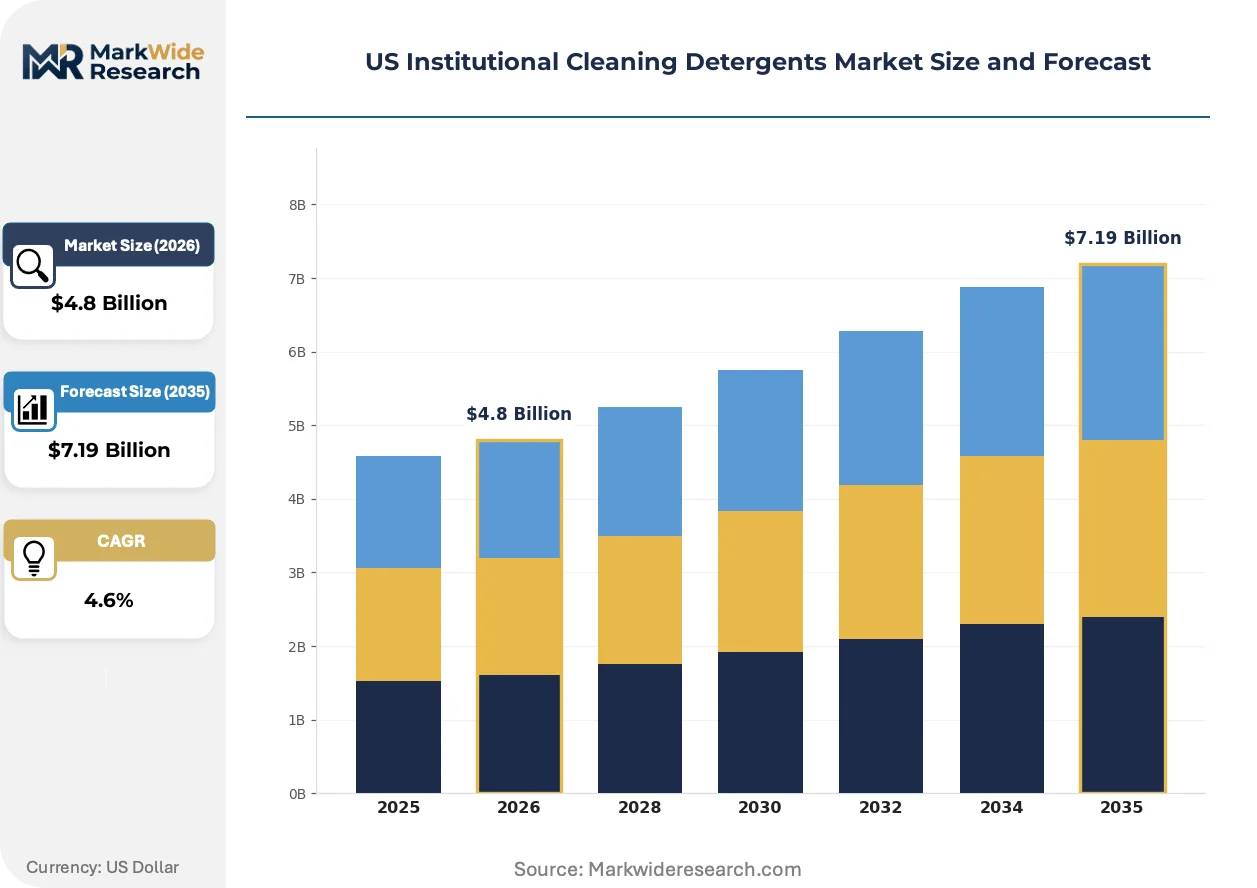
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cleaners, Powder Cleaners, Disinfectants, Surface Wipes Application: Healthcare Facilities, Educational Institutions, Food Service, Hospitality End User: Commercial Establishments, Government Facilities, Industrial Sites, Residential Services Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Specialty Stores |
| Companies Covered | Procter & Gamble Co, Ecolab Inc, The Clorox Company, Diversey Holdings Ltd, Reckitt Benckiser Group plc, Henkel AG & Co KGaA, Spartan Chemical Company, Zep Inc, S C Johnson & Son Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Institutional Cleaning Detergents Market Emerging Trajectories
Formulation chemistry and dispensing automation are converging to reduce human error in concentration management while regulatory pressure accelerates the retirement of legacy actives with unfavorable toxicity profiles.
Hypochlorous acid generated through electrochemical activation is displacing quaternary ammonium compounds in foodservice and hospitality applications where no-rinse sanitization requirements intersect with fragrance sensitivity concerns. Large casino operators and national hotel chains are piloting on-site generation systems to eliminate bulk chemical storage liabilities. The shift is compressing traditional liquid concentrate volumes in segments previously dominated by dilution-control contracts.
OSHA Hazard Communication Standard updates and state-level green procurement mandates in California, New York, and Massachusetts are forcing reformulation transparency and worker safety documentation that smaller regional blenders struggle to maintain. The compliance burden is favoring integrated suppliers with dedicated regulatory affairs staff and toxicology databases. Healthcare systems with Joint Commission accreditation cycles are consolidating vendor lists to reduce audit preparation complexity.
Subscription-based chemical management programs with embedded compliance reporting are replacing transactional purchase orders in multi-site healthcare and education accounts. Distributors bundle inventory sensing, automatic replenishment, and training documentation into per-room or per-bed pricing models. The Southeast exhibits the fastest uptake as hospital construction and hospitality recovery concentrate new facility openings in Florida, Georgia, and Tennessee.
US Institutional Cleaning Detergents Market Segmentation
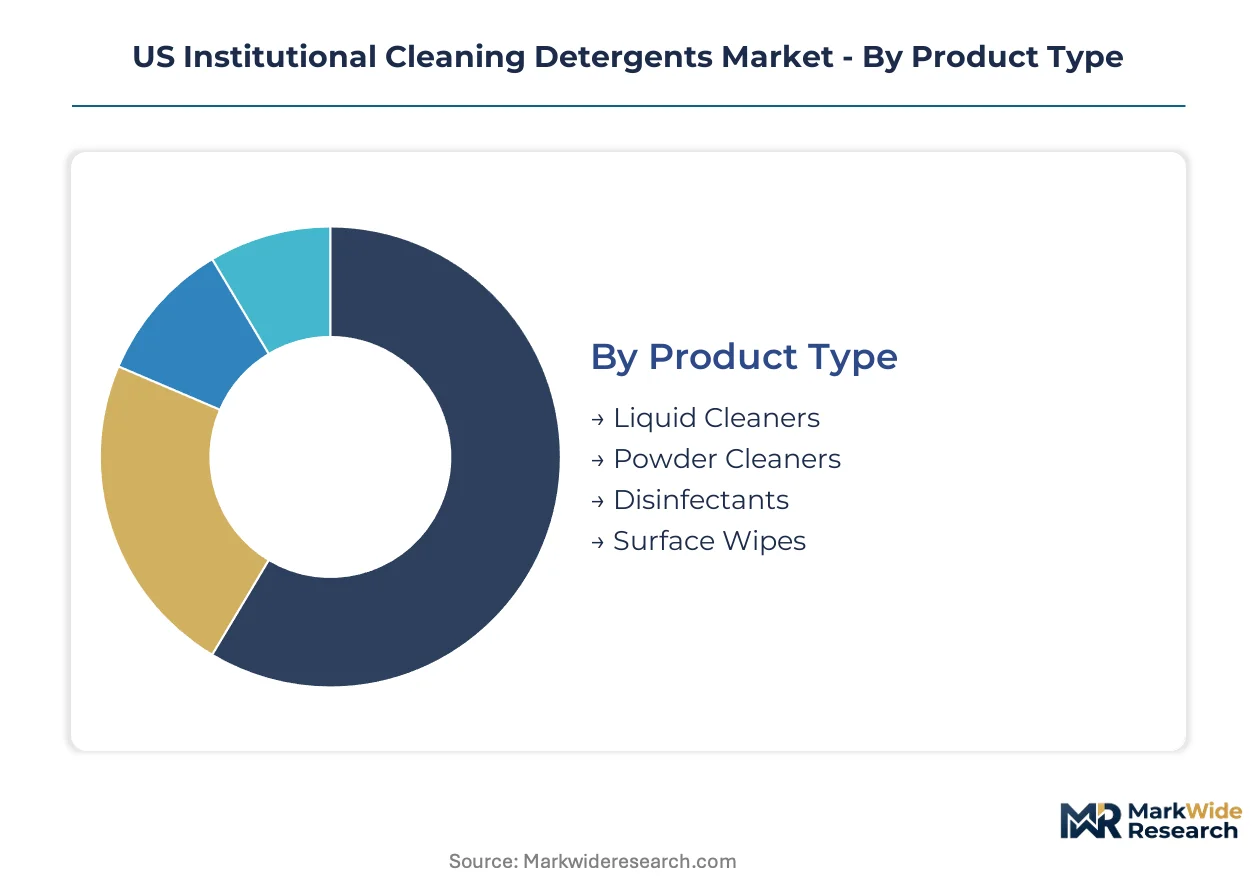
Institutional cleaning detergents fragment across four intersecting dimensions that determine procurement workflows, margin capture, and regulatory exposure. Product chemistry dictates EPA registration burdens while application context shapes dilution system requirements and service bundling economics.
Product Type:
Margin pools concentrate in disinfectants where FIFRA registration creates regulatory moats, while liquid cleaners dominate procurement volumes through automated dilution contracts.
- Liquid Cleaners:Surfactant-based formulations delivered through wall-mounted dilution control systems dominate K-12 districts and hospital environmental services. Southeast healthcare construction is driving concentrated demand for turnkey liquid programs with IoT-enabled inventory sensing in Florida and Georgia facilities.
- Disinfectants:EPA-registered chemistries carrying hospital-grade or broad-spectrum claims command premium positioning. Healthcare Facilities application demand is accelerating reformulation toward peracetic acid and hypochlorous acid actives as Joint Commission audits intensify surface bioburden documentation requirements.
- Powder Cleaners:Alkaline builders and enzyme blends retain relevance in industrial floor care and food processing plant CIP systems where high-temperature stability matters.
- Surface Wipes:Pre-saturated towelettes capture ambulatory surgery center and long-term care demand for point-of-use convenience with reduced cross-contamination risk.
Liquid Cleaners holds installed capacity. Disinfectants is rotating up the share rankings.
Application:
Volume concentration tracks healthcare construction corridors and hospitality recovery patterns across sub-regional economies.
- Healthcare Facilities:Acute care hospitals, ambulatory surgery centers, and long-term care facilities drive infection control chemistry procurement. Texas, Florida, and North Carolina ASC development is generating concentrated demand for sporicidal chemistries with materials compatibility guarantees for endoscopic equipment.
- Educational Institutions:K-12 districts and university systems prioritize bulk concentrate programs with automated dilution to minimize custodial labor exposure. California's Cleaning Product Right to Know Act compliance is forcing ingredient disclosure documentation that favors suppliers with dedicated regulatory affairs staff.
- Food Service:No-rinse sanitization requirements intersect with fragrance sensitivity concerns in casino and hotel chain operations.
- Hospitality:Post-pandemic occupancy recovery in Tennessee and Georgia is restoring linen and housekeeping chemical volumes.
Healthcare Facilities anchors procurement value. Educational Institutions is expanding most quickly as ESSER-funded facility upgrades refresh dispensing infrastructure.
End User:
Contract structure complexity varies sharply across ownership models and procurement centralization.
- Commercial Establishments:Property management companies and building service contractors purchase through distribution with embedded compliance auditing. Multi-site operators in the Southeast are consolidating vendor lists to reduce Joint Commission preparation complexity.
- Government Facilities:Federal healthcare facilities and Veterans Affairs medical centers trigger Safer Choice program preferences that accelerate quaternary ammonium compound reformulation.
- Industrial Sites:Manufacturing and warehousing operations emphasize floor care and degreasing chemistries with OSHA Hazard Communication Standard documentation.
- Residential Services:Multi-family property management and senior living operators represent a contracting channel as hospitality staffing shortages shift some institutional supply relationships.
Commercial Establishments maintains contract density. Government Facilities is climbing the fastest as federal procurement rules tighten.
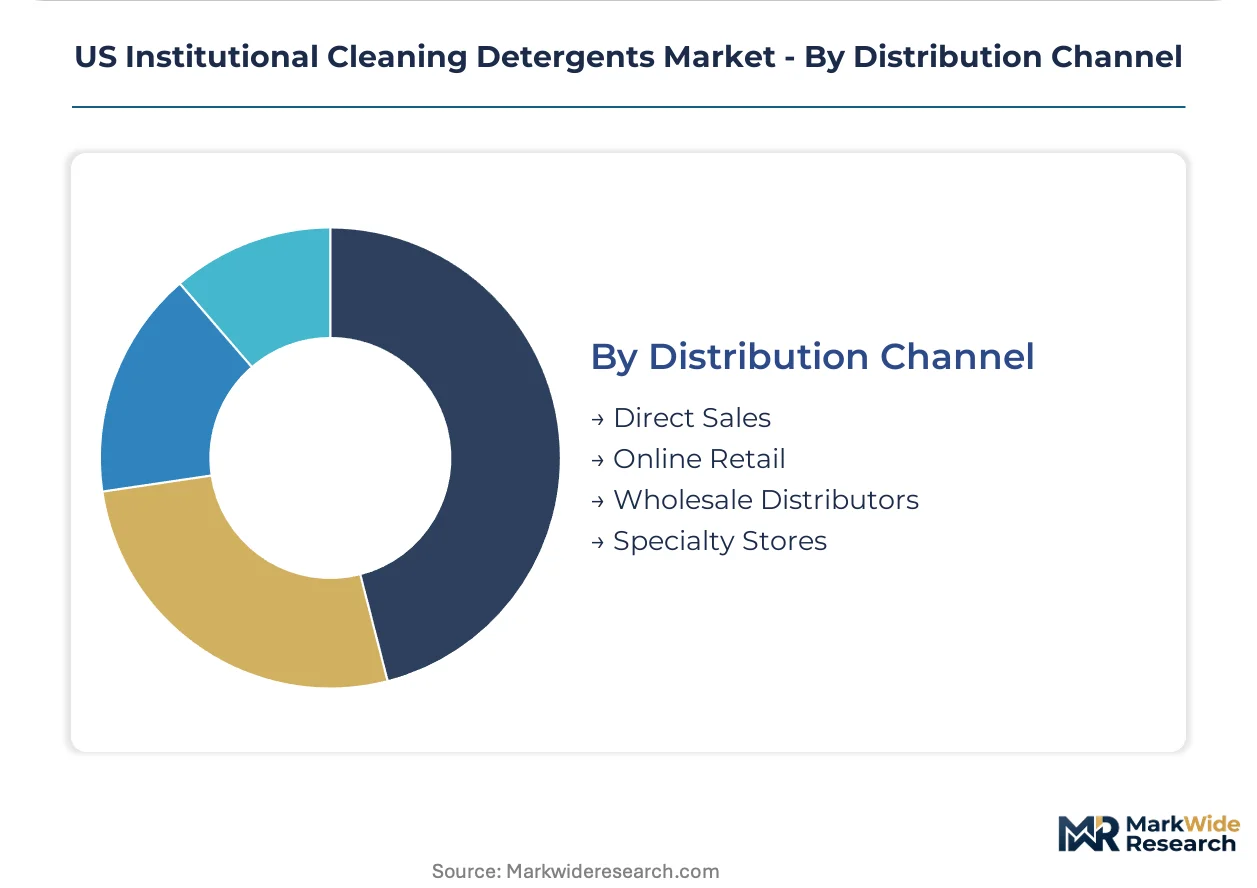
Distribution Channel:
Service bundling and compliance documentation capabilities are restructuring channel economics away from transactional supply.
- Direct Sales:Manufacturers with captive service networks bundle chemical supply with dispensing equipment, training documentation, and audit preparation. Ecolab's model anchors this channel through per-room pricing with automatic replenishment.
- Wholesale Distributors:Regional distributors navigate California SB 258 and Prop 65 documentation for multi-state operators, capturing advisory revenue streams alongside product margins.
- Online Retail:E-commerce penetration remains limited to small commercial accounts and emergency replenishment due to bulk shipping economics and dilution equipment compatibility requirements.
- Specialty Stores:Janitorial supply houses serve municipal and school district accounts with legacy relationships but face displacement from subscription-based chemical management programs.
Direct Sales controls the premium tier. Wholesale Distributors is gaining share fastest through compliance service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US institutional cleaning detergent production outpaces domestic consumption, creating a modest export surplus concentrated in EPA-registered disinfectants shipped to Canadian healthcare networks and Mexican hospitality chains. Import dependency remains minimal, limited to specialized European surfactant intermediates and Asian-manufactured dispensing equipment components.
Southeast
Florida, Georgia, and Tennessee drive concentrated demand through ambulatory surgery center construction and hospitality occupancy recovery. EPA Safer Choice procurement preferences at Veterans Affairs medical centers in Atlanta and Miami accelerate quaternary ammonium compound reformulation. Orlando and Nashville hotel chains pilot on-site hypochlorous acid generation systems to eliminate bulk chemical storage liabilities.
Texas
De novo healthcare facility development in Dallas-Fort Worth and Houston generates turnkey infection control program demand with automated dilution systems. OSHA Hazard Communication Standard enforcement in Gulf Coast petrochemical corridors shapes industrial site procurement documentation requirements. San Antonio school districts consolidate vendor lists to reduce California SB 258 compliance preparation complexity.
Midwest
Ohio, Illinois, and Michigan host concentrated liquid detergent manufacturing clusters with hurricane and winter storm exposure disrupting just-in-time Southeast delivery networks. EPA registration timelines for novel actives freeze innovation pipelines for regional formulators near Cleveland and Chicago. Detroit-area automotive suppliers emphasize floor care chemistries with OSHA-compliant worker safety labeling.
California
The Cleaning Product Right to Know Act and Prop 65 disclosure mandates force ingredient transparency documentation that favors suppliers with dedicated regulatory affairs staff. Los Angeles and San Francisco healthcare systems consolidate vendor lists ahead of Joint Commission accreditation cycles. Central Valley food processing plants retain alkaline powder cleaners for high-temperature CIP system compatibility.
Northeast
New York and Massachusetts state-level green procurement mandates accelerate retirement of legacy actives with unfavorable toxicity profiles. Boston-area integrated health systems add FDA oversight layers for sterile processing department chemistries. Philadelphia and Baltimore municipal contracts favor distributors navigating multi-state compliance documentation requirements.
US Institutional Cleaning Detergents Market Vendor Landscape
Concentration sits with diversified chemical conglomerates that bundle formulation supply with captive service networks and compliance auditing capabilities. Mid-tier regional blenders compete on delivery velocity for school district and municipal accounts but struggle with California disclosure mandate documentation burdens. Two strategic archetypes dominate: integrated full-service providers with per-room pricing models, and specialized healthcare formulators targeting Joint Commission protocols. Competitive moves center on M&A to capture automated dilution system installed bases and strategic partnerships with dispensing equipment manufacturers.
Among US-based integrated providers, Ecolab Inc and Spartan Chemical Company exemplify the full-service archetype through geographic anchoring in Midwest manufacturing corridors. Diversey Holdings Ltd represents specialization in healthcare-specific formulations. Reckitt Benckiser Group plc and The Clorox Company occupy positions in the diversified consumer-to-institutional crossover tier. Henkel AG & Co KGaA and Procter & Gamble Co sit within multinational conglomerate structures that leverage surfactant scale across adjacent categories. Zep Inc and S C Johnson & Son Inc anchor regional and family-owned positioning respectively.
| Leading Market Players |
|---|
| Procter & Gamble Co |
| Ecolab Inc |
| The Clorox Company |
| Diversey Holdings Ltd |
| Reckitt Benckiser Group plc |
| Henkel AG & Co KGaA |
| Spartan Chemical Company |
| Zep Inc |
| S C Johnson & Son Inc |
| Others |
Supply Flow & Price Mechanics
Midwest manufacturing scale economies in Ohio and Illinois concentrate liquid detergent production among integrated formulators, creating capacity-utilization advantages that simultaneously compress price floors for regional competitors and elevate service-bundling premiums for national accounts. This concentration dynamic forces smaller blenders toward commodity positioning in municipal and school district segments while EPA-registered disinfectant producers capture disproportionate margins through FIFRA compliance moats.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across institutional channels, with three-tier pricing stratification across premium hospital-grade disinfectants, standard commercial cleaners, and economy bulk concentrates. Price differentiation hinges on EPA registration tier and automated dilution system compatibility, with certification-bearing formulations commanding substantial premiums over unregistered alternatives. Pricing pressure stems from petrochemical feedstock volatility tied to Gulf Coast refinery capacity, compressing margin predictability for mid-tier suppliers. K-12 districts exhibit highest price sensitivity due to ESSER-funded budget constraints, while integrated health systems prioritize compliance documentation over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate healthcare procurement as hurricane and winter storm exposure across Ohio, Illinois, and Texas manufacturing clusters disrupts just-in-time delivery to Southeast networks. Geographic supply concentration centers on domestic production with minimal import dependency, drawing from regional surfactant intermediates and Asian-manufactured dispensing equipment components. Raw material dependencies rest on ethylene oxide, linear alkylbenzene, and quaternary ammonium compound precursors. Single-source vulnerability concentrates in automated dilution system manufacturers whose IoT-enabled inventory sensing equipment locks facilities into proprietary chemical supply relationships. Distribution runs through captive service networks for premium accounts and wholesale distributors for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through EPA FIFRA registration timelines creates formidable defensive moats, as 18-36 month approval cycles freeze competitor pipelines and cement incumbent positioning in healthcare procurement channels.
For Market Incumbents: Compound defensive positioning through backward integration into automated dilution equipment manufacturing and captive compliance auditing services. Expand per-room pricing models with embedded IoT inventory sensing to raise switching costs for multi-site healthcare accounts. Threats from electrolyzed water on-site generation technology demand counter-investment in hybrid chemical-UV-C protocol development to defend service-bundling premiums. For New Entrants and Emerging Players: Lead with California SB 258 compliance advisory services as a wedge into multi-state operator accounts burdened by ingredient disclosure mandates. Target municipal and K-12 district segments previously locked by incumbent chemical suppliers through electrolyzed water system distribution partnerships. White-space opportunity concentrates in long-term care facilities seeking labor substitution through no-touch disinfection robotics integration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized healthcare formulators with Joint Commission protocol expertise over diversified chemical conglomerates facing margin compression in commodity segments. Long-term viability hinges on peracetic acid and hypochlorous acid formulation capabilities displacing legacy quaternary ammonium compounds. Acquisition targets should demonstrate installed base density in ASC construction corridors. Signal to watch: EPA updates to disinfectant efficacy testing protocols accelerating laboratory revalidation cost burdens that favor scaled players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dispensing Equipment | Captive IoT-enabled dilution systems lock healthcare accounts into recurring chemical supply contracts with automatic replenishment. |
| Peracetic Acid Formulation Scale-Up | Sporicidal efficacy without endoscopic equipment corrosion addresses Joint Commission bioburden documentation requirements in ASC sterile processing. |
| California Compliance Advisory Services | SB 258 and Prop 65 documentation capabilities capture distributor advisory revenue streams from multi-state operators. |
| Electrolyzed Water System Partnerships | On-site generation technology opens municipal and K-12 accounts by eliminating EPA registration requirements and bulk chemical storage liabilities. |
| UV-C Hybrid Protocol Development | No-touch disinfection robotics integration creates premium service tiers in long-term care facilities facing staffing shortages. |
Methodological Framework
A spread of perspectives from environmental services directors at integrated health systems, procurement managers at ambulatory surgery centers, regulatory affairs specialists at institutional chemical suppliers, and distribution channel partners converged on the working assumptions underlying demand forecasts. Primary fieldwork combined structured interviews with secondary validation against EPA registration databases, OSHA Hazard Communication Standard filings, and state-level green procurement mandate records. Bottom-up facility-level procurement analysis triangulated against top-down chemical production capacity data from Midwest manufacturing clusters.
Segmentation dimensions modeled span product chemistry tier, application context, end-user ownership structure, and distribution channel service-bundling intensity across the projection horizon. Analytical framework derived CAGRs through facility construction pipeline tracking, infection control budget expansion patterns, and ambulatory surgery center development velocity in Texas, Florida, and North Carolina. Industry-specific inputs incorporated EPA Safer Choice program procurement preference adoption curves and automated dilution system installed base penetration rates.
Forecasts assume regulatory continuity in EPA FIFRA registration protocols and California Cleaning Product Right to Know Act enforcement; material policy shifts would require re-modeling active ingredient portfolio viability and disclosure documentation burdens. Specific risks include pending EPA disinfectant efficacy testing protocol updates and emerging state restrictions on per- and polyfluoroalkyl substances. Revision becomes warranted when electrolyzed water on-site generation adoption crosses threshold penetration in hospitality and foodservice segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Rust Remover Market
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market
Cleaning Chemicals
Green Floor Care Chemical Systems for Commercial Facilities Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
Efflorescence Remover Market
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
Liquid Detergent Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Global Bleach Wipes Market
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Dry Electrostatic Wipes Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Commercial Deodorizers Market