
 Electrocoat Market | 2026-2036
Electrocoat Market Size, Share, and Industry Trends Forecast 2026-2036
Electrocoat Market Intelligence
ISO 12944 corrosion protection certification is redrawing competitive boundaries for electrocoat suppliers serving automotive and industrial OEMs. PPG Industries leverages its vertical integration into resin manufacturing to sustain cost advantages across cathodic electrocoat lines. BASF SE anchors European supply through specialized anodic formulations for electrical equipment manufacturers. Kansai Paint Co., Ltd competes aggressively in Asia-Pacific with high-build clear coat systems for premium automotive applications.
Electrocoat is an electrodeposition coating process where charged paint particles migrate to a conductive substrate under direct current, typically forming films of 15-35 micrometers that provide uniform corrosion protection across complex geometries. Cathodic epoxy systems dominate automotive body-in-white applications due to superior salt-spray resistance and edge coverage, while anodic acrylic variants retain share in cost-sensitive furniture and general industrial finishing where lower capital investment matters. Automated dip-coating lines with multi-stage pretreatment sequences command the technology margin pool as OEMs prioritize throughput consistency and reduced solvent emissions over manual electrostatic spray alternatives.
EPA National Emission Standards for Hazardous Air Pollutants and REACH substance restrictions are forcing reformulation away from hexavalent chromium and certain isocyanate curing agents, tightening raw material qualification timelines. China's MEE enforces dual carbon goals that limit solvent-based coating capacity expansions, redirecting investment toward waterborne electrodeposition systems. Stakeholders must monitor evolving substance restriction lists and carbon border adjustment mechanisms to anticipate which coating chemistries will retain market access across major manufacturing jurisdictions.
Market Dynamics
Cathodic epoxy electrocoat systems are consolidating automotive body-in-white specifications as OEMs face compressed corrosion warranty timelines and zero-defect quality mandates from Tier 1 suppliers.
Growth Catalysts
- EPA NESHAP compliance deadlines:Automotive OEMs in the United States are accelerating cathodic line conversions to meet hazardous air pollutant emission limits, creating replacement demand for legacy anodic systems.
- China's dual carbon goals:The MEE's solvent-based coating capacity restrictions are redirecting industrial finishing investment toward waterborne electrodeposition technologies in Jiangsu and Guangdong provinces.
- Salt-spray performance thresholds:Extended automotive corrosion warranties now require 1,000+ hour salt-spray resistance, specifications only cathodic epoxy formulations reliably achieve.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin prices fluctuate with propylene and bisphenol-A markets, compressing margin visibility for electrocoat formulators.
- Concentrated pigment supply:Specialty corrosion-inhibiting pigments concentrate among Chinese and German chemical suppliers, creating single-source vulnerability for qualified automotive grades.
- Hexavalent chromium substitution lag:REACH substance restrictions have eliminated chromate pretreatments, yet trivalent and non-chrome alternatives extend qualification cycles by 18-24 months.
Strategic Opportunities
- India industrial infrastructure buildout:The PLI scheme for automotive and electrical equipment manufacturing is creating first-mover advantage for electrodeposition system integrators establishing local technical service presence.
- Energy storage enclosure finishing:Battery pack manufacturers require uniform edge coverage on aluminum extrusions, an application specification anodic acrylic electrocoats address cost-effectively.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive coatings are incentivizing European OEMs to source electrodeposition chemicals from low-carbon production facilities.
Industry Challenges
- ISO 12944-9 certification timelines:Achieving C5-M and CX corrosion protection grades requires extended field exposure testing, delaying supplier qualification for offshore wind and marine applications.
- Legacy pretreatment integration:Automotive plants with zinc-phosphate lines face capital-intensive conversion to zirconium or silane-based systems compatible with next-generation electrocoat chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrocoat Market |
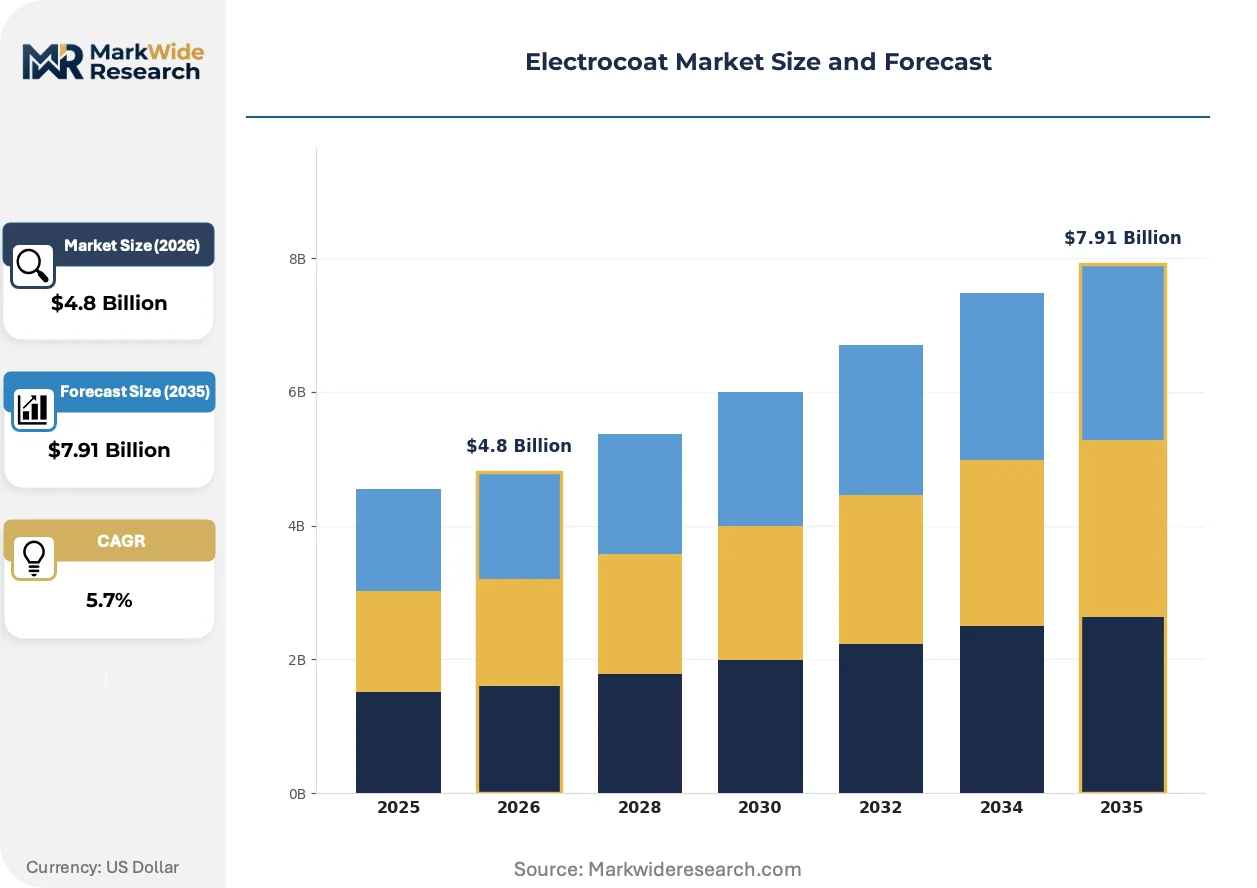
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cathodic, Anodic, Hybrid, Clear Coat Application: Automotive, Electrical Equipment, Furniture, Industrial Technology: Electrostatic Spray, Dip Coating, Automated Systems, Multi-Stage Process End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Construction |
| Companies Covered | Henkel AG & Co. KGaA, Nippon Paint Holdings Co., Ltd., PPG Industries Inc., KCC Corporation, Kansai Paint Co., Ltd, Axalta Coating Systems, The Sherwin-Williams Company, Dymax Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrocoat Market Strategic Shifts & Innovations
Electrocoat formulation science is pivoting toward ultra-low volatile organic compound systems and intelligent film-build control as regulatory thresholds tighten and substrate diversity expands beyond traditional steel.
High-build cathodic clearcoat technology is supplanting conventional primer-topcoat sequences in premium automotive segments. Luxury OEMs in Germany and Japan are specifying 35-45 micrometer single-layer electrodeposition films to eliminate sanding operations and reduce paint shop footprint. This consolidation is compressing the addressable market for conventional basecoat suppliers while elevating resin purity requirements for electrocoat formulators.
REACH authorization procedures are forcing systematic substitution of bisphenol-A derived epoxy resins in European consumer-facing applications. ECHA's 2024 update to the candidate list of substances of very high concern triggered reformulation programs across electrical equipment and furniture finishing sectors. Suppliers are responding with glycidyl ester and aliphatic epoxy alternatives, though these chemistries require modified curing profiles and tank stability management.
Automotive OEMs are unbundling coating system procurement from line installation contracts, creating direct relationships with electrocoat chemical suppliers. Tier 1 paint shops in the United States and Germany now negotiate raw material supply agreements separately from capital equipment purchases, shifting technical service responsibility toward formulators. This disintermediation is most visible in North American greenfield electric vehicle assembly plants, where chemical suppliers establish on-site laboratories to manage tank chemistry and film-build optimization.
Electrocoat Market Segmentation
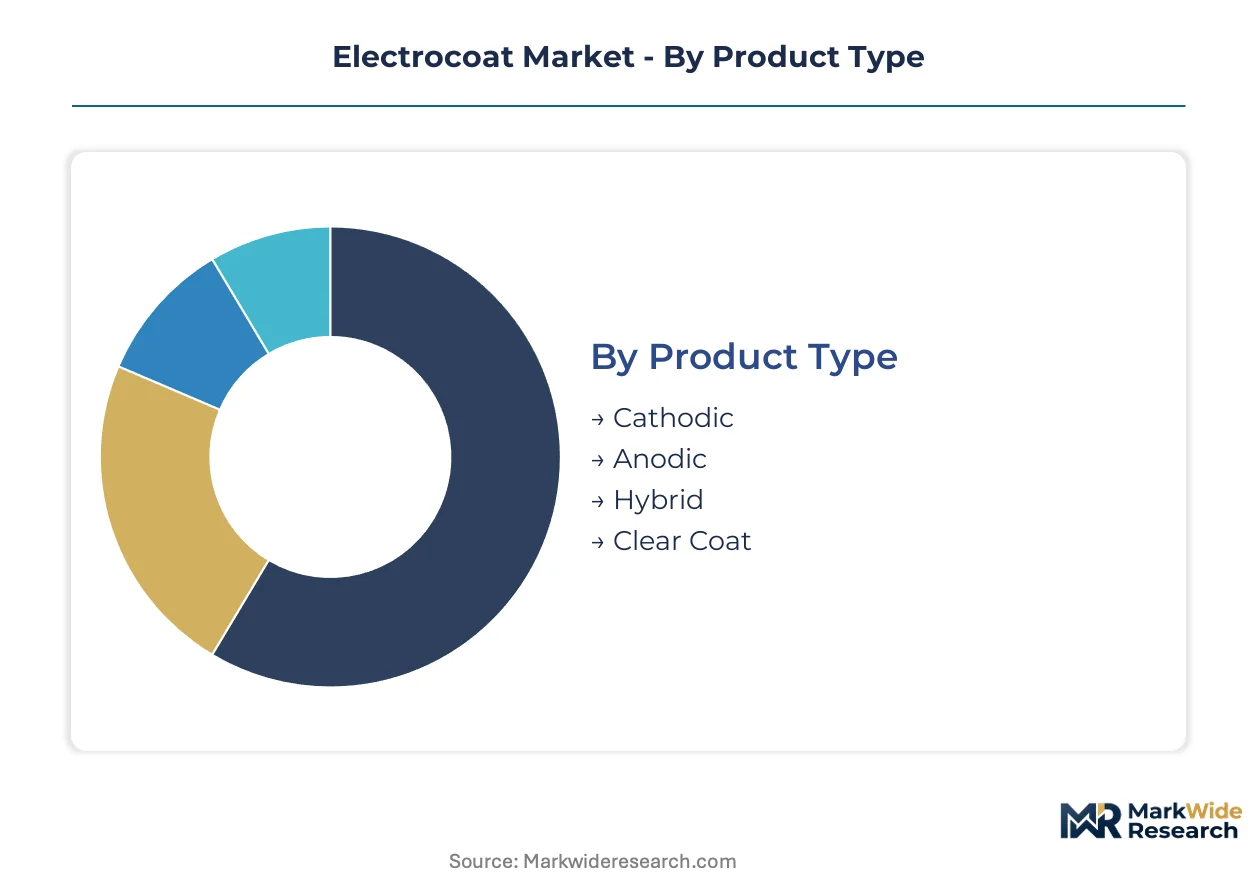
Electrocoat segmentation reveals how cathodic epoxy systems defend automotive specifications against powder coating substitution, while anodic variants cede share in furniture and general industrial finishing. Technology choices separate high-throughput OEM installations from job-shop flexibility requirements.
Product Type:
Cathodic formulations face powder coating encroachment in heavy equipment, yet retain irreplaceable edge coverage advantages in automotive body-in-white applications.
- Cathodic:Epoxy-amine systems electrodeposit onto negatively charged substrates, delivering 15-35 micrometer films with superior throw power into box sections and hem flanges. Automotive OEMs in Germany and the United States specify cathodic primers exclusively for corrosion warranties exceeding 10 years, as salt-spray resistance above 1,000 hours remains unmatched by alternative technologies.
- Anodic:Acrylic and alkyd resins deposit on positively charged parts, requiring lower capital investment and operating temperatures. Furniture manufacturers in China and Italy specify anodic systems for decorative metal frames where corrosion demands are moderate and equipment budgets are constrained.
- Hybrid:Combines cathodic deposition with UV-curable topcoat functionality, addressing premium appliance and electrical enclosure segments seeking single-line processing efficiency.
- Clear Coat:High-build cathodic clear systems eliminate basecoat-sanding sequences in luxury automotive finishing, specified by German and Japanese OEMs for 35-45 micrometer single-layer films.
Cathodic retains volume leadership; clear coat holds the steepest expansion curve.
Application:
Cost tier differentiation separates capital-intensive automotive lines from margin-sensitive job-shop operations across industrial finishing.
- Automotive:Body-in-white, chassis, and underbody components require uniform 20-25 micrometer films across complex stamped geometries. EPA NESHAP compliance deadlines in the United States are accelerating line conversions from solvent-borne spray to electrodeposition, with OEMs in Michigan and Tennessee investing in multi-stage pretreatment integration.
- Electrical Equipment:Switchgear enclosures, transformer housings, and cable trays demand consistent dielectric properties alongside corrosion protection. Manufacturers in India and Germany specify electrocoat for C4 and C5-M corrosion categories under ISO 12944, particularly for outdoor electrical infrastructure.
- Furniture:Decorative metal seating, shelving, and fixture frames utilize anodic acrylic systems where appearance and moderate durability suffice. Italian and Chinese producers favor lower-temperature curing to protect wood-composite substrates in mixed-material designs.
- Industrial:Agricultural equipment, material handling systems, and general fabrication represent fragmented demand served by both cathodic and anodic technologies, with coating selection driven by local environmental regulations and pretreatment compatibility.
Automotive commands the premium tier; electrical equipment is gaining share fastest as grid infrastructure investment accelerates.
Technology:
Volume concentration in high-throughput OEM installations creates technology margin pools distinct from flexible job-shop equipment.
- Electrostatic Spray:Manual and automatic spray guns apply charged paint particles to grounded substrates, serving low-volume and touch-up operations where dip tank capital is unjustified. Tier-1 automotive suppliers in the United States deploy robotic electrostatic cells for repair and specialty vehicle finishing.
- Dip Coating:Submersion in electrocoat tanks delivers complete coverage of interior cavities and complex weldments. Automotive OEMs in Germany and China specify dip systems for unibody construction, with tank volumes exceeding 500 cubic meters in high-volume plants.
- Automated Systems:Conveyor-integrated electrodeposition with programmable voltage profiling and film-build control. Electric vehicle assembly plants in the United States and South Korea specify automated lines with on-site chemical laboratories for real-time tank management.
- Multi-Stage Process:Sequential pretreatment, electrodeposition, and post-rinse integration with zirconium or silane conversion coatings. REACH substance restrictions in Europe are forcing conversion from legacy zinc-phosphate systems, extending qualification cycles for next-generation electrocoat compatibility.
Automated systems dominate new capacity investment; multi-stage process integration determines supplier selection for regulatory compliance.
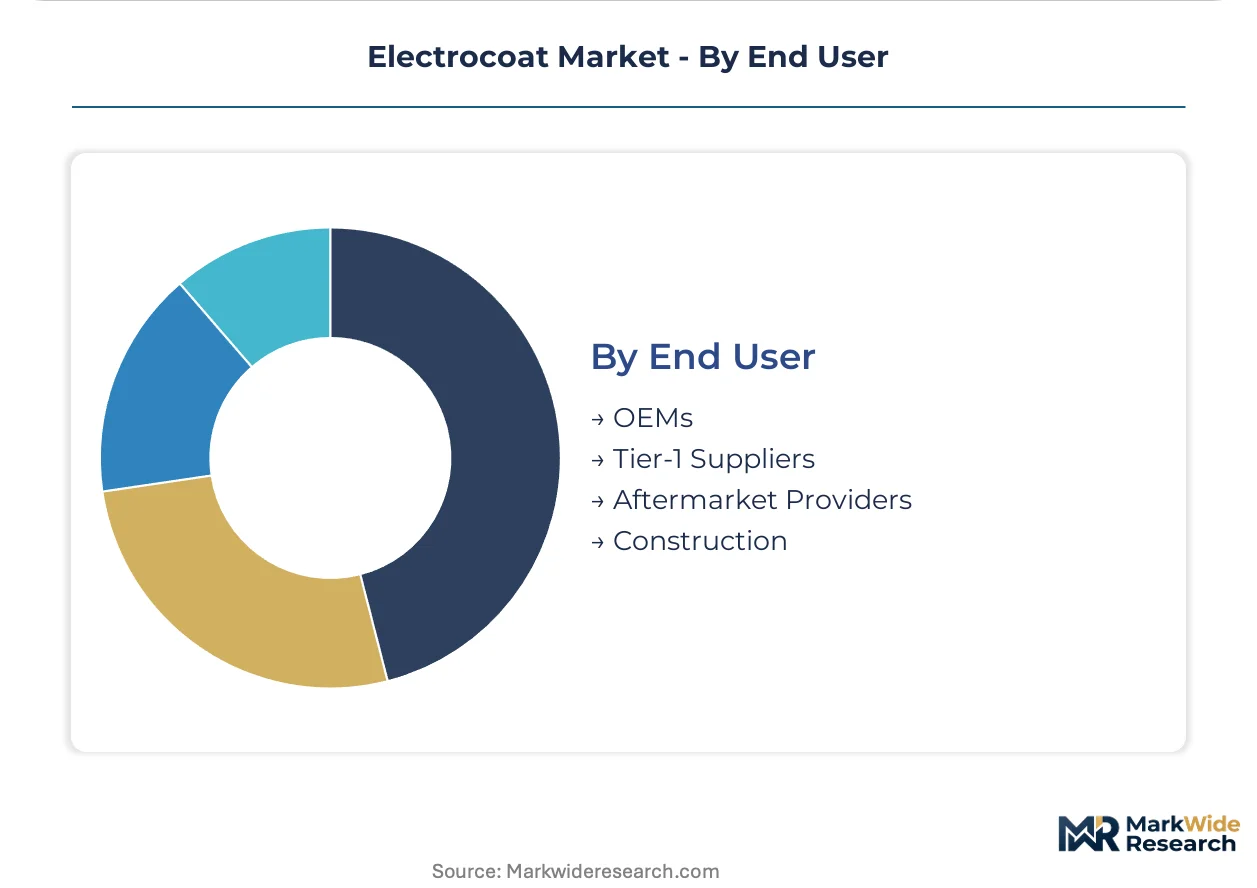
End User:
Customer type segmentation separates specification authority from execution responsibility across automotive supply chains.
- OEMs:Original equipment manufacturers in automotive, appliance, and electrical sectors retain direct relationships with electrocoat chemical suppliers, unbundling coating procurement from line installation contracts. Greenfield electric vehicle plants in the United States and Germany negotiate raw material supply agreements with on-site technical service requirements.
- Tier-1 Suppliers:Contract manufacturers operating captive paint shops for automotive seating, fuel systems, and structural components. Suppliers in Mexico and Eastern Europe face compressed qualification timelines as OEMs consolidate approved coating source lists.
- Aftermarket Providers:Refinishing operations and component remanufacturers serving collision repair and equipment rebuild markets. Demand concentrates in North American and European distribution networks for color-matched electrocoat primers.
- Construction:Structural steel fabricators and architectural metalworkers specifying corrosion protection for building frameworks and infrastructure. China's MEE solvent-based capacity restrictions are redirecting investment toward waterborne electrodeposition in Jiangsu and Guangdong provinces.
OEMs control specification authority; Tier-1 suppliers represent the most contested procurement channel as disintermediation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and industrial coaters in Germany, the United States, China, India, and Japan drive electrocoat procurement decisions. These markets concentrate cathodic line investment, regulatory compliance spending, and technical service requirements for electrodeposition systems.
United States
Automotive OEMs in Michigan and Tennessee accelerate cathodic line conversions to meet EPA NESHAP hazardous air pollutant deadlines. Tier-1 paint shops negotiate direct chemical supply agreements separate from capital equipment purchases. Electric vehicle assembly plants in the Southeast establish on-site laboratories for real-time tank chemistry management.
Germany
Luxury automotive manufacturers specify high-build cathodic clearcoat systems to eliminate sanding operations and compress paint shop footprint. ECHA substance restrictions under REACH force systematic substitution of bisphenol-A derived epoxy resins in consumer-facing applications. Industrial clusters in Bavaria and Baden-Württemberg anchor European supply for C5-M corrosion protection grades.
China
MEE solvent-based coating capacity restrictions redirect investment toward waterborne electrodeposition systems in Jiangsu and Guangdong provinces. Domestic automotive production in the Yangtze River Delta and Pearl River Delta sustains demand for cathodic epoxy primers. Grid infrastructure expansion drives electrical equipment finishing specifications under dual carbon compliance timelines.
India
PLI scheme incentives for automotive and electrical equipment manufacturing create first-mover advantage for electrodeposition system integrators. Maharashtra and Gujarat industrial corridors attract technical service presence from global chemical suppliers. Domestic OEMs face compressed qualification cycles as approved coating source lists consolidate.
Japan
Premium automotive manufacturers in the Kanto and Kansai regions specify 35-45 micrometer single-layer electrodeposition films. METI industrial standards reinforce corrosion warranty requirements that favor cathodic epoxy performance. Battery pack manufacturers require uniform edge coverage on aluminum extrusions for energy storage enclosure applications.
Electrocoat Market Key Industry Players
Player mix skews toward diversified chemical conglomerates with captive resin manufacturing and regional specialists with technical service depth. Market structure concentrates specification authority among five to seven global suppliers capable of automotive OEM qualification. Strategic archetypes include backward-integrated resin producers, application-technology licensors, and regional formulation specialists. Competitive moves center on unbundling chemical supply from line installation contracts and establishing on-site technical laboratories at greenfield OEM plants.
Among diversified coating conglomerates, PPG Industries Inc., BASF SE, and Kansai Paint Co., Ltd represent the integrated-resin archetype with in-house manufacturing of key electrocoat intermediates. These companies occupy positions where vertical control over epoxy-amine chemistry sustains cost advantages across cathodic product lines. Regional specialists including Nippon Paint Holdings Co., Ltd and The Sherwin-Williams Company exemplify the technical-service-intensive model, anchoring customer relationships through localized tank management and film-build optimization capabilities.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Nippon Paint Holdings Co., Ltd. |
| PPG Industries Inc. |
| KCC Corporation |
| Kansai Paint Co., Ltd |
| Axalta Coating Systems |
| The Sherwin-Williams Company |
| Dymax Corporation |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Bisphenol-A epoxy resin substitution with glycidyl ester alternatives in European formulations simultaneously redistributes raw material sourcing toward specialty chemical producers in Germany and Japan while compressing formulation margins through extended tank stability qualification cycles. REACH substance restrictions on SVHC-listed intermediates force automotive OEMs to absorb higher chemical costs or renegotiate multi-year supply agreements indexed to petrochemical feedstock volatility.
Pricing Analysis
Cost-plus contracts with propylene and bisphenol-A indexation dominate cathodic electrocoat procurement between automotive OEMs and integrated resin suppliers. Price differentiation rests on ISO 12944 corrosion grade certification and cathodic versus anodic technology tier, with premium clearcoat systems commanding substantial margins over standard primer grades. Pricing pressure stems from compressed corrosion warranty timelines forcing higher-performance formulations at equivalent contract values. Tier-1 suppliers in Mexico and Eastern Europe exhibit greatest price sensitivity due to OEM consolidation of approved source lists, while German luxury OEMs prioritize technical performance over unit cost.
Supply Chain Analysis
Inventory cycles for specialty corrosion-inhibiting pigments extend lead times as Chinese and German chemical suppliers concentrate qualified automotive grades. Epoxy resin production draws from propylene and bisphenol-A feedstocks anchored in United States Gulf Coast and Northeast Asian petrochemical complexes. Single-source vulnerability for qualified pigment grades creates supply chain risk as REACH substance restrictions eliminate chromate alternatives. Distribution runs through direct chemical supply agreements with on-site technical laboratories at greenfield OEM plants, displacing traditional system integrator intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrocoat qualification timelines for ISO 12944-9 C5-M and CX corrosion grades create acute scarcity of suppliers capable of offshore wind and marine certification, constraining market entry to firms with sustained R&D investment and field exposure testing infrastructure.
For Market Incumbents: Consolidate specification authority by establishing captive resin manufacturing for glycidyl ester alternatives ahead of REACH authorization deadlines. Deepen technical service presence in Maharashtra and Gujarat industrial corridors to capture PLI scheme-driven demand from domestic automotive and electrical equipment OEMs facing compressed qualification cycles. For New Entrants and Emerging Players: Anchor in energy storage enclosure finishing for battery pack manufacturers requiring uniform edge coverage on aluminum extrusions, where anodic acrylic electrocoats address cost-sensitive specifications outside automotive body-in-white dominance. Target technical service partnerships with electrodeposition system integrators in India rather than direct OEM qualification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional formulation specialists possessing ISO 12944 certification capabilities but lacking backward integration into resin intermediates. Long-term viability hinges on exposure to electric vehicle platform standardization and grid infrastructure buildout. Monitor ECHA candidate list updates for bisphenol-A derivative restrictions as inflection indicators for reformulation-driven M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Intermediates | Captive glycidyl ester production insulates margin structure from REACH-driven raw material substitution costs. |
| On-Site Technical Laboratory Establishment | Real-time tank chemistry management at greenfield EV plants secures unbundled chemical supply contracts. |
| ISO 12944-9 Certification Investment | C5-M and CX grade qualification opens offshore wind and marine applications with extended supplier timelines. |
| Multi-Stage Pretreatment Integration | Zirconium and silane conversion coating compatibility addresses REACH substance restrictions on zinc-phosphate systems. |
| Geographic Expansion to India Industrial Corridors | PLI scheme incentives in Maharashtra and Gujarat create first-mover advantage for electrodeposition system integrators. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with electrocoat formulators, automotive OEM procurement directors, Tier-1 paint shop managers, and electrodeposition system integrators; and secondary validation through customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings of diversified coating conglomerates, and EPA NESHAP compliance documentation. Bottom-up volume modeling by cathodic and anodic product segments triangulated against top-down value estimates derived from OEM coating procurement disclosures.
Across the analysis window, the forecasting framework modeled electrocoat demand through segmentation by product type, application technology, end-use industry, and regional production cluster. CAGRs were derived from regression analysis of historical capacity expansion announcements and regulatory compliance-driven replacement cycles. Industry-specific inputs incorporated automotive corrosion warranty timeline compression, MEE dual carbon capacity restrictions, and ECHA SVHC list evolution.
Decision-makers should treat outputs as directional under assumptions of sustained EPA and REACH regulatory stringency and stable petrochemical feedstock availability; material deviation in authorization timelines or resin substitution economics would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Self-Healing Coatings Market
Coatings
Fluid Bed and Coating System Market
Coatings
Europe Waterborne Polyurethane Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
Polyester Coatings Market
Coatings
Carpet Back Coatings Market
Coatings
United Kingdom Protective Coatings Market
Coatings
Canada Industrial Wood Coatings Market
Coatings
Polysiloxane Coatings Market
Coatings
Functional Coil Coating Market
Coatings
Superhydrophobic Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
United States Industrial Wood Coatings Market